
 Plastic Contract Manufacturing Market | 2026-2036
Plastic Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Contract Manufacturing Market Intelligence
Medical device outsourcing is pivoting toward high-precision polymer processing as original equipment manufacturers divest in-house molding operations. Tessy Plastics leverages cleanroom injection molding capabilities to anchor its position in healthcare supply chains. Mack Molding sustains geographic dominance across North American medical and defense accounts through vertically integrated toolmaking. EVCO Plastics competes on manufacturing scale, operating multi-site capacity that serves automotive tier-one programs across the Midwest and Southeast.
Plastic contract manufacturing encompasses the outsourced production of engineered polymer components through processes including injection molding with tolerances reaching ±0.001 inches, blow molding for hollow geometries, and thermoforming for thin-gauge packaging shells, serving industries that require specialized equipment without capital ownership. Injection molding leads in revenue contribution due to its suitability for tight-tolerance medical and electronic housings, while blow molding captures expanding share in sustainable packaging conversions. Prototype development services command premium pricing as OEMs compress product development cycles, though full production contracts generate the dominant margin pool through multi-year supply agreements.
FDA device master file requirements and EU MDR technical documentation standards shape supplier qualification barriers, forcing contract manufacturers to maintain validated processes and traceable material lots. EPA emissions guidelines for plastic processing facilities add compliance costs that favor scaled operators with environmental control investments. Stakeholders must monitor how ISO 13485 certification spreads beyond medical specialists into automotive and electronics segments, redrawing competitive boundaries.
Market Dynamics
Medical device OEMs are systematically divesting captive molding operations, transferring validated polymer processing expertise to contract manufacturers who must absorb FDA device master file accountability and ISO 13485 certification burdens.
Growth Catalysts
- EU MDR technical documentation mandates:European medical device regulations compel OEMs to outsource to contract manufacturers with established quality management systems and traceable material lot records.
- Automotive lightweighting programs:Electric vehicle battery housings and structural components drive demand for fiber-reinforced polymer processing in Mexico's Bajío cluster.
- Micro-injection molding:Tolerances reaching ±0.001 inches enable contract manufacturers to capture diagnostic consumable and drug delivery device contracts from pharmaceutical OEMs.
Market Restraints
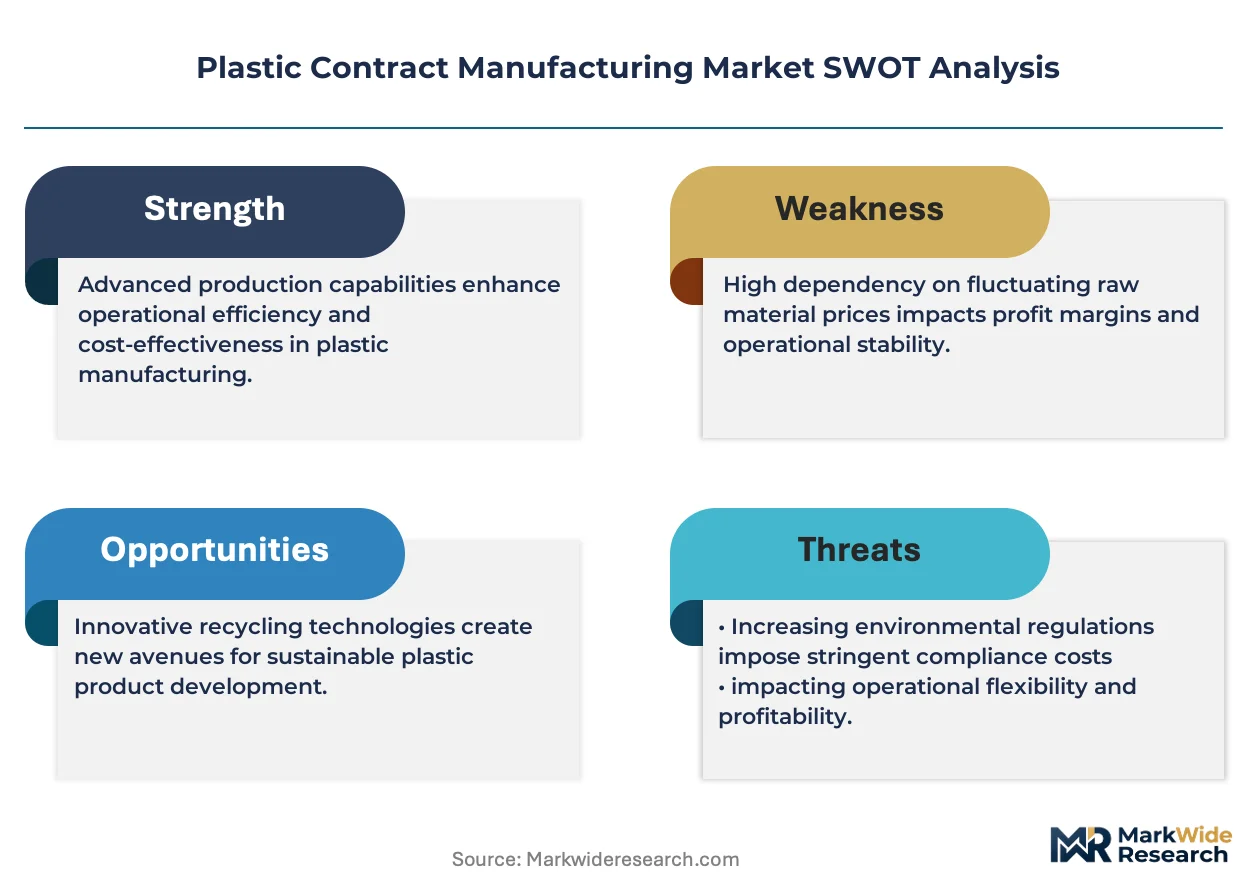
- Resin price volatility:Engineering-grade polymers and medical-certified compounds expose contract manufacturers to petrochemical feedstock cost swings that compress fixed-price contract margins.
- Tooling capex concentration:Precision mold fabrication requires capital investment that concentrates among vertically integrated operators with in-house toolrooms, marginalizing pure-play processors.
- Biopolymer performance gaps:PLA and PHA substitutes lack the mechanical properties and sterilization compatibility required for Class II medical devices, limiting sustainable material conversions.
Strategic Opportunities
- India's medical device PLI scheme:Production-linked incentives for domestic manufacturing attract contract molders to serve export-oriented orthopedic and cardiovascular device OEMs.
- Closed-loop recycling integration:Automotive and electronics brands mandate post-consumer recycled content thresholds, rewarding processors with in-house regrind and compounding capabilities.
- Continuous liquid interface printing:Convergence of photopolymer additive manufacturing with injection molding enables bridge tooling and low-volume production without hard tooling lead times.
Industry Challenges
- Process validation engineering shortage:FDA 21 CFR Part 820 compliance requires specialized talent for installation qualification, operational qualification, and performance qualification documentation that outpaces vocational training pipelines.
- Multi-site quality system harmonization:Contract manufacturers operating across Mexico, the United States, and China must synchronize change control procedures and deviation management across divergent regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Contract Manufacturing Market |
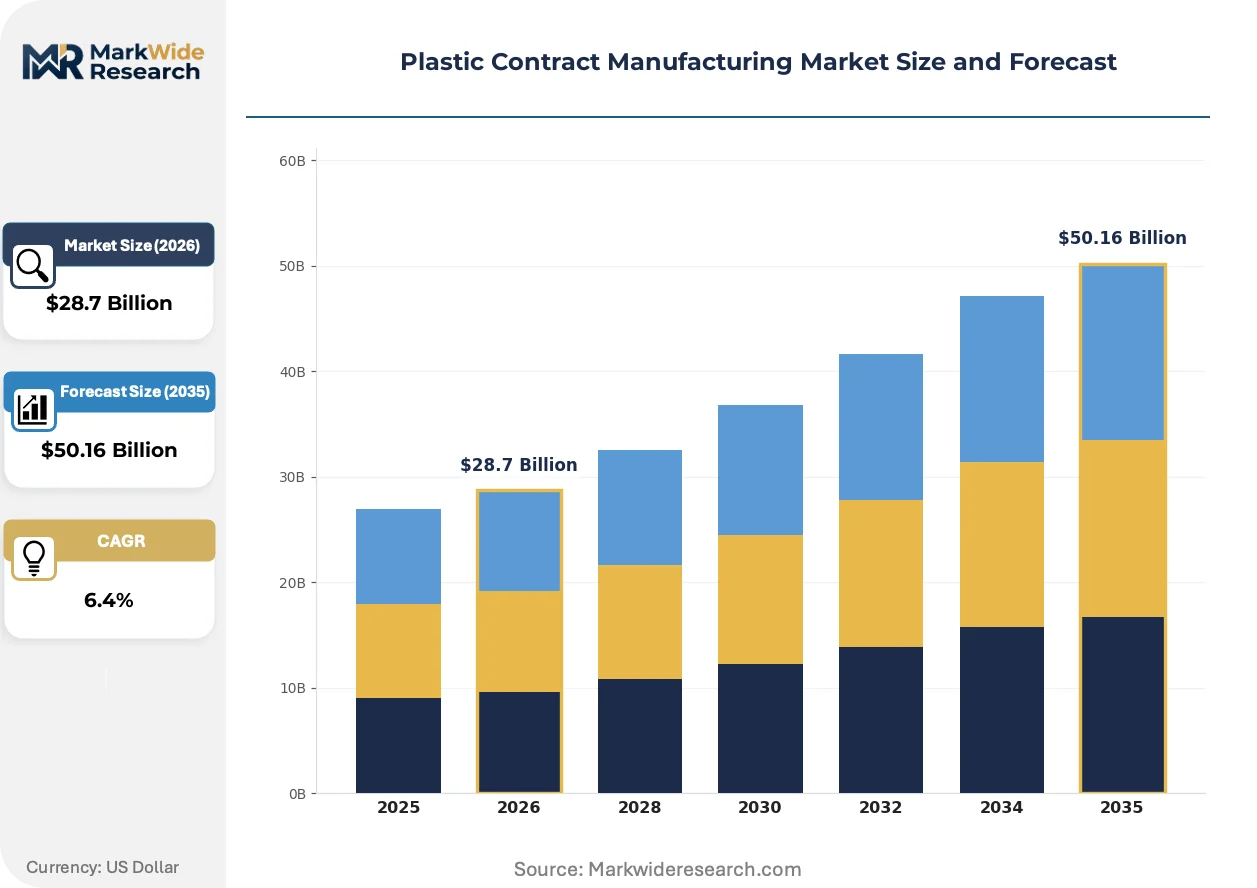
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Blow Molding, Rotational Molding, Thermoforming End User: Automotive, Consumer Goods, Healthcare, Electronics Technology: 3D Printing, CNC Machining, Vacuum Forming, Compression Molding Service Type: Prototype Development, Full Production, Custom Design, Assembly |
| Companies Covered | Tessy Plastics, Mack Molding, EVCO Plastics, Genesis Plastics Welding, PTI Engineered Plastics, McClarin Plastics LLC, Plastikon Industries, Baytech Plastics, C&J Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Contract Manufacturing Market Strategic Shifts & Innovations
Digital thread technologies are compressing product development cycles while regulatory data integrity requirements reshape how contract manufacturers document process parameters and material genealogy across distributed production networks.
All-electric injection molding platforms is unifying servo-driven clamping and plasticizing units with integrated cavity pressure sensing and adaptive process control. Medical device OEMs specify these systems for critical-to-quality dimensions in drug delivery autoinjectors. The technology is unifying real-time SPC data with electronic batch records, collapsing the validation gap between prototype and production environments.
REACH SVHC candidate list expansions are forcing reformulation of plasticizers, flame retardants, and colorants across electronics and automotive supply chains. ECHA substance restrictions cascade into device master file updates and material change notifications. Medical packaging and pediatric product categories face the steepest compliance recertification timelines as biocompatibility testing protocols lag regulatory substance bans.
Consolidated supplier programs are compressing approved vendor lists at major automotive and healthcare OEMs, concentrating purchase orders among contract manufacturers with multi-process capability certificates. Tier-one suppliers now require single-source accountability for injection molding, secondary assembly, and sterile barrier packaging. The Midwest automotive corridor and China's Yangtze River Delta electronics hub exhibit the most pronounced buyer concentration effects.
Plastic Contract Manufacturing Market Segmentation
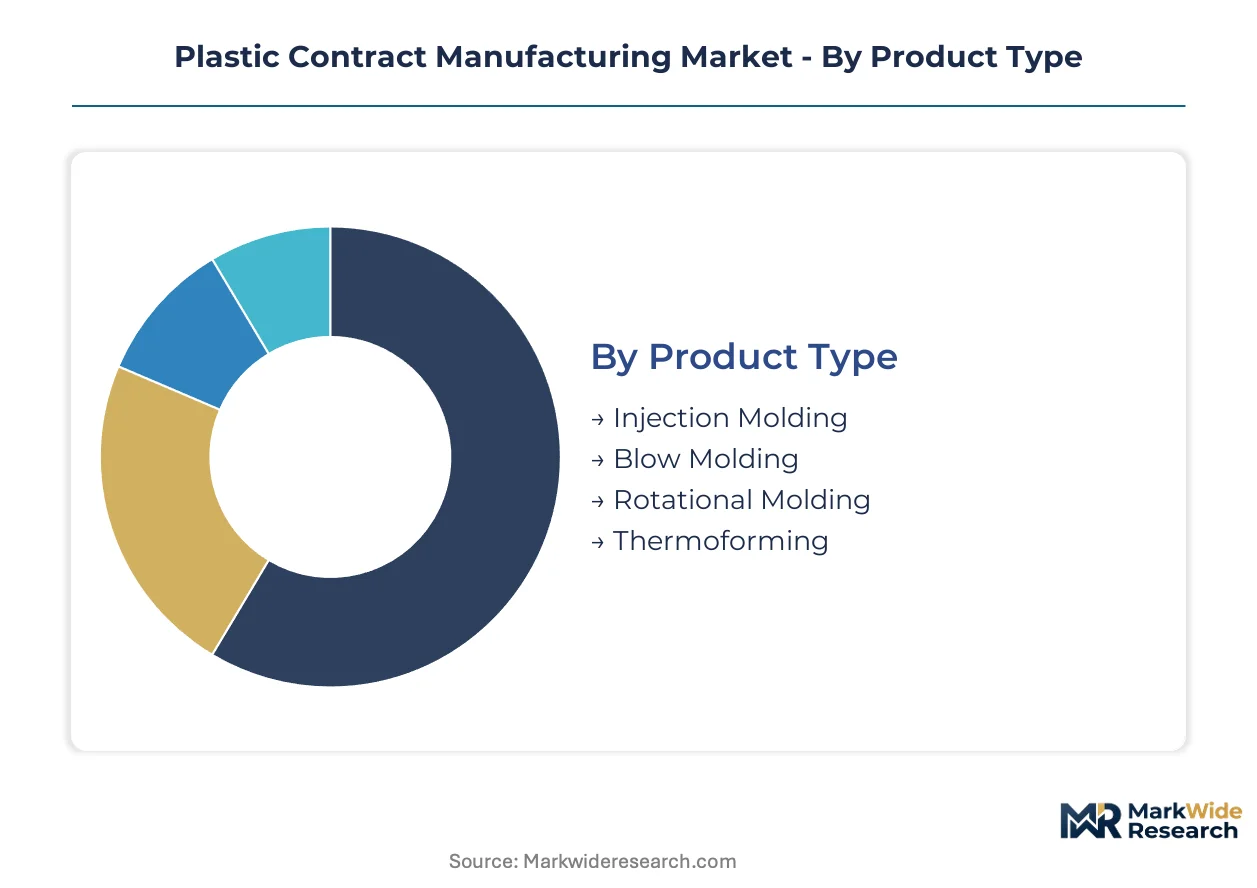
Segmentation in plastic contract manufacturing exposes how process capabilities align with regulatory burdens and capital intensity. Each dimension reveals distinct margin structures and qualification barriers that reshape supplier selection criteria across medical, automotive, and electronics supply chains.
Product Type:
FDA device master files and ISO 13485 certification requirements concentrate most heavily on injection molding, while blow molding faces EPA emissions scrutiny and rotational molding navigates lower regulatory thresholds.
- Injection Molding:Delivers tolerances reaching ±0.001 inches through all-electric servo-driven platforms with integrated cavity pressure sensing. Demand concentrates in diagnostic consumables and drug delivery autoinjectors where FDA 21 CFR Part 820 validation is mandatory.
- Blow Molding:Produces hollow geometries for fluid reservoirs and sustainable packaging conversions using extrusion and injection blow processes. Automotive washer systems and personal care brands in Mexico's Bajío cluster drive capacity expansion despite resin price volatility exposure.
- Rotational Molding:Fabricates large, stress-free hollow parts from polyethylene powders for industrial tanks and recreational equipment.
- Thermoforming:Forms thin-gauge packaging shells and medical trays through vacuum and pressure-assisted processes.
Injection molding sits at the top of the volume ranking, with blow molding climbing the fastest on sustainable packaging conversions.
End User:
Customer concentration patterns split between healthcare's multi-year validated contracts and automotive's program-based procurement cycles.
- Healthcare:Demands ISO 13485-certified cleanroom operations with full material traceability and sterilization compatibility validation. Orthopedic implant housings and cardiovascular device components in India's PLI scheme corridors attract contract manufacturer investment.
- Automotive:Requires IATF 16949 quality systems for fiber-reinforced polymer processing in electric vehicle battery housings and structural lightweighting programs.
- Consumer Goods:Prioritizes cost-competitive cycle times and cosmetic surface finishes over regulatory documentation depth.
- Electronics:Mandates REACH SVHC-compliant formulations and ESD protection for precision housings in China's Yangtze River Delta corridor.
Healthcare commands premium pricing tiers, with automotive expanding most quickly on electrification-driven lightweighting.
Technology:
Capital deployment intensity varies dramatically between additive platforms and conventional subtractive methods.
- 3D Printing:Enables bridge tooling and low-volume production through photopolymer vat polymerization and material extrusion without hard tooling lead times. Medical device OEMs leverage continuous liquid interface printing for diagnostic prototype iterations.
- CNC Machining:Delivers metal-to-plastic conversion parts with tight tolerances for aerospace and defense applications requiring ITAR compliance.
- Vacuum Forming:Produces cost-effective enclosures and packaging through simplified tooling for short-run production.
- Compression Molding:Processes thermoset composites and high-performance polymers for electrical insulation and thermal management components.
CNC machining holds the largest installed base, with 3D printing gaining share fastest on compressed product development cycles.
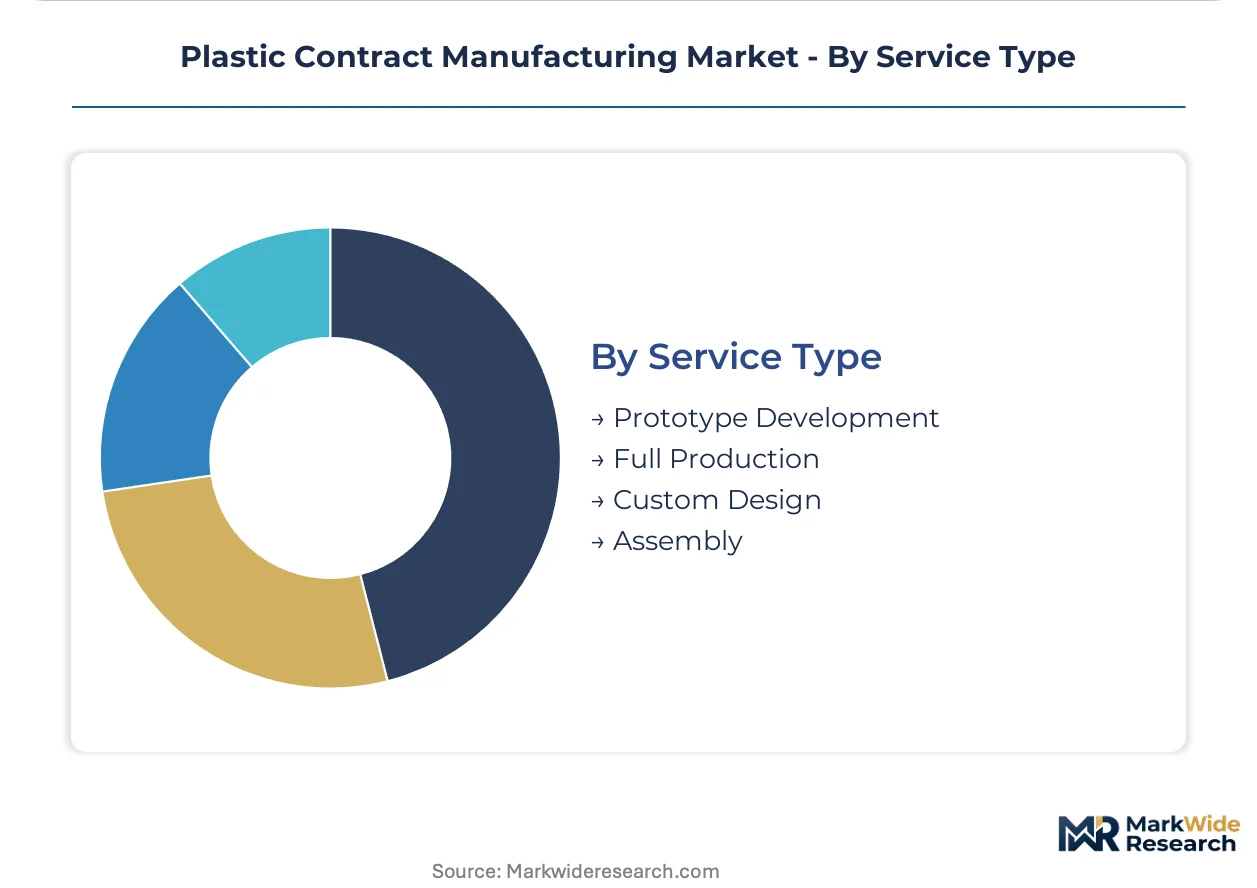
Service Type:
Margin structures diverge between prototype premiums and production contract annuity streams.
- Prototype Development:Commands premium pricing as OEMs compress design-to-production timelines through rapid tooling and iterative validation. Medical device startups in the Minneapolis-St. Paul corridor leverage these services for FDA pre-submission builds.
- Full Production:Generates dominant margin pools through multi-year supply agreements with locked resin escalation clauses and volume commitments.
- Custom Design:Integrates DFM feedback and mold flow analysis into early-stage customer engineering teams.
- Assembly:Captures value through secondary operations including ultrasonic welding, pad printing, and sterile barrier packaging.
Full production dominates revenue contribution, with prototype development expanding most quickly on accelerated medical device commercialization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's Bajío automotive cluster anchors regional demand concentration for precision polymer processing, with contract manufacturers expanding cleanroom capacity to serve cross-border medical device supply chains. FDA device master file requirements and EU MDR technical documentation standards reshape supplier qualification protocols across manufacturing corridors.
United States
Medical device OEMs in the Minneapolis-St. Paul corridor outsource diagnostic consumable molding to ISO 13485-certified contract manufacturers. FDA 21 CFR Part 820 compliance mandates absorb process validation engineering talent. Greater Boston's pharmaceutical packaging hub drives demand for drug delivery autoinjector housings with ±0.001 inch tolerances.
Mexico
Electric vehicle battery housing programs in the Bajío cluster accelerate fiber-reinforced polymer processing investments. IATF 16949 quality systems govern automotive tier-one supplier relationships. Querétaro and Guanajuato industrial parks concentrate multi-site contract manufacturing capacity for North American OEMs.
China
Electronics OEMs in the Yangtze River Delta corridor mandate REACH SVHC-compliant formulations for precision housings. NMPA medical device registration requirements parallel FDA standards for export-oriented manufacturers. Suzhou and Shanghai industrial zones host vertically integrated molders with in-house toolmaking capabilities.
Germany
Automotive lightweighting programs in Baden-Württemberg drive demand for thermoplastic composite structural components. ECHA substance restrictions cascade into material change notifications across supply chains. Stuttgart's industrial corridor concentrates injection molding capacity for electric powertrain housings.
India
CDSCO medical device licensing requirements align with export market standards for orthopedic implant contract manufacturers. PLI scheme incentives attract molders to serve cardiovascular device OEMs in Maharashtra and Gujarat industrial corridors. Ahmedabad and Pune clusters expand cleanroom capacity for sterile barrier packaging.
Plastic Contract Manufacturing Market Key Industry Players
Capacity expansion dominates the current landscape as contract manufacturers add all-electric injection molding platforms to capture medical device outsourcing volumes. The vendor base organizes into three tiers: vertically integrated specialists with in-house toolrooms, multi-site scale operators serving automotive programs, and regional processors focused on consumer goods. Strategic differentiation hinges on FDA device master file accountability and ISO 13485 certification depth. M&A activity and geographic expansion represent the dominant competitive moves as players seek multi-process capability certificates.
Among North American fabricators, Tessy Plastics and Mack Molding occupy positions at the premium-capability end of the spectrum, exemplifying the vertically integrated archetype with validated cleanroom operations. EVCO Plastics represents the scale-driven tier, anchoring multi-site capacity configurations across Midwest and Southeast manufacturing corridors. These three entities collectively illustrate how supplier qualification barriers concentrate purchase orders among manufacturers with simultaneous injection molding, secondary assembly, and sterile barrier packaging competencies.
| Leading Market Players |
|---|
| Tessy Plastics |
| Mack Molding |
| EVCO Plastics |
| Genesis Plastics Welding |
| PTI Engineered Plastics |
| McClarin Plastics LLC |
| Plastikon Industries |
| Baytech Plastics |
| C&J Industries |
| Others |
Cost & Logistics Intelligence
All-electric injection molding platforms with integrated cavity pressure sensing simultaneously compress energy costs per unit and concentrate production capacity among capital-rich operators with validated cleanroom infrastructure. This technology transition reshapes margin structures across medical and automotive supply chains as FDA device master file accountability and IATF 16949 certification requirements erect qualification barriers that smaller processors cannot surmount.
Pricing Analysis
Engineering-grade polymer feedstock volatility passes through to contract manufacturers via fixed-price agreements with locked resin escalation clauses. Pricing stratifies across ISO 13485-certified medical tiers, IATF 16949 automotive tiers, and commodity consumer goods tiers based on validation depth and traceability documentation. Cost compression in consumer-facing segments intensifies as automotive OEMs consolidate approved vendor lists. Healthcare buyers exhibit lowest price sensitivity due to multi-year validated contract structures and sterilization compatibility requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from medical device and automotive tier-one suppliers, bypassing distributor markups for validated production lots. Geographic concentration centers on Mexico's Bajío cluster, China's Yangtze River Delta corridor, and Germany's Baden-Württemberg industrial zone. Raw material dependencies draw from petrochemical feedstocks, medical-certified compounds, and fiber-reinforced thermoplastics. Single-source vulnerability around precision mold fabrication creates chokepoints as tooling capex concentrates among vertically integrated operators with captive toolrooms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic contract manufacturing functions as a stable compounder anchored by irreversible OEM divestment of captive molding operations. Medical device outsourcing and automotive lightweighting programs generate predictable multi-year revenue streams.
For Market Incumbents: Acquire in-house toolmaking capabilities to defend against pure-play processors marginalizing on price. Expand cleanroom capacity in India's Maharashtra and Gujarat corridors to capture PLI scheme incentives for orthopedic and cardiovascular device contracts. Absorb FDA 21 CFR Part 820 process validation engineering talent before vocational training pipelines collapse.
For New Entrants and Emerging Players: EU MDR technical documentation mandates in Europe open a window for contract manufacturers with established quality management systems to capture diagnostic consumable contracts from divesting OEMs. Target bridge tooling and low-volume production through continuous liquid interface printing as an entry wedge before hard tooling investments. Pursue closed-loop recycling integration capabilities to meet automotive and electronics brand mandates for post-consumer recycled content thresholds.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale ISO 13485-certified molders because buyer concentration at major healthcare and automotive OEMs compresses approved vendor lists and concentrates purchase orders among multi-process operators. Five-to-ten year viability hinges on certification depth rather than geographic footprint alone. Monitor FDA device master file submission velocity as an inflection indicator for outsourcing momentum acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | All-electric injection molding platforms capture medical device outsourcing volumes with ±0.001 inch tolerance capabilities. |
| Backward Integration | In-house toolrooms reduce precision mold fabrication lead times and defend margins against pure-play processors. |
| Certification Investment | ISO 13485 and FDA device master file accountability erect barriers that concentrate purchase orders among qualified operators. |
| Geographic Expansion | Cleanroom capacity additions in India's PLI scheme corridors serve export-oriented orthopedic and cardiovascular device OEMs. |
| Joint Venture | Closed-loop recycling partnerships with automotive brands meet post-consumer recycled content mandates through in-house regrind capabilities. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's manufacturing corridors. Interviews with contract manufacturing executives, medical device OEM procurement leads, automotive tier-one supplier quality managers, and polymer compound technical directors combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation databases, customs trade records, and SEC 10-K disclosures. Bottom-up capacity modeling and top-down demand estimation triangulate market sizing.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions include process technology, end-use industry, service type, and regional regulatory cluster. CAGRs derive from installed base expansion, outsourcing penetration rates, and content-per-unit trajectories in electric vehicle battery housings and drug delivery autoinjectors.
Revisions become necessary when resin price volatility exceeds historical bands, regulatory substance bans accelerate beyond biocompatibility testing timelines, or automotive program cancellations disrupt multi-year offtake agreements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Industrial Closures Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Permethrin Market