
 Global Nitrite Market | 2026-2036
Global Nitrite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nitrite Market Foresight
Calcium nitrite is broadening its addressable market in concrete admixtures as construction sectors phase out traditional corrosion inhibitors. BASF SE leverages its integrated chemical manufacturing footprint to supply food-grade and industrial-grade nitrite streams from European hubs. Deepak Nitrite Limited anchors South Asian supply through backward integration into basic chemicals and dye intermediates. Shandong Hailan Chemical Industry dominates Chinese domestic output with captive nitric acid capacity.
Nitrites are salts of nitrous acid (HNO₂) typically manufactured via absorption of nitrogen oxides in alkaline solutions, with sodium nitrite (NaNO₂) representing the most commercially significant form due to its solubility and reactivity profile. These compounds serve primarily as oxidation agents, diazotization precursors, and preservation agents that inhibit Clostridium botulinum growth in cured meats. Sodium nitrite occupies the largest product type position given its dual role in food preservation and chemical manufacturing, while calcium nitrite represents the fastest-growing category driven by infrastructure spending and concrete durability standards. Food preservation leads application demand structurally, though water treatment applications are gaining share as municipalities address nitrification control in wastewater systems.
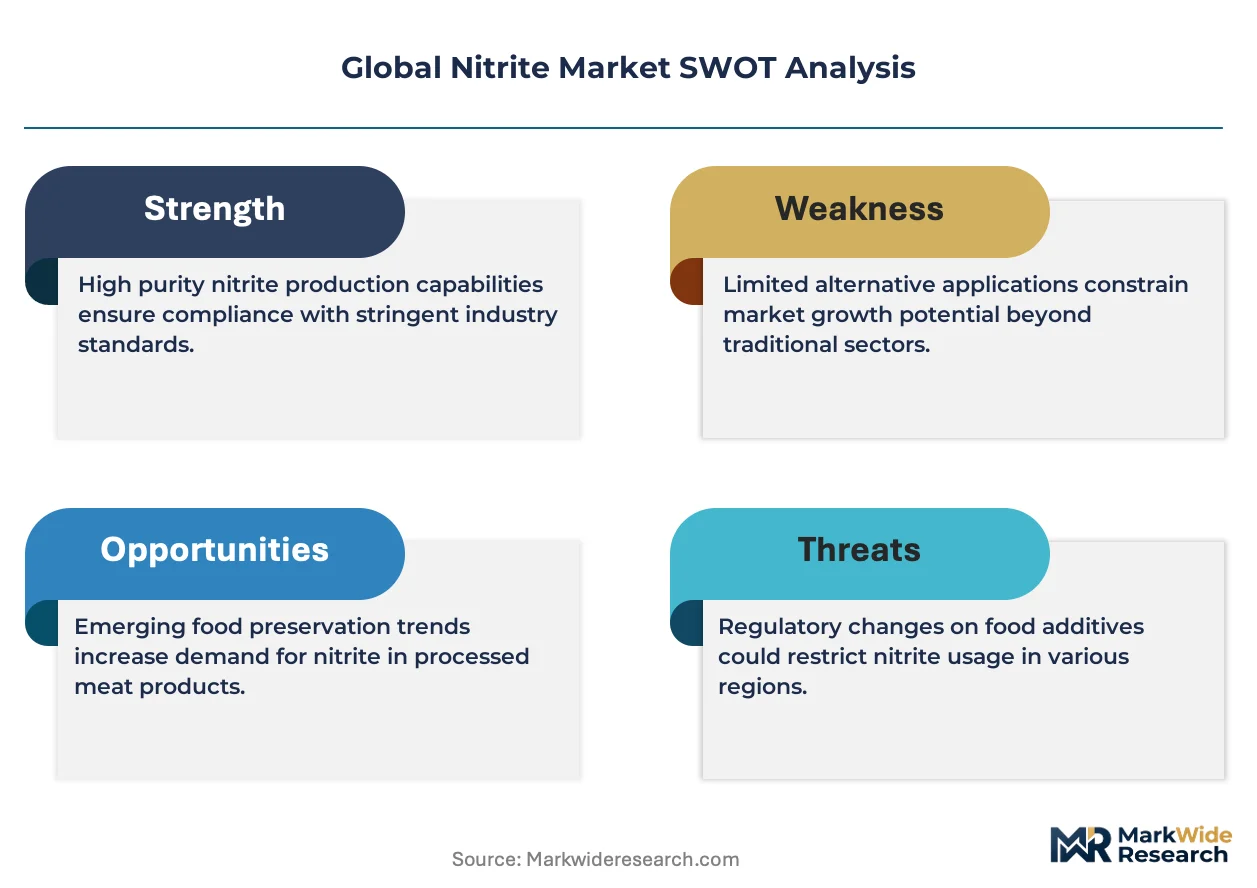
REACH registration requirements in the European Union and FDA food additive regulations under 21 CFR govern purity thresholds and labeling protocols for nitrite salts entering food and industrial channels. China's GB standards and NMPA oversight impose parallel constraints on domestic production and import flows. EPA discharge limits for nitrogenous compounds in the United States shape water treatment demand patterns. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification burdens.
Market Dynamics
Processed meat manufacturers are accelerating sodium reduction initiatives while preserving nitrite's antimicrobial function, forcing dual-track reformulation across food-grade supply chains. This tension between health-driven ingredient reduction and safety-critical preservation requirements is restructuring procurement patterns and technical specifications simultaneously.
Growth Catalysts
- Concrete durability mandates:Infrastructure agencies in India and China are specifying corrosion-resistant admixtures for bridge decks and marine structures, expanding calcium nitrite consumption in ready-mix concrete.
- REACH registration completion:ECHA's full substance evaluation for sodium nitrite has clarified compliance pathways, reducing regulatory uncertainty for EU-based food processors and chemical distributors.
- Wastewater nitrification control:Municipal utilities facing EPA discharge limits are deploying nitrite-based denitrification protocols to manage total nitrogen loads in activated sludge systems.
Market Restraints
- Nitric acid feedstock volatility:Ammonia oxidation capacity constraints and natural gas price swings transmit directly to nitrite production economics, compressing margins for non-integrated producers.
- Shandong production concentration:China's domestic supply clusters around captive nitric acid complexes, creating geographic single-point vulnerability for regional availability.
- Clean-label substitution pressure:Celery powder and other nitrate-containing vegetable extracts are displacing direct nitrite addition in premium cured meat segments, threatening volume in high-margin food-grade channels.
Strategic Opportunities
- Brazilian processed meat expansion:ANVISA's streamlined food additive approval pathways and JBS's capacity investments are opening import demand for US and European nitrite suppliers.
- Green hydrogen integration:Nitric acid production via electrolytic ammonia routes is converging with renewable energy infrastructure, offering carbon-intensity differentiation for ESG-mandated procurement.
- Direct-to-municipality water treatment channels:Specialized chemical distributors are bypassing traditional industrial intermediaries to contract directly with wastewater authorities for bulk nitrite supply.
Industry Challenges
- Food-grade certification timelines:FDA facility registration and third-party audit requirements for 21 CFR compliance are extending qualification cycles for new supply entrants by 12-18 months.
- Legacy dosing equipment incompatibility:Municipal water treatment plants operating fixed-rate feed systems face retrofit costs to accommodate variable-concentration nitrite solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nitrite Market |
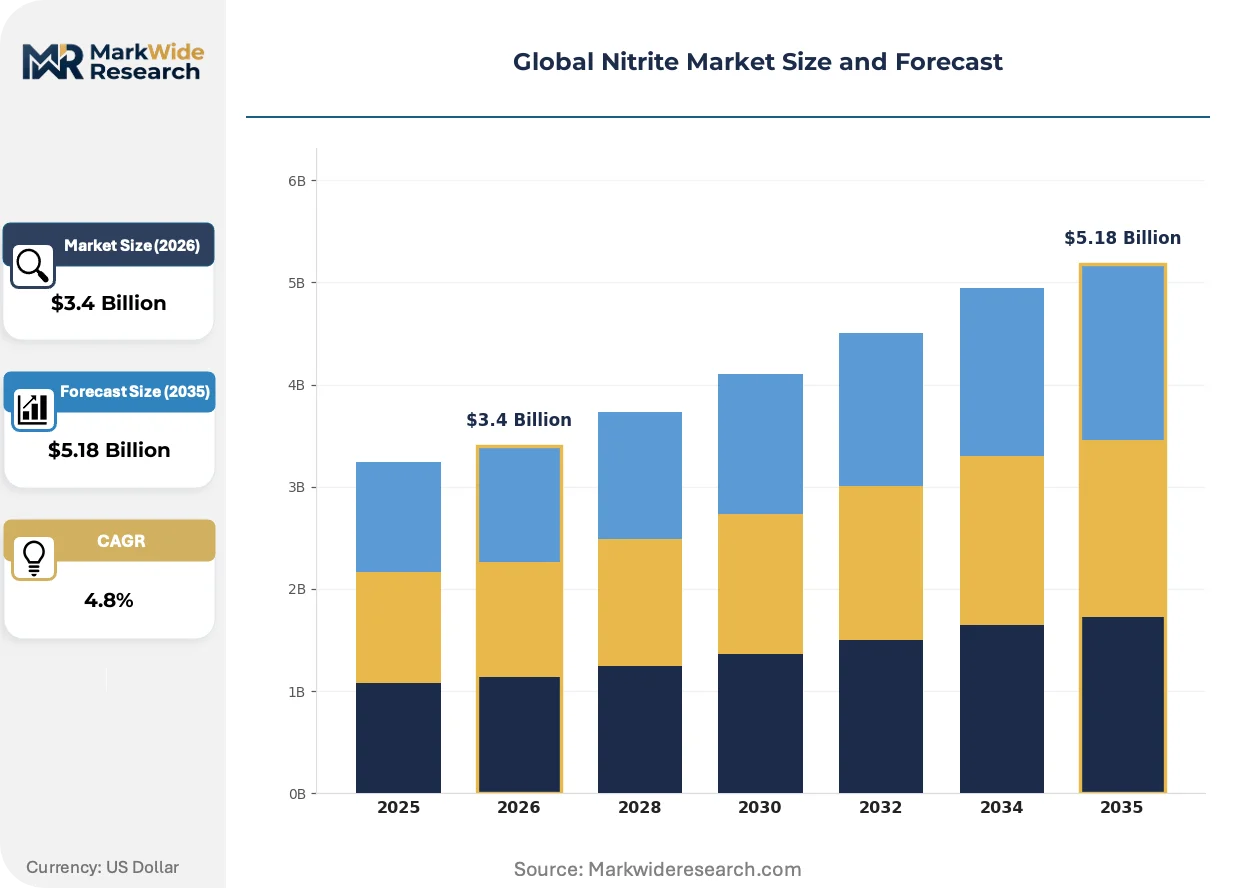
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Nitrite, Potassium Nitrite, Calcium Nitrite, Ammonium Nitrite Application: Food Preservation, Chemical Manufacturing, Water Treatment, Pharmaceuticals End User: Food Industry, Agriculture, Healthcare, Textile Industry Distribution Channel: Direct Sales, Online Sales, Retail, Distributors |
| Companies Covered | BASF SE, Deepak Nitrite Limited, Shandong Hailan Chemical Industry Co., Ltd., Nouryon, Yara International ASA, Uralchem JSC, Finoric LLC, Airedale Chemical Company Ltd., Chemtrade Logistics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nitrite Market Shifts & Advancements
Digital process control and alternative feedstock chemistry are compressing traditional manufacturing boundaries while regulatory harmonization efforts create new compliance frameworks across jurisdictions.
Membrane electrolysis for on-site nitrite generation is modularizing distributed production architecture. Regional concrete admixture blenders and mid-size meat processors are adopting containerized units to reduce transport costs and inventory exposure. This technology is modularizing supply chain topology, enabling point-of-use manufacturing that bypasses centralized chemical complexes.
EU Green Deal carbon border adjustment mechanisms are tightening embodied emissions accounting for imported nitrite salts. ECHA's proposed scope expansion to cover indirect greenhouse gas intensity will require non-European exporters to document ammonia source and energy inputs. Food-grade importers into Germany and the Netherlands are responding by securing renewable-energy certificates from upstream suppliers.
Specification-driven procurement is consolidating buyer power among multinational meatpackers and ready-mix concrete networks. Tier-1 suppliers are unbundling technical service from product supply, selling formulation expertise separately from commodity nitrite volumes. This behavior is most visible in North American channels where Tyson Foods and Cargill have centralized additive sourcing through single-contractor arrangements.
Global Nitrite Market Segmentation
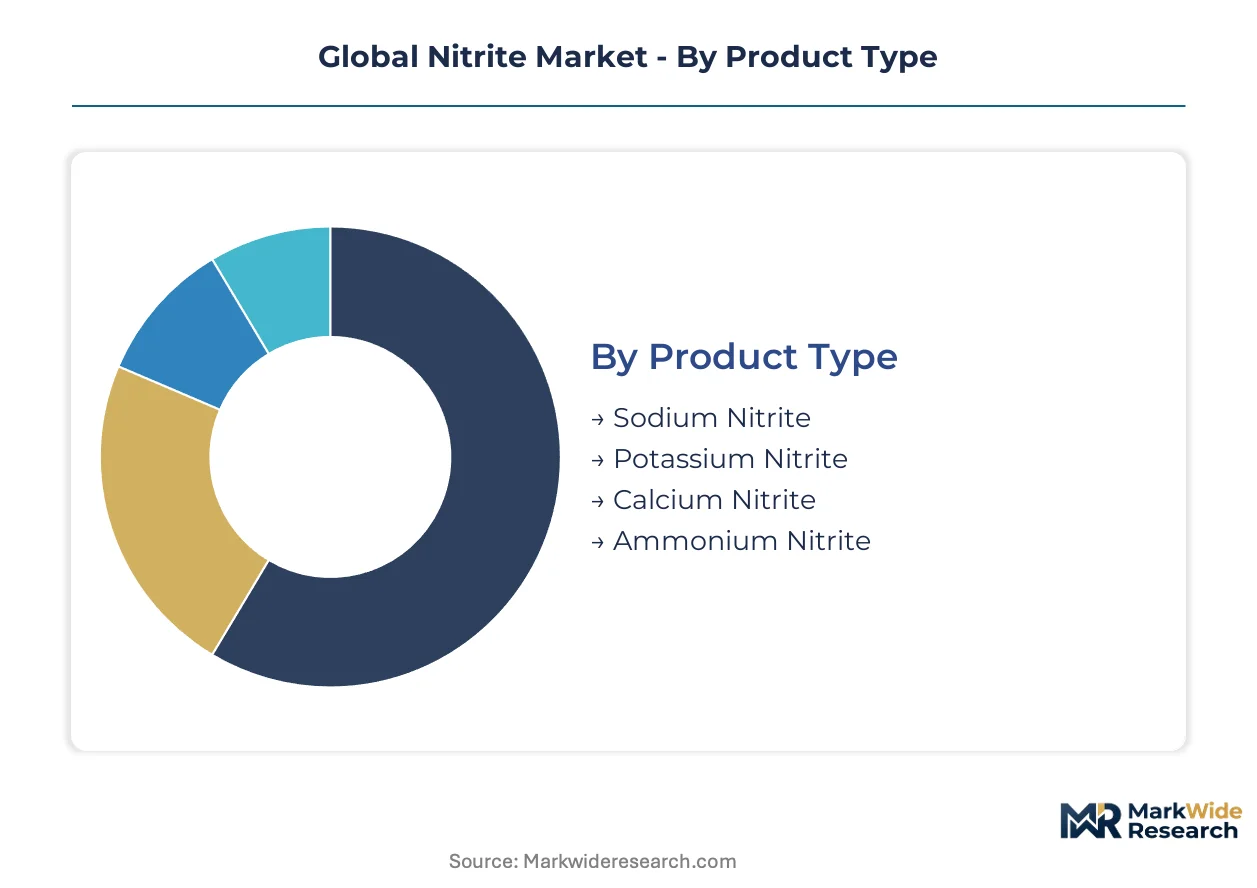
Nitrite market segmentation reveals how product chemistry, application requirements, and channel economics fragment procurement patterns. Buyers in food preservation demand certified purity grades while concrete admixture customers prioritize volume pricing and logistics reliability.
Product Type:
Customization intensity varies sharply across this category, from commodity sodium grades to specification-heavy calcium formulations for infrastructure applications.
- Sodium Nitrite:The most widely manufactured form, produced via absorption of nitrogen oxides in aqueous sodium hydroxide. Food preservation demand concentrates in Germany and the United States where processors require 99% minimum purity for cured meat applications under FDA and EFSA oversight. Sodium reduction campaigns are forcing dual-track procurement strategies.
- Calcium Nitrite:Engineered specifically for concrete corrosion inhibition with controlled chloride penetration resistance. Infrastructure spending in India and China is driving specification upgrades as transportation agencies mandate 30-year service life guarantees for bridge decks. This segment is climbing the fastest.
- Potassium Nitrite:Substitute sodium in low-sodium cured meat formulations where potassium salt compatibility matters. Niche uptake in European clean-label product lines.
- Ammonium Nitrite:Laboratory reagent grade and specialized diazotization chemistry applications. Limited commercial volume outside analytical supply chains.
Most installed capacity flows through Sodium Nitrite. Expansion is steepest in Calcium Nitrite.
Application:
Margin structures diverge based on regulatory burden intensity and technical service requirements.
- Food Preservation:The foundational demand driver, leveraging nitrite's specific inhibition of Clostridium botulinum spore germination in cured meats. USDA-FSIS labeling requirements and maximum ingoing limits govern formulation precision. Celery powder displacement threatens direct addition volumes in premium retail channels.
- Chemical Manufacturing:Diazo coupling reactions for azo dyes and pharmaceutical intermediates consume consistent technical-grade volumes. Deepak Nitrite Limited's backward integration into dye chemistry anchors South Asian demand.
- Water Treatment:Municipal denitrification protocols for EPA discharge compliance. Direct-to-utility contracting is bypassing traditional chemical distribution layers.
- Pharmaceuticals:GMP-certified nitrite salts for vasodilator synthesis and diagnostic reagents. Batch documentation and audit trails command 40-60% price premiums over industrial grades.
Food Preservation commands the largest revenue pool. Water Treatment is gaining share fastest.
End User:
Procurement sophistication separates price-sensitive agricultural buyers from specification-driven healthcare purchasers.
- Food Industry:Multinational meatpackers centralize additive sourcing through single-contractor arrangements. Tyson Foods and JBS negotiate annual volume commitments with technical service bundling.
- Agriculture:Fertilizer-chemical complexes in Shandong province consume industrial nitrite for downstream nitrogen compound manufacturing. Price volatility in ammonia feedstock transmits directly to purchasing decisions.
- Healthcare:Pharmaceutical manufacturers require USP-grade certification with elemental impurity testing under ICH Q3D guidelines. Qualification cycles extend 12-18 months for new supply entrants.
- Textile Industry:Azo dye production in Gujarat and Jiangsu provinces drives regional sodium nitrite consumption. Environmental compliance costs are consolidating buyer power among integrated mills.
The Food Industry maintains the deepest supplier relationships. Healthcare is expanding most quickly.
Distribution Channel:
Channel selection reflects order scale, geographic density, and technical support requirements.
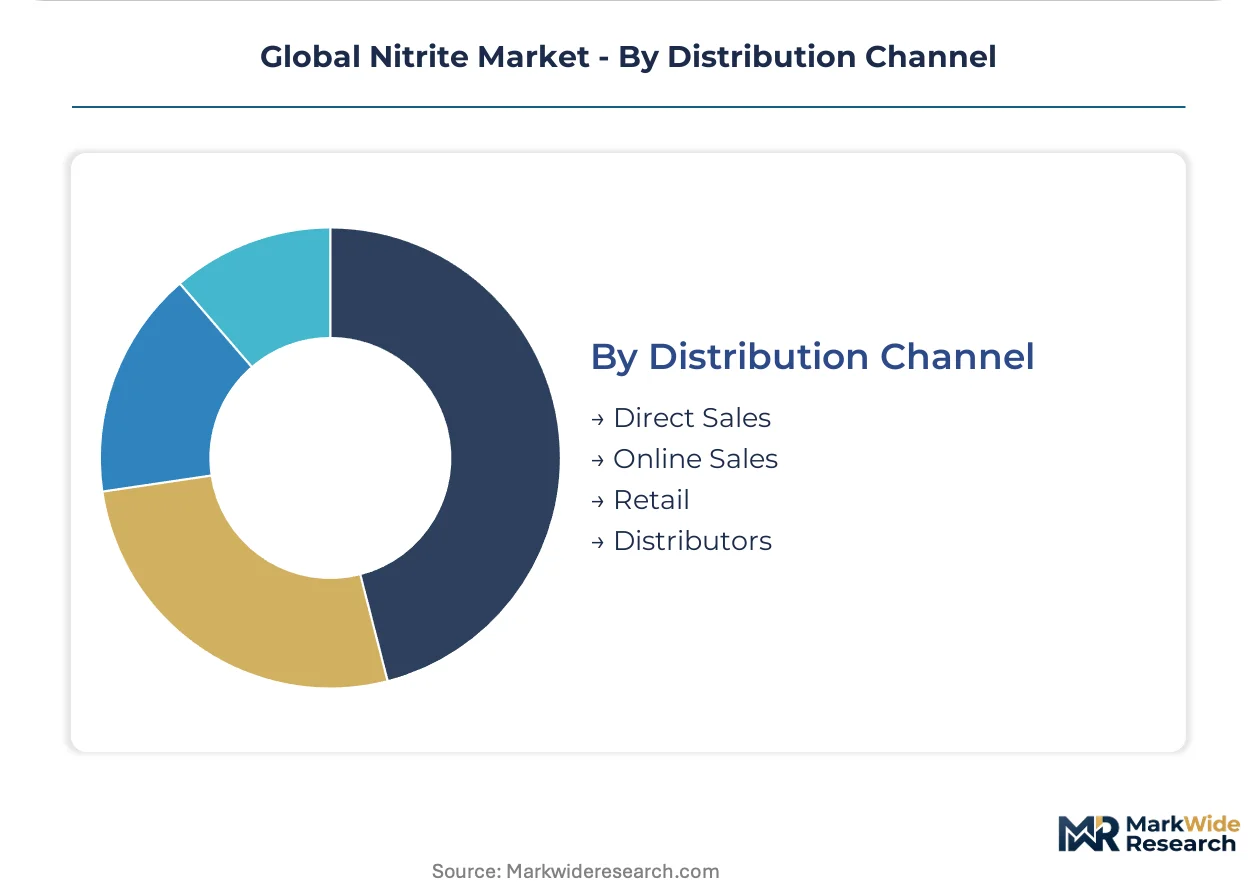
- Direct Sales:Bulk contracts for ready-mix concrete networks and multinational meatpackers. BASF SE and Shandong Hailan Chemical Industry operate dedicated account teams for tier-1 customers.
- Distributors:Regional chemical distributors stock food-grade and industrial grades for mid-size processors. Inventory financing and just-in-time delivery justify 15-25% markups over direct pricing.
- Online Sales:Laboratory reagent grades and small-batch pharmaceutical raw materials. Limited to sub-ton quantities with certificate-of-analysis documentation.
- Retail:Consumer-facing curing salt blends in specialty food channels. Minimal volume relative to industrial procurement.
Direct Sales channels handle the majority of tonnage. Distributor relationships are deepening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors global nitrite production capacity through integrated nitric acid complexes serving domestic and export demand. Regional markets diverge sharply in regulatory stringency and end-use concentration. Infrastructure spending patterns and processed meat consumption dictate procurement volumes across major economies.
China
Shandong Hailan Chemical Industry commands domestic output from captive nitric acid facilities in Weifang and Qingdao. GB standards under NMPA oversight impose purity thresholds for food-grade exports to Europe and North America. Yangtze River Delta concrete admixture blenders are absorbing rising calcium nitrite volumes for bridge deck specifications.
United States
USDA-FSIS labeling requirements and FDA 21 CFR food additive standards govern cured meat formulation precision. Tyson Foods and Cargill have centralized additive sourcing through single-contractor arrangements. Gulf Coast chemical distributors stock both food-grade and industrial grades for mid-size meat processors facing sodium reduction mandates.
Germany
REACH registration completion through ECHA has clarified compliance pathways for sodium nitrite imports. BASF SE operates integrated manufacturing from Ludwigshafen supplying food-grade and industrial-grade streams. Bavarian meat processors are reformulating around dual-track sodium reduction while preserving antimicrobial function.
India
Deepak Nitrite Limited anchors South Asian supply through backward integration into basic chemicals and dye intermediates in Gujarat. FSSAI food safety standards and BIS industrial specifications create parallel certification tracks. Mumbai-Pune concrete networks are specifying corrosion-resistant admixtures for coastal infrastructure projects.
Brazil
ANVISA streamlined food additive approval pathways are opening import demand for processed meat expansion. JBS capacity investments in São Paulo and Mato Grosso are driving technical-grade nitrite procurement. Port infrastructure at Santos is consolidating chemical import flows for distribution to domestic meatpacking clusters.
Global Nitrite Market Competitive Landscape
Capacity expansion dominates the current landscape as producers integrate backward into nitric acid feedstock to margin compression from ammonia volatility. The vendor base concentrates around three strategic tiers: integrated chemical conglomerates with captive raw material supply, regional specialists serving single geographies or applications, and fertilizer-chemical complexes leveraging existing nitrogen infrastructure. M&A activity targets mid-scale distributors in water treatment channels, while portfolio diversification into food-grade certification separates premium suppliers from commodity players.
Among European-integrated chemical conglomerates, BASF SE exemplifies the multi-grade supply archetype spanning food and industrial channels. Deepak Nitrite Limited and Shandong Hailan Chemical Industry Co., Ltd. represent the regional specialist and captive-production archetypes respectively, with the former anchoring South Asian dye chemistry demand and the latter dominating Chinese domestic output through nitric acid self-sufficiency.
| Leading Market Players |
|---|
| BASF SE |
| Deepak Nitrite Limited |
| Shandong Hailan Chemical Industry Co., Ltd. |
| Nouryon |
| Yara International ASA |
| Uralchem JSC |
| Finoric LLC |
| Airedale Chemical Company Ltd. |
| Chemtrade Logistics Inc. |
| Others |
Supply & Pricing Matrix
Multinational meatpackers and ready-mix concrete networks concentrate procurement power, forcing contract-based long-term offtake structures that lock in volume commitments against ammonia feedstock volatility. This buyer consolidation compresses margin flexibility for non-integrated producers while rewarding suppliers with captive nitric acid capacity.
Pricing Analysis
Ammonia oxidation economics transmit directly to nitrite production costs, with natural gas price swings compressing margins for distributors lacking upstream control. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates USP-certified salts commanding 40-60% premiums from commodity technical grades. Cost compression in industrial channels is intensifying because fertilizer-chemical complexes in Shandong province leverage captive feedstock supply. Mid-size meat processors exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize batch documentation over unit cost.
Supply Chain Analysis
Return flows of spent nitrite solutions from municipal water treatment facilities remain minimal given single-use denitrification chemistry, though containerized on-site generation units are modularizing reverse logistics for regional blenders. Manufacturing gravity centers on China, Germany, and India, with Shandong province anchoring global ammonia oxidation capacity. Feedstock supply draws from natural gas reforming and electrolytic hydrogen routes, with energy inputs and nitric acid availability as critical dependencies. Single-source vulnerability concentrates around Shandong Hailan's captive complexes, while distribution runs through direct sales for tier-1 meatpackers and specialized chemical distributors for mid-size processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Nitrite Market functions as a stable compounder anchored by irreplaceable antimicrobial functionality in cured meat safety protocols. Infrastructure durability mandates and wastewater discharge compliance generate predictable demand visibility across economic cycles.
For Market Incumbents: Hedge against clean-label substitution by securing dual-track sodium reduction formulations that preserve nitrite's Clostridium botulinum inhibition while accommodating celery powder displacement in premium retail channels. Deepen backward integration into ammonia oxidation capacity to defend margin position against feedstock volatility, particularly in European hubs facing EU Green Deal carbon border adjustments. For New Entrants and Emerging Players: Begin with Brazilian processed meat expansion corridors where ANVISA streamlining and JBS capacity investments are opening import demand for food-grade certification specialists. Target direct-to-municipality water treatment contracting as the most penetrable channel, bypassing traditional industrial intermediaries through specialized technical service bundling for EPA-compliant denitrification protocols. For Investors and Strategic Acquirers: Chemical conglomerates with captive nitrogen infrastructure represent the most active acquirer in this space, consolidating mid-scale distributors in water treatment channels to secure recurring municipal revenue streams. Acquisition candidates should demonstrate food-grade certification completion and renewable energy certificate coverage from upstream ammonia suppliers. Monitor ECHA scope expansion proposals for indirect greenhouse gas intensity accounting as an inflection indicator for carbon-border-adjusted import competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitric Acid | BASF SE and Shandong Hailan anchor margin defense through captive ammonia oxidation capacity. |
| Food-Grade Certification Investment | FDA facility registration and 21 CFR compliance extend qualification cycles, creating supplier stickiness. |
| Green Manufacturing Transition | Electrolytic ammonia routes converge with renewable energy infrastructure for ESG-mandated procurement differentiation. |
| Long-term Supply Agreement | Tyson Foods and Cargill centralize additive sourcing through single-contractor arrangements with technical service bundling. |
| Joint Venture | Regional concrete admixture blenders partner with nitrite suppliers for containerized on-site generation deployment. |
Research Methodology
Direct dialogue with plant managers at nitrite manufacturing facilities, procurement leads at multinational meatpackers, technical R&D directors at concrete admixture blenders, and regulatory affairs specialists at FDA-registered food additive suppliers grounded qualitative assessment. Secondary validation incorporated customs and trade data from China and India, ECHA REACH registration databases, SEC 10-K filings from listed chemical producers, and EPA discharge compliance records from municipal utilities. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Segmentation outputs reflect grade tier differentiation, end-use industry concentration, regional production hub economics, and channel structure complexity modeled throughout the forecast period. CAGRs were derived from production capacity expansion timelines, infrastructure spending trajectories in India and China, and processed meat consumption elasticity assumptions. Key inputs included ammonia feedstock price forecasting, regulatory approval pathway durations for food-grade certification, and municipal wastewater treatment capital expenditure cycles.
Several conditions sit outside the modeled scope, including abrupt regulatory bans on nitrite preservatives, breakthrough clean-label antimicrobial substitutes achieving commercial scale, and geopolitical disruption to Shandong province production clusters. Practitioners should monitor ECHA substance evaluation outcomes, ANVISA approval pathway modifications, and electrolytic ammonia cost parity milestones for early signals of structural demand shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Triazine Market