
 Octanoyl Chloride Market | 2026-2036
Octanoyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Octanoyl Chloride Market Analytics
The capital-intensity gap between integrated acyl chloride producers and merchant suppliers is collapsing as energy and raw material costs equalize across tiers. BASF SE leverages captive chlorination infrastructure to sustain margin structures that smaller competitors cannot replicate. CABB Group GmbH anchors its position through backward integration into thionyl chloride supply, while Thermo Fisher Scientific Inc. differentiates via pharmaceutical-grade certification and channel control into regulated end markets.
Octanoyl chloride is an eight-carbon acyl halide with the molecular formula C8H15ClO, produced primarily through the reaction of octanoic acid with thionyl chloride or phosphorus pentachloride, serving as a reactive intermediate in esterification and amidation reactions across organic synthesis. Its primary industrial purpose centers on introducing capryloyl functional groups into active pharmaceutical ingredients, flavor esters, and agrochemical precursors. The pharmaceutical application segment leads value generation due to stringent purity premiums in API synthesis, while the flavors segment registers faster volume expansion as clean-label food formulations multiply. Chemical manufacturing end-use dominates absolute consumption, though personal care applications concentrate margin pools through fragrance-grade specifications.
REACH registration requirements and ECHA substance evaluation protocols govern market access across Europe, while FDA oversight of pharmaceutical intermediates shapes purity standards for US-bound supply chains. India's CDSCO and BIS frameworks increasingly mandate impurity profiling for imported acyl chlorides used in domestic drug production. Stakeholders must monitor evolving PFAS restrictions and halogenated solvent regulations that could redirect synthesis routes or trigger substitution investments in key manufacturing clusters.
Market Dynamics
Pharmaceutical-grade acyl chloride demand is concentrating around CDSCO-regulated API clusters in India, collapsing the traditional merchant-supplier tier as integrated producers capture margin through captive chlorination and backward thionyl chloride control.
Growth Catalysts
- REACH substance evaluation protocols:ECHA purity mandates force API manufacturers toward certified intermediate suppliers, tightening vendor qualification pools and advantaging registered producers.
- Clean-label flavor ester synthesis:Food formulators replace synthetic carriers with capryloyl-derived natural esters, expanding octanoyl chloride offtake in FSSAI-regulated flavor applications.
- Thionyl chloride supply concentration:Backward integration into SOCl2 production shields integrated acyl chloride manufacturers from feedstock volatility, securing cost structures smaller merchants cannot match.
Market Restraints
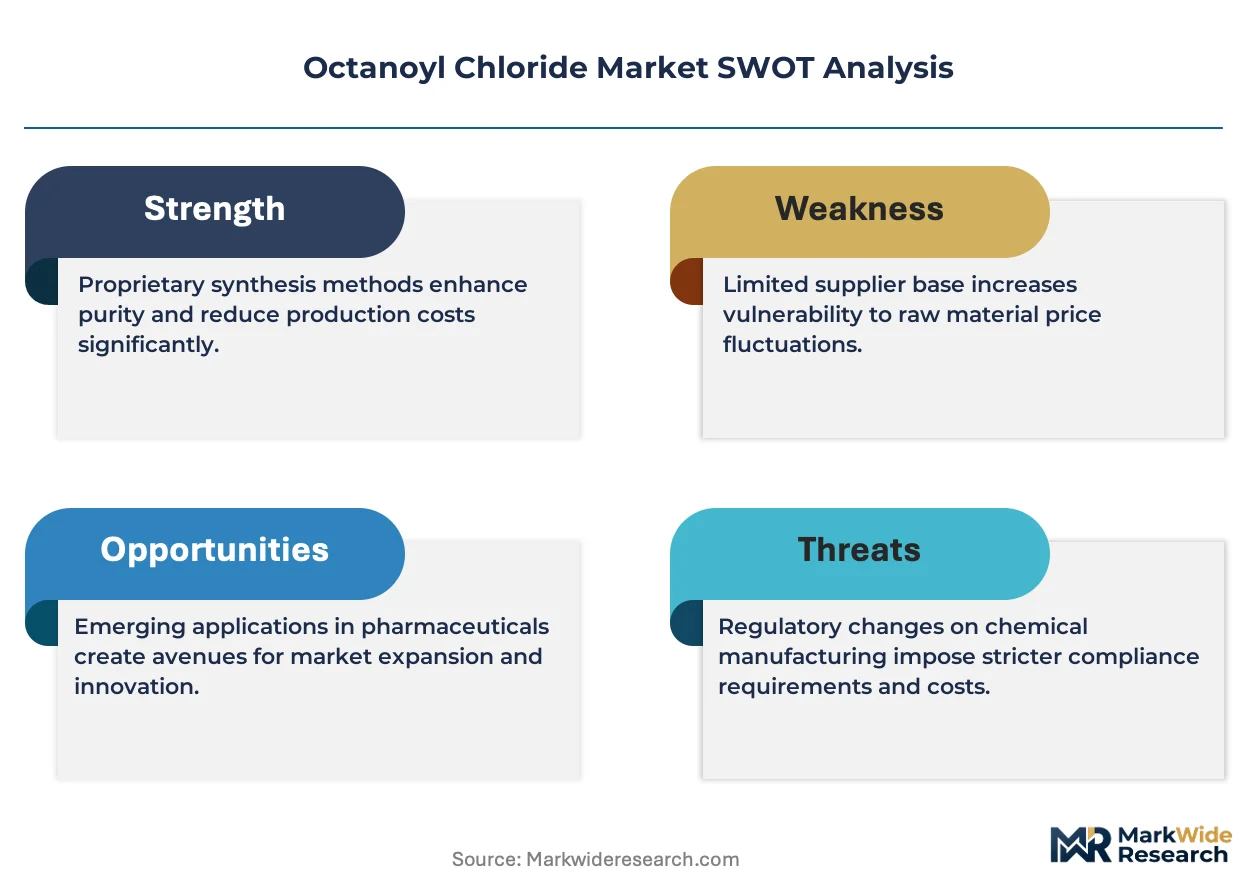
- Feedstock cost volatility:Octanoic acid prices track palm kernel and coconut oil commodity swings, compressing margin predictability for non-integrated producers.
- PFAS restriction trajectory:EU F-Gas Regulation and emerging halogenated solvent limits threaten chlorination-based synthesis routes, forcing capital-intensive process redesign.
- Substitution by acid anhydrides:Acetic and propionic anhydrides displace acyl chlorides in certain amidation protocols where moisture tolerance permits milder reagents.
Strategic Opportunities
- Underpenetrated Brazilian agrochemical synthesis:ANVISA-regulated crop protection manufacturing lacks domestic acyl chloride capacity, creating import substitution potential for certified exporters.
- Continuous flow chlorination technology:Microreactor platforms reduce solvent inventory and improve heat transfer, enabling modular capacity expansion with lower capex thresholds.
- PLI scheme alignment in India:Production-linked incentives for API intermediates reward domestic acyl chloride manufacturing with tax offsets and capital subsidies.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA DMF filing requirements extend qualification cycles to 18-24 months, freezing supplier switches mid-contract.
- Halogen handling competency gaps:Thionyl chloride management demands specialized HSE protocols and corrosion-resistant infrastructure scarce in emerging manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octanoyl Chloride Market |
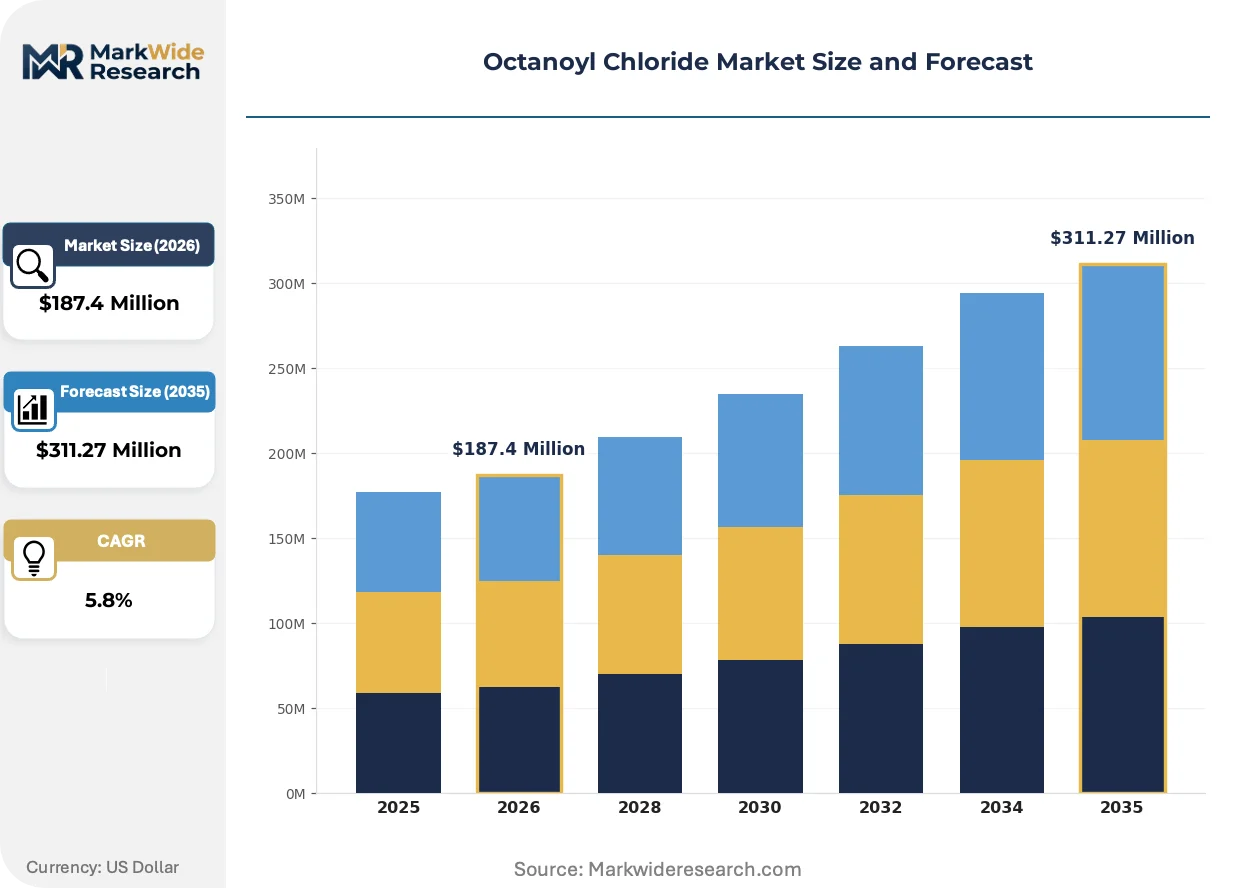
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
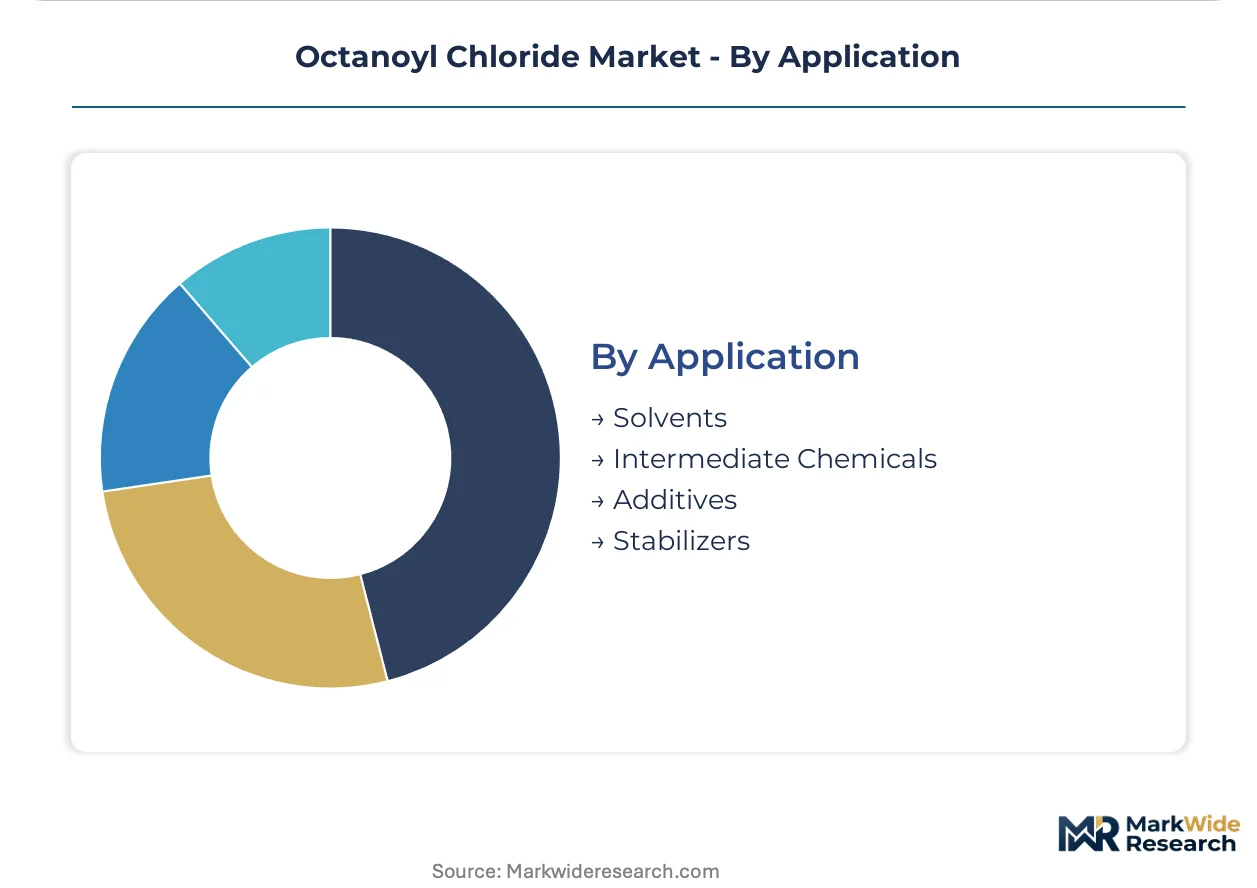
| Segmentation | Product Type: Pharmaceuticals, Flavors, Fragrances, Agrochemicals End Use Industry: Food & Beverage, Personal Care, Chemical Manufacturing, Coatings Technology: Synthesis, Extraction, Formulation, Processing Application: Solvents, Intermediate Chemicals, Additives, Stabilizers |
| Companies Covered | BASF SE, Merck KGaA, Sigma-Aldrich Corporation, TCI Chemicals (India) Pvt. Ltd., Alfa Aesar, Thermo Fisher Scientific Inc., CABB Group GmbH, WeylChem Group of Companies, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octanoyl Chloride Market Evolving Landscape
Process intensification and regulatory chemistry are reshaping acyl chloride manufacturing, splitting the market between commodity-scale chlorination and precision pharmaceutical-grade production.
Continuous flow microreactor technology is bifurcating the acyl chloride production landscape. These systems enable precise temperature control and reduced solvent volumes during octanoic acid chlorination. Pharmaceutical intermediates manufacturers in Switzerland and Singapore are piloting modular units for on-demand API precursor synthesis. The technology is compressing batch cycle times from hours to minutes while isolating hazardous thionyl chloride exposure.
EU REACH authorization requirements are tightening impurity disclosure thresholds for acyl chlorides entering pharmaceutical supply chains. ECHA substance evaluation now mandates full analytical profiles for chlorinated byproducts down to 0.1% mass fraction. German and Dutch chemical distributors are consolidating supplier bases to registered producers with complete dossier coverage. This regulatory compression is eliminating unregistered merchant traders from European API intermediate channels.
Buyer concentration among CDSCO-registered Indian API manufacturers is compressing procurement cycles and hardening specification requirements. Large contract manufacturers now demand dedicated production lines and locked-in capacity commitments from acyl chloride suppliers. Mumbai and Hyderabad pharmaceutical clusters are vertically integrating into captive intermediate synthesis where volume justifies capital deployment. This consolidation is marginalizing spot-market merchants unable to meet audit depth and supply security standards.
Octanoyl Chloride Market Segmentation
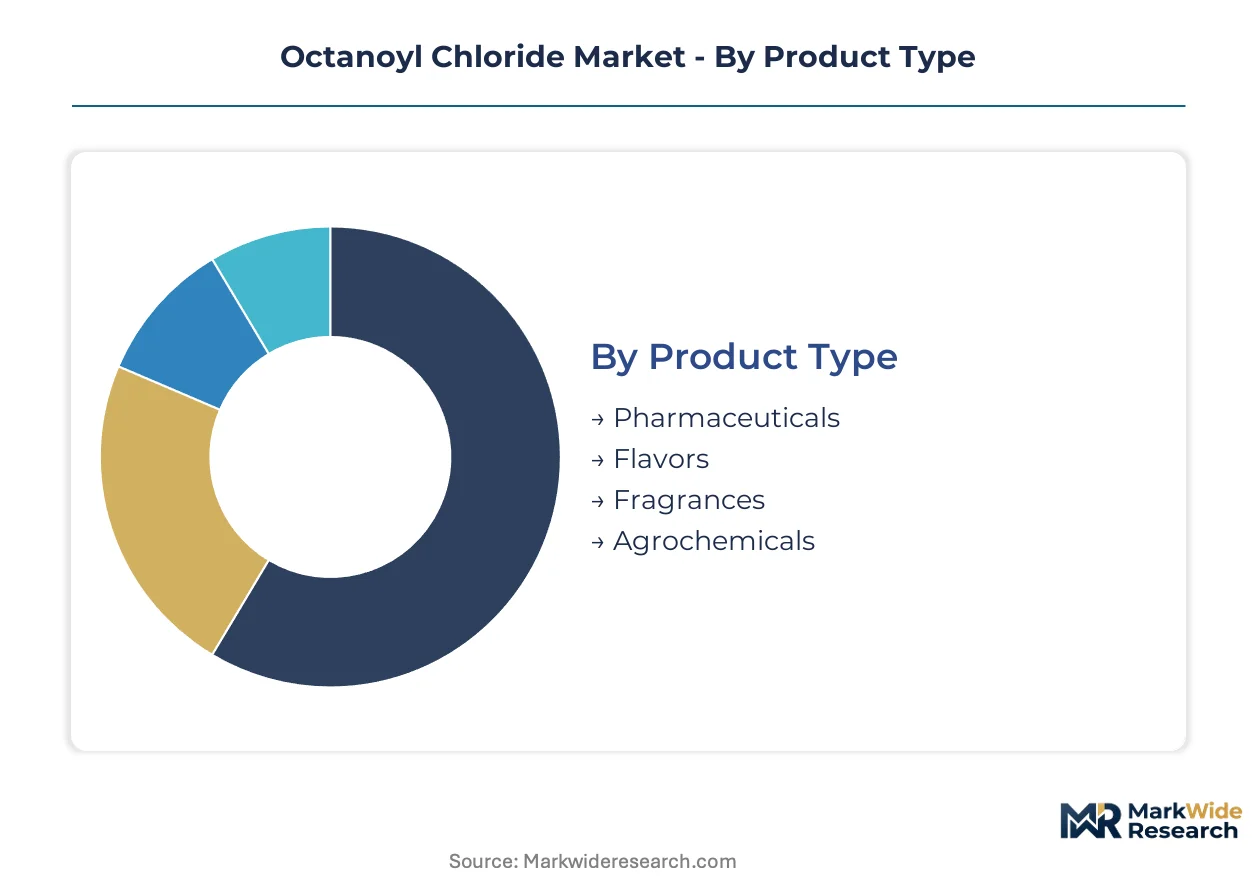
Octanoyl chloride procurement channels diverge sharply by purity grade and regulatory certification requirements. Pharmaceutical intermediates flow through qualified supplier networks with locked capacity agreements, while flavor and fragrance grades move through more flexible spot-market channels.
Product Type:
Pharmaceutical-grade material commands premium positioning through dedicated production lines and audit-heavy vendor qualification, while commodity grades distribute through broader chemical distribution networks.
- Pharmaceuticals:Ultra-high purity specifications with impurity thresholds below 0.1% mass fraction satisfy EMA and FDA DMF requirements for API synthesis. CDSCO-registered manufacturers in Mumbai and Hyderabad concentrate demand through backward-integrated supply agreements that bypass merchant distributors entirely.
- Flavors:Food-grade ester precursors require FSSAI-compliant certification for clean-label formulation trends. Capryloyl-derived natural esters are expanding most quickly as synthetic carriers face replacement pressure in EU and North American food applications.
- Fragrances:Personal care applications concentrate margin pools through fragrance-grade specifications with sensory neutrality requirements.
- Agrochemicals:Crop protection intermediates serve ANVISA-regulated Brazilian manufacturing with less stringent purity tiers than pharmaceutical channels.
Pharmaceuticals dominates installed base. Flavors is where expansion concentrates.
End Use Industry:
Cost structures stratify sharply across end-use tiers, with chemical manufacturing absorbing volume at thinner margins while personal care extracts premium pricing.
- Food & Beverage:Clean-label ester synthesis drives FSSAI-regulated demand for natural flavor carriers. Formulators replace petroleum-derived carriers with capryloyl-based alternatives, compressing procurement cycles toward certified suppliers with full traceability documentation.
- Personal Care:Fragrance-grade specifications for skincare and cosmetics command 40-60% price premiums over industrial grades due to sensory neutrality and low-odor requirements.
- Chemical Manufacturing:Bulk amidation and esterification protocols absorb the largest absolute volumes at standardized purity tiers.
- Coatings:Specialty resin modification applications require consistent acid chloride reactivity rather than ultra-high purity.
Chemical Manufacturing anchors volume throughput. Personal Care captures margin concentration.
Technology:
Technology selection determines capital intensity and regulatory exposure, with synthesis routes facing escalating scrutiny under halogenated solvent regulations.
- Synthesis:Thionyl chloride-mediated chlorination of octanoic acid remains dominant, though continuous flow microreactor adoption is compressing batch cycle times from hours to minutes in Swiss and Singaporean pharmaceutical facilities.
- Extraction:Purification protocols for pharmaceutical-grade material isolate chlorinated byproducts through fractional distillation and adsorption.
- Formulation:Blending and dilution operations for end-use concentration requirements.
- Processing:Final conditioning steps including stabilization and packaging for regulated supply chains.
Synthesis commands capital deployment. Continuous flow platforms are gaining share fastest.
Application:
Application function dictates specification depth, with reactive intermediates requiring full analytical dossiers while stabilizer applications accept broader purity bands.
- Solvents:Reaction media applications in organic synthesis demand anhydrous specifications with moisture content below 50 ppm.
- Intermediate Chemicals:API precursor and agrochemical intermediate applications drive the steepest expansion trajectory through CDSCO-regulated Indian manufacturing clusters.
- Additives:Functional modifiers for polymer and coating systems.
- Stabilizers:Shelf-life extension applications with less stringent purity requirements than pharmaceutical channels.
Intermediate Chemicals dominates value generation. Additives shows emerging volume traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical buyers absorb price premiums for certified material while Brazilian agrochemical formulators remain acutely price-sensitive. European REACH compliance costs widen spreads between registered and unregistered suppliers. Chinese merchant producers face margin compression from feedstock volatility.
India
CDSCO-registered API manufacturers in Mumbai and Hyderabad drive pharmaceutical-grade consumption through backward-integrated supply agreements. The PLI scheme for API intermediates rewards domestic acyl chloride production with tax offsets and capital subsidies. Telangana's Genome Valley pharmaceutical cluster concentrates demand for impurity-profiled material with locked capacity commitments.
Germany
ECHA substance evaluation protocols mandate full analytical dossiers for chlorinated byproducts down to 0.1% mass fraction. REACH registration requirements eliminate unregistered merchant traders from pharmaceutical intermediate channels. BASF SE leverages captive chlorination infrastructure in Ludwigshafen to sustain margin structures smaller competitors cannot replicate.
United States
FDA oversight of pharmaceutical intermediates shapes purity standards for acyl chlorides entering drug synthesis supply chains. Thermo Fisher Scientific Inc. differentiates via pharmaceutical-grade certification and channel control into regulated end markets. New Jersey and Massachusetts pharmaceutical manufacturing corridors concentrate demand for DMF-filed material.
Brazil
ANVISA-regulated crop protection manufacturing lacks domestic acyl chloride capacity, creating import substitution potential for certified exporters. Agrochemical formulators prioritize cost efficiency over ultra-high purity tiers. São Paulo state's agrochemical formulation cluster sources through spot-market channels with less stringent vendor qualification depth.
Switzerland
Swissmedic-regulated pharmaceutical facilities pilot continuous flow microreactor technology for on-demand API precursor synthesis. Modular units compress batch cycle times from hours to minutes while isolating hazardous thionyl chloride exposure. Basel's pharmaceutical research corridor concentrates precision manufacturing investment for high-value intermediate synthesis.
Octanoyl Chloride Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the acyl chloride market. BASF SE and CABB Group GmbH anchor the upper tier through captive chlorination infrastructure and backward integration into thionyl chloride supply. Thermo Fisher Scientific Inc. occupies a distinct position via pharmaceutical-grade certification and controlled distribution into regulated channels. Strategic moves concentrate on capacity expansion in CDSCO-aligned Indian manufacturing zones and technology licensing for continuous flow platforms.
Among German-integrated chemical producers, BASF SE and CABB Group GmbH exemplify the backward-integrated archetype with in-house thionyl chloride production shielding cost structures from feedstock volatility. Thermo Fisher Scientific Inc. represents the certification-driven channel controller, leveraging pharmaceutical-grade dossier coverage to access FDA and EMA-regulated supply chains. Merck KGaA and Sigma-Aldrich Corporation sit within the research-grade distribution tier, serving laboratory-scale demand with catalog breadth rather than bulk manufacturing scale. TCI Chemicals (India) Pvt. Ltd. anchors the emerging-market specialist position, positioned to capture PLI scheme benefits as Indian API intermediate manufacturing expands.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| Sigma-Aldrich Corporation |
| TCI Chemicals (India) Pvt. Ltd. |
| Alfa Aesar |
| Thermo Fisher Scientific Inc. |
| CABB Group GmbH |
| WeylChem Group of Companies |
| Lubrizol Corporation |
| Others |
Value Network & Pricing Analysis
Captive chlorination scale at Ludwigshafen and Frankfurt-Höchst plants sets minimum viable capacity thresholds that marginalize sub-scale merchant producers, compressing price floors toward integrated cost structures while concentrating supply authority among thionyl chloride-backward operators.
Pricing Analysis
After-sales service bundling for pharmaceutical-grade certification and DMF filing support drives lifetime value capture beyond base chemical offtake. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates EMA-registered producers from FSSAI-compliant flavor suppliers and commodity amidation buyers. Pricing pressure stems from palm kernel oil feedstock volatility transmitting through octanoic acid spot markets. Agrochemical formulators in São Paulo state exhibit highest price sensitivity, while CDSCO-registered API manufacturers in Hyderabad absorb premiums for locked capacity and audit depth.
Supply Chain Analysis
Inbound logistics costs from Rotterdam-Antwerp chemical corridors through Hamburg port congestion periodically strain thionyl chloride delivery schedules for non-integrated German producers. Manufacturing concentrates in Germany, India, and Switzerland, with merchant capacity in China facing margin compression from feedstock swings. Raw material dependencies center on octanoic acid from palm kernel and coconut oil fractionation, thionyl chloride from sulfur-chlorine integration, and phosphorus pentachloride alternatives. Single-source vulnerability around Indian CDSCO-registered API clusters creates geographic concentration risk. Distribution runs through qualified supplier networks for pharmaceutical grades and spot-market chemical distributors for industrial tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as clean-label flavor ester demand and continuous flow technology adoption create service-layer niches beneath integrated chemical majors.
For Market Incumbents: Consolidate through captive thionyl chloride capacity additions in CDSCO-aligned Indian manufacturing zones, defending against backward-integrating API formulators in Telangana's Genome Valley. Lock in multi-year capacity commitments from Mumbai and Hyderabad pharmaceutical clusters before qualification timelines freeze supplier switches. Prioritize continuous flow microreactor licensing to capture technology differentiation as batch chlorination faces PFAS regulatory pressure. For New Entrants and Emerging Players: Custom synthesis service gaps in Swissmedic-regulated Basel corridor and ANVISA-aligned Brazilian agrochemical import channels offer white-space entry points. Target underpenetrated São Paulo agrochemical formulation with spot-market flexibility and faster qualification cycles than integrated majors permit. Lead with modular microreactor deployment for on-demand API precursor production, bypassing capital-intensive batch infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade certification holders with locked capacity agreements and DMF dossier coverage. Long-term viability hinges on regulatory chemistry capabilities and thionyl chloride supply security rather than commodity scale. Acquisition focus should center on mid-cap specialists with ECHA-registered status and Indian PLI scheme alignment. Watch for CDSCO impurity profiling mandate expansion as inflection signal for certified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thionyl Chloride | CABB Group GmbH's captive SOCl2 supply shields margin structures from feedstock volatility smaller merchants cannot match. |
| Continuous Flow Microreactor Deployment | Swissmedic-regulated Basel facilities compress batch cycle times from hours to minutes while isolating hazardous chlorination exposure. |
| Pharmaceutical-Grade Certification Investment | Thermo Fisher Scientific Inc. leverages FDA and EMA DMF coverage to access regulated supply chains with audit-heavy vendor qualification. |
| PLI Scheme Capacity Expansion in India | Telangana's Genome Valley pharmaceutical cluster concentrates demand for impurity-profiled material with tax-offset and capital-subsidy support. |
| Long-term Supply Agreement Lock-in | CDSCO-registered API manufacturers in Mumbai and Hyderabad demand dedicated production lines and committed capacity from acyl chloride suppliers. |
Research Methodology
Operator-level perspectives from plant managers at integrated chlorination facilities, procurement leads at CDSCO-registered API manufacturers, distribution channel partners in Rotterdam-Antwerp chemical corridors, and technical R&D directors at pharmaceutical-grade producers anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, Cefic and ACC chemical industry reports, SEC 10-K filings from listed chemical majors, and ECHA substance evaluation dossiers. Bottom-up capacity and consumption estimates triangulated against top-down value-chain reconstructions across the analysis window.
Sensitivity analysis around feedstock price volatility, regulatory timeline compression, and technology substitution scenarios shaped the analytical framework. Segmentation dimensions modeled include purity grade tier, end-use industry application, synthesis technology type, and regional production hub concentration. CAGRs derived from trend extrapolation with cross-validation against historical capacity expansion patterns and announced investment pipelines. Forecast inputs incorporated PLI scheme disbursement trajectories and REACH authorization timeline assumptions.
Underlying assumptions cover sustained palm kernel oil supply availability, ECHA impurity threshold stability, and CDSCO regulatory alignment with ICH guidelines, with deviation risk concentrated in PFAS restriction acceleration and thionyl chloride feedstock disruption. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement intensity and Indian domestic manufacturing incentive evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Global Palm Wax Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Ethylhexyl Cocoate Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Glycerine Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Europe Wax Market