
 Mancozeb Market | 2026-2036
Mancozeb Market Size, Share, and Industry Trends Forecast 2026-2036
Mancozeb Market Analysis
India is rewriting the global supply map for mancozeb with expanded technical-grade capacity in Gujarat and Andhra Pradesh. UPL leverages backward integration into ethylene bisdithiocarbamate intermediates to protect margin pools. Corteva anchors its position through proprietary wettable powder formulations optimized for tropical humidity. Indofil Industries Limited dominates the Indian domestic channel with deep distribution into Maharashtra's soybean belt.
Mancozeb is a broad-spectrum ethylene bisdithiocarbamate fungicide supplied as granules, liquid, powder, or suspension, with a typical metal content of 20% manganese and zinc complexed in a polymeric dithiocarbamate structure that releases toxic carbon disulfide upon fungal contact. The compound serves primarily as a protective foliar treatment against downy mildew, early blight, and rust in high-value vegetable and field crops. Powder formulations retain the largest volume share due to compatibility with existing farmer equipment and lower per-unit logistics costs, though liquid suspensions represent the fastest-growing category as precision spraying infrastructure spreads. Agricultural crops absorb the dominant share of end-user demand, while horticulture commands the highest per-hectare application rates and associated margin premiums.
India's Central Insecticides Board mandates residue limits under the Insecticides Act, while the EU's REACH and MDR frameworks restrict import tolerances and drive reformulation toward reduced-dose delivery. The US EPA reviews ethylene bisdithiocarbamate cumulative risk assessments periodically, influencing reregistration timelines and label restrictions. Stakeholders must monitor regulatory divergence between jurisdictions where residue thresholds tighten and those where food security priorities sustain broader approval windows.
Market Dynamics
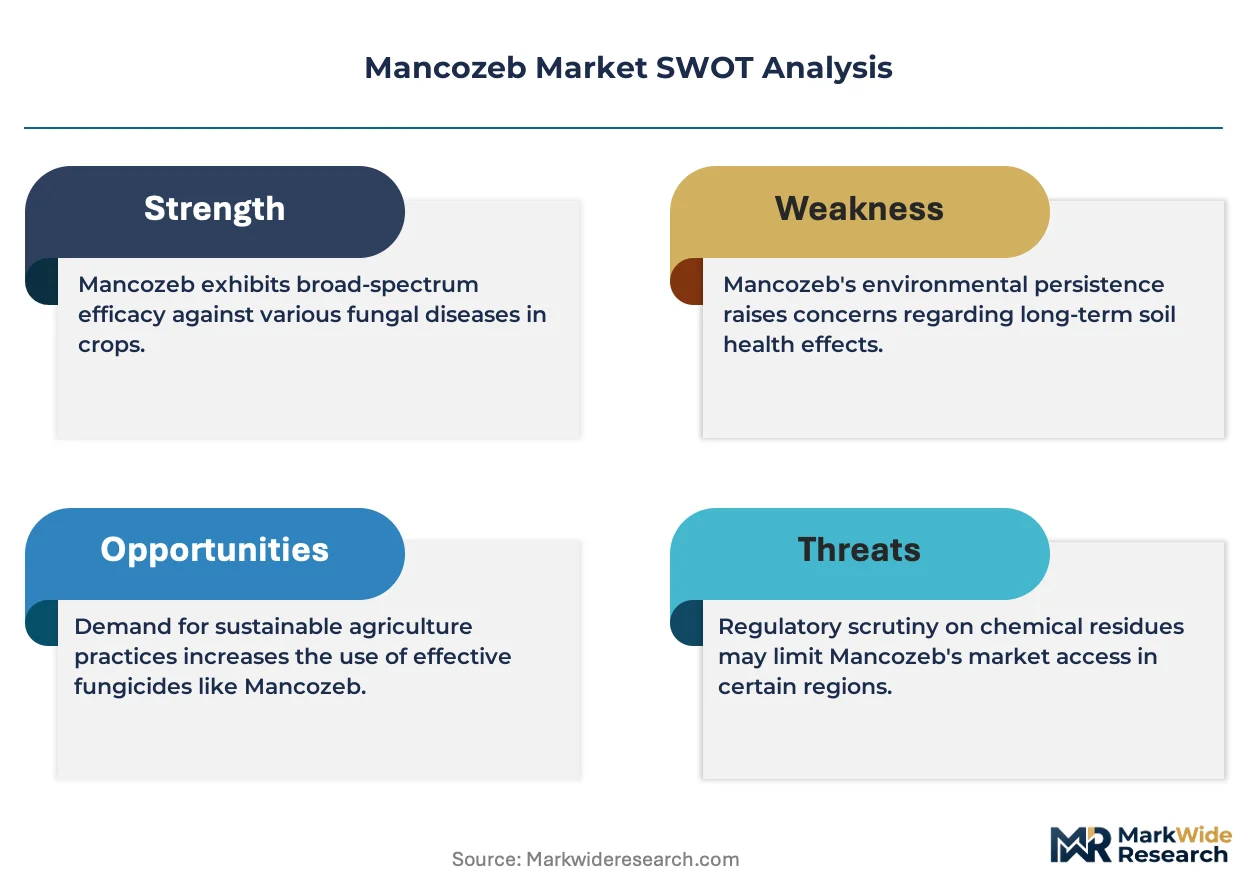
India's Central Insecticides Board and the EU's REACH framework are compressing residue tolerances simultaneously, forcing manufacturers to reformulate delivery systems while maintaining cost structures suited to price-sensitive agricultural buyers.
Growth Catalysts
- Soybean cultivation expansion:Maharashtra and Gujarat farmers are intensifying protective fungicide applications as downy mildew pressure mounts across India's western agrarian belt.
- REACH reformulation mandates:The EU's tightening ethylene bisdithiocarbamate residue thresholds are accelerating investment in lower-dose suspension concentrate technologies.
- Precision spraying infrastructure:Drone-based application systems are penetrating Andhra Pradesh's horticulture corridors, creating pull for liquid suspension formats.
Market Restraints
- Ethylene bisdithiocarbamate intermediate concentration:Technical-grade production clusters in Gujarat and China create input vulnerability for non-integrated formulators.
- F-Gas Regulation residue compression:The EU's cumulative risk assessment framework is narrowing import tolerance windows faster than reformulation cycles can adapt.
- Biofungicide substitution:Trichoderma-based biological controls are capturing organic-certified vegetable acreage in Karnataka and Maharashtra.
Strategic Opportunities
- Andhra Pradesh horticulture belt:Chili and tomato cultivation in Guntur and Warangal districts remains underpenetrated by suspension concentrate distributors.
- PLI scheme alignment:India's production-linked incentive framework for agrochemical intermediates rewards captive ethylene bisdithiocarbamate capacity expansion.
- Drone-as-a-service channels:Agritech platforms in Punjab and Haryana are creating direct-to-farmer liquid formulation procurement pathways outside traditional dealer networks.
Industry Challenges
- Analytical chemistry capacity:Residue testing laboratory scarcity in Madhya Pradesh and Rajasthan delays export certification timelines for bulk shipments.
- Legacy powder formulation infrastructure:Wettable powder manufacturing assets require capital-intensive retrofitting to produce low-dose suspension concentrates compliant with EU MRL standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mancozeb Market |
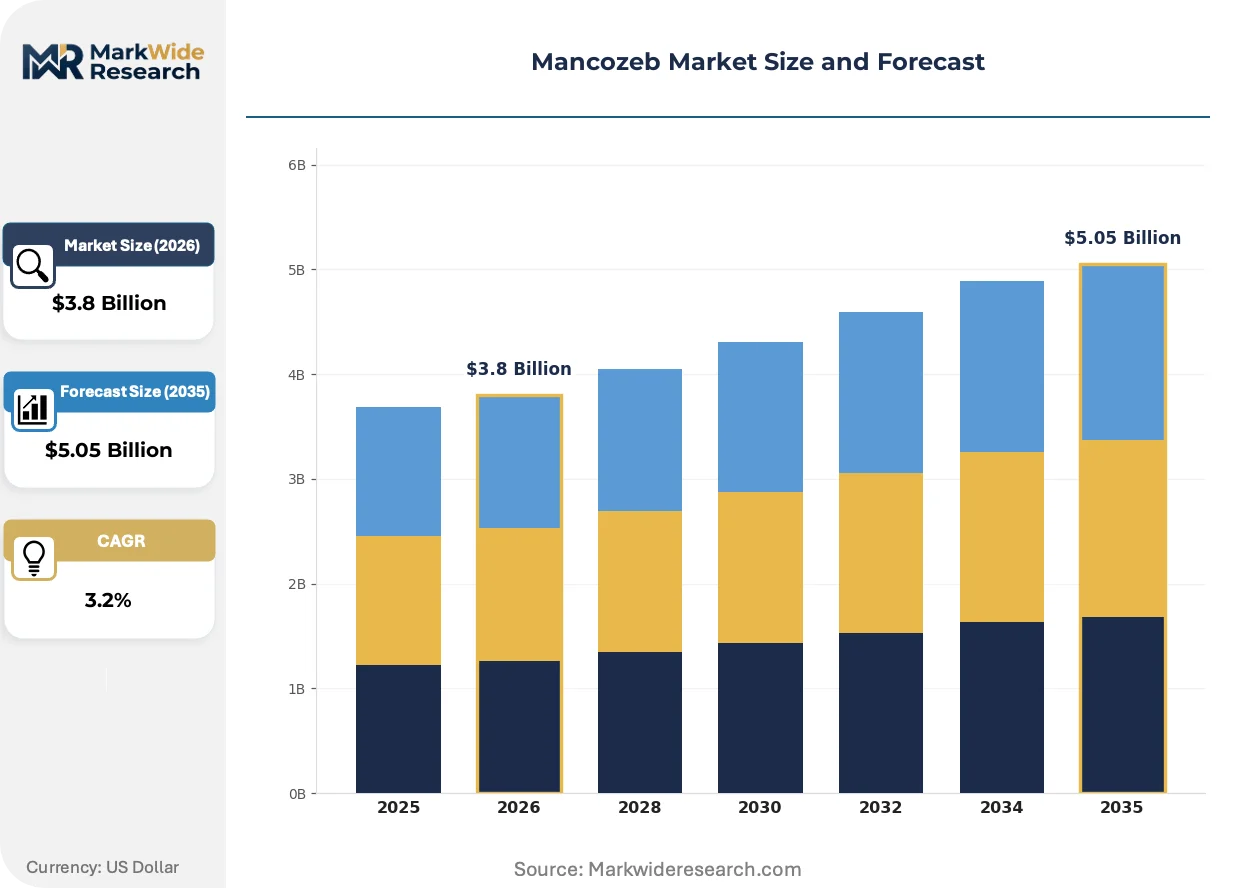
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid, Powder, Suspension Application: Agricultural Crops, Horticulture, Turf, Ornamental Plants End User: Farmers, Landscapers, Gardeners, Agricultural Institutions Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | UPL, Corteva, Indofil Industries Limited, Coromandel International Limited, Limin Group Co., Ltd., ADAMA, Nufarm, Syngenta, Sumitomo Chemical Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mancozeb Market Emerging Trajectories
Nano-delivery systems and precision application hardware are converging to compress dose rates per hectare. Regulatory divergence between residue-tightening jurisdictions and food-security-prioritized markets is forcing bifurcated product development pipelines.
Suspension concentrate formulations employing sub-micron particle milling are penetrating Maharashtra's soybean belt. Large-scale cooperative procurement societies in Jalgaon and Latur are adopting these liquid systems for drone compatibility. Traditional wettable powder formats are rendering obsolete in high-mechanization districts where spray drift regulations tighten.
The EU's F-Gas Regulation and REACH cumulative risk assessments are tightening ethylene bisdithiocarbamate residue limits in parallel. Formulators are accelerating co-formulation with systemic fungicides to reduce mancozeb load per application. Export-oriented technical-grade producers in Gujarat face compressed reregistration timelines as ECHA reviews escalate.
Cooperative buying collectives in Maharashtra are consolidating procurement volumes to negotiate direct manufacturer pricing. Traditional multi-tier distributor networks in groundnut-growing districts are losing volume to these aggregated purchasing bodies. The disintermediation trend is most visible in Gujarat's Saurashtra region where farmer producer organizations command bulk tender participation.
Mancozeb Market Segmentation
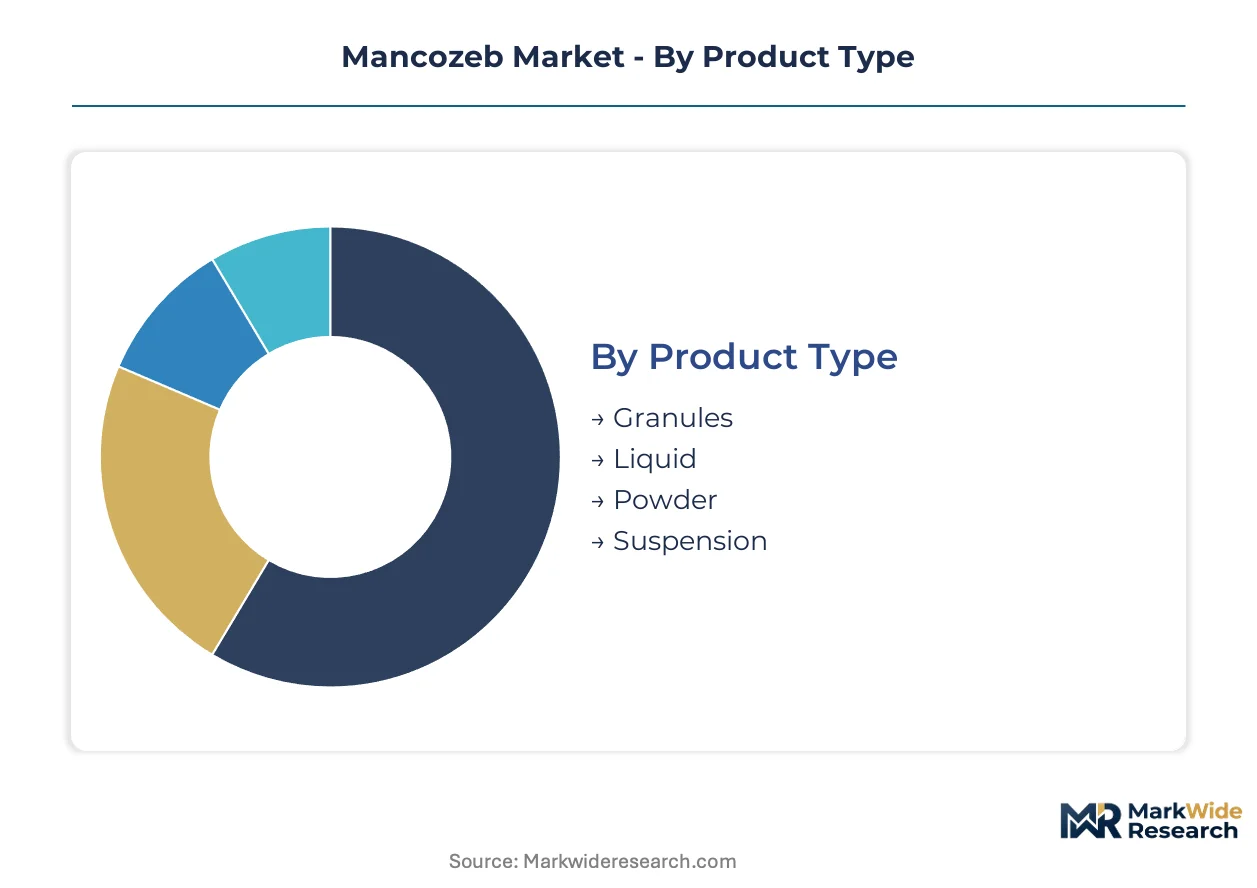
Mancozeb formulations diverge sharply in performance economics and regulatory compliance pathways. Product format selection determines residue management feasibility, application labor requirements, and access to precision agriculture infrastructure.
Product Type:
Formulation chemistry dictates dose efficiency, storage stability, and compatibility with mechanized spraying systems across India's western agrarian belt.
- Powder:Wettable powder formulations combine 80% active ingredient with dispersing agents for tank-mix compatibility. Maharashtra's soybean cooperatives favor this format for existing backpack sprayer fleets and lower per-kilogram freight costs from Gujarat technical-grade plants.
- Suspension:Sub-micron particle milling delivers 40-50% active loads in aqueous dispersion. Drone-as-a-service operators in Andhra Pradesh's chili corridors are pulling this category fastest as spray drift regulations tighten and water scarcity raises tank-mix efficiency premiums.
- Liquid:Ready-to-use solutions eliminate field mixing errors. Landscapers and ornamental nurseries in Karnataka's peri-urban belts absorb concentrated volumes.
- Granules:Soil-applied formulations release active ingredient through moisture activation. Turf management contracts in Haryana's golf and cricket ground maintenance channels sustain niche demand.
Powder commands the established base. The steepest expansion runs through suspension.
Application:
Crop value per hectare and fungal pressure intensity segment mancozeb demand into distinct margin pools and technical service requirements.
- Agricultural Crops:Soybean, groundnut, and wheat plantings across Maharashtra and Gujarat drive protective fungicide protocols against downy mildew and rust complexes. Central Insecticides Board residue limits shape application calendars and pre-harvest intervals.
- Horticulture:Chili, tomato, and grape cultivation commands the highest per-hectare application rates and associated formulation premiums. Guntur and Warangal districts in Andhra Pradesh concentrate procurement volume for high-value export-oriented produce.
- Turf:Sports field and golf course maintenance in Punjab and Haryana sustains steady demand for systemic-protective co-formulations.
- Ornamental Plants:Nursery stock and floriculture operations in Karnataka and Tamil Nadu absorb specialized low-phytotoxicity variants.
Agricultural crops anchor volume throughput. Horticulture generates the steepest margin expansion.
End User:
Scale of operation and technical advisory access determine procurement channel selection and price sensitivity thresholds.
- Farmers:Smallholder plots under five hectares dominate Indian consumption. Cooperative buying collectives in Jalgaon and Latur districts are consolidating volumes to negotiate direct manufacturer pricing outside traditional dealer markups.
- Agricultural Institutions:State agricultural universities and Krishi Vigyan Kendras conduct demonstration trials and extension programs. Their procurement influences neighboring farmer adoption patterns.
- Landscapers:Commercial grounds maintenance contractors in urban corridors require consistent supply security and bulk packaging formats.
- Gardeners:Household-scale consumers access mancozeb through retail garden centers for ornamental and vegetable plot protection.
Farmers absorb the dominant share. Agricultural institutions shape adoption velocity fastest.
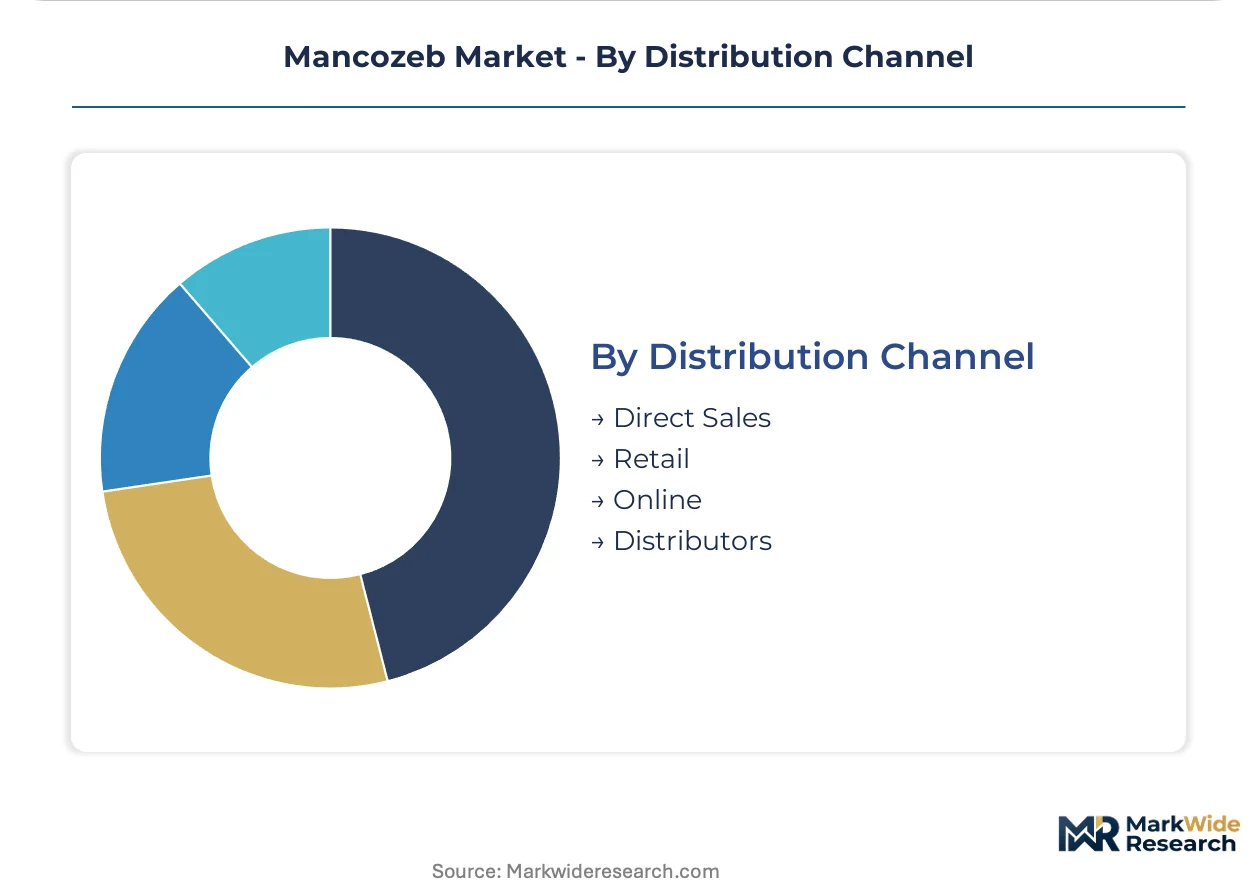
Distribution Channel:
Channel structure determines working capital intensity, technical service embedding, and exposure to regulatory compliance documentation.
- Distributors:Multi-tier dealer networks spanning state-level stockists to village-level retailers still handle the majority of wettable powder volumes. Gujarat's Saurashtra region maintains dense traditional coverage.
- Direct Sales:Manufacturer-to-cooperative contracts are penetrating Maharashtra's groundnut belt. Farmer producer organizations command bulk tender participation with compressed payment cycles.
- Retail:Agricultural input shops and garden centers serve fragmented smallholder demand with immediate availability.
- Online:Agritech platforms in Punjab and Haryana are creating direct-to-farmer liquid formulation procurement pathways, bypassing dealer credit dependencies.
Distributors retain the volume core. Direct sales channels are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical-grade production clusters in Gujarat and China concentrate upstream supply, while downstream formulation demand fragments across tropical and subtropical growing belts. Regulatory divergence between residue-tightening jurisdictions and food-security-prioritized markets shapes regional competitive positioning.
India
Maharashtra's soybean belt and Gujarat's groundnut cultivation drive protective fungicide procurement at scale. The Central Insecticides Board enforces residue limits under the Insecticides Act, compressing pre-harvest intervals. Jalgaon and Latur districts host cooperative buying collectives that consolidate volumes for direct manufacturer negotiation.
China
Ethylene bisdithiocarbamate intermediate manufacturing anchors the supply base for export-oriented technical-grade output. The Ministry of Ecology and Environment reviews chemical production licensing under evolving environmental compliance frameworks. Jiangsu and Shandong provinces concentrate active ingredient synthesis capacity serving Asian and African formulation markets.
United States
Soybean rust management in the Midwest and specialty crop protection in California sustain import demand for suspension concentrate formats. The EPA conducts periodic cumulative risk assessments for ethylene bisdithiocarbamate reregistration, influencing label restrictions. Gulf Coast ports handle bulk technical-grade arrivals for domestic wettable powder repackaging.
Brazil
Soybean monoculture expansion across Mato Grosso and Paraná intensifies protective fungicide application protocols. ANVISA administers residue tolerance frameworks that align with Mercosur trade harmonization pressures. Campinas and São Paulo state house formulation facilities serving South American distribution networks.
Germany
REACH enforcement through ECHA tightens ethylene bisdithiocarbamate import thresholds faster than reformulation cycles adapt. The F-Gas Regulation parallels residue compression for agricultural chemical co-formulants. Frankfurt and Hamburg concentrate regulatory affairs capacity for EU-27 compliance navigation.
Mancozeb Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with intermediate and technical-grade supply control. The vendor base stratifies between backward-integrated formulators with captive ethylene bisdithiocarbamate capacity and non-integrated blenders exposed to input price volatility. Two archetypes dominate: multinational agrochemical platforms with tropical formulation expertise, and regional specialists with deep distribution into price-sensitive smallholder markets. Competitive moves center on capacity expansion in Gujarat and Andhra Pradesh, and portfolio diversification into suspension concentrate technologies.
Among the integrated platform tier, UPL anchors positions through backward integration into ethylene bisdithiocarbamate intermediates. Corteva occupies a position exemplifying proprietary wettable powder optimization for tropical humidity conditions. Indofil Industries Limited represents the regional specialist archetype with concentrated distribution into Maharashtra's cooperative procurement channels.
| Leading Market Players |
|---|
| UPL |
| Corteva |
| Indofil Industries Limited |
| Coromandel International Limited |
| Limin Group Co., Ltd. |
| ADAMA |
| Nufarm |
| Syngenta |
| Sumitomo Chemical Co Ltd |
| Others |
Supply Flow & Price Mechanics
The Mumbai-Jawaharlal Nehru Port freight corridor transmits cost volatility from Gujarat's technical-grade plants to Maharashtra's cooperative buyers, compressing margins for non-integrated formulators while rewarding backward-integrated players with captive ethylene bisdithiocarbamate capacity. This logistics artery concentrates pricing power among manufacturers with upstream control, forcing price-sensitive smallholders toward bulk procurement collectives.
Pricing Analysis
REACH dictates the pricing tier structure across export-oriented and domestic-only product lines. Three-tier pricing separates EU-compliant suspension concentrates from standard wettable powders and unregistered economy grades. Price differentiation rests on residue certification levels and volume scale, with export-grade formulations commanding substantial premiums. Cost compression in the powder tier is intensifying because of biofungicide substitution in Karnataka's organic belts. Smallholder cooperatives exhibit the highest price sensitivity, while horticulture exporters in Andhra Pradesh absorb premium tiers with minimal elasticity.
Supply Chain Analysis
Extended payment terms from Gujarat technical-grade producers to Maharashtra formulators have become standard working capital practice, with 90-day cycles now baseline. Geographic supply concentrates in India, China, and Brazil for ethylene bisdithiocarbamate intermediates and downstream formulation. Raw material dependencies include carbon disulfide, ethylene diamine, and manganese sulfate. Single-source vulnerability runs through Jiangsu province's intermediate synthesis clusters. Distribution runs through multi-tier dealer networks in Gujarat's Saurashtra region, though direct-to-cooperative channels are displacing traditional stockists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against Trichoderma-based biological controls capturing organic-certified acreage in Maharashtra and Karnataka. The analytical framework treats biofungicide penetration as the primary demand erosion threat requiring strategic response.
For Market Incumbents: Insulate core margin pools by accelerating captive ethylene bisdithiocarbamate capacity expansion under India's PLI scheme for agrochemical intermediates. Secure cooperative procurement contracts in Jalgaon and Latur districts before drone-as-a-service platforms disintermediate traditional dealer networks. The priority defensive lever is backward integration into technical-grade production. For New Entrants and Emerging Players: Establish a beachhead in Andhra Pradesh's underpenetrated chili and tomato suspension concentrate corridors, where Guntur and Warangal districts lack dedicated liquid formulation distributors. Target horticulture cooperatives seeking EU export compliance with lower-dose delivery systems. The optimal go-to-market angle partners with drone-as-a-service operators for direct farmer access. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational agrochemical parents seeking to divest legacy wettable powder assets amid REACH-driven reformulation cycles. Long-term viability hinges on exposure to suspension concentrate technology and Indian domestic channel control. The signal to watch is ECHA's cumulative risk assessment timeline compression, which would accelerate stranded asset recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EBDC Intermediates | Captive supply of ethylene bisdithiocarbamate insulates margin pools from Gujarat-China input volatility. |
| Suspension Concentrate Capacity Expansion | Sub-micron milling capabilities unlock EU export access and drone-spraying compatibility in Andhra Pradesh. |
| Direct-to-Cooperative Channel Development | Bypassing Saurashtra's dealer networks captures procurement volume from Maharashtra's farmer producer organizations. |
| Residue Testing Laboratory Investment | Analytical chemistry capacity in Madhya Pradesh accelerates export certification timelines for bulk shipments. |
| Biofungicide Co-Formulation Partnership | Hybrid biological-chemical positioning defends against Trichoderma substitution in Karnataka organic belts. |
Methodological Framework
Desk research of customs trade filings, Central Insecticides Board registration databases, and ECHA regulatory submissions preceded structured interviews with formulation plant managers, cooperative procurement officers, drone-as-a-service operators, and agricultural extension directors. Primary fieldwork across Maharashtra's soybean belt and Gujarat's technical-grade clusters was validated against secondary trade flow data and SEC filings from listed agrochemical platforms. Bottom-up volume estimates from district-level cooperative procurement data were triangulated with top-down technical-grade production capacity assessments.
Assumptions held fixed include REACH residue limit enforcement intensity, PLI scheme continuation for agrochemical intermediates, and drone-spraying infrastructure penetration rates in Andhra Pradesh and Punjab. Variables stress-tested encompass ethylene bisdithiocarbamate intermediate pricing volatility, biofungicide substitution velocity in organic-certified acreage, and EU import tolerance compression timelines. Segmentation dimensions modeled include formulation chemistry, crop application type, end-user scale, and distribution channel structure. CAGRs were derived from trend extrapolation of cooperative procurement volumes and technical-grade capacity expansion announcements.
Stress conditions across regulatory enforcement intensity, biological substitution rates, and input cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding residue limit trajectories and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Europe Lime Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Pivaloyl Chloride Market