
 Chlorine Dioxide Market | 2026-2036
Chlorine Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorine Dioxide Market Analysis
Modular on-site generation systems is rebalancing procurement patterns across municipal and industrial buyers who previously relied on bulk chemical delivery. Evoqua Water Technologies LLC leverages integrated generator-to-control architecture to anchor large utility contracts in North America. ProMinent GmbH specializes in compact European-format skids that compete effectively in space-constrained treatment plants. CDG Environmental LLC sustains its position through technology leadership in precursor-handling safety systems.
Chlorine dioxide is an unstable, highly reactive oxidizing agent with a molecular weight of 67.45 g/mol, typically generated on-site from sodium chlorite and acid activators because concentrated forms decompose explosively above partial pressures of 0.1 atm. Its primary commercial purpose centers on selective microbial inactivation with minimal halogenated byproduct formation compared to elemental chlorine. Solution-format delivery dominates current revenue owing to established logistics infrastructure, while on-site generation commands expanding share as safety regulations tighten on precursor transport. Water treatment applications anchor volume demand, though food processing disinfection represents the fastest-growing end-use segment as processors substitute chlorine dioxide for peracetic acid in certain wash systems.
EPA Office of Water enforces Stage 2 Disinfectants and Disinfection Byproducts Rules that directly elevate chlorine dioxide demand by constraining total trihalomethane allowances in finished drinking water. EU F-Gas Regulation and REACH compliance frameworks shape product formulation standards and equipment material specifications for suppliers operating across European member states. OSHA permissible exposure limits and DOT hazardous materials classifications in the United States govern worker safety protocols and shipping container requirements for precursor chemicals. Stakeholders must monitor evolving state-level PFAS contamination mandates that could redirect municipal capital toward advanced oxidation trains where chlorine dioxide serves as pretreatment.
Market Dynamics
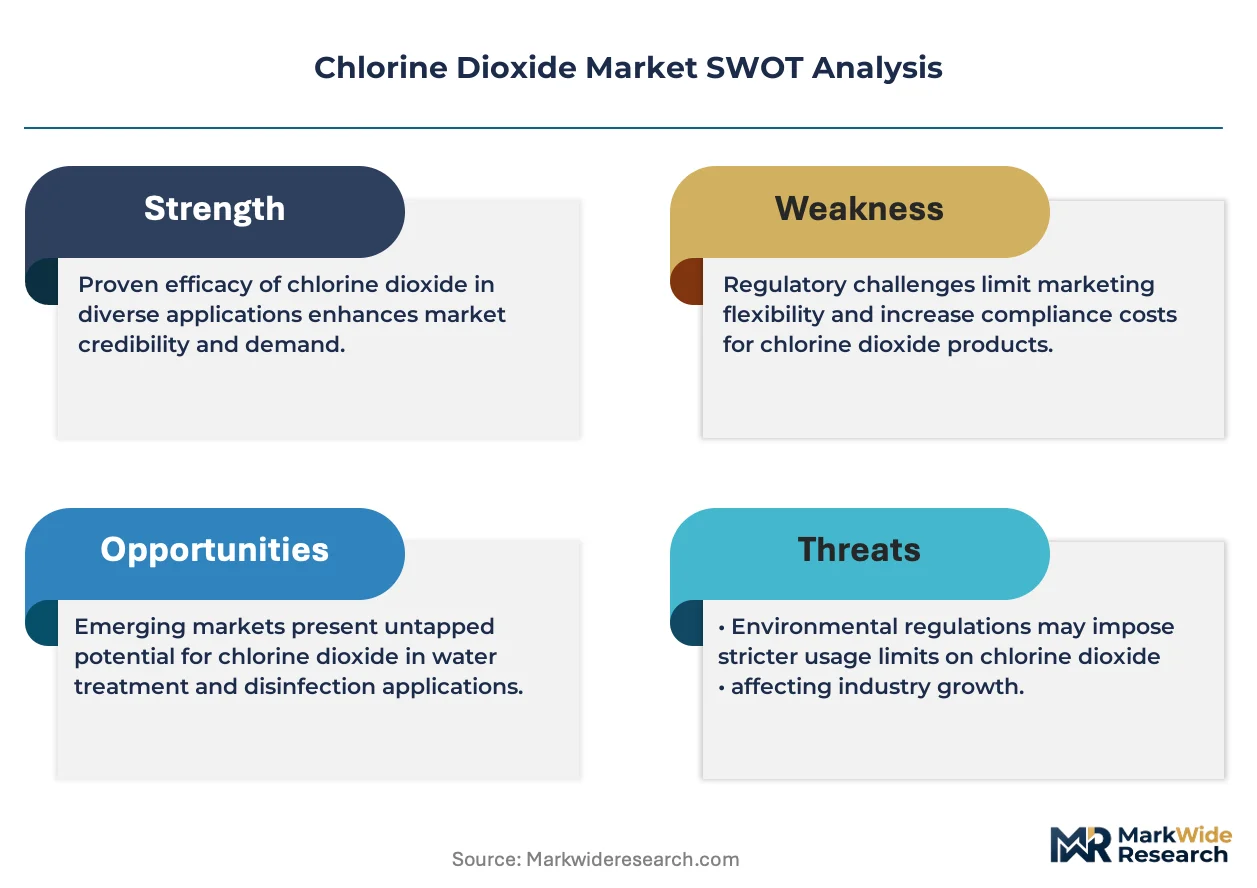
On-site generation technology is restructuring procurement economics for chlorine dioxide buyers, compressing the delivered-chemical channel while elevating capital-equipment relationships with generator suppliers. Municipal utilities now face a binary choice between operational expenditure models and upfront capital deployment with lower lifetime precursor costs.
Growth Catalysts
- EPA Stage 2 Disinfectants and Disinfection Byproducts Rules:The regulation's trihalomethane limits compel water utilities to abandon elemental chlorine for primary disinfection. Chlorine dioxide's selective oxidation chemistry delivers compliant finished water without the halogenated byproduct burden.
- Food processing wash systems:Poultry and produce processors are substituting chlorine dioxide for peracetic acid in certain applications, driven by residue-profile advantages and equipment compatibility with existing flume infrastructure.
- Germany's transport safety enforcement:Stiffened hazardous materials routing restrictions for sodium chlorite tankers concentrate demand for localized generation systems at municipal treatment plants across Bavaria and North Rhine-Westphalia.
Market Restraints
- Precursor cost volatility:Sodium chlorite supply concentrates with a limited producer base, exposing municipal buyers to input price swings that erode the economic case against delivered hypochlorite alternatives.
- Technical decomposition risk:Chlorine dioxide's explosive instability above 0.1 atm partial pressure mandates complex on-site engineering that disqualifies smaller treatment facilities lacking capital maintenance capacity.
- Substitution by UV-LED systems:Advanced ultraviolet technology is capturing niche municipal contracts where byproduct elimination outweighs oxidation strength requirements, particularly in groundwater-dependent utilities.
Strategic Opportunities
- India's municipal water infrastructure:Underpenetrated secondary cities lack legacy chlorine entrenchment, creating greenfield adoption potential as the country's national water quality framework tightens microbial standards.
- Cooling tower biofouling control:Power generation and data center operators represent an emerging application vertical where chlorine dioxide's biofilm penetration outperforms traditional non-oxidizing biocides.
- EU F-Gas Regulation compliance:The framework's phase-down schedules for fluorinated gases create indirect tailwinds for chlorine dioxide in industrial refrigeration system sanitization applications.
Industry Challenges
- Specialized technician scarcity:Safe operation of precursor-handling systems demands certified personnel with cross-training in chemical process safety and water treatment operations, a profile scarce in rural utility labor markets.
- Legacy SCADA integration complexity:Generator control architecture must interface with decades-old municipal automation infrastructure, extending deployment timelines and requiring custom protocol bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorine Dioxide Market |
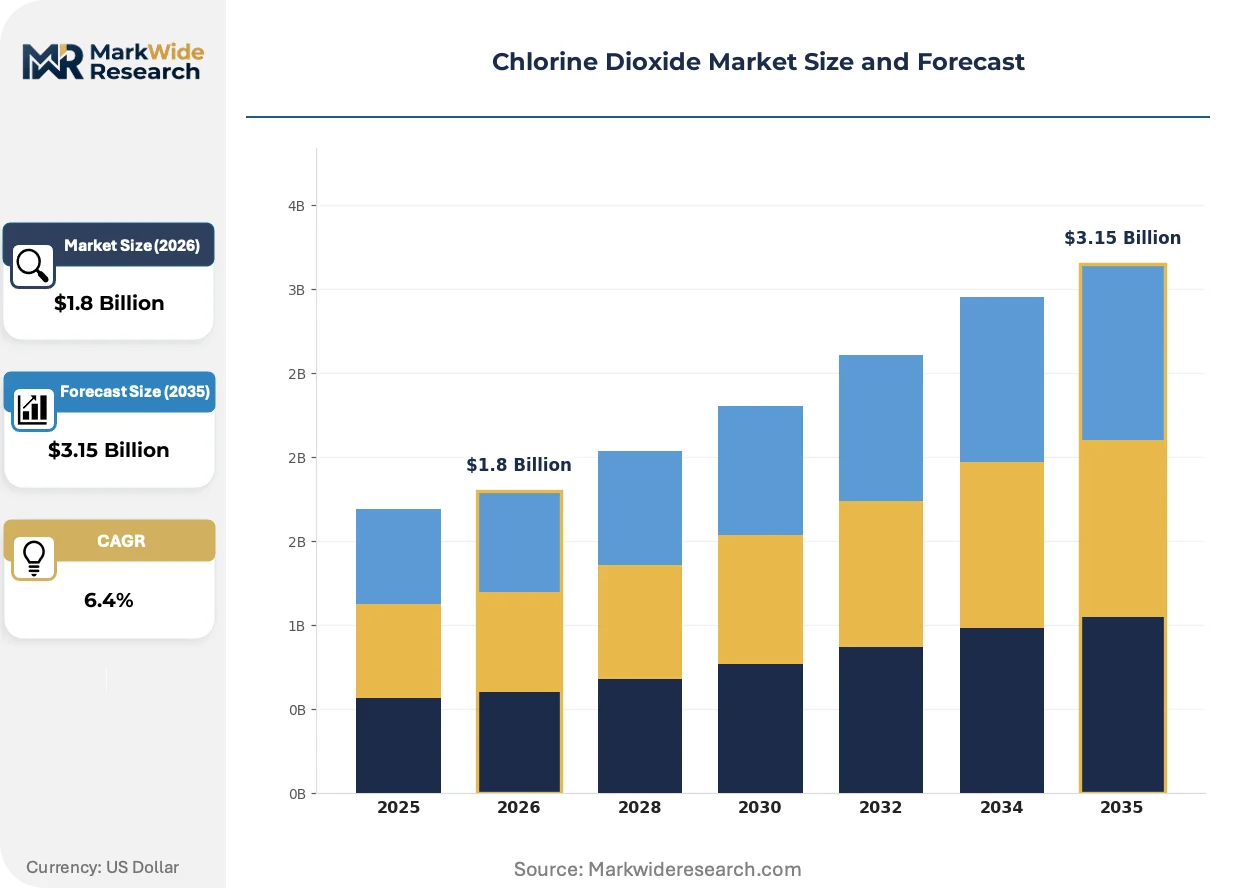
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Solution, Powder, Granules Application: Water Treatment, Wastewater Treatment, Disinfection, Bleaching End User: Municipalities, Industrial Sector, Agriculture, Food Processing Delivery Mode: Bulk, Portable, On-site Generation, Packaged Solutions |
| Companies Covered | Grundfos Holding A/S, Accepta LLC, Ecolab Inc., BASF SE, Chemours Company, Evoqua Water Technologies LLC, CDG Environmental LLC, Sabre Technologies LLC, ProMinent GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorine Dioxide Market Emerging Trajectories
Electrochemical generation methods are displacing traditional acid-chlorite chemistry across industrial installations, altering the competitive terrain for equipment suppliers. This technological pivot redefines the precursor supply chain while reshaping buyer relationships with chemical distributors.
Membrane-electrode chlorine dioxide generation is overtaking acid-activation systems in food processing applications. The technology eliminates sulfuric acid handling entirely, reducing safety protocol burden for plant operators. Major poultry processors in the United States are adopting electrochemical units at replacement cycle points, compressing demand for conventional generator skids and forcing incumbent suppliers to retool product architectures toward electrochemical platforms.
REACH authorization requirements for chlorite precursors are tightening material specifications across European supply chains. The regulation's downstream user obligations now extend to generator equipment certification, elevating compliance costs for non-EU manufacturers. German and Dutch water utilities are prioritizing suppliers with pre-validated component traceability, shifting procurement evaluation criteria toward regulatory documentation depth rather than unit cost alone.
Utility buyers are consolidating chemical procurement under integrated service contracts that bundle generator maintenance with precursor supply. The model displaces transactional chemical purchasing and transfers operational risk to equipment vendors. This restructuring concentrates most visibly in United States municipal utilities with strained in-house technical capacity, where performance-based contracts now dominate RFP structures for plants above 10 MGD capacity.
Chlorine Dioxide Market Segmentation
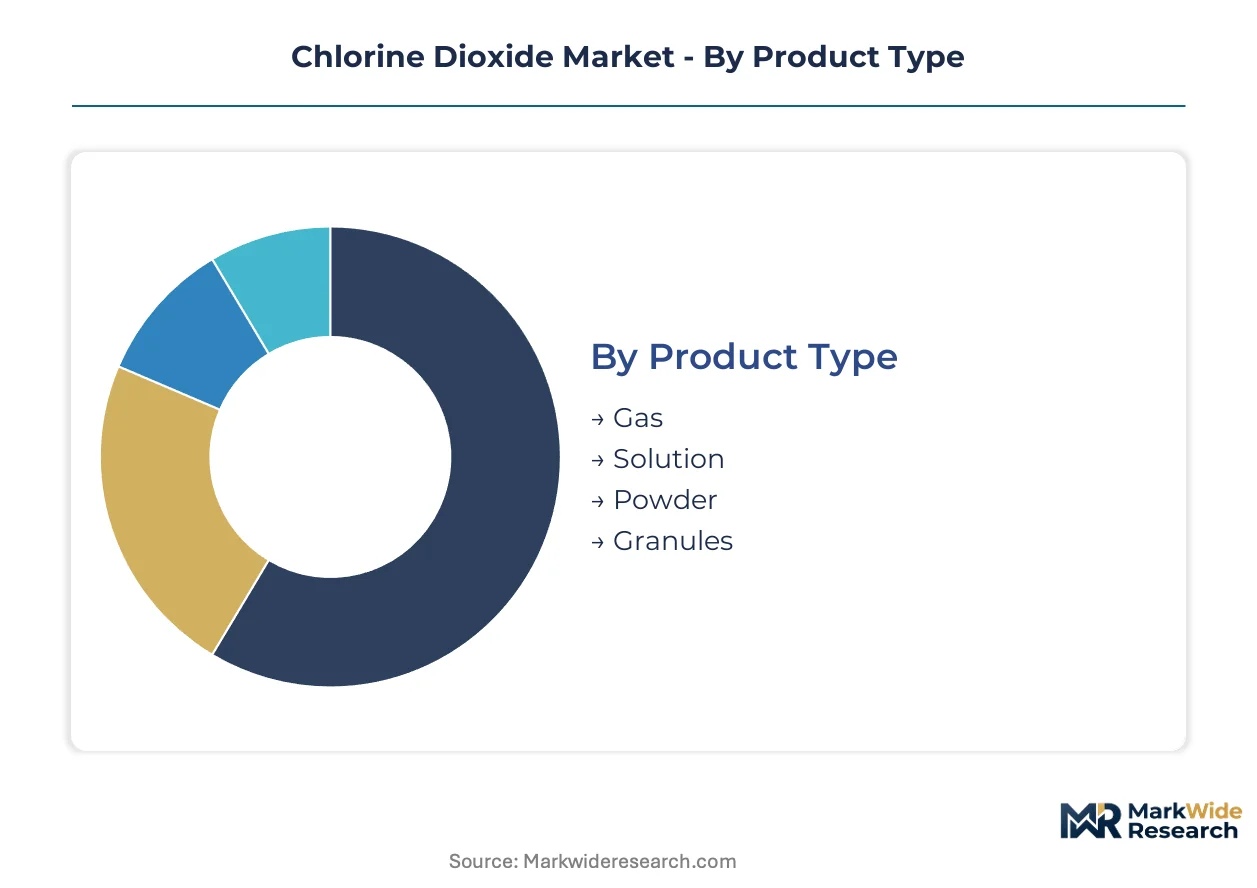
Segmentation reveals how chlorine dioxide procurement splits between capital-intensive generation systems and recurring chemical purchases. Understanding these divisions exposes where supplier relationships consolidate and where buyer power concentrates across municipal and industrial accounts.
Product Type:
Replacement cycles favor formats that minimize transport liability while preserving oxidation potency, with upgrade decisions pivoting on facility engineering capacity and precursor access.
- Solution:Stabilized aqueous formulations at 2-3% concentration dominate current revenue through established tanker logistics and direct-feed compatibility with existing dosing infrastructure. Municipal utilities in Germany and the United States anchor demand as transport regulations for hazardous precursors stiffen.
- On-site Generation Systems:Electrochemical and acid-activation skids eliminate precursor shipping entirely, capturing procurement share at plants above 10 MGD capacity where capital budgets accommodate automated control architecture. Bavarian and North Rhine-Westphalian utilities prioritize these units under tightened hazardous materials routing restrictions.
- Gas:Pure chlorine dioxide gas requires specialized containment and finds limited application in controlled industrial settings.
- Powder:Stabilized precursor blends serve remote facilities lacking liquid handling infrastructure.
- Granules:Slow-release formulations target small-scale agricultural and food processing applications.
Volume placements concentrate in Solution; the faster expansion belongs to On-site Generation Systems.
Application:
Cost tier differentiation separates applications where regulatory compliance commands premium pricing from those competing on operational expenditure alone.
- Water Treatment:Primary disinfection for drinking water utilities drives the largest absolute volume, with EPA Stage 2 Disinfectants and Disinfection Byproducts Rules compelling abandonment of elemental chlorine to meet trihalomethane limits. North American municipalities anchor this tier.
- Disinfection:Food processing wash systems represent the steepest expansion trajectory as poultry and produce processors substitute chlorine dioxide for peracetic acid to achieve residue-profile advantages without flume infrastructure replacement.
- Wastewater Treatment:Odor control and effluent polishing applications compete on cost with alternative oxidants.
- Bleaching:Pulp and textile applications face pressure from oxygen-based alternatives in sustainability-conscious supply chains.
Revenue gravity sits with Water Treatment; Disinfection climbs the fastest.
End User:
Customer type determines whether procurement flows through integrated service contracts or transactional chemical purchasing.
- Municipalities:Public water utilities above 10 MGD capacity increasingly bundle generator maintenance with precursor supply under performance-based contracts that transfer operational risk to equipment vendors. United States utilities with strained in-house technical capacity drive this shift.
- Industrial Sector:Power generation and data center operators emerge as a distinct vertical where chlorine dioxide's biofilm penetration outperforms traditional non-oxidizing biocides in cooling tower systems.
- Food Processing:Major poultry processors in the United States adopt electrochemical units at replacement cycle points, compressing demand for conventional generator skids.
- Agriculture:Irrigation system sanitization and post-harvest treatment applications remain fragmented across small-scale operators.
Contract value concentrates with Municipalities; Industrial Sector gains share fastest.
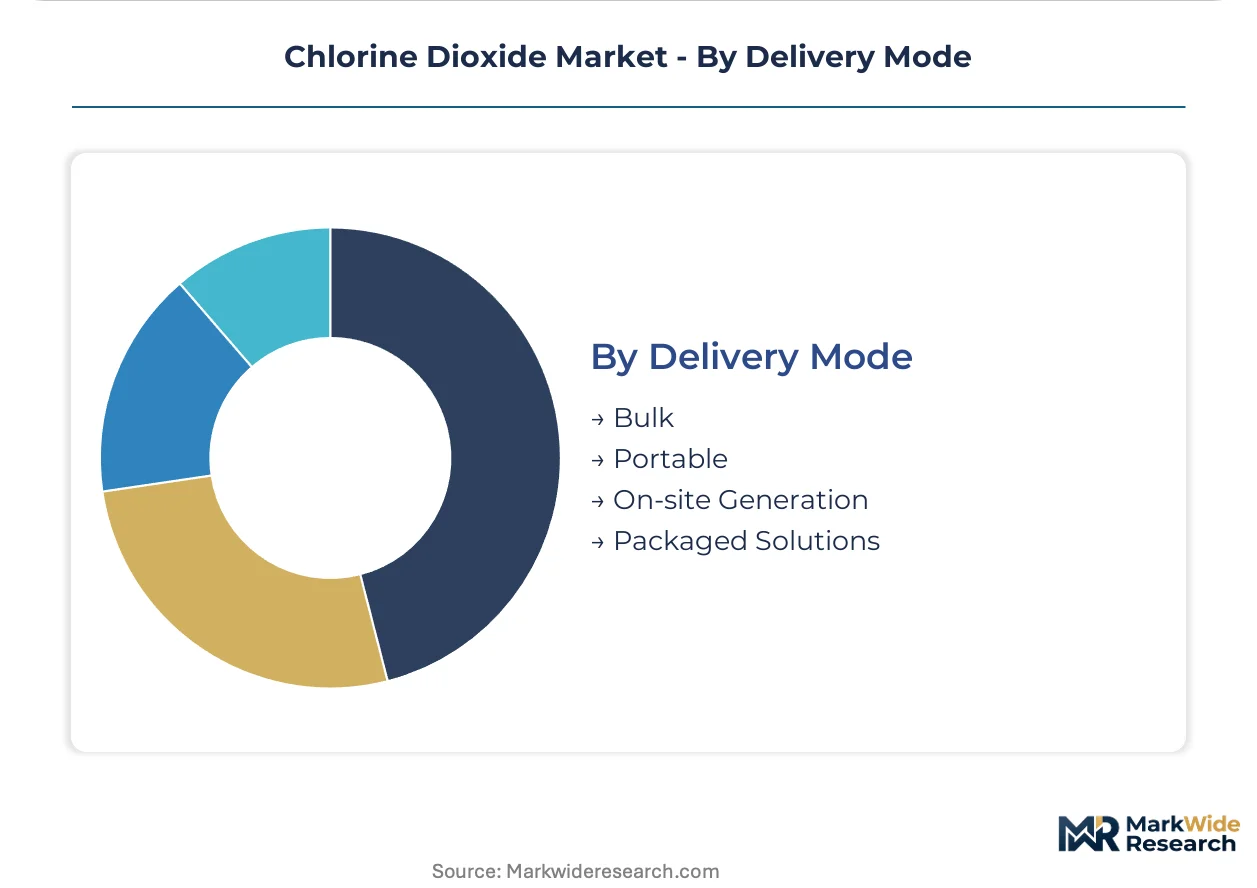
Delivery Mode:
Supply concentration in precursor production shapes which delivery formats sustain margin versus commodity pricing pressure.
- On-site Generation:Capital equipment relationships displace transactional chemical purchasing as utilities face binary choices between operational expenditure models and upfront deployment with lower lifetime precursor costs. Germany and the United States concentrate adoption.
- Bulk:Tanker-delivered stabilized solution retains position at mid-size utilities lacking capital maintenance capacity or SCADA integration expertise.
- Packaged Solutions:Containerized precursor-plus-generator bundles serve rapid-deployment scenarios and temporary treatment needs.
- Portable:Mobile generation units address emergency response and remote construction site requirements.
Equipment revenue concentrates in On-site Generation; Packaged Solutions expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate chlorine dioxide precursor manufacturing capacity under India's production-linked incentive schemes for specialty chemicals.
United States
Municipal utilities above 10 MGD capacity drive generator system procurement under EPA Stage 2 Disinfectants and Disinfection Byproducts Rules. OSHA permissible exposure limits govern worker safety protocols at precursor-handling facilities. The Ohio River Valley anchors chemical production clusters where sodium chlorite supply concentrates for Midwestern water treatment plants.
Germany
Bavarian and North Rhine-Westphalian utilities prioritize on-site generation systems under tightened hazardous materials routing restrictions for tanker transport. EU REACH authorization requirements shape equipment certification standards for chlorite precursor handling. The Rhine-Main industrial corridor hosts generator fabrication clusters serving municipal buyers across Central Europe.
India
Secondary cities lacking legacy chlorine infrastructure present greenfield adoption potential as the Central Pollution Control Board tightens microbial standards under the National Water Quality Framework. BIS certification requirements govern equipment material specifications for imported generator systems. The Delhi-Mumbai Industrial Corridor concentrates food processing disinfection demand from poultry and produce wash operations.
China
MIIT emission standards for industrial wastewater treatment elevate chlorine dioxide demand for effluent polishing applications. GB standards for drinking water quality drive municipal adoption in Yangtze River Delta megacities. The Shandong Peninsula hosts precursor chemical manufacturing clusters supplying on-site generation systems for coastal industrial zones.
Brazil
ANVISA sanitation regulations for food processing facilities expand chlorine dioxide substitution for peracetic acid in poultry wash systems. The country's national water quality framework elevates disinfection requirements for municipal utilities in São Paulo and Rio de Janeiro metropolitan regions. The São Paulo state industrial belt concentrates generator system demand from beverage and meat processing plants.
Chlorine Dioxide Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment and chemical supply channels. The market structure tilts toward consolidation in precursor production while fragmenting across generator system fabrication. Three archetypes dominate: integrated water technology conglomerates, regional equipment specialists, and chemical distribution intermediaries. Competitive moves concentrate on technology licensing partnerships and backward integration into precursor manufacturing.
Within the integrated technology tier, Evoqua Water Technologies LLC and Ecolab Inc. occupy positions spanning generator systems through service contracts. ProMinent GmbH exemplifies the European-format specialist archetype with compact skid architectures. CDG Environmental LLC anchors the safety-systems specialization vector through precursor-handling technology leadership.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Accepta LLC |
| Ecolab Inc. |
| BASF SE |
| Chemours Company |
| Evoqua Water Technologies LLC |
| CDG Environmental LLC |
| Sabre Technologies LLC |
| ProMinent GmbH |
| Others |
Supply Flow & Price Mechanics
Municipal utilities above 10 MGD capacity concentrate procurement leverage through integrated service contracts that bundle generator maintenance with precursor supply, compressing transactional chemical purchasing into long-term performance-based arrangements. This buyer consolidation elevates pricing power toward equipment vendors who absorb operational risk, while smaller facilities lacking capital budgets face commodity exposure in bulk solution markets.
Pricing Analysis
Short lead-time premiums command substantial markups for emergency generator deployments and spot precursor deliveries, while contract buyers with extended planning horizons capture volume discounts through annual offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates certified REACH-compliant European equipment from basic acid-activation skids and non-integrated chemical supply. Price differentiation rests on automation sophistication and precursor-handling safety certification tiers. Cost compression in standard-grade generator skids is intensifying because electrochemical technology displacement forces incumbent suppliers to defend share through equipment discounting. Mid-size municipal utilities exhibit highest price sensitivity as they lack capital maintenance capacity yet face identical regulatory compliance burdens.
Supply Chain Analysis
Regional distribution centers in the Ohio River Valley, Rhine-Main industrial corridor, and Shandong Peninsula anchor hub-and-spoke patterns for precursor chemical flow to municipal and industrial end users. Supply concentrates in the United States, Germany, and China for sodium chlorite production and generator system fabrication. Raw material dependencies draw from chlor-alkali chlorine feedstock, sodium chlorite synthesis capacity, and specialized corrosion-resistant alloys for reactor vessels. Single-source vulnerability in sodium chlorite supply exposes buyers to input price swings when producer maintenance outages occur. Distribution runs through integrated service contracts at large utilities, bulk tanker logistics for mid-size plants, and packaged container solutions for rapid-deployment scenarios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium chlorite production capacity constraints prop pricing resilience across the value chain, as limited qualified producers maintain tight control over precursor availability. This supply bottleneck sustains margin pools for integrated equipment-chemical vendors while pressuring pure-play distributors.
For Market Incumbents:Anchored positions in REACH-certified equipment and precursor-handling safety systems defend against electrochemical technology displacement and emerging membrane-electrode specialists. Backward integration into sodium chlorite production secures supply security for generator system deployments. Capacity addition in Bavaria and North Rhine-Westphalia reinforces geographic moats under Germany's stiffened hazardous materials routing restrictions.
For New Entrants and Emerging Players:Capture India's secondary cities lacking legacy chlorine infrastructure as greenfield adoption accelerates under tightening national water quality frameworks. The Delhi-Mumbai Industrial Corridor food processing belt offers the most penetrable vertical for electrochemical unit penetration. A go-to-market angle bundling generator lease with precursor supply undercuts capital-constrained municipal procurement committees.
For Investors and Strategic Acquirers:The window for entry favors electrochemical technology specialists with membrane-electrode platforms and established food processing customer relationships. Long-term viability hinges on regulatory tailwinds from EPA Stage 2 and EU Drinking Water Directive enforcement sustaining chlorine dioxide substitution against elemental chlorine. The signal to watch is state-level PFAS contamination mandates redirecting municipal capital toward advanced oxidation trains where chlorine dioxide serves as pretreatment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive sodium chlorite supply secures generator system deployment economics against input volatility. |
| Electrochemical Platform Transition | Membrane-electrode technology eliminates sulfuric acid handling for food processing safety compliance. |
| Integrated Service Contract Expansion | Performance-based bundling transfers operational risk from strained municipal technical capacity. |
| REACH Certification Pre-Validation | Component traceability documentation accelerates procurement evaluation for German and Dutch utilities. |
| India Market Entry Partnership | BIS certification pathways and PLI scheme alignment unlock secondary city greenfield adoption. |
Methodological Framework
EPA enforcement guidance documents, EU REACH authorization databases, and municipal utility procurement records formed the secondary backbone for regulatory and demand-side validation. Primary interviews with water treatment plant managers, chemical procurement leads at municipal utilities, generator system engineers, and precursor distribution channel partners combined with customs trade data and SEC equipment supplier filings. Bottom-up unit deployment tracking and top-down chemical consumption estimates triangulated market sizing across the analysis window.
Historical trendline analysis of municipal capital expenditure cycles and industrial disinfection substitution patterns anchored the projection framework. Segmentation dimensions modeled include product format, application vertical, end-user type, and delivery mode across the projection horizon. CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering. Chlorite precursor price volatility indices and UV-LED technology cost curves informed sensitivity boundaries.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrochemical technology adoption rates and sodium chlorite supply consolidation. Forecasts reflect documented assumptions regarding EPA enforcement intensity and EU F-Gas Regulation phase-down schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Continuously Sterilized Product Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
MMA Triazine Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Global Animal Disinfectants Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Global Fumigation Products Market