
 Natural Thickener Market | 2026-2036
Natural Thickener Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Thickener Market Insights
The natural thickener category is restructuring around a sharp split between premium clean-label hydrocolloids and commodity starch derivatives. Cargill leverages its North American grain supply base to dominate commodity guar and starch volumes. Ingredion differentiates through specialty tapioca and pulse-based solutions targeting premium beverage and dairy applications. CP Kelco anchors its position in microbial fermentation with gellan gum production at industrial scale.
Natural thickeners are polymeric substances—typically polysaccharides such as starches, galactomannans, or exopolysaccharides—that hydrate in aqueous systems to increase viscosity, stabilize emulsions, or control syneresis at concentrations generally below five percent by weight. Their primary commercial purpose spans texture engineering in processed foods, controlled-release matrices in pharmaceuticals, and rheology modification in personal care formulations. The gum segment leads value generation due to superior performance in low-pH and high-shear environments, while plant-based sources capture the fastest growth trajectory as formulators reject seaweed supply volatility. Powder form maintains volume dominance owing to shelf stability and freight efficiency, though liquid dispersions gain share in continuous-process beverage plants.
Regulatory frameworks including the FDA GRAS notification process, EFSA food additive evaluations under Regulation (EC) No 1333/2008, and EU REACH chemical registration requirements collectively shape ingredient approval timelines and reformulation costs. The EU F-Gas Regulation indirectly pressures manufacturers by restricting fluorinated processing aids used in some extraction technologies. Stakeholders must monitor evolving EFSA opinions on novel hydrocolloids and prepare for potential reclassification of established thickeners under tightening European clean-label standards.
Market Dynamics
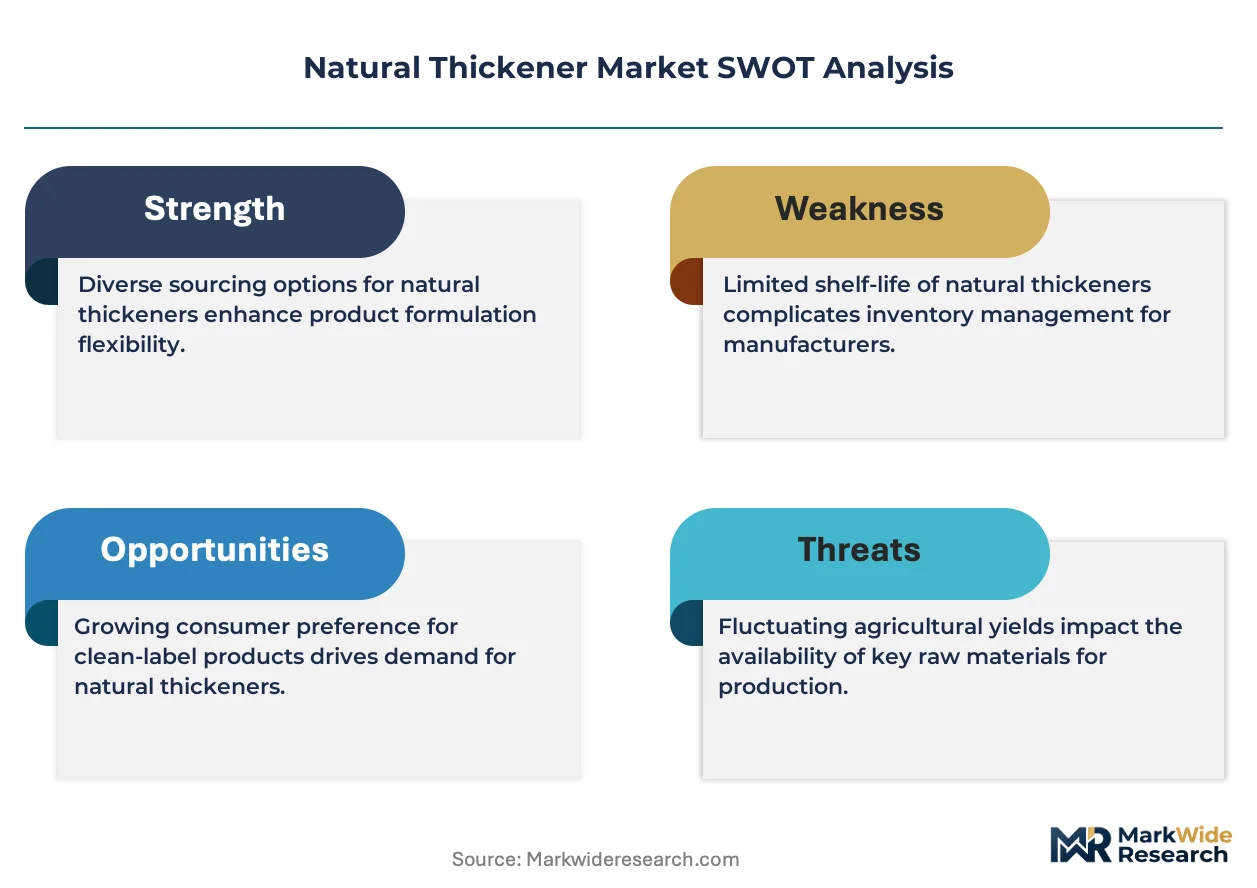
The EU Green Deal's clean-label mandates are forcing formulators to abandon synthetic stabilizers and rebuild supply chains around verified plant-based hydrocolloids with full traceability documentation.
Growth Catalysts
- EU Green Deal reformulation mandates:German and French food manufacturers face binding deadlines to eliminate synthetic additives, redirecting procurement toward guar, tapioca, and fermentation-derived gums with EFSA-approved status.
- Clean-label dairy and beverage expansion:Premium yogurt, oat milk, and functional drink brands specify hydrocolloids on front-of-pack ingredient lists as a competitive differentiator in retail and foodservice channels.
- F-Gas Regulation processing constraints:Restrictions on fluorinated extraction solvents are accelerating investment in enzymatic and mechanical separation technologies for gum and starch refinement.
Market Restraints
- Guar seed supply volatility:Rajasthan and Gujarat harvest fluctuations create 40-60% price swings that destabilize cost forecasting for hydrocolloid-dependent formulations.
- Seaweed sourcing concentration:Carrageenan and agar supply chains cluster in Indonesian and Philippine coastal regions exposed to climate-induced harvest disruption and export licensing delays.
- EFSA novel food approval timelines:Exopolysaccharides from non-traditional microbial strains face 18-24 month safety evaluation windows that block commercialization of next-generation fermentation products.
Strategic Opportunities
- Underpenetrated Mexican and Brazilian markets:Latin American processed food sectors remain reliant on modified starches, creating conversion potential for clean-label hydrocolloids as export standards tighten.
- Pharmaceutical controlled-release matrices:Oral dosage form manufacturers seek hydrocolloid-based tablet coatings and gel matrices to replace synthetic polymers in pediatric and geriatric drug delivery.
- EU F-Gas processing aid substitution:Equipment retrofits for non-fluorinated extraction create first-mover advantage for suppliers with validated enzymatic purification platforms.
Industry Challenges
- Fermentation scale-up engineering deficit:Microbial gum producers struggle to recruit bioprocess engineers capable of translating lab-scale gellan and xanthan yields to industrial bioreactor consistency.
- Dual certification burden:Suppliers targeting both food and pharmaceutical applications must maintain parallel FDA GRAS and USP-NF documentation systems with divergent audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Thickener Market |
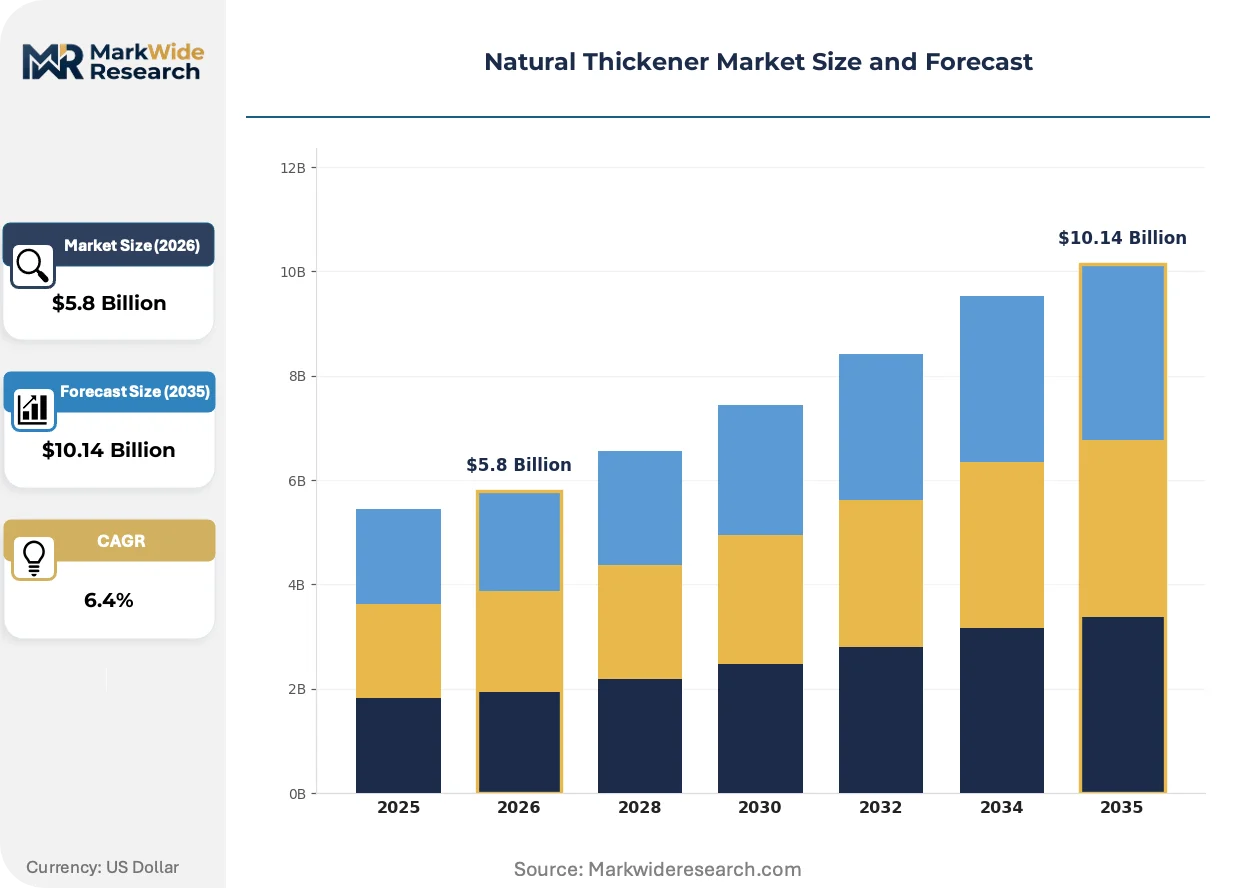
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Gum, Pectin, Agar Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Powder, Liquid, Granule, Flake Source: Plant-Based, Seaweed, Microbial, Animal-Based |
| Companies Covered | Cargill, Ingredion, Archer Daniels Midland, Tate & Lyle, CP Kelco, DuPont de Nemours, Kerry Group, Ashland, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Thickener Market Trends and Innovations
Enzymatic modification and precision fermentation are displacing conventional extraction methods, enabling hydrocolloid customization without the agricultural yield constraints that have historically governed supply security.
Precision fermentation of tailored polysaccharides is converging with CRISPR-engineered microbial strains to produce hydrocolloids with rheological properties previously achievable only through chemical derivatization. Pharmaceutical and personal care formulators in Switzerland and the Netherlands are piloting these bio-identical gums at commercial scale. This convergence is compressing the traditional agricultural processing value chain by decoupling output from seasonal crop cycles.
REACH registration requirements under ECHA are tightening disclosure obligations for hydrocolloid impurities and processing aids, extending compliance timelines for non-EU suppliers. The regulation forces importers to maintain analytical laboratories capable of detecting residual solvents at parts-per-billion thresholds. Specialty beverage and infant nutrition segments in Germany and France are responding by qualifying suppliers with pre-validated REACH dossiers and third-party audit certifications.
Direct supplier relationships are replacing distributor intermediation as large food manufacturers build captive technical service teams for hydrocolloid application development. Nestlé and Unilever procurement functions in Vevey and Rotterdam now specify on-site formulation support as a contract requirement, bypassing traditional ingredient distribution channels. This disintermediation is most visible in Northern European dairy and plant-based beverage operations where continuous-process lines demand real-time viscosity troubleshooting.
Natural Thickener Market Segmentation
Natural thickener procurement decisions hinge on functional performance thresholds, regulatory compliance burdens, and supply security metrics that vary sharply across product categories. Formulators weigh hydration kinetics, shear stability, and label positioning differently depending on end-use specifications and regional clean-label mandates.
Product Type:
Capital intensity peaks in microbial fermentation infrastructure, where bioreactor networks and sterile processing lines demand the heaviest upfront investment compared to agricultural extraction or physical modification plants.
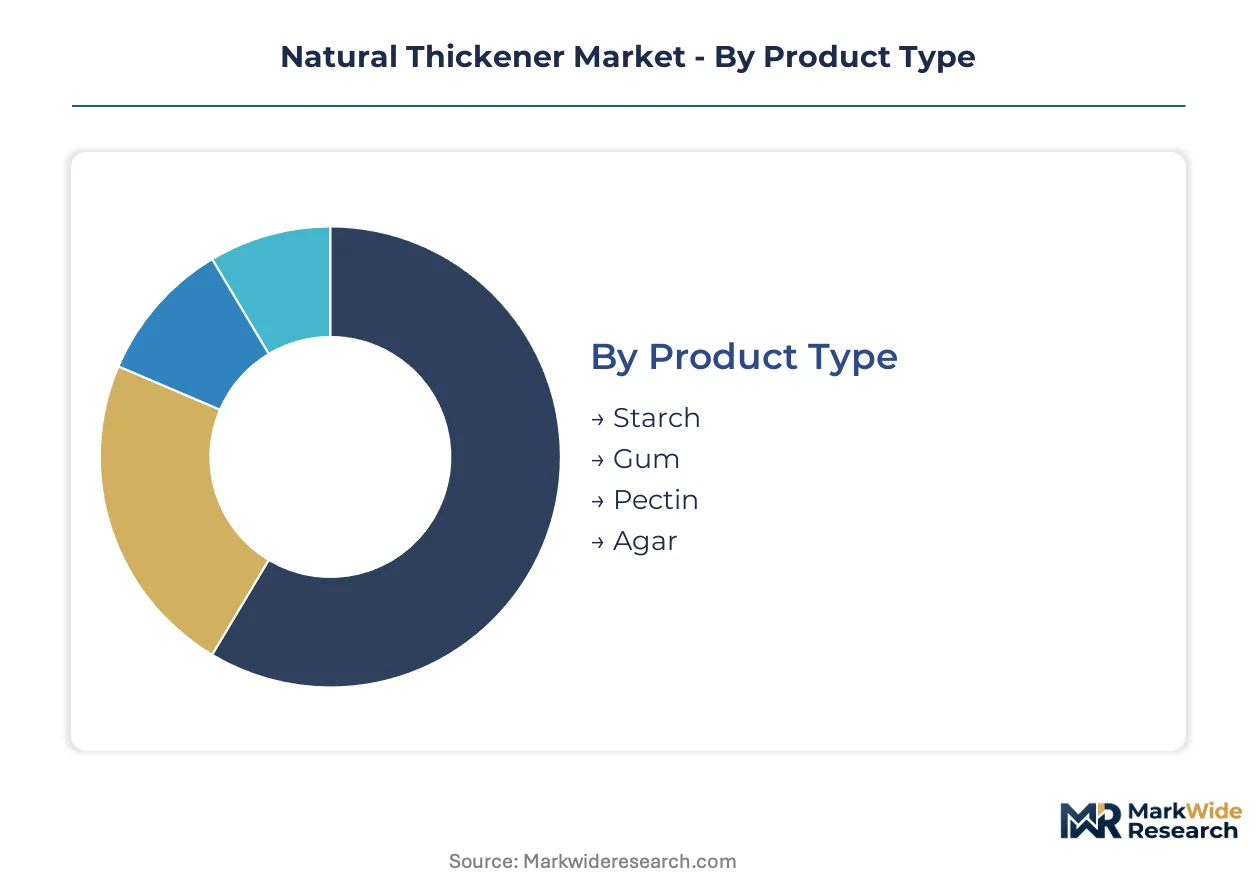
- Starch:Modified and native starches from corn, tapioca, and potato sources provide cost-efficient viscosity building in high-volume sauce and bakery applications. European dairy processors specify waxy maize variants for freeze-thaw stability in premium frozen desserts, though EFSA scrutiny of chemical modification residues is tightening qualification requirements.
- Gum:Galactomannans and microbial exopolysaccharides deliver superior performance in low-pH beverages and high-shear dairy systems where starch fails. German oat milk formulators specify guar and locust bean gums for clean-label positioning under EU Green Deal additive reduction timelines.
- Pectin:Citrus and apple-derived high-methoxyl grades dominate conventional jam gelling; low-methoxyl variants enable reduced-sugar positioning.
- Agar:Seaweed-extracted polysaccharide serves specialized microbiological media and premium confectionery with rigid gel requirements.
Most installed capacity flows through Starch. Expansion is steepest in Gum.
Application:
Margin structures diverge most dramatically between commodity food volumes and pharmaceutical qualification premiums, where USP-NF certification multiplies effective pricing power.
- Food & Beverage:Texture engineering in processed sauces, dairy alternatives, and functional beverages consumes the majority of hydrocolloid volumes. French and German clean-label mandates are accelerating substitution of modified starches with guar and tapioca-derived options in retail-ready soups and plant-based yogurts.
- Pharmaceuticals:Controlled-release tablet matrices, ophthalmic viscosifiers, and suspension stabilizers demand batch-to-batch consistency with full analytical documentation. Swiss and Dutch formulators pilot precision-fermented hydrocolloids to replace synthetic polymers in pediatric dosage development.
- Cosmetics:Rheology modification in creams and serums favors transparent, non-tacky gum solutions over starch opacity.
- Nutraceuticals:Gelling and encapsulation for soft-gel supplements and functional gummies drives specialized pectin and starch derivative demand.
Volume concentration sits in Food & Beverage. Value expansion is most pronounced in Pharmaceuticals.
Form:
Freight economics and handling infrastructure shape regional form preferences, with powder dominating intercontinental trade and liquid gaining share in continuous-process manufacturing clusters.
- Powder:Spray-dried and roller-dried particulates offer shelf stability and container efficiency for global distribution. German and Dutch beverage compounders maintain substantial powder inventories to buffer against guar seed harvest volatility from Rajasthan supply bases.
- Liquid:Pre-hydrated dispersions eliminate dust exposure and reduce batch-to-batch hydration variance in high-throughput lines. French dairy processors specify liquid pectin for continuous-process yogurt fruit preparation systems.
- Granule:Intermediate particle size reduces clumping in high-solids bakery premixes without full powder dispersion requirements.
- Flake:Agar and carrageenan flakes serve specialized laboratory and artisan food preparation with controlled dissolution rates.
Supply chain throughput centers on Powder. Share gains are strongest in Liquid.
Source:
Agricultural yield uncertainty versus bioprocess engineering reliability defines the strategic trade-off between plant-based and microbial supply strategies.
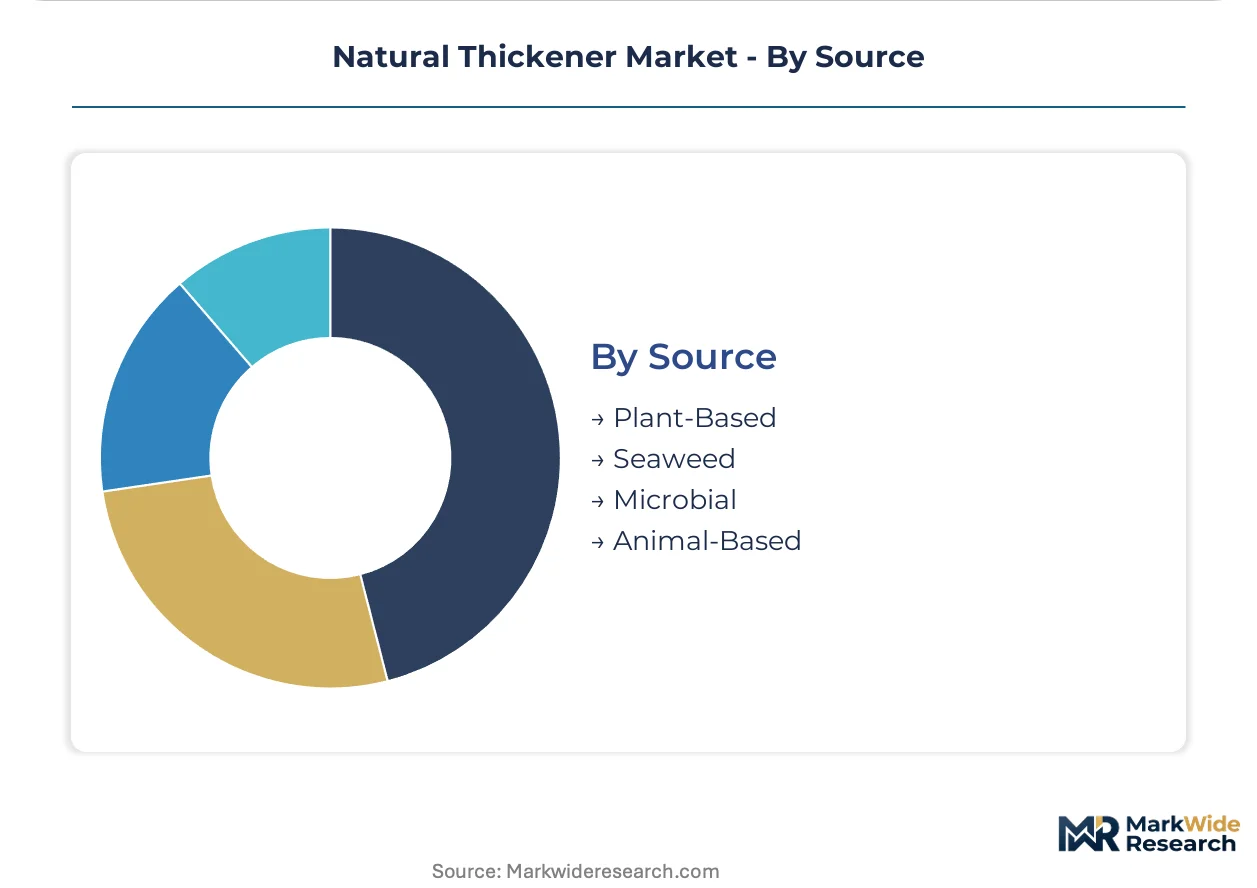
- Plant-Based:Guar, tapioca, locust bean, and starch crops anchor conventional supply with established farmer networks and mechanical processing infrastructure. German formulators are qualifying Indian guar suppliers with full traceability documentation to satisfy EU Green Deal due diligence requirements.
- Microbial:Fermentation-derived xanthan, gellan, and pullulan offer supply security decoupled from climate and harvest cycles. Dutch and Swiss precision fermentation ventures are scaling tailored polysaccharide production for pharmaceutical and personal care qualification.
- Seaweed:Carrageenan and agar extraction concentrates in Indonesian and Philippine coastal zones exposed to climate disruption and export licensing volatility.
- Animal-Based:Gelatin and related collagen derivatives serve specialized pharmaceutical capsule and confectionery applications with restricted use in clean-label food positioning.
Current procurement volume concentrates in Plant-Based. Commercial momentum is accelerating fastest in Microbial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in regulatory pressure intensity, with EU Green Deal timelines forcing faster reformulation cycles than FDA GRAS notification requirements permit. Clean-label procurement in Western Europe concentrates in dairy and beverage clusters, while North American demand spreads across broader processed food categories with less centralized mandate structure.
Germany
Oat milk and plant-based yogurt formulators in Bavaria and North Rhine-Westphalia specify guar and locust bean gums to satisfy EU Green Deal additive reduction deadlines. EFSA evaluations under Regulation (EC) No 1333/2008 govern novel hydrocolloid approvals. The Hamburg-Rotterdam corridor anchors distribution infrastructure for Indian guar imports with full traceability documentation.
United States
Clean-label beverage brands in California and the Pacific Northwest drive specialty tapioca and pulse-based thickener specification. FDA GRAS notification timelines allow faster ingredient adoption than European parallel processes. Chicago and Minneapolis-St. Paul host formulation laboratories where Cargill and Ingredion maintain technical service teams for dairy and sauce applications.
France
Premium jam and confectionery producers in Île-de-France and Auvergne-Rhône-Alpes specify high-methoxyl pectin for reduced-sugar positioning. ANSM and DGCCRF enforcement of EU clean-label standards pressures elimination of modified starches. Lyon-based dairy compounders pilot liquid pectin dispersions for continuous-process yogurt fruit preparation systems.
India
Rajasthan and Gujarat guar seed processing clusters supply global hydrocolloid demand despite harvest volatility driving price swings. FSSAI food additive regulations and DGFT export licensing shape outbound shipment timing. Ahmedabad and Jodhpur processing facilities face mounting European buyer demands for farm-to-factory traceability documentation under EU Green Deal due diligence rules.
Netherlands
Precision fermentation ventures in Rotterdam and Eindhoven scale microbial gum production for pharmaceutical and personal care qualification. ECHA REACH registration requirements tighten impurity disclosure obligations for hydrocolloid imports. Wageningen University partnerships anchor bioprocess engineering talent pipelines addressing industry-wide scale-up deficits.
Natural Thickener Market Competitive Landscape
Top-tier vendors anchor commodity starch and guar volumes through captive agricultural supply bases, while mid-tier specialists capture premium positioning through fermentation-derived and specialty plant-based solutions. The vendor base stratifies across three archetypes: grain processors with North American supply dominance, hydrocolloid specialists with microbial fermentation platforms, and diversified ingredient houses with cross-sector pharmaceutical qualification capabilities. M&A activity concentrates on microbial fermentation capacity acquisitions, while strategic partnerships link ingredient suppliers with beverage brands requiring on-site technical service.
Within the fermentation-specialist tier, CP Kelco represents industrial-scale gellan gum production through microbial platforms. Cargill and Ingredion exemplify divergent commodity-versus-premium positioning, with the former leveraging grain supply integration and the latter targeting specialty tapioca and pulse-based applications. These three anchors illustrate the competitive tension between agricultural extraction reliability and bioprocess engineering customization that defines procurement decision frameworks across European and North American formulator accounts.
| Leading Market Players |
|---|
| Cargill |
| Ingredion |
| Archer Daniels Midland |
| Tate & Lyle |
| CP Kelco |
| DuPont de Nemours |
| Kerry Group |
| Ashland |
| ADM |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal procurement mandates for verified plant-based hydrocolloids with full traceability documentation are forcing suppliers to absorb compliance costs and restructure sourcing networks, compressing margins at the commodity tier while creating pricing power for certified premium grades.
Pricing Analysis
Capacity additions in precision fermentation facilities across the Netherlands and Switzerland are reshaping price floors for microbial gums. Three-tier pricing structure across pharmaceutical-grade, food-grade certified, and commodity unmodified tiers reflects divergence in USP-NF documentation burden and EFSA approval status. Pricing pressure stems from guar seed harvest volatility in Rajasthan, where 40-60% price swings destabilize cost forecasting. Contract manufacturers in high-volume sauce applications exhibit highest price sensitivity; pharmaceutical formulators in pediatric dosage development show lowest sensitivity due to batch consistency requirements.
Supply Chain Analysis
Return flows of expired hydrocolloid inventories and packaging materials from European pharmaceutical compounders feed into specialized refurbishment channels for non-food reprocessing. Raw material concentration centers on Indian guar seed clusters, Indonesian seaweed coastal zones, and North American corn and tapioca processing hubs. Supply chains draw from agricultural harvest cycles, fermentation bioreactor networks, and enzymatic extraction platforms. Single-source vulnerability concentrates in Rajasthan guar processing and Philippine carrageenan extraction exposed to climate disruption. Distribution runs through direct supplier relationships with captive technical service teams replacing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural thickener market functions as a stable compounder anchored by structural clean-label mandates that perpetually refresh reformulation demand across food, pharmaceutical, and personal care sectors.
For Market Incumbents: Cement supply security through backward integration into Indian guar seed processing with farm-to-factory traceability documentation that satisfies EU Green Deal due diligence requirements. Expand fermentation capacity in Rotterdam and Eindhoven biotech corridors to capture pharmaceutical qualification premiums. Synthetic polymer substitution threats in pediatric drug delivery and precision-fermentation entrants in tailored polysaccharides demand defensive positioning through USP-NF certification maintenance and CRISPR-engineered strain development partnerships. For New Entrants and Emerging Players: Precision fermentation platforms for customized rheology profiles offer the most penetrable wedge into Swiss and Dutch pharmaceutical formulation accounts seeking bio-identical gum alternatives. Target Brazilian and Mexican processed food sectors where modified starch reliance creates conversion potential as export standards tighten. Lead with enzymatic purification technology that bypasses F-Gas Regulation constraints on fluorinated extraction solvents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale microbial fermentation specialists possessing validated pharmaceutical dossiers and scalable bioreactor infrastructure. The five-to-ten-year viability window favors suppliers decoupled from agricultural yield volatility through bioprocess engineering capabilities. Target acquisition archetype: precision fermentation ventures with ECHA REACH pre-validated dossiers and Wageningen University talent pipelines. Monitor EFSA novel food approval timelines for exopolysaccharides as inflection indicator for next-generation product commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Seed Processing | Captive supply from Rajasthan farming networks satisfies EU Green Deal traceability mandates. |
| Precision Fermentation Scale-Up | Rotterdam bioreactor capacity addresses pharmaceutical demand for batch-consistent microbial gums. |
| Enzymatic Purification Platform Deployment | Non-fluorinated extraction technology circumvents EU F-Gas Regulation processing constraints. |
| USP-NF Certification Investment | Dual food-pharmaceutical documentation opens pediatric and geriatric drug delivery applications. |
| Direct Technical Service Team Expansion | On-site formulation support at Vevey and Rotterdam bypasses distributor intermediation. |
Research Methodology
Multiple input streams — regulatory filings, trade customs data, and industry stakeholder consultations — were reconciled through bottom-up and top-down triangulation. Primary interviews engaged hydrocolloid procurement managers at dairy and beverage manufacturers, plant managers at Indian guar processing facilities, regulatory affairs leads navigating EFSA novel food approvals, and pharmaceutical formulation scientists developing controlled-release matrices. Secondary validation drew from ECHA REACH registration databases, DGFT export licensing records, FSSAI food additive regulations, and SEC filings from publicly traded ingredient suppliers.
Historical volume trajectories were cross-referenced against panel input from procurement executives to anchor projection parameters across the analysis window. Segmentation dimensions modeled include product type, application category, form specification, and source origin. CAGRs were derived from elasticity-adjusted demand curves incorporating clean-label substitution rates and pharmaceutical qualification pipeline velocities. Industry-specific forecast inputs encompassed guar seed harvest yield variance bands and precision fermentation scale-up engineering timelines.
The model holds under stable EU Green Deal implementation schedules and consistent EFSA evaluation timelines; deviation in regulatory acceleration or novel hydrocolloid reclassification would shift volume trajectories. Forecasts embed assumptions regarding continued pharmaceutical polymer substitution demand and sustained clean-label procurement pressure in Northern European dairy processing. Practitioners should monitor EFSA opinions on established thickener reclassification and Rajasthan monsoon patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Trimellitic Anhydride Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Global Butyric Acid Market