
 Global Polyvinyl Alcohol Fiber Market | 2026-2036
Global Polyvinyl Alcohol Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyvinyl Alcohol Fiber Market Intelligence
A focus on high strength fiber specifications for industrial applications is rotating the market toward higher-value product segments. KURARAY CO., LTD. leverages its extensive R&D to maintain a leading position in specialized grades. Sinopec Sichuan Vinylon anchors a significant portion of the production capacity in Asia. Meanwhile, Mitsubishi Chemical Corporation competes through its diversified polymer portfolio and global supply chain.
Polyvinyl alcohol fiber is a synthetic polymer fiber derived from polyvinyl alcohol through a wet spinning process. It exhibits high tensile strength, excellent alkali resistance, and strong adhesion properties, making it an effective reinforcement agent. Within product types, high strength fiber commands premium pricing for demanding applications like construction materials. Staple fiber formats see extensive use in the production of nonwoven fabrics and specialty papers.
Product formulation and market access are governed by chemical safety regulations like the EU's REACH framework. In construction, compliance with standards such as CE marking in Europe and national GB standards in China is mandatory. Future development will require balancing the performance attributes of PVA fibers with increasing regulatory scrutiny on polymer lifecycle and disposal.
Market Dynamics
The polyvinyl alcohol fiber market is shaped by a fundamental bifurcation between high-value, high-strength grades for industrial reinforcement and advanced water-soluble grades for specialty nonwovens. This division is amplified by significant production concentration within China, influencing global supply dynamics.
Growth Catalysts
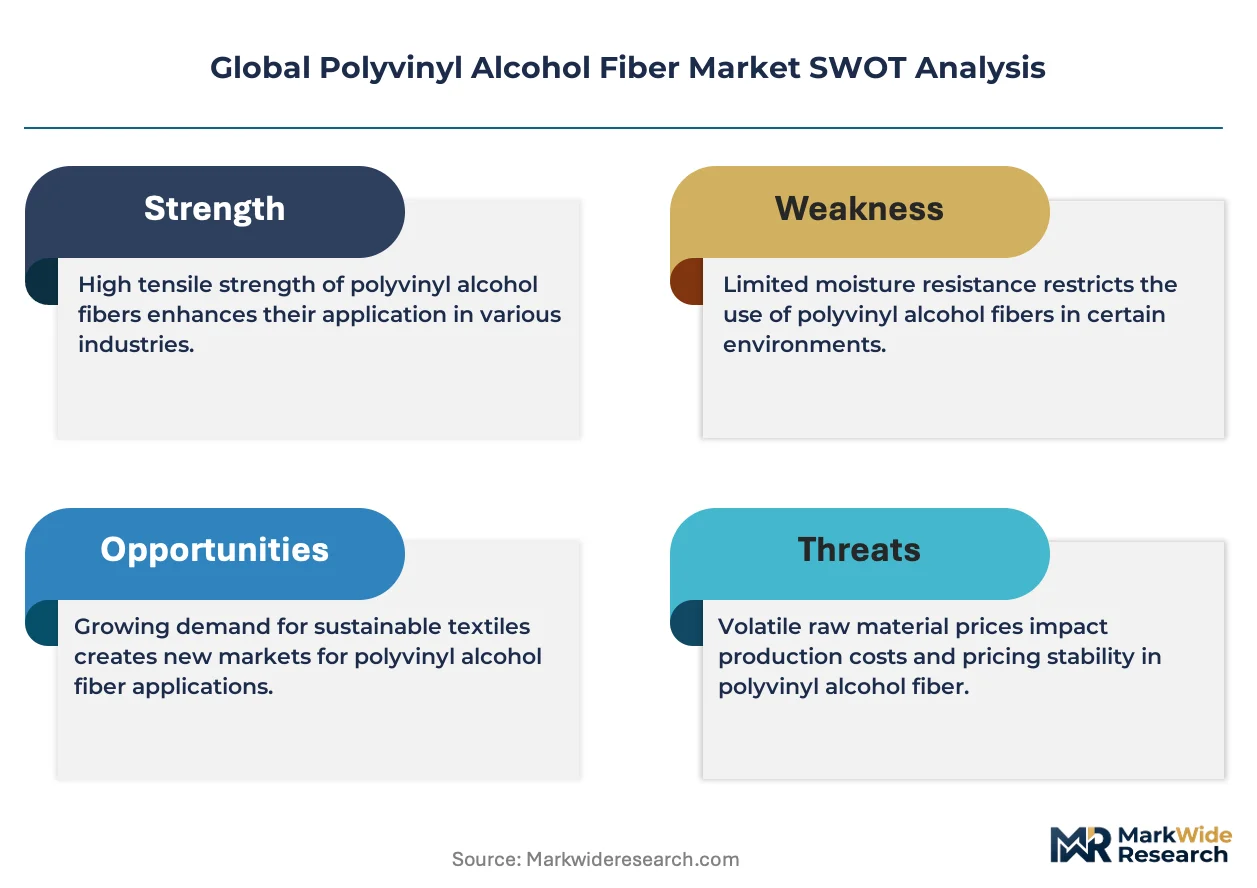
- Infrastructure Modernization:Government-led infrastructure projects in Asia and the Middle East drive demand for PVA fiber as a non-corrosive reinforcement agent in concrete, replacing traditional steel and asbestos in many applications.
- Water-Soluble Product Innovation:The development of precisely formulated water-soluble fibers expands use in consumer goods like laundry pods, as well as in agricultural films and flushable nonwoven hygiene products.
- Asbestos Replacement Mandates:Regulatory bans on asbestos in construction materials, enforced across Europe, North America, and Australia, create a direct substitution pathway for high-strength PVA fibers in cementitious products like roofing and siding.
Market Restraints
- Raw Material Price Volatility:The market's cost structure is directly tied to the price of vinyl acetate monomer (VAM), a petrochemical derivative subject to fluctuations in global oil and natural gas markets.
- Energy-Intensive Manufacturing:The wet spinning process required for PVA fiber production consumes significant amounts of electricity and heat, creating a cost disadvantage in regions with high energy prices.
- Substitution from Polypropylene:In less demanding, cost-sensitive applications like secondary concrete reinforcement, lower-priced polypropylene (PP) fibers present a persistent substitution threat, capping price ceilings for standard PVA grades.
Strategic Opportunities
- Biomedical Applications:Developing high-purity, biocompatible PVA fibers opens new avenues in medical devices, including absorbable surgical sutures, wound dressings, and scaffolds for tissue engineering.
- Advanced Filtration Media:Engineering fibers with tailored surface properties and deniers creates opportunities in high-performance liquid and air filtration systems for the automotive, industrial, and cleanroom sectors.
- Geotextile Development:Promoting PVA-based geotextiles for soil stabilization, erosion control, and agricultural applications represents an underpenetrated market, especially in regions facing land degradation and water scarcity.
Industry Challenges
- End-of-Life Management:Establishing scalable and economically viable recycling processes for PVA-reinforced composites, particularly from construction and demolition waste, remains a significant logistical and technical challenge.
- Technical Control of Solubility:Achieving precise and repeatable dissolution characteristics for advanced water-soluble grades requires sophisticated control over polymerization and hydrolysis, posing a high technical barrier for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyvinyl Alcohol Fiber Market |
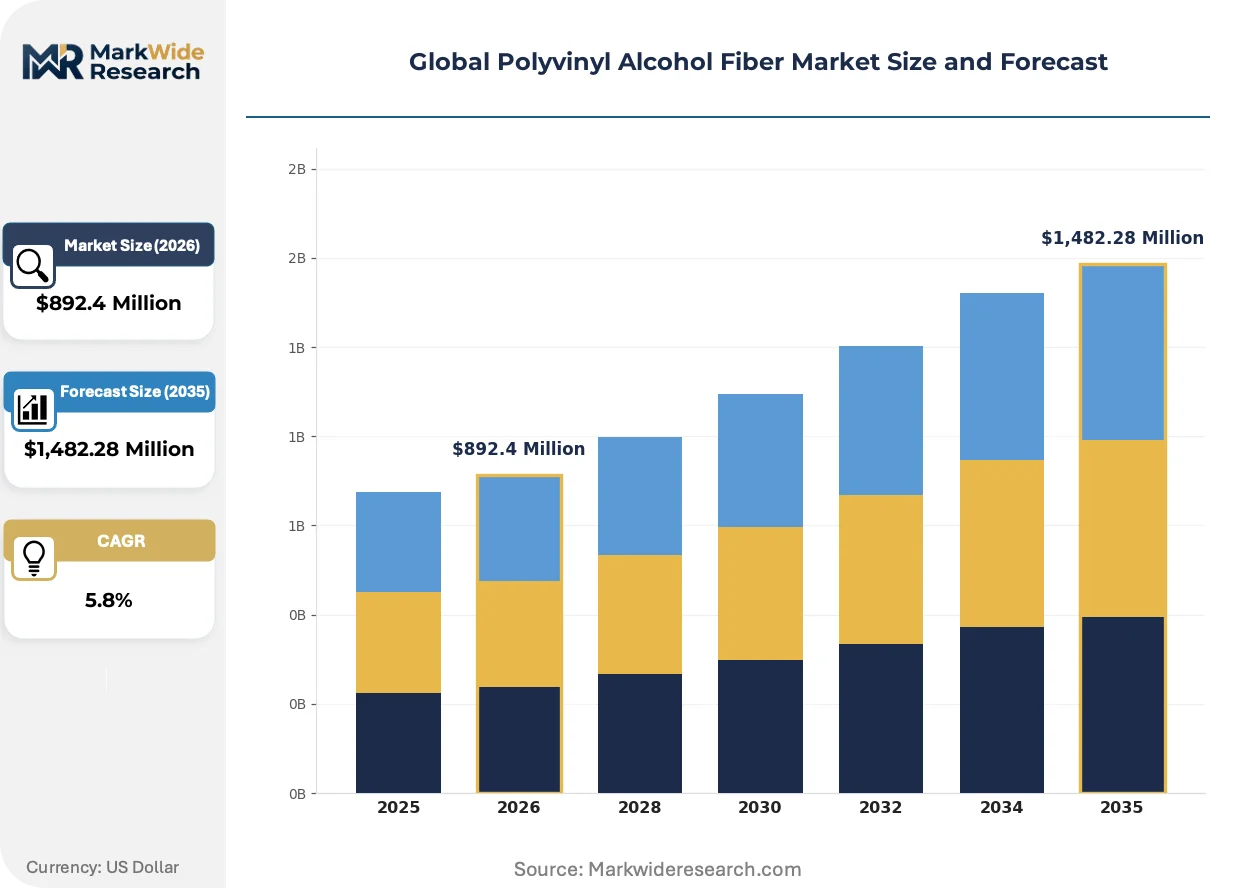
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Strength Fiber, Standard Fiber, Microfiber, Staple Fiber, Filament Fiber Application: Textile Reinforcement, Paper Coating, Nonwoven Fabrics, Adhesives, Construction Materials, Packaging End Use Industry: Automotive OEMs, Aerospace Manufacturing, Civil Engineering, Consumer Electronics, Marine Equipment Form: Powder, Granules, Flakes, Film, Sheet |
| Companies Covered | KURARAY CO., LTD., Mitsubishi Chemical Corporation, Eastman Chemical Company, UNITIKA LTD., Sinopec Sichuan Vinylon, Hunan Xiangwei Co., Ltd., EI du Pont de Nemours and Company, Nycon Corporation, Inner Mongolia Shuangxin Environment-Friendly Material Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyvinyl Alcohol Fiber Market Strategic Shifts & Innovations
Material science advancements are pushing polyvinyl alcohol fibers into new performance tiers, enabling their use in applications from critical infrastructure reinforcement to dissolving consumer products. This evolution creates distinct value streams for specialized versus commodity grades across the market.
Advanced high-modulus PVA fibers deliver exceptional tensile strength and alkali resistance for demanding environments. Adopted primarily by the civil engineering sector, these fibers are integral to high-performance concrete formulations for bridges and tunnels. This technology is displacing traditional steel rebar and asbestos in many cementitious applications due to superior corrosion resistance and reduced weight.
Heightened regulatory scrutiny, including China's GB standards for construction materials and the EU's REACH framework, is formalizing performance and safety requirements. This forces producers to invest in extensive testing and documentation, creating a compliance barrier for non-conforming products. The high-strength fiber segment targeting infrastructure projects is most affected, with certification becoming a prerequisite for market access in these key geographies.
Specification-driven purchasing is altering procurement patterns, particularly in technical textiles and specialty papers. The practice of buying generic staple fiber is yielding to demand for engineered fibers with specific attributes like cut length, denier, and solubility rate. This shift is most visible in the nonwoven fabric sectors of Japan and Germany, where final product functionality dictates raw material selection.
Global Polyvinyl Alcohol Fiber Market Segmentation
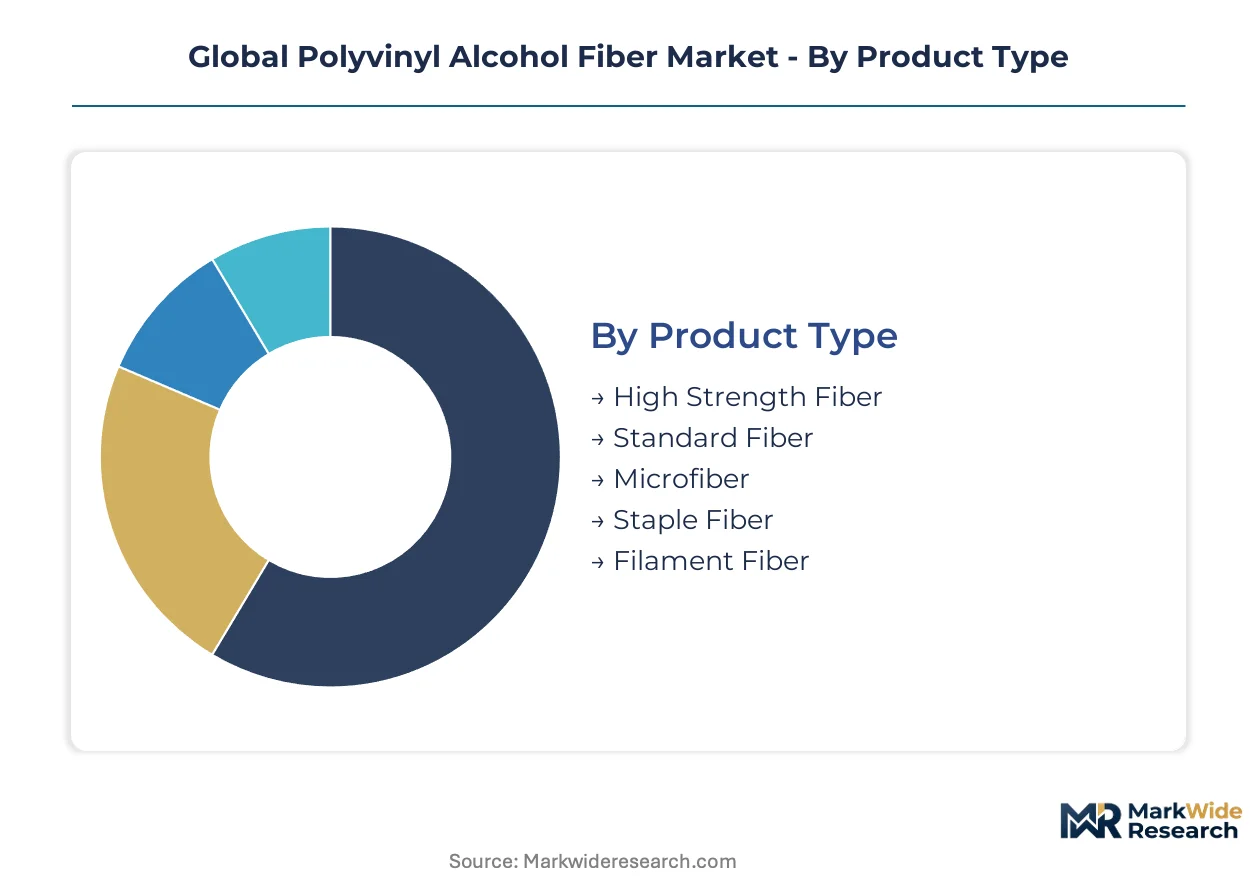
The polyvinyl alcohol fiber market differentiates across various dimensions, reflecting the diverse performance requirements and end-use applications for this synthetic material. Understanding these segments is crucial for producers to target specific value chains and for regulatory bodies to establish relevant compliance frameworks.
Product Type:
Regulatory differentiation significantly influences product type development and market access for PVA fibers. Compliance with standards like the EU's REACH framework and China's GB standards dictates material specifications for high-strength and specialized grades.
- High Strength Fiber:This fiber type exhibits superior tensile strength and alkali resistance, making it ideal for demanding industrial applications. Demand concentrates in civil engineering projects across China and Europe, driven by infrastructure modernization and asbestos replacement mandates.
- Staple Fiber:Composed of short-cut fibers, this format is extensively used in nonwoven fabrics and specialty papers, offering versatility in texture and absorbency. Japan and Germany demonstrate strong demand for engineered staple fibers in hygiene products and filtration media.
- Standard Fiber:These general-purpose fibers serve a broad range of cost-sensitive applications requiring moderate strength and chemical resistance.
- Microfiber:Characterized by extremely fine denier, microfibers find use in advanced filtration and high-performance textiles where surface area and softness are critical.
- Filament Fiber:Continuous strands of PVA fiber are utilized in specialized textiles and ropes, offering high strength-to-weight ratios for specific industrial uses.
Established volume favors Standard Fiber; emerging adoption favors Microfiber.
Application:
Application-specific performance requirements drive the demand for polyvinyl alcohol fibers, with each sector valuing distinct material attributes. The market's growth trajectory is heavily influenced by the expansion of these key application areas.
- Construction Materials:PVA fibers reinforce concrete, mortars, and cementitious products, enhancing durability and crack resistance, particularly in infrastructure projects. Civil engineering projects in Asia and the Middle East are significant consumers due to infrastructure modernization.
- Nonwoven Fabrics:Used in hygiene products, medical textiles, and wipes, PVA fibers contribute to strength, absorbency, and water dispersibility in nonwoven structures. Innovation in water-soluble grades for flushable nonwovens drives demand in Europe and North America.
- Textile Reinforcement:PVA fibers strengthen various textile products, including industrial fabrics and apparel, by improving tear resistance and dimensional stability.
- Paper Coating:These fibers enhance the strength, printability, and surface finish of specialty papers and board products.
- Adhesives:PVA fibers can act as a binder or reinforcement in certain adhesive formulations, improving bond strength and flexibility.
- Packaging:In packaging, PVA fibers contribute to the strength and biodegradability of certain film and paper-based solutions.
Demand concentration is highest in Construction Materials; Nonwoven Fabrics exhibits a steep expansion trajectory.
End Use Industry:
The end-use industries dictate the technical specifications and volume requirements for PVA fibers, creating distinct market segments based on industry-specific needs and regulatory landscapes.
- Civil Engineering:This sector utilizes high-strength PVA fibers for concrete reinforcement in bridges, tunnels, and buildings, driven by infrastructure development. Government-led projects in China and India significantly influence consumption patterns.
- Automotive OEMs:PVA fibers find application in automotive composites, interior components, and filtration systems, contributing to lighter weight and improved performance. European automotive manufacturers prioritize these materials for sustainability and performance.
- Aerospace Manufacturing:High-performance PVA fibers are explored for lightweight composites and specialized components in the aerospace industry, where material properties are critical.
- Consumer Electronics:PVA fibers can be incorporated into components requiring specific structural or functional properties within electronic devices.
- Marine Equipment:In marine applications, PVA fibers are used in ropes, nets, and composites, valued for their strength and resistance to environmental factors.
Volume consumption is dominated by Civil Engineering; Automotive OEMs shows expanding demand.
Form:
The physical form of polyvinyl alcohol fiber dictates its ease of processing and suitability for various manufacturing techniques, influencing procurement patterns across industries.
- Powder:PVA in powder form is primarily used as an additive in cementitious materials, coatings, and adhesives for easy dispersion and mixing. Construction material manufacturers in Southeast Asia frequently procure PVA powder.
- Film:PVA films are utilized in packaging, agricultural films, and laundry pods due to their water-solubility and barrier properties. Consumer goods manufacturers in North America drive demand for specialized PVA films.
- Granules:Granular PVA is often used in extrusion and molding processes for manufacturing specific components or products.
- Flakes:PVA flakes serve as a raw material for various industrial applications, including the production of adhesives and specialty chemicals.
- Sheet:PVA in sheet form finds specialized applications where a solid, water-soluble or high-strength sheet material is required.
Processing convenience favors Powder; functional versatility drives demand for Film.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of polyvinyl alcohol fiber production within China significantly influences global supply dynamics. This geographic focus impacts material availability and pricing across international markets. Key demand centers are also emerging or solidifying their positions through specific application needs and regulatory frameworks.
China
Demand for high-strength PVA fiber in China is driven by extensive civil engineering projects and infrastructure modernization. National GB standards mandate specific performance attributes for construction materials. The Yangtze River Delta region hosts significant production capacity and material science research for advanced PVA fiber applications.
Japan
Japan demonstrates strong demand for engineered staple fibers in nonwoven hygiene products and filtration media. METI promotes material innovation and sustainable manufacturing practices within the chemical sector. Osaka and Tokyo remain key hubs for specialty chemical production and advanced textile development.
Germany
Germany's automotive OEMs and advanced manufacturing sectors generate demand for PVA fibers in composites and technical textiles. The EU's REACH framework and CE marking ensure compliance for imported and domestically produced materials. The Rhine-Ruhr area focuses on chemical production and high-performance material development for industrial applications.
United States
Infrastructure projects and the expanding nonwoven fabrics sector drive PVA fiber consumption in the United States. EPA regulations influence material safety and environmental compliance for polymer production and use. The Gulf Coast region supports petrochemical derivatives, providing raw materials for synthetic fiber manufacturing.
India
India's rapid urbanization and infrastructure development fuel demand for PVA fibers in concrete reinforcement. The PLI scheme encourages domestic manufacturing and innovation in specialty chemicals. Gujarat and Maharashtra are emerging as critical centers for chemical processing and construction material production.
Global Polyvinyl Alcohol Fiber Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the polyvinyl alcohol fiber market. The market exhibits a tiered structure, with established global chemical giants competing with specialized fiber producers and large-scale Asian manufacturers. Strategic archetypes include innovation-driven specialists, volume-focused producers, and diversified polymer conglomerates. Companies pursue capacity expansion and portfolio diversification to secure market share and enhance their competitive positioning.
Among the innovation-driven specialists, KURARAY CO., LTD. represents a global leader leveraging extensive R&D for specialized grades and high-value applications. Mitsubishi Chemical Corporation, a diversified polymer conglomerate, competes through its broad polymer portfolio and global supply chain, serving a wide range of industrial clients. Sinopec Sichuan Vinylon anchors a significant portion of the production capacity in Asia, exemplifying the volume-focused producers who serve large-scale construction and industrial markets. These companies collectively illustrate the varied approaches to market penetration and value creation, from high-performance materials to commodity volumes, across the polyvinyl alcohol fiber industry.
| Leading Market Players |
|---|
| KURARAY CO., LTD. |
| Mitsubishi Chemical Corporation |
| Eastman Chemical Company |
| UNITIKA LTD. |
| Sinopec Sichuan Vinylon |
| Hunan Xiangwei Co., Ltd. |
| EI du Pont de Nemours and Company |
| Nycon Corporation |
| Inner Mongolia Shuangxin Environment-Friendly Material Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized PVA fibers reflect a concentrated production base in China, granting producers significant pricing leverage for high-value grades.
Pricing Analysis
China's GB standards dictate the pricing tier structure for high-strength PVA fibers, particularly for construction materials. Contract-based long-term offtake agreements secure volumes for high-strength grades, while standard fibers often trade on commodity spot pricing. Price differentiation stems from quality grade, adherence to specific certifications like CE marking, and volume scale. Pricing softness affects standard grades due to persistent substitution from lower-cost polypropylene fibers. Civil engineering projects exhibit lower price sensitivity for certified high-strength fibers, contrasting with the high sensitivity in commodity nonwoven applications.
Supply Chain Analysis
Strategic stockpiles of vinyl acetate monomer (VAM) mitigate raw material price volatility for major PVA fiber producers. Polyvinyl alcohol fiber production concentrates significantly in China, with notable capacities also in Japan and Germany. The entire supply chain relies on VAM, a petrochemical derivative subject to global oil and natural gas market fluctuations. This dependence creates a structural risk of cost spikes for fiber manufacturers. Distribution runs primarily through direct sales channels to large-scale industrial consumers and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Polyvinyl Alcohol Fiber market offers a defensive moat story, as regulatory entrenchment through compliance with CE marking and GB standards creates significant barriers to entry for new players.
For Market Incumbents: Consolidate market share by expanding production capacity for high-strength grades in strategic geographies like India, leveraging the PLI scheme. Deepen vertical integration into key raw material production to mitigate vinyl acetate monomer price volatility. Prioritize certification investment for new product formulations to maintain market access against evolving EU REACH and China GB standards. This strategy counters margin pressure from commodity grades and emerging competitive threats.
For New Entrants and Emerging Players: Lead with innovative, high-purity PVA fibers targeting emerging biomedical applications such as absorbable surgical sutures. The most penetrable segment lies in specialized filtration media, where tailored surface properties command premium pricing. Focus on engineering fibers with precise deniers for high-performance liquid and air filtration systems. A strategic go-to-market angle involves direct partnerships with medical device OEMs for co-development.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the high-strength PVA fiber segment due to specialized R&D and compliance requirements. This market demonstrates long-term viability, underpinned by essential infrastructure demand and regulatory tailwinds replacing asbestos. Target acquisition profiles include specialized fiber producers with proprietary water-soluble technologies or strong regional market access in Asia. The signal to watch is the pace of new regulatory mandates for sustainable construction materials, which will drive further PVA adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Secures market share in high-growth infrastructure markets like China and India. |
| R&D for Water-Soluble Grades | Unlocks new applications in consumer goods and addresses sustainability demands. |
| Biomedical Application Partnerships | Creates high-value, niche revenue streams in medical device manufacturing. |
| Certification and Compliance Investment | Ensures continued market access in regulated regions like Europe and China. |
| Geotextile Product Development | Addresses underpenetrated markets for soil stabilization and erosion control. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings. Interviews included R&D directors, procurement leads for construction materials, nonwoven fabric manufacturers, and chemical engineers. Secondary validation drew from customs data, chemical industry association reports, company financial filings, and regulatory body publications like REACH and China's GB standards. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and comprehensive market sizing.
Sensitivity analysis informed the development of a robust analytical framework across the projection horizon. The framework modeled market dynamics across product type, application, end-use industry, form, and regional regulatory environments. Compound annual growth rates were derived from historical trends, expert consensus, and projected demand drivers. Key forecast inputs included vinyl acetate monomer price forecasts and global infrastructure spending projections.
The analysis sits within stated boundaries; outcomes outside of anticipated raw material price stability or regulatory evolution would require recalibration. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Revision becomes warranted when geopolitical shifts significantly impact VAM supply or unforeseen regulatory changes alter market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
North America Nanofiber Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Bioglass Fiber Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Vinylon Market
Fibers
E-Glass Fiber Market
Fibers
Acoustical Fiber Board Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Global Fiberglass Mold Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Global R-Glass Fiber Market
Fibers
Renewable Carbon Fibers Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
High Performance Fibers for Defense Market