
 Asia-Pacific Formic Acid Market | 2026-2036
Asia-Pacific Formic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Formic Acid Market Insights
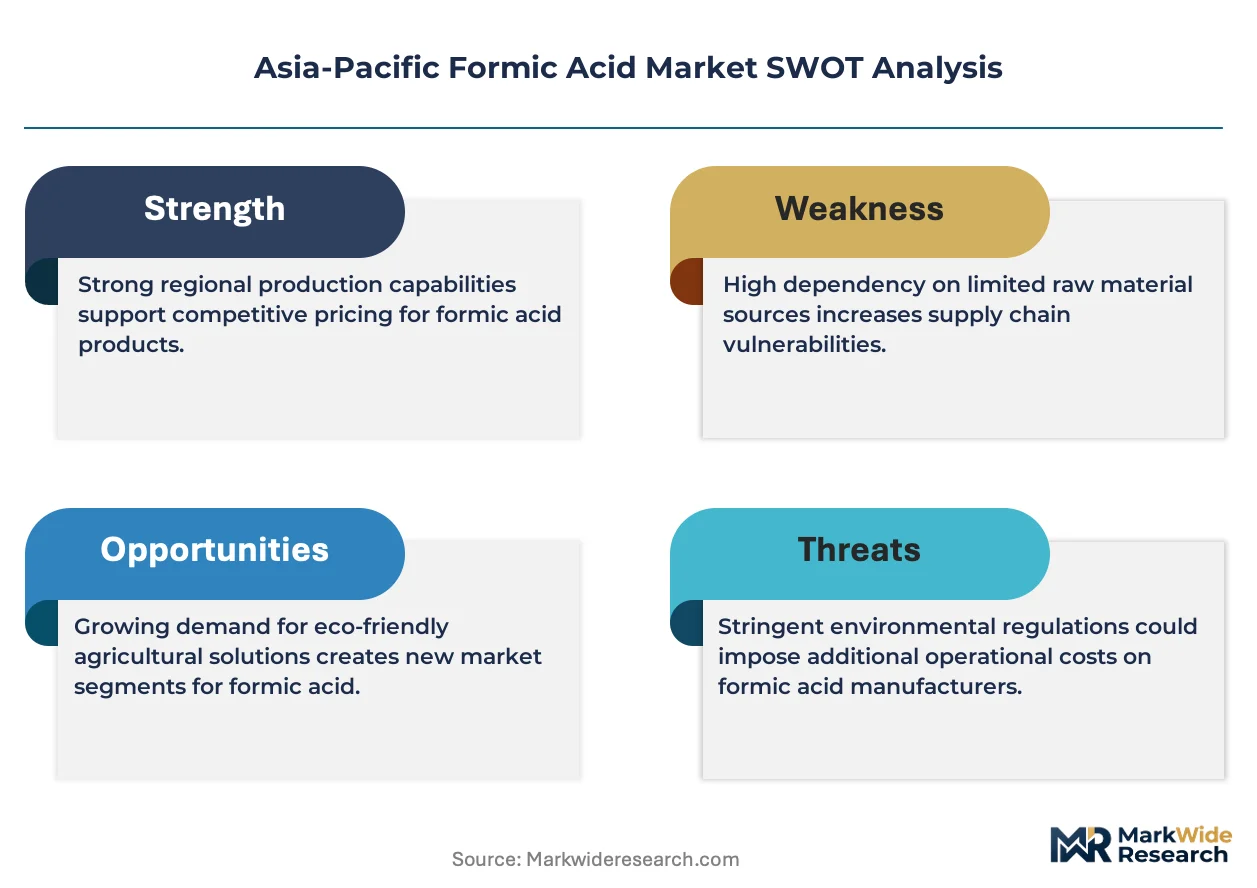
Aftermarket technical service revenue is fragmenting as regional distributors build in-house blending capabilities. Gujarat Narmada Valley Fertilizers & Chemicals Limited anchors its position through captive methanol supply and integrated ammonia-formic acid loops. Chongqing Chuandong Chemical competes on rail-linked logistics across Sichuan and Guizhou provinces. BASF SE differentiates via pharmaceutical-grade certification and REACH-aligned quality protocols exported from its Ludwigshafen base into Asian markets.
Formic acid (HCOOH) is the simplest carboxylic acid, typically manufactured through methyl formate hydrolysis or carbonylation of methanol, with commercial grades ranging from 85 percent to 99 percent purity depending on end-use tolerance for water content. Its primary industrial purpose spans leather tanning, animal feed silage preservation, and textile dyeing reduction chemistry. Concentrated formic acid occupies the dominant margin pool due to freight efficiency and downstream dilution economics, while diluted variants serve cost-sensitive agricultural buyers across Indonesia and Vietnam. Preservative applications lead volume throughput, though pH regulator demand in specialty textile finishing is expanding fastest among application categories.
China's MEE enforces COD and formic acid effluent limits that elevate compliance costs for small tanneries, while India's CPCB mandates zero liquid discharge in Kanpur-Unnao clusters. BIS certification for feed-grade formic acid creates non-tariff barriers for uncertified imports into Indian animal nutrition channels. Stakeholders must monitor how China's dual carbon goals reshape methanol feedstock pricing and whether Southeast Asian leather houses accelerate consolidation to absorb regulatory compliance burdens.
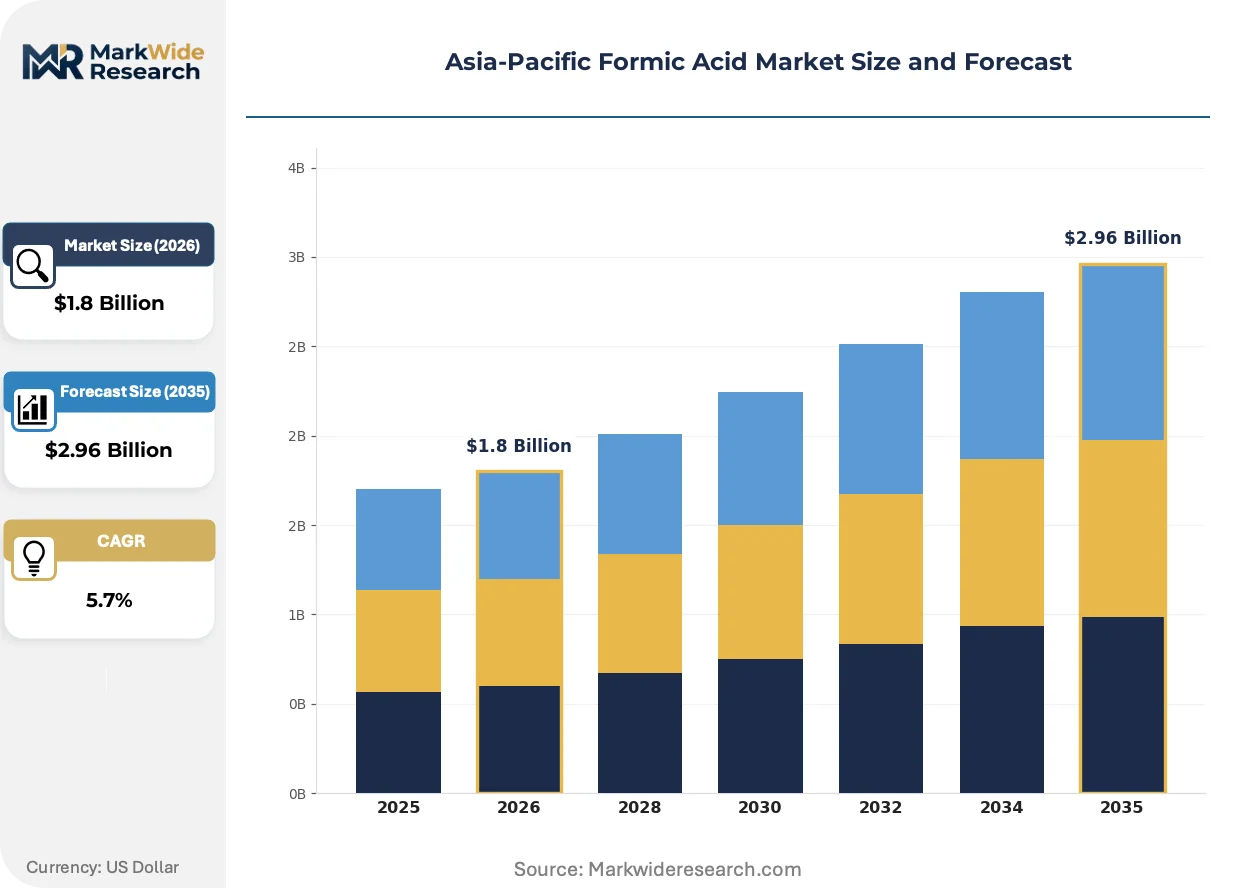
Market Dynamics
China's MEE wastewater discharge enforcement is compressing small-tannery capacity while concentrating demand among integrated leather processors capable of absorbing higher-purity acid costs.
Growth Catalysts
- Leather Tanning Intensification:Southeast Asian tanneries are expanding preservative-grade formic acid offtake as finished leather export orders concentrate in Vietnam and Indonesia.
- MEE Compliance Upgrades:China's tightening COD and formic acid effluent limits are forcing tannery consolidation toward higher-purity formulations that reduce downstream treatment burden.
- Silage Preservation Expansion:India's northern dairy belt around Punjab and Haryana is absorbing feed-grade volumes as commercial feed operations displace traditional preservation methods.
Market Restraints
- Methanol Feedstock Volatility:Formic acid production economics hinge on methanol pricing, which fluctuates with China's dual carbon policy implementation and coal-to-chemicals capacity adjustments.
- BIS Certification Barriers:India's BIS feed-grade certification creates non-tariff friction for uncertified imports, limiting supplier diversification in animal nutrition channels.
- Caustic Soda Substitution:Textile processors in Bangladesh and Pakistan are partially reverting to caustic soda for pH adjustment where formic acid cost premiums exceed performance benefits.
Strategic Opportunities
- Pharmaceutical-Grade Certification:REACH-aligned quality protocols are creating premium positioning for European-certificate holders supplying Asian pharmaceutical intermediate manufacturers.
- Zero Liquid Discharge Clusters:India's CPCB-mandated ZLD implementation in Kanpur-Unnao leather belts is concentrating demand among acid suppliers capable of technical service integration.
- Rail-Linked Logistics Hubs:Sichuan and Guizhou provinces offer captive distribution nodes for methanol-integrated producers serving interior Chinese tanneries.
Industry Challenges
- Effluent Chemistry Expertise Gap:Small tanneries lack in-house capability to optimize formic acid dosing for MEE-compliant wastewater profiles, creating service dependency on chemical distributors.
- Multi-Grade Inventory Complexity:Suppliers must maintain parallel 85 percent and 99 percent purity stocks across divergent agricultural and industrial specifications, compressing working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Formic Acid Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Formic Acid, Diluted Formic Acid, Formic Acid Solution, Anhydrous Formic Acid End User: Agriculture, Leather, Chemicals, Animal Feed Application: Preservative, Reducing Agent, Catalyst, pH Regulator Distribution Channel: Direct Sales, Wholesale, Online Retail, Specialty Chemical Distributors |
| Companies Covered | Gujarat Narmada Valley Fertilizers & Chemicals Limited, Chongqing Chuandong Chemical (Group) Co., Ltd., BASF SE, Mudanjiang Fengda Chemical Co Ltd, Feicheng Acid Chemicals Co., Ltd, Eastman Chemical Company, Shandong Acid Technology Co Ltd, Huanghua Pengfa Chemical Co Ltd, LUXI GROUP, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Formic Acid Market Trends and Innovations
Membrane-based methyl formate hydrolysis is displacing conventional sulfuric acid catalysis, reshaping capital intensity and purity thresholds across Asian production bases.
Continuous membrane reactor technology is rendering obsolete batch-wise sulfuric acid catalysis in formic acid manufacturing. Chinese producers in Shandong and Jiangsu provinces are retrofitting existing methyl formate units to capture energy efficiency gains and reduce acid byproduct handling. The shift is compressing marginal production costs for 99 percent purity grades while elevating technical barriers for non-integrated entrants.
India's BIS feed-grade certification mandate is segmenting supplier tiers in animal nutrition channels. Uncertified imports face extended customs scrutiny and end-user rejection, while domestic certificate holders capture price premiums in compound feed formulations. The friction is accelerating backward integration among large dairy cooperatives seeking supply security.
Aftermarket technical service unbundling is disrupting traditional distributor relationships in leather processing. Kanpur-based tanneries are building in-house blending capabilities for dilute acid formulations, compressing margin pools for regional distributors dependent on value-added mixing services. The pattern is most visible among export-oriented processors supplying European automotive leather contracts.
Asia-Pacific Formic Acid Market Segmentation
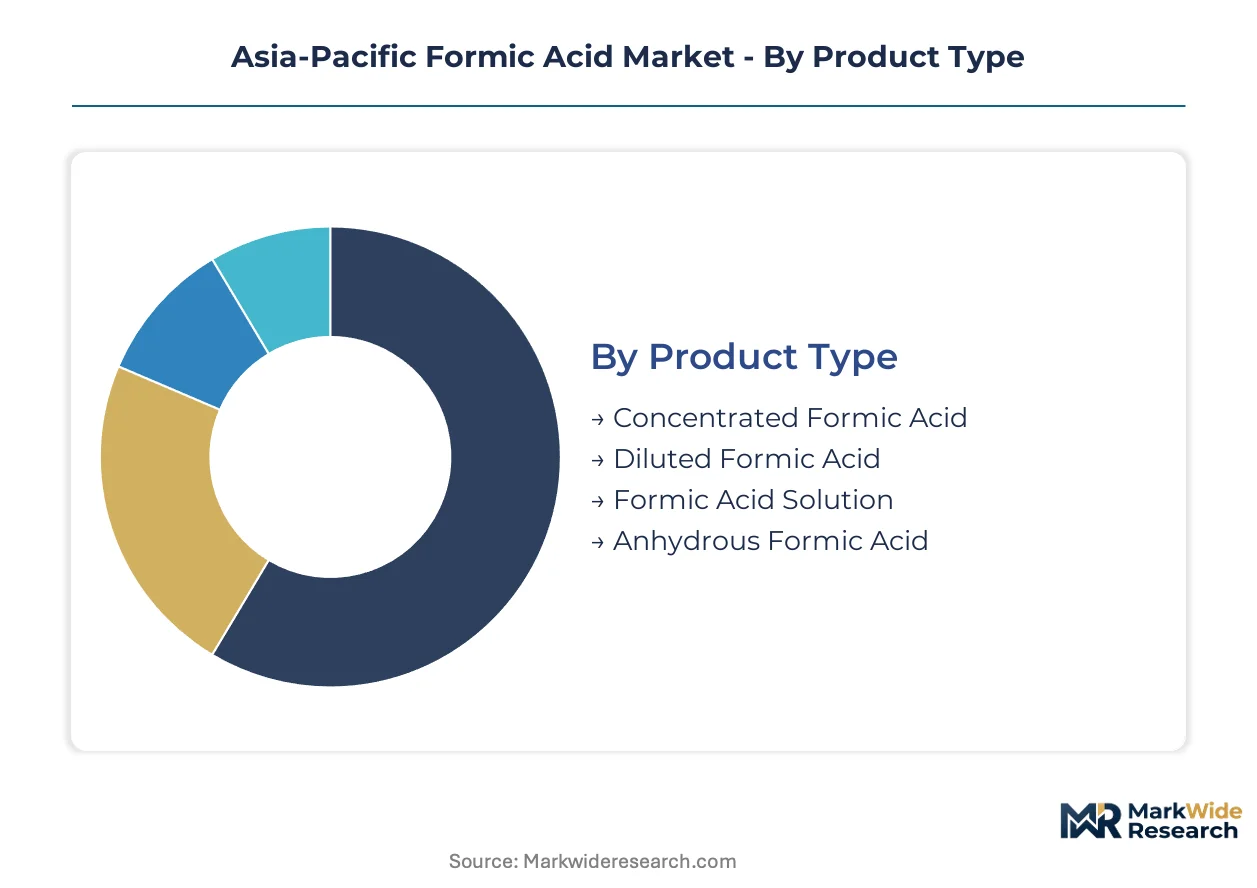
Formic acid buyers in the Asia-Pacific region exhibit sharply divergent service expectations across purity grades and end-use applications. Technical support intensity varies from minimal for standardized agricultural dilutions to intensive for leather processors navigating MEE wastewater compliance.
Product Type:
After-sales service intensity escalates with concentration level, as higher-purity grades demand dosing optimization support and effluent chemistry guidance.
- Concentrated Formic Acid:Commercial grades at 85-99 percent purity dominate freight economics through downstream dilution. Demand concentrates among integrated Vietnamese and Indonesian tanneries supplying European automotive leather contracts, where MEE-aligned wastewater protocols require precise acid dosing.
- Diluted Formic Acid:Pre-mixed solutions at 10-50 percent concentration serve cost-sensitive agricultural buyers. India's Punjab dairy belt absorbs feed-grade volumes as commercial silage operations displace traditional preservation methods, though BIS certification creates supplier friction.
- Formic Acid Solution:Custom-blended aqueous formulations address textile dyeing houses in Bangladesh requiring pH buffer precision.
- Anhydrous Formic Acid:Ultra-high purity above 99 percent serves pharmaceutical intermediate manufacturers in Japan and South Korea demanding REACH-aligned certification.
Concentrated Formic Acid holds the largest share; momentum sits with Anhydrous Formic Acid.
End User:
Margin structures vary dramatically by customer sophistication, from commodity procurement in agriculture to specification-driven purchasing in specialty chemicals.
- Agriculture:Silage preservation across India's northern states absorbs standardized dilutions. Procurement concentrates among dairy cooperatives building backward integration into compound feed manufacturing.
- Leather:Kanpur-Unnao clusters under CPCB zero liquid discharge mandates drive technical service bundling. Vietnamese export houses absorb higher-purity grades for European contract compliance.
- Chemicals:Formic acid serves as reducing agent and synthetic intermediate across Shandong province methanol-integrated complexes.
- Animal Feed:BIS-certified feed-grade volumes face import scrutiny, accelerating domestic certificate holder premiums.
Leather commands the dominant volume position; Animal Feed is climbing the fastest on dairy commercialization.
Application:
Functional differentiation determines pricing power, with reactive chemistry applications commanding premiums over passive preservation uses.
- Preservative:Leather tanning and silage applications absorb the majority of regional throughput. Southeast Asian tanneries expand offtake as finished leather export orders concentrate in Vietnam.
- Reducing Agent:Textile dyeing chemistry in Bangladesh and Pakistan demands precise redox control, though caustic soda substitution pressure limits growth.
- Catalyst:Pharmaceutical intermediate synthesis in Japan and South Korea requires pharmaceutical-grade certification.
- pH Regulator:Specialty textile finishing in China's Zhejiang province is expanding most quickly among application categories on performance fabric demand.
Preservative maintains volume leadership; pH Regulator shows the steepest expansion trajectory.
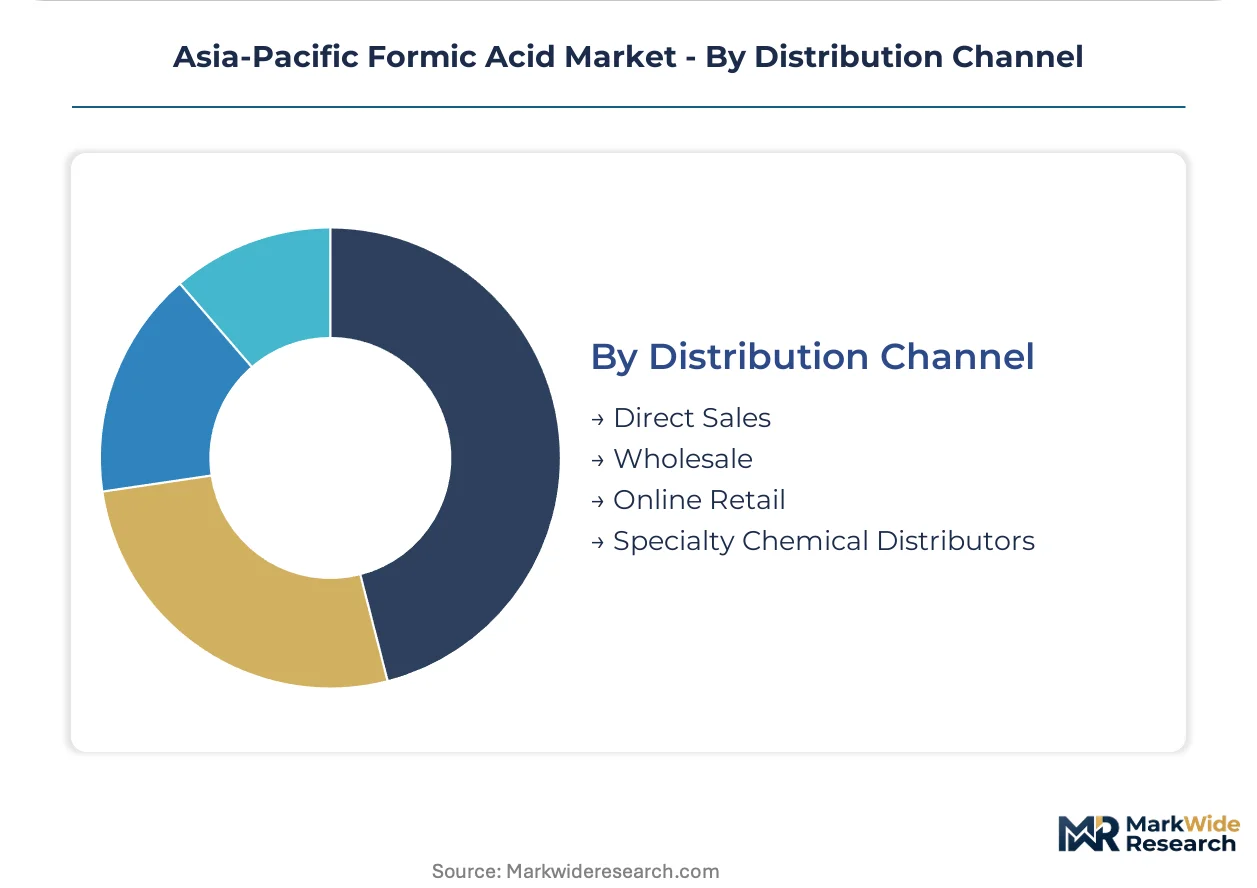
Distribution Channel:
Channel selection reflects buyer scale and technical capability, with large processors bypassing intermediaries while smaller tanneries rely on service-integrated distributors.
- Direct Sales:Integrated leather processors and methanol-captive chemical complexes purchase concentrated volumes via mill-direct arrangements. Gujarat Narmada Valley Fertilizers & Chemicals Limited leverages captive supply relationships.
- Wholesale:Bulk agricultural buyers across Indonesia and Vietnam procure standardized dilutions through regional trading houses.
- Online Retail:Small-scale dairy operations in India's secondary cities access feed-grade volumes via B2B platforms.
- Specialty Chemical Distributors:Kanpur-based tanneries source technical service bundles for MEE-compliant wastewater optimization, though in-house blending capabilities are compressing margin pools.
Direct Sales captures the dominant value share; Specialty Chemical Distributors face structural pressure from unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural buyers in Vietnam and Indonesia exhibit the highest price elasticity, while pharmaceutical-grade purchasers in Japan and South Korea absorb substantial premiums for REACH-aligned certification.
China
Shandong and Jiangsu provinces host retrofitted membrane reactor facilities serving methanol-integrated chemical complexes. MEE wastewater discharge rules under dual carbon policy implementation are compressing small-tannery capacity toward higher-purity acid demand. Sichuan-Chongqing rail corridors enable captive distribution to interior leather processors.
India
Punjab and Haryana dairy belts absorb feed-grade volumes as commercial silage operations displace traditional preservation methods. BIS certification mandates create non-tariff barriers for uncertified imports into animal nutrition channels. Kanpur-Unnao leather clusters under CPCB zero liquid discharge mandates concentrate demand among technically integrated suppliers.
Vietnam
Export-oriented tanneries supplying European automotive leather contracts drive preservative-grade offtake expansion. Cost-sensitive agricultural procurement in Mekong Delta regions favors diluted formulations over concentrated alternatives. Ho Chi Minh City logistics hubs facilitate regional distribution across Southeast Asian leather houses.
Indonesia
Java-based leather processors absorb standardized dilutions for cost-sensitive tanning operations serving domestic footwear markets. Feed-grade demand concentrates among large dairy cooperatives building backward integration into compound feed manufacturing. Jakarta-Bandung industrial corridors anchor chemical distribution infrastructure.
Japan
Pharmaceutical intermediate manufacturers in Kanto and Kansai regions command ultra-high purity grades above 99 percent. METI-aligned quality protocols create premium positioning for REACH-certified imports serving synthetic chemistry applications. Osaka-Tokyo pharmaceutical clusters drive specification-driven procurement with minimal price sensitivity.
Asia-Pacific Formic Acid Market Competitive Landscape
Methanol-captive producers and specialty-certification holders split the market along purity-grade lines. The vendor base organizes into three strategic archetypes: integrated fertilizer-chemical complexes with captive feedstock control, regional logistics specialists leveraging rail-linked distribution, and European-certified suppliers commanding pharmaceutical-grade premiums. Capacity expansion and technical service bundling represent the dominant competitive moves as regulatory compliance burdens reshape buyer-supplier relationships.
Among Indian integrated producers, Gujarat Narmada Valley Fertilizers & Chemicals Limited occupies a position exemplifying captive methanol supply and ammonia-formic acid loop integration. Chinese regional specialists Chongqing Chuandong Chemical and Shandong Acid Technology represent archetypes leveraging interior rail corridors and membrane reactor retrofits respectively. European-certificate holders BASF SE anchor the premium-tier vector through REACH-aligned quality protocols exported into Asian pharmaceutical channels.
| Leading Market Players |
|---|
| Gujarat Narmada Valley Fertilizers & Chemicals Limited |
| Chongqing Chuandong Chemical (Group) Co., Ltd. |
| BASF SE |
| Mudanjiang Fengda Chemical Co Ltd |
| Feicheng Acid Chemicals Co., Ltd |
| Eastman Chemical Company |
| Shandong Acid Technology Co Ltd |
| Huanghua Pengfa Chemical Co Ltd |
| LUXI GROUP |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shandong and Jiangsu membrane reactor facilities is compressing spot margins for 99 percent purity grades while elevating bargaining power among methanol-captive producers. This utilization imbalance forces non-integrated distributors toward service bundling to defend position, even as freight economics favor concentrated acid shipments to interior Chinese tanneries.
Pricing Analysis
After-sales technical service revenue drives lifetime value differentiation across the Asia-Pacific formic acid market. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and agricultural-grade levels separates BASF's REACH-certified premiums from commodity spot transactions. Cost compression in preservative-grade volumes is intensifying because Kanpur-based tanneries are building in-house blending capabilities. Agricultural buyers across Indonesia and Vietnam exhibit the highest price elasticity, while Japanese pharmaceutical intermediate manufacturers absorb substantial premiums for anhydrous certification.
Supply Chain Analysis
Extended payment terms from Sichuan-Chongqing rail-linked distributors are easing working capital constraints for interior Chinese leather processors. Supply concentrates in China, India, and Vietnam, with methanol feedstock sourcing from coal-to-chemicals complexes in Shandong and Ningxia. Production draws from methyl formate hydrolysis and carbonylation inputs, with membrane reactor retrofits displacing legacy sulfuric acid catalysis. Single-source vulnerability around methanol pricing under China's dual carbon policy implementation threatens margin stability. Distribution runs through mill-direct arrangements for integrated processors and specialty chemical distributors for MEE-compliant tanneries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane reactor technology disruption is reshaping production economics across the Asia-Pacific formic acid market, with China's MEE wastewater enforcement compressing small-tannery capacity toward higher-purity demand concentration.
For Market Incumbents: Insulate margin position through captive methanol supply integration and ammonia-formic acid loop investments in Gujarat and Ningxia production bases. Defend against in-house blending unbundling by embedding technical service teams directly within Kanpur-Unnao leather clusters for MEE-compliant wastewater optimization.
For New Entrants and Emerging Players: Pursue white-space opportunity in pharmaceutical-grade certification gaps across South Korean and Japanese synthetic chemistry channels. Target India's BIS-certified feed-grade segment where import scrutiny creates domestic supply security premiums. Enter through technical service partnerships with large dairy cooperatives building backward integration into compound feed manufacturing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane reactor-equipped producers with rail-linked distribution networks serving interior Chinese tanneries. Long-term viability over a five-to-ten-year window favors methanol-captive integrated complexes over pure-play distributors exposed to blending unbundling. Monitor China's dual carbon policy implementation pace as the critical inflection signal for methanol feedstock pricing trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Reactor Retrofit | Shandong and Jiangsu facilities capture energy efficiency gains while reducing acid byproduct handling burdens. |
| Backward Integration into Methanol | Gujarat Narmada Valley Fertilizers anchors cost position through captive feedstock supply security. |
| Pharmaceutical-Grade Certification | BASF's REACH-aligned protocols command premium positioning in Japanese and South Korean intermediate synthesis. |
| Rail-Linked Distribution Hub | Chongqing Chuandong Chemical leverages Sichuan-Guizhou corridors for interior tannery captive supply. |
| Technical Service Embedding | Kanpur-Unnao cluster integration defends against distributor margin compression from in-house blending. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with leather processing technical directors, dairy cooperative procurement leads, chemical distribution channel partners, and MEE compliance officers at Chinese tanneries. Secondary validation drew from customs and trade flow databases, China MEE discharge monitoring reports, India CPCB zero liquid discharge cluster filings, and BIS certification registries. Bottom-up volume modeling triangulated against top-down methanol consumption estimates across methyl formate hydrolysis and carbonylation routes.
Calibration against historical capacity utilization rates and purity-grade shipment patterns anchored projections across the analysis window. Segmentation dimensions modeled include concentration tier, end-use application, and regional regulatory cluster. CAGRs were derived from regression analysis of methanol pricing elasticity, leather export order concentration, and dairy commercialization rates. Forecast inputs incorporated membrane reactor retrofit adoption curves and MEE enforcement intensity trajectories.
Sensitivities concentrate around methanol feedstock volatility under dual carbon policy implementation and tannery consolidation pace under wastewater compliance burdens. Forecasts reflect assumptions regarding regulatory enforcement continuity and technology adoption timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
United States Calcium Chloride Market