
 Isobutene Market | 2026-2036
Isobutene Market Size, Share, and Industry Trends Forecast 2026-2036
Isobutene Market Outlook
US Gulf Coast steam cracker operators is shifting isobutene extraction priorities toward on-purpose dehydrogenation units as ethane feedslates yield lighter C4 fractions. LyondellBasell Industries leverages its Channelview complex integration to sustain merchant isobutene supply flexibility. BASF anchors European demand through its Ludwigshafen derivatives chain, while ExxonMobil competes via Baton Rouge refinery-borne C4 processing scale.
Isobutene is a branched four-carbon olefin produced via steam cracking, catalytic dehydrogenation of isobutane, or dehydration of tertiary butyl alcohol, with a boiling point of minus 6.9 degrees Celsius and reactivity driven by its terminal double bond. The compound serves primarily as a chemical intermediate for polymers, fuel oxygenates, and synthetic rubber production. Polyisobutylene dominates value capture in sealants and lubricant additive formulations where molecular weight control commands premium positioning. Methyl tert-butyl ether retains structural volume in fuel oxygenate blending despite regional regulatory phase-outs, while isobutylene-isoprene rubber specializes in tire innerliner applications demanding low gas permeability.
EPA Tier 3 sulfur regulations and REACH restrictions on residual olefin content in fuel formulations shape product purity standards and refinery investment cycles. The EU F-Gas Regulation and California Air Resources Board low-carbon fuel standards are forcing bio-based isobutene pathway development through fermentation routes. Stakeholders must monitor dehydrogenation catalyst technology advances and bio-isobutene cost parity timelines to time capacity commitments.
Market Dynamics
Steam cracker feedstock shifts toward lighter ethane slates are structurally depleting refinery-derived C4 stream availability, forcing isobutene producers toward on-purpose dehydrogenation investments and bio-based fermentation pathways to maintain supply continuity.
Growth Catalysts
- EPA Tier 3 sulfur standards:Refiners require higher-purity isobutene for fuel oxygenate blending to meet gasoline sulfur limits, sustaining demand for extraction capacity upgrades along the US Gulf Coast petrochemical corridor.
- Polyisobutylene sealant formulations:Automotive OEMs specify high-molecular-weight grades for underbody coatings and window sealing systems, creating specification pull through tiered supplier networks.
- Butyl rubber tire innerliners:Electric vehicle weight loads accelerate wear on tire gas-barrier layers, expanding isobutylene-isoprene rubber consumption for low-permeability liner compounds.
Market Restraints
- Propane dehydrogenation feedstock volatility:Isobutane supply tightens during peak winter heating demand cycles, compressing cracker margins and forcing production curtailments at merchant extraction units.
- REACH residual olefin restrictions:European fuel formulation standards limit olefin content in finished gasoline pools, constraining MTBE blending ratios and redirecting isobutene toward chemical derivative outlets.
- Bio-isobutene cost parity gaps:Fermentation-derived pathways from agricultural sugars remain 15-30% above petrochemical production economics, delaying commercial scale-up despite EU F-Gas Regulation pressure.
Strategic Opportunities
- Lubricant additive premiumization:Polyisobutylene viscosity modifiers command price premiums in synthetic motor oil formulations, particularly for API SP and ILSAC GF-6 certification tiers requiring thermal stability.
- India automotive emission norms:BS-VI Phase II implementation expands fuel oxygenate demand as refiners upgrade to meet particulate and sulfur specifications, opening import substitution opportunities for regional dehydrogenation investments.
- Carbon capture integration:On-purpose production units can co-locate with CO2 utilization for enhanced oil recovery, qualifying for US IRA 45Q credits while reducing net process emissions.
Industry Challenges
- Dehydrogenation catalyst regeneration cycles:Chromia-alumina catalyst deactivation rates accelerate under high-severity operating conditions, requiring specialized technical services for turnaround scheduling and spent catalyst handling.
- Derivatives qualification timelines:Polyisobutylene molecular weight certification for pharmaceutical stoppers and food-grade sealants demands 18-24 month stability testing protocols, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isobutene Market |
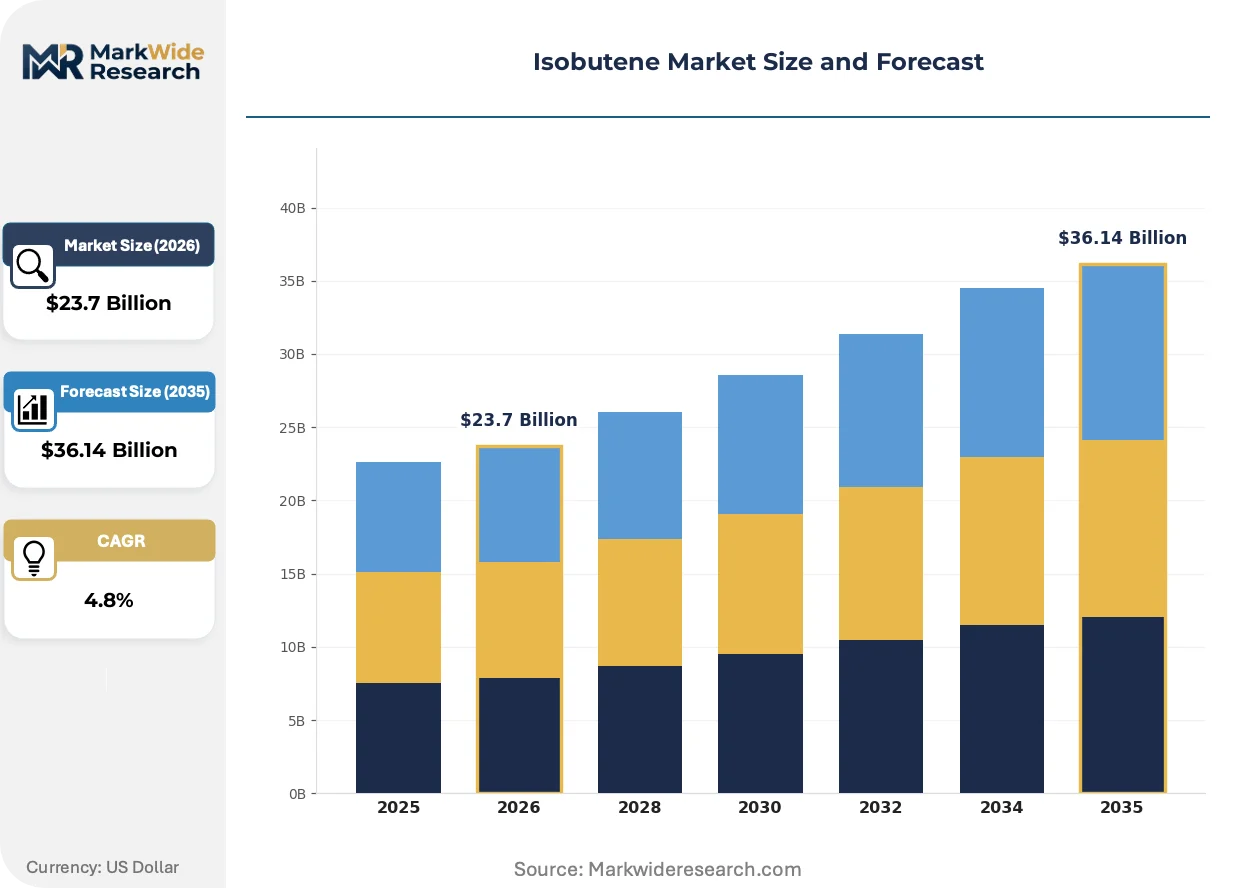
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyisobutylene, Methyl Tert-Butyl Ether, Isobutylene-Isoprene Rubber, Octyl Acrylate End User: Automotive, Packaging, Adhesives, Pharmaceuticals Application: Fuel Additives, Sealants, Lubricants, Coatings Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Evonik Industries, LyondellBasell Industries, BASF, ExxonMobil, TPC Group, Linde, Honeywell International, Global Bioenergies, Enterprise Products Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isobutene Market Strategic Shifts
Process intensification and digital control systems are compressing isobutene production economics while regulatory carbon accounting forces disclosure of Scope 3 emissions across derivative supply chains.
Advanced process control using machine learning algorithms is automating reactor temperature profiling and catalyst life prediction at dehydrogenation units. Operators at integrated petrochemical complexes deploy these systems to minimize unplanned shutdowns and extend catalyst cycles beyond 24 months. The technology is automating yield optimization decisions previously requiring manual laboratory intervention, reducing off-spec production episodes.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are redirecting isobutene toward halogen-free blowing agent applications in rigid polyurethane foam insulation. Chemical intermediate producers reformulate polyol systems to accommodate isobutene-derived pentane blends as drop-in replacements. Building retrofit programs in Germany and France accelerate specification pull for low-global-warming-potential insulation materials.
Refinery-procurement contracts now incorporate carbon intensity clauses requiring disclosure of upstream methane leakage and flaring rates from C4 feedstock origins. Integrated oil companies impose these terms on merchant isobutene suppliers serving their downstream blending operations. The practice concentrates purchasing power among buyers with in-house lifecycle assessment capabilities, disadvantaging smaller extraction operators lacking emissions verification infrastructure.
Isobutene Market Segmentation
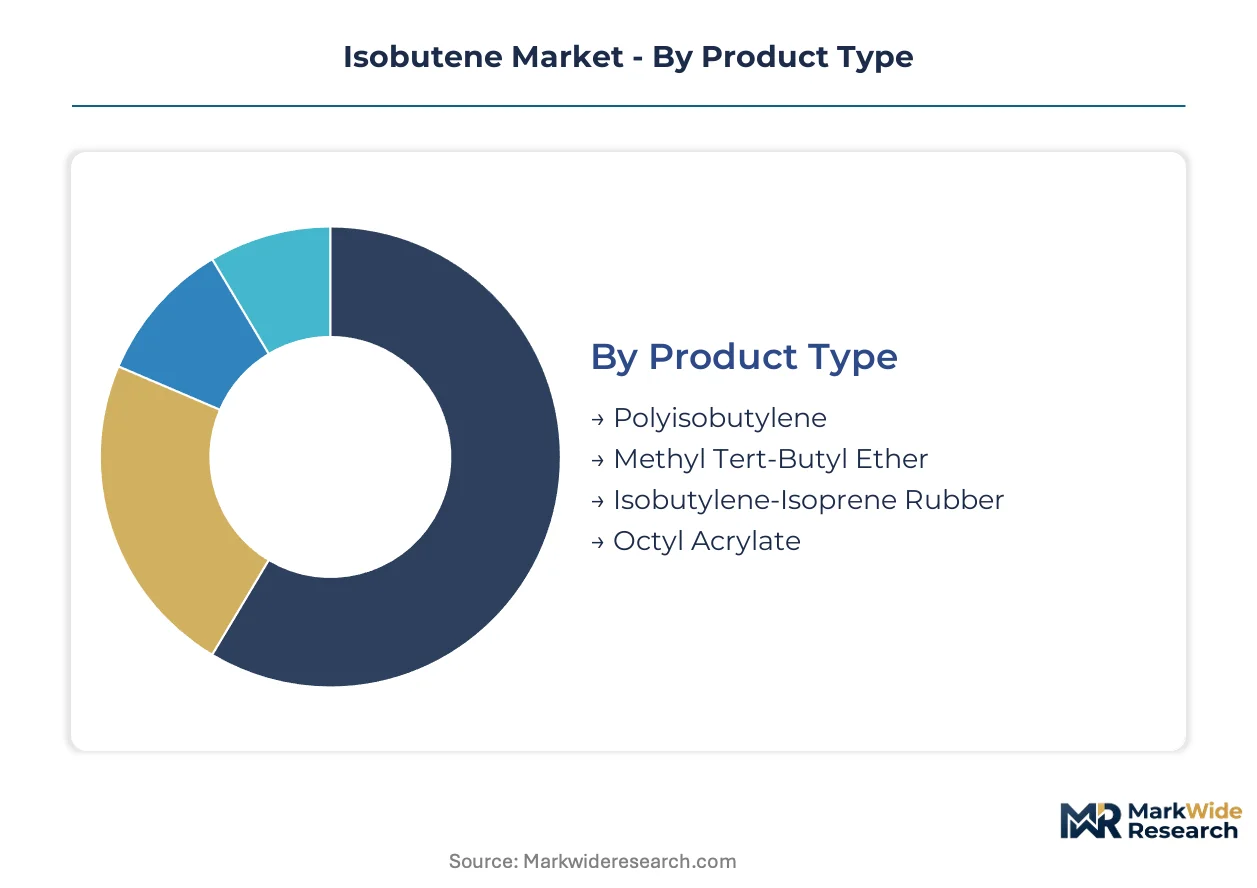
Isobutene derivatives serve divergent specification regimes across fuel blending, polymer formulation, and rubber compounding end-uses. Buyer procurement criteria vary sharply by application—purity thresholds for fuel oxygenates, molecular weight distribution for sealants, and gas permeability coefficients for tire innerliners.
Product Type:
Selection hinges on downstream margin capture potential and technical specification barriers.
- Polyisobutylene:High-molecular-weight grades dominate sealant and lubricant additive formulations where viscosity index improvers command formulation premiums. Automotive OEMs specify narrow polydispersity ranges for underbody coatings and window sealing systems, creating qualification barriers that sustain incumbent supplier positions.
- Methyl Tert-Butyl Ether:Fuel oxygenate blending retains structural volume in gasoline pools despite regional regulatory phase-outs. EPA Tier 3 sulfur standards sustain demand for high-purity MTBE in US Gulf Coast refinery operations where extraction capacity upgrades concentrate.
- Isobutylene-Isoprene Rubber:Tire innerliner applications demand ultra-low gas permeability for electric vehicle weight loads.
- Octyl Acrylate:Pressure-sensitive adhesive monomers for packaging tapes and label applications.
Polyisobutylene leads on scale; Isobutylene-Isoprene Rubber leads on momentum.
End User:
Volume concentration tracks automotive emission regulation cycles and packaging material substitution trends.
- Automotive:Fuel oxygenate demand concentrates in OEM supply chains adapting to BS-VI Phase II norms in India and EPA Tier 3 standards in the US. Tire innerliner specifications for electric vehicle platforms accelerate isobutylene-isoprene rubber consumption.
- Packaging:Pressure-sensitive adhesives and sealant films drive octyl acrylate and polyisobutylene demand for food-grade barrier layers.
- Adhesives:Construction and industrial bonding applications specify high-tack polyisobutylene grades.
- Pharmaceuticals:Medical stoppers and vial seals require 18-24 month stability certification protocols.
Automotive absorbs the largest volume share; Pharmaceuticals shows the steepest expansion trajectory.
Application:
Specification intensity separates commodity blending from premium formulation segments.
- Fuel Additives:Refinery blending operations require sulfur-compliant oxygenates meeting EPA Tier 3 gasoline pool standards. US Gulf Coast petrochemical corridor concentration shapes procurement contract structures with carbon intensity disclosure clauses.
- Sealants:High-molecular-weight polyisobutylene dominates automotive underbody coatings and construction glazing applications where elongation recovery rates determine specification compliance.
- Lubricants:Viscosity modifiers for API SP and ILSAC GF-6 certified motor oils.
- Coatings:Protective and corrosion-resistant industrial finishes.
Fuel Additives commands the broadest volume base; Sealants captures the highest margin premiums.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and geographic proximity to production assets.
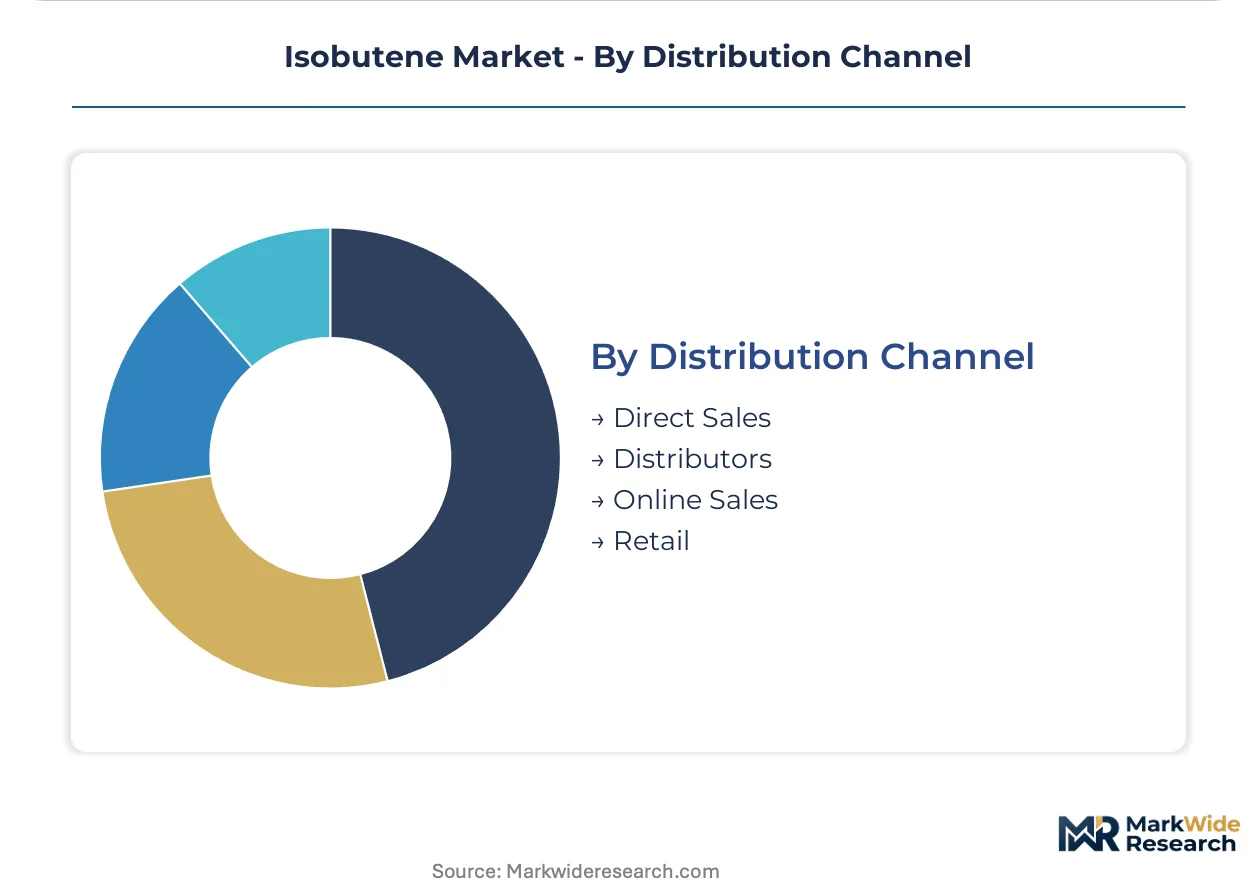
- Direct Sales:Integrated refiners and large polymer compounders procure isobutene and derivatives through long-term offtake agreements with US Gulf Coast steam cracker operators. Contracts incorporate carbon intensity verification and catalyst regeneration service provisions.
- Distributors:Regional chemical distributors serve mid-tier adhesive and sealant formulators requiring smaller lot sizes and technical formulation support.
- Online Sales:Specialty chemical marketplaces for research-grade and small-volume industrial samples.
- Retail:Consumer-packaged lubricant additives and fuel treatments through automotive aftermarket channels.
Direct Sales leads on contract value; Distributors leads on customer reach expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands extraction capacity scale unmatched elsewhere, while Germany anchors European derivative demand through integrated chemical complexes. China and India represent the fastest-growing consumption centers as automotive emission norms tighten. Saudi Arabia emerges as a strategic feedstock supplier leveraging advantaged propane economics.
United States
EPA Tier 3 sulfur standards sustain refinery oxygenate demand along the Gulf Coast petrochemical corridor. The Inflation Reduction Act's 45Q carbon capture credits incentivize dehydrogenation unit co-location with CO2 utilization infrastructure. Houston-Channelview cluster operators leverage steam cracker integration to maintain merchant supply flexibility.
Germany
EU F-Gas Regulation phase-downs redirect isobutene toward halogen-free blowing agents for rigid polyurethane insulation. REACH residual olefin restrictions constrain fuel blending ratios, forcing derivative outlet prioritization. BASF's Ludwigshafen complex anchors continental demand through backward-integrated polyisobutylene and rubber production chains.
China
Dual carbon goals and NEV weight loads accelerate tire innerliner consumption for low-permeability compounds. MIIT fuel quality standards expand oxygenate blending requirements as refiners upgrade gasoline pool specifications. Yangtze River Delta chemical parks concentrate dehydrogenation investments serving domestic automotive OEM supply chains.
India
BS-VI Phase II implementation drives fuel additive demand as refiners adapt to particulate and sulfur limits. The PLI scheme for advanced chemistry cell batteries indirectly supports butyl rubber demand for EV tire applications. Gujarat's Dahej and Hazira industrial corridors attract import-substitution investments in on-purpose production capacity.
Saudi Arabia
Advantaged propane feedstock economics support export-oriented dehydrogenation project development. SABIC integration strategies prioritize derivative value capture over merchant olefin sales. Jubail Industrial City hosts expanding C4 processing infrastructure serving Asian polymer and rubber compounder demand.
Isobutene Market Competitive Environment
US Gulf Coast producers anchor the scale-driven tier; European specialists hold specification-sensitive positions in pharmaceutical and food-grade sealants. The market structures around three archetypes: integrated petrochemical majors with cracker-derived feedstock access, on-purpose dehydrogenation operators serving merchant markets, and bio-based pathway developers targeting regulatory-driven premium segments. Capacity expansion and carbon capture co-location represent dominant competitive moves as producers defend margin positions against feedstock volatility.
Within the integrated major tier, LyondellBasell Industries and ExxonMobil exemplify Gulf Coast concentration advantages through Channelview and Baton Rouge complex integration. BASF occupies a position bridging European derivative demand with Ludwigshafen-based backward integration. Global Bioenergies represents the bio-based archetype, anchoring fermentation pathway development despite current cost parity gaps with petrochemical economics.
| Leading Market Players |
|---|
| Evonik Industries |
| LyondellBasell Industries |
| BASF |
| ExxonMobil |
| TPC Group |
| Linde |
| Honeywell International |
| Global Bioenergies |
| Enterprise Products Partners |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 3 sulfur specifications and REACH residual olefin limits are forcing refiners and chemical processors to source higher-purity isobutene grades, compelling supply chain reconfiguration toward integrated Gulf Coast producers and certified European specialists with backward-integrated derivative capabilities.
Pricing Analysis
Distributor margins for polyisobutylene and MTBE separate premium pharmaceutical-grade sealants from standard fuel oxygenate blending stock, with certification tier and volume scale as the primary price differentiation drivers. Pricing pressure stems from bio-isobutene fermentation pathways approaching cost parity with petrochemical routes. Small-lot adhesive formulators exhibit highest price sensitivity, while automotive OEMs under long-term offtake agreements show lowest.
Supply Chain Analysis
ISO 9001 and pharmaceutical-grade stability certification requirements gate entry for medical stopper and food-grade sealant suppliers, creating 18-24 month qualification barriers. Production concentrates in the United States, Germany, and China, with feedstock drawn from steam cracker C4 streams, refinery alkylation units, and on-purpose dehydrogenation plants. Single-source vulnerability runs through chromia-alumina catalyst supply for dehydrogenation units. Distribution feeds from direct refinery-procurement contracts into long-term offtake agreements with integrated polymer compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isobutene functions as a stable compounder anchored by regulatory-mandated fuel reformulation cycles and electric vehicle tire specification upgrades that sustain predictable demand across automotive and chemical derivative channels.
For Market Incumbents: Anchor Gulf Coast extraction capacity against bio-isobutene cost parity threats by co-locating dehydrogenation units with carbon capture infrastructure qualifying for IRA 45Q credits. Deepen catalyst regeneration technical services to extend customer switching costs. Defend against merchant supply disruption by locking long-term C4 feedstock agreements with ethane-flexible steam cracker operators. For New Entrants and Emerging Players: Fermentation-derived bio-isobutene pathways offer a technology-first wedge into EU F-Gas Regulation-driven halogen-free blowing agent segments where petrochemical incumbents lack certified low-carbon supply. Target German and French building retrofit insulation markets with drop-in pentane blend formulations. Pursue joint development agreements with polyol system houses to accelerate specification pull-through. For Investors and Strategic Acquirers: Asymmetric upside sits with on-purpose dehydrogenation operators holding Gulf Coast feedstock access and carbon capture co-location options. Long-term viability centers on 5-10 year regulatory compliance runway for fuel oxygenate and low-GWP insulation material demand. Monitor bio-isobutene production cost curves as the signal for petrochemical margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Feedstock Supply | Captive isobutane access insulates LyondellBasell and ExxonMobil from winter heating demand volatility. |
| Carbon Capture Co-location | 45Q credit qualification at Channelview and Baton Rouge complexes reduces net process emissions for merchant supply. |
| Pharmaceutical Grade Certification Investment | 18-24 month stability protocols for medical stoppers lock out unqualified competitors from premium sealant segments. |
| Bio-based Pathway Scale-up | Fermentation routes from Global Bioenergies target EU F-Gas Regulation premiums despite current cost gaps. |
| Long-term Supply Agreement with Automotive OEMs | Direct offtake contracts for tire innerliner compounds secure volume through electric vehicle platform ramps. |
Study Parameters
Direct dialogue with dehydrogenation unit operators, refinery procurement managers, polyisobutylene compounders, automotive Tier 1 tire suppliers, and pharmaceutical packaging engineers grounded qualitative assessment. Secondary validation drew from EPA Tier 3 compliance filings, ECHA REACH registration data, USITC trade flow records, and SEC 10-K disclosures from integrated petrochemical majors. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Bottom-up unit economics for steam cracker extraction, catalytic dehydrogenation, and fermentation pathways were cross-checked against top-down derivative demand across fuel additives, sealants, lubricants, and tire applications. Segmentation modeled product type, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of capacity utilization rates and specification-driven substitution elasticities, incorporating dehydrogenation catalyst life cycles and bio-isobutene cost curve trajectories as industry-specific inputs.
The model holds under stable EPA Tier 3 and REACH regulatory enforcement; deviation in bio-isobutene cost parity timelines or Gulf Coast hurricane disruption frequency would shift capacity investment assumptions. Forecasts reflect documented feedstock slate shifts and emission credit eligibility criteria. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down schedules or IRA 45Q credit permanence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Adipic Acid Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
India Iodine Market