
 Europic Chloride Market | 2026-2036
Europic Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Europic Chloride Market Insights
Pharmaceutical-grade specification tiers is bifurcating the Europic Chloride Market into premium and industrial supply streams. Olin Corporation leverages its integrated chlor-alkali platform to sustain cost advantages in bulk chloride precursors. Shin-Etsu Chemical Co., Ltd. anchors the high-purity segment through advanced rare-earth separation capabilities. American Elements specializes in custom synthesis for research and aerospace clients, competing on specification breadth rather than volume.
Europic chloride is a rare-earth halide salt with the chemical formula EuCl₃, typically synthesized through direct chlorination of europium oxide or reduction of europium metal with hydrogen chloride; it serves primarily as a precursor for europium-doped phosphors in lighting and display technologies. The product type dimension shows calcium chloride and magnesium chloride occupying mature, volume-driven positions where margin compression is routine, while sodium chloride and potassium chloride attract premium pricing in de-icing and chemical synthesis applications. The end use industry split reveals oil and gas and water treatment as established demand basins, with construction and food processing offering faster growth but smaller absolute volumes.
REACH registration requirements and ECHA substance evaluation protocols govern europic chloride import and formulation within the European Union, compelling suppliers to maintain exhaustive toxicity and exposure documentation. The EU Green Deal's chemical sustainability targets are pushing phosphor manufacturers toward closed-loop rare-earth recovery, indirectly tightening feedstock specifications for virgin europic chloride. Stakeholders must monitor how ECHA's evolving restriction proposals for chlorinated compounds interact with critical raw material security designations for europium.
Market Dynamics
Europic chloride procurement is tightening around REACH-mandated purity thresholds that now separate qualified from marginal suppliers across the European Union. Specialty phosphor manufacturers in Germany's chemical corridor are consolidating their supplier base to secure compliant feedstock.
Growth Catalysts
- Rare-earth phosphor expansion:Display and LED lighting manufacturers are scaling europium-doped phosphor production, directly lifting precursor demand for high-purity EuCl₃.
- REACH compliance elevation:ECHA substance evaluation protocols are disqualifying lower-grade imports, creating protected demand pockets for registered suppliers.
- Hydrogen chloride reduction methods:Advanced chlorination techniques are improving yield rates and reducing oxide contamination in final product streams.
Market Restraints
- Europium ore concentration:Raw material sourcing concentrates in limited mining jurisdictions, exposing processors to geopolitical supply interruptions.
- Chlor-alkali input volatility:Energy-intensive chlorine production creates margin pressure that propagates through the europic chloride value chain.
- Phosphor recycling loops:Closed-loop rare-earth recovery systems under EU Green Deal targets are reducing virgin feedstock requirements for established applications.
Strategic Opportunities
- Medical imaging phosphors:Radiography and CT scintillator manufacturers are qualifying europium-activated compounds for next-generation detector arrays.
- Research-grade custom synthesis:Aerospace and defense laboratories are contracting bespoke EuCl₃ specifications outside standard industrial tiers.
- Battery electrolyte exploration:Solid-state battery developers are testing europium halides for ionic conductivity enhancement in prototype cells.
Industry Challenges
- Analytical certification timelines:ECHA registration dossiers require extensive toxicological data that delays market entry for new production batches.
- High-purity separation expertise:Rare-earth separation chemistry specialization is concentrated among aging technical workforces in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europic Chloride Market |
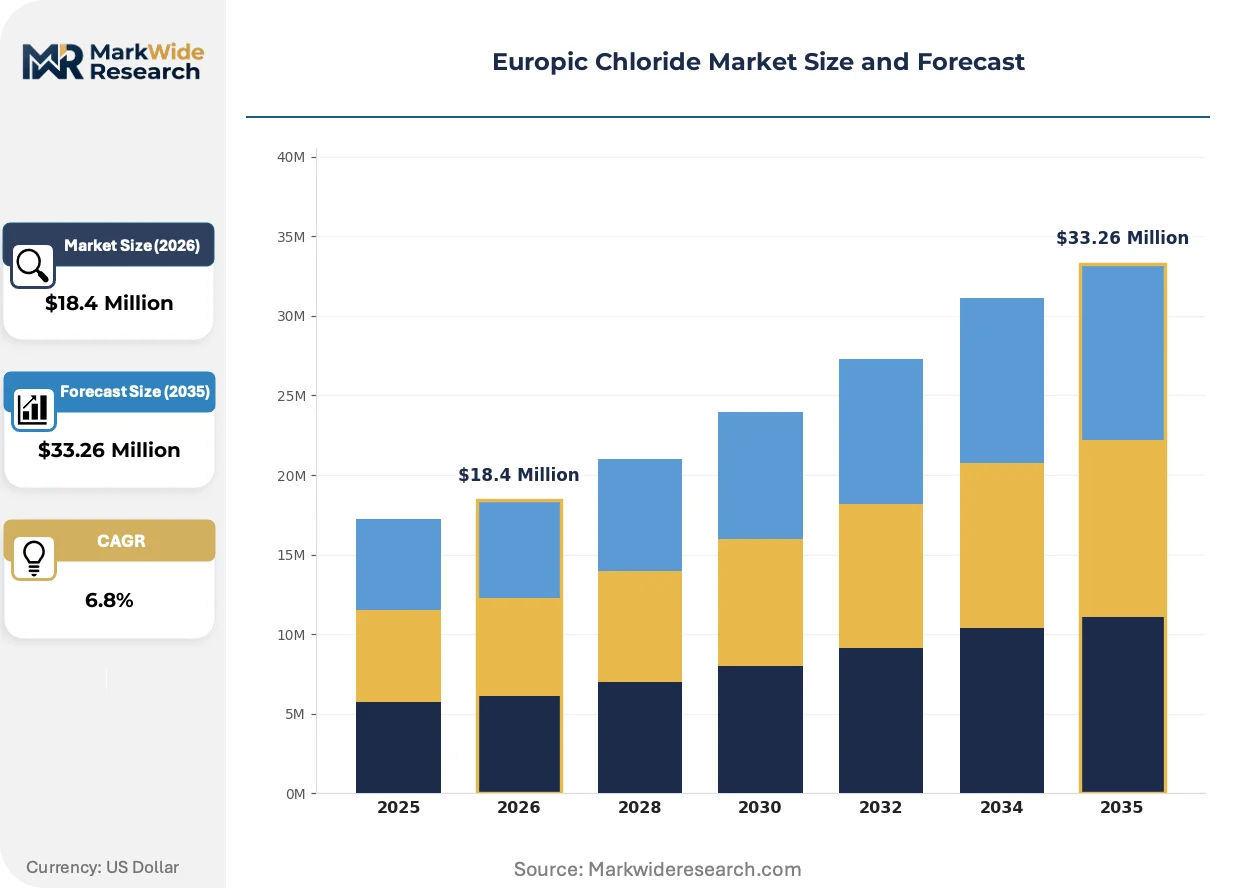
| Market Size in 2026 | $18.4 Million |
| Market Size in 2035 | $33.26 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Chloride, Magnesium Chloride, Sodium Chloride, Potassium Chloride End Use Industry: Construction, Food Processing, Oil & Gas, Water Treatment Packaging Type: Bulk Bags, Drums, Pallets, Bags Application: De-icing, Dust Control, Chemical Production, Agriculture |
| Companies Covered | Olin Corporation, Westlake Chemical Corporation, Shin-Etsu Chemical Co., Ltd., BASF SE, Solvay S.A., American Elements, TCI Chemicals Pvt. Ltd., Sigma-Aldrich, Stanford Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europic Chloride Market Trends and Innovations
Solvent extraction and ion exchange purification methods are advancing rapidly, enabling producers to meet tightening specification windows without proportionate cost escalation. These technical shifts are redrawing competitive boundaries between integrated chlor-alkali operators and specialized rare-earth processors.
Membrane-based chloride purification is supplanting traditional fractional crystallization in high-purity europic chloride production. Specialty phosphor manufacturers in Germany and Japan are adopting membrane systems to achieve sub-ppm contamination levels. This technology is compressing the viable supplier base to operators with capital-intensive separation infrastructure.
ECHA's evolving restriction proposals for chlorinated compounds are intersecting with critical raw material security designations for europium under EU industrial policy. Phosphor formulators are preemptively documenting supply chain resilience plans to defend against potential dual-use classification. The regulatory friction is most acute for importers lacking EU-based toll processing arrangements.
Specification-driven supplier consolidation is concentrating procurement decisions among fewer technical buyers with direct laboratory relationships. Research institutions and aerospace contractors are bypassing traditional distribution channels to contract directly with synthesis specialists. This pattern is most pronounced in North American and German procurement offices where custom purity certificates are mandatory.
Europic Chloride Market Segmentation
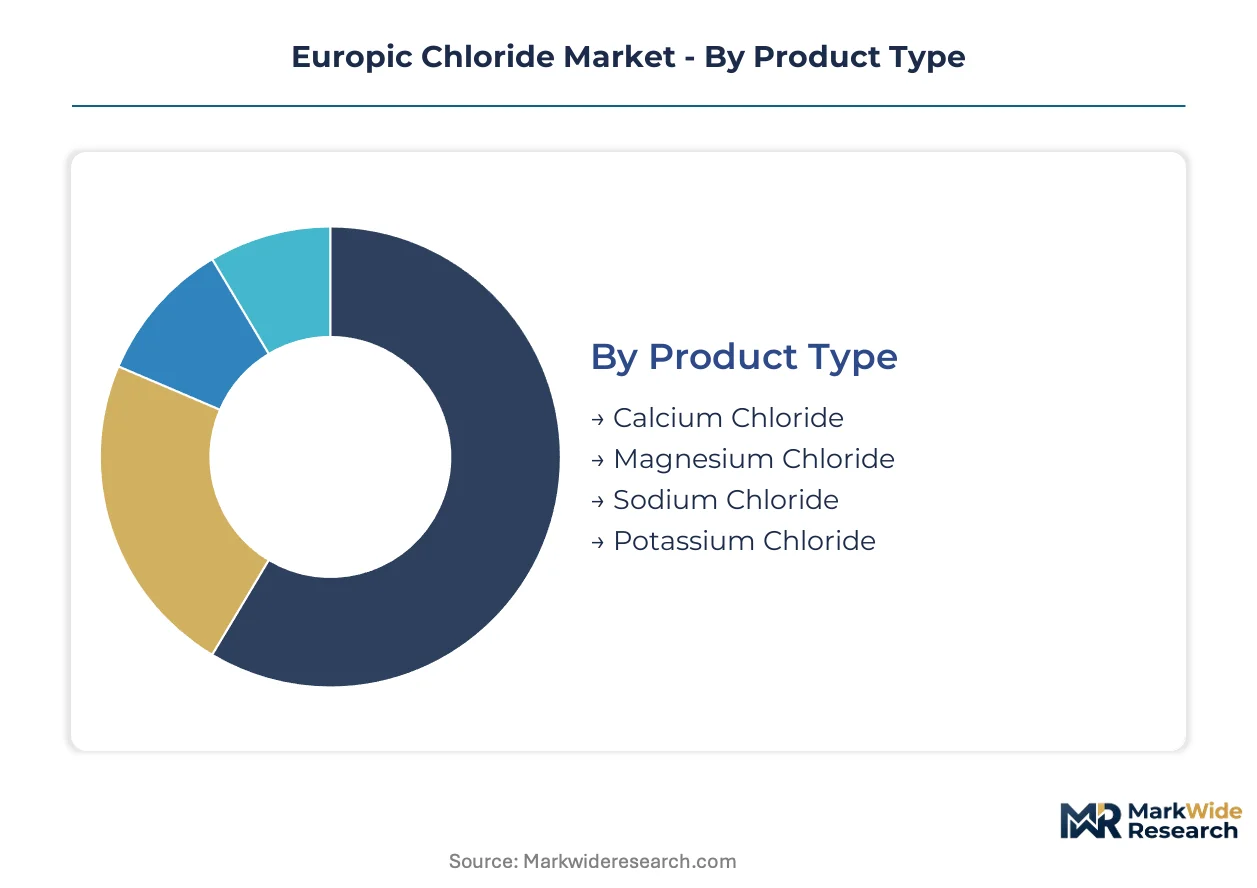
Europic chloride procurement patterns diverge sharply across specification tiers, with REACH-mandated purity thresholds creating distinct supply channels for phosphor manufacturers versus industrial chemical processors. Segmentation clarity enables buyers to map technical requirements against qualified supplier capabilities.
Product Type:
REACH registration tiers separate pharmaceutical-grade specifications from industrial feedstock categories, with ECHA substance evaluation protocols creating compliance moats around higher-purity segments.
- Calcium Chloride:Dihydrate and anhydrous grades dominate volume procurement for de-icing and dust suppression applications. German municipal authorities in Hesse and Bavaria specify technical-grade calcium chloride for winter road maintenance, with purity requirements tightening under EU environmental discharge regulations.
- Magnesium Chloride:Hexahydrate crystals and flake forms serve dust control and de-icing markets where lower corrosivity offsets premium pricing. French and Belgian highway authorities are consolidating magnesium chloride contracts around suppliers with ECHA-registered production facilities.
- Sodium Chloride:Refined vacuum salt grades command premium positioning in food processing and chemical synthesis.
- Potassium Chloride:Agricultural and industrial grades compete on chloride content and contaminant profiles.
Calcium chloride handles the majority of throughput; magnesium chloride is expanding most quickly on share as corrosion-sensitive infrastructure applications multiply.
End Use Industry:
Application maturity drives margin differentiation, with established sectors absorbing volume volatility while emerging segments absorb specification premiums.
- Oil & Gas:Drilling fluid formulations and completion brines consume high-volume chloride salts where density and compatibility specifications dominate procurement criteria. North Sea operators in Norwegian and UK waters are qualifying lower-grade calcium chloride for wellbore stabilization, with supply contracts tied to spot crude differentials.
- Water Treatment:Softening and disinfection applications demand food-grade sodium chloride certifications. Italian and Spanish municipal water utilities are consolidating procurement around suppliers with ISO 22000 documentation, creating protected positions for certified processors.
- Construction:Concrete acceleration and soil stabilization drive seasonal demand spikes.
- Food Processing:Curing, preservation, and flavoring applications require pharmacopoeia-grade certifications.
Oil & gas absorbs the greatest absolute volume; water treatment is climbing the fastest as infrastructure replacement cycles accelerate.
Packaging Type:
Logistics configuration determines supplier radius, with bulk formats favoring integrated producers and unitized packaging enabling distributor intermediation.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate construction and municipal de-icing procurement. German chemical distributors in the Rhine-Ruhr corridor operate bulk bagging lines that toll-process chlor-alkali output for regional construction markets.
- Drums:Steel and fiber drums serve laboratory, pharmaceutical, and specialty chemical customers requiring lot traceability and contamination control. French fine chemical manufacturers near Lyon specify drum packaging for GMP-documented supply chains.
- Pallets:Unitized shrink-wrapped configurations support retail and light industrial distribution.
- Bags:25-50kg woven polypropylene bags serve agricultural and consumer de-icing markets.
Bulk bags move the greatest tonnage; drums are gaining share fastest as specification documentation requirements intensify.
Application:
Seasonal demand patterns and regulatory exposure create divergent risk profiles across end-use applications.
- De-icing:Road salt and liquid brine applications concentrate demand in Nordic and Alpine geographies with extended frost periods. Swedish and Finnish transport agencies are piloting pre-wetted magnesium chloride systems that reduce chloride runoff while maintaining friction coefficients.
- Chemical Production:Chlor-alkali feedstock and organic synthesis applications require consistent purity and reliable rail or pipeline delivery. Dutch chemical clusters in Rotterdam and Geleen source sodium chloride via barge from North Sea evaporite deposits.
- Dust Control:Mining haul roads and unpaved surfaces drive summer-season magnesium chloride demand.
- Agriculture:Fertilizer blending and animal nutrition applications favor potassium chloride sourcing.
De-icing commands the largest seasonal volume; chemical production is advancing fastest as European chlor-alkali capacity restructures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances favor European Union destinations for high-purity europic chloride, while Asian production centers supply volume-grade material to industrial processors. Germany maintains a structural deficit in rare-earth halides, sourcing specialized grades from toll processors in Japan and the United States. Chinese export licensing for europium compounds creates intermittent supply tightness that European phosphor manufacturers hedge through long-term offtake contracts.
Germany
Phosphor manufacturers along the Frankfurt-Ludwigshafen chemical corridor consume the majority of EU-imported europic chloride for LED and display applications. REACH registration requirements under ECHA protocols disqualify non-registered suppliers from qualifying for specialty chemical procurement. The Rhine-Main metropolitan cluster hosts three major rare-earth formulation facilities that toll-process imported EuCl₃ into phosphor precursors.
Japan
Domestic rare-earth separation expertise supports captive production of high-purity europic chloride for domestic phosphor and scintillator manufacturers. METI industrial policy designates europium as a critical raw material, triggering stockpiling mandates that buffer supply interruptions. The Kansai region around Osaka concentrates advanced ceramic and phosphor R&D facilities that specify sub-ppm contamination thresholds.
United States
Research institutions and aerospace contractors drive demand for custom-synthesis europic chloride outside standard industrial grades. EPA TSCA reporting requirements govern import volumes for unregistered chemical substances, creating documentation burdens for small-batch procurement. The Southwestern rare-earth belt in Texas and California hosts emerging separation facilities that could reduce import dependence for domestic phosphor manufacturers.
China
State-controlled rare-earth processing enterprises dominate global europium oxide feedstock supply, constraining downstream chloride production economics for non-integrated processors. MIIT production quotas on heavy rare-earth elements directly limit europium availability for export-oriented chloride manufacturers. The Jiangxi and Inner Mongolia mining districts supply concentrate to chlor-alkali integrated facilities in the Yangtze River Delta.
India
Specialty chemical importers in Maharashtra and Gujarat distribute technical-grade europic chloride to research institutions and emerging phosphor formulators. CDSCO import licensing for pharmaceutical-grade rare-earth compounds creates regulatory friction for high-purity procurement. The Mumbai-Pune industrial corridor hosts toll-processing arrangements that re-export refined material to Middle Eastern and African markets.
Europic Chloride Market Competitive Landscape
Concentration sits with integrated chlor-alkali operators and specialized rare-earth processors that command distinct positions in the value chain. The supplier base stratifies across three tiers: bulk chemical conglomerates with captive chlorine supply, rare-earth separation specialists with purification expertise, and custom synthesis houses serving specification-intensive niches. Strategic moves center on backward integration into rare-earth oxide feedstock and forward integration into phosphor formulation partnerships.
Within the integrated chemical tier, Olin Corporation and Westlake Chemical Corporation exemplify scale-driven positions anchored by chlor-alkali infrastructure. Shin-Etsu Chemical Co., Ltd. occupies a specialist position representing advanced rare-earth separation capabilities. American Elements sits within the custom synthesis archetype, serving research and aerospace procurement channels that prioritize specification breadth over volume scale.
| Leading Market Players |
|---|
| Olin Corporation |
| Westlake Chemical Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| BASF SE |
| Solvay S.A. |
| American Elements |
| TCI Chemicals Pvt. Ltd. |
| Sigma-Aldrich |
| Stanford Advanced Materials |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory buffers at German phosphor manufacturers signal supply-chain rigidity that amplifies pricing power for REACH-registered europic chloride suppliers. This lead-time concentration creates asymmetric leverage where certified producers capture premium spreads while marginal suppliers face exclusion from specialty chemical procurement channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the europic chloride value chain. Pricing stratifies across pharmaceutical-grade, technical-grade, and industrial feedstock tiers, with REACH certification status and volume scale serving as the primary differentiation drivers. Cost compression in bulk chloride precursors is intensifying because integrated chlor-alkali operators leverage captive chlorine supply. Research institutions and aerospace contractors exhibit the lowest price sensitivity, while municipal de-icing procurement offices demonstrate acute responsiveness to unit cost fluctuations.
Supply Chain Analysis
Extended analytical certification timelines—often spanning twelve to eighteen months for ECHA dossier approval—constrain working capital velocity for new market entrants. Raw material sourcing concentrates in Chinese rare-earth mining districts, Japanese separation facilities, and German toll-processing corridors, with europium oxide feedstock, hydrogen chloride reagents, and membrane purification equipment serving as critical input dependencies. Single-source vulnerability around Chinese export licensing for europium compounds exposes European phosphor manufacturers to geopolitical supply interruptions. Distribution runs through integrated chemical distributors in the Rhine-Ruhr corridor and direct laboratory relationships for custom synthesis tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical certification services and analytical documentation packages represent a recurring-revenue layer expanding faster than base chemical sales, as REACH compliance complexity drives sustained demand for regulatory support.
For Market Incumbents: Shield market position by deepening backward integration into rare-earth oxide feedstock through toll-processing arrangements in Japan or the United States, and accelerate certification investment to preempt ECHA restriction proposals for chlorinated compounds. Emerging rare-earth recovery technologies from phosphor recycling loops threaten virgin feedstock demand, making upstream control essential for margin defense. For New Entrants and Emerging Players: ECHA registration fast-tracks for pre-existing substance dossiers offer the most viable entry pathway for qualified suppliers. Target medical imaging phosphor manufacturers in Germany and Japan, where sub-ppm contamination specifications and limited qualified supplier bases create protected demand pockets. A go-to-market strategy centered on direct laboratory relationships with research institutions bypasses entrenched distribution channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized rare-earth separation capabilities or stranded chlor-alkali assets in European industrial corridors. Long-term viability hinges on positioning within closed-loop rare-earth recovery ecosystems mandated by EU Green Deal targets. Monitor ECHA substance evaluation timelines as the critical inflection signal—accelerated restriction proposals would compress the viable supplier base and revalue incumbent certification assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Oxide Feedstock | Captive europium supply from Chinese or Australian mining jurisdictions insulates margin from export quota volatility. |
| REACH Registration Acceleration | ECHA dossier completion before restriction proposal windows secures protected supplier status for specialty chemical procurement. |
| Membrane Purification Technology Deployment | Sub-ppm contamination capability from Japanese or German engineering partners qualifies supply for medical imaging phosphors. |
| Long-term Supply Agreement with Phosphor Manufacturers | Frankfurt-Ludwigshafen corridor offtake contracts hedge against spot market tightness from Chinese export licensing. |
| Joint Venture for Closed-Loop Rare-Earth Recovery | EU Green Deal-aligned recycling partnerships with LED display OEMs secure preferred virgin feedstock positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews, with phosphor formulation chemists, chlor-alkali plant managers, rare-earth procurement leads at specialty chemical distributors, and ECHA regulatory affairs specialists providing operational perspective. Secondary validation drew from customs trade data, ECHA substance evaluation protocols, SEC filings of integrated chemical producers, and Cefic industry reports. Bottom-up volume estimates from application-specific consumption rates were triangulated against top-down market sizing from production capacity and trade flow analysis.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning purity grade tiers, end-use industry clusters, packaging format configurations, and regional regulatory compliance status. CAGRs were derived from trend extrapolation of phosphor production growth, chlor-alkali capacity utilization patterns, and substitution elasticity estimates for rare-earth recovery systems. Forecast inputs incorporated ECHA regulatory timeline assumptions and Chinese MIIT production quota trajectories for europium compounds.
Decision-makers should treat outputs as directional under sustained REACH enforcement intensity and stable Chinese export licensing regimes; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market