
 Epoxy Curing Agents Market | 2026-2036
Epoxy Curing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Curing Agents Market Analysis
Specialty chemical distribution is tilting toward direct technical service partnerships between curing agent producers and large coating formulators. Huntsman Corporation leverages its integrated epoxy systems expertise to sustain long-term supply agreements with wind energy OEMs. Kukdo Chemical Co., Ltd. anchors its position through backward integration into amine intermediates, while Evonik Industries AG differentiates via high-purity specialty amines for electronics-grade applications.
Epoxy curing agents are reactive hardeners that cross-link epoxy resins through polyaddition reactions, typically requiring precise stoichiometric ratios and controlled exotherm profiles to achieve target glass transition temperatures above 120°C for structural composites. Their primary purpose is to transform liquid epoxy prepolymers into thermoset networks with defined mechanical, chemical, and thermal properties for industrial bonding and protection. Amine-based curing agents dominate volume consumption in construction and marine coatings due to room-temperature cure flexibility, while anhydrides command premium positioning in electrical laminates and aerospace composites where thermal stability and low dielectric loss are non-negotiable. UV curing technology is expanding fastest in electronics assembly and automotive refinish, driven by line-speed productivity and energy reduction relative to thermal oven systems.
EPA regulations in the United States enforce stringent VOC limits under National Emission Standards for Hazardous Air Pollutants, forcing coating manufacturers to reformulate toward waterborne and high-solids epoxy systems with compliant curing chemistries. REACH registration requirements and the EU Green Deal's carbon border adjustments are reshaping raw material sourcing decisions for European producers, while China's MEE enforces dual carbon goals that tighten emissions permits at amine manufacturing facilities. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation costs and qualify alternative curing technologies before compliance deadlines harden.
Market Dynamics
REACH compliance deadlines and EU Green Deal carbon border adjustments are forcing epoxy curing agent producers to reformulate entire product portfolios, while China's state-backed infrastructure pull concentrates demand in specific regional manufacturing clusters.
Growth Catalysts
- Wind turbine blade manufacturing:OEMs are specifying high-performance amine curing systems for longer offshore blades requiring glass transition temperatures above 140°C.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment emissions permits are accelerating consolidation at domestic amine facilities, favoring compliant suppliers.
- UV curing line-speed gains:Electronics assemblers are replacing thermal oven systems with UV-curable epoxies to reduce energy consumption and floor space.
Market Restraints
- Propylene oxide feedstock volatility:Aliphatic amine production costs fluctuate with propylene derivative pricing, compressing margin stability for formulators.
- Specialty amine supply concentration:High-purity cycloaliphatic and aromatic amine intermediates remain concentrated among integrated chemical producers in Germany and Japan.
- Anhydride handling limitations:Solid anhydride curing agents require heated storage and moisture-controlled environments, restricting adoption in humid climates.
Strategic Opportunities
- India construction coatings penetration:BIS certification requirements for industrial protective coatings are creating qualified supplier gaps that specialty amine producers can fill.
- Waterborne epoxy conversion:EPA NESHAP VOC limits are pushing automotive refinish shops toward waterborne systems requiring compatible modified amine hardeners.
- Direct technical service partnerships:Large coating formulators are bypassing distributors to secure captive R&D support from curing agent producers.
Industry Challenges
- Stoichiometric formulation expertise gap:Compounders lack technicians trained in precise amine-epoxy ratio calculations for high-Tg aerospace laminates.
- REACH registration timeline compression:ECHA data requirements for novel amine structures extend commercialization cycles by 18-24 months.
- Legacy solventborne system integration:Coating manufacturers face retrofit costs when adapting existing production lines for high-solids or waterborne curing chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Curing Agents Market |
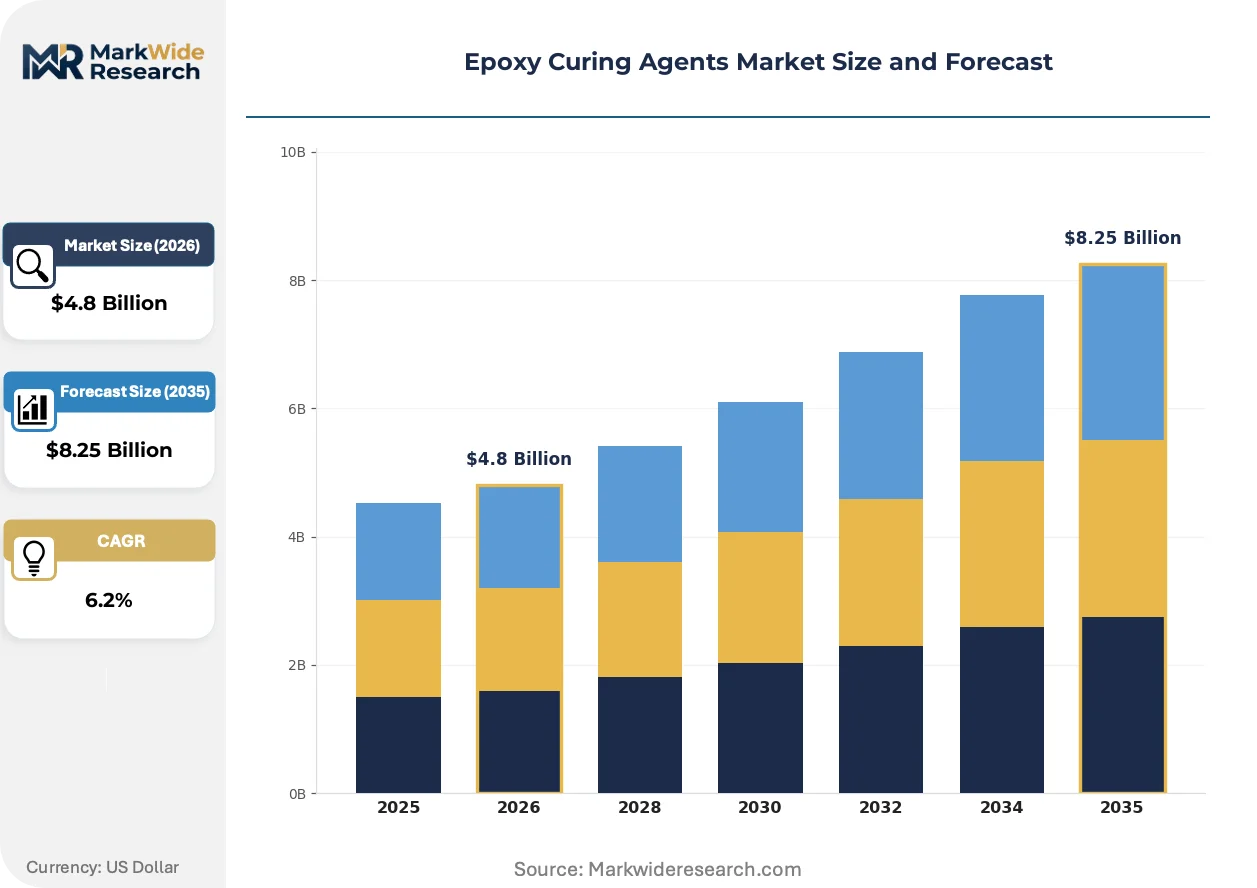
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amines, Anhydrides, Aromatics, Others End Use Industry: Construction, Automotive, Electronics, Aerospace Curing Technology: Thermal Curing, UV Curing, Ambient Curing, Hybrid Curing Form: Liquid, Solid, Gel, Powder |
| Companies Covered | Cardolite Corporation, Kukdo Chemical Co., Ltd., Huntsman Corporation, Aditya Birla Chemicals, Westlake Epoxy, Evonik Industries AG, BASF SE, Gabriel Performance Products, Olin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Curing Agents Market Emerging Trajectories
Digital formulation tools and accelerated curing technologies are compressing product development cycles while regulatory pressure drives chemistry innovation toward lower-exposure systems.
Additive manufacturing of composite tooling is virtualizing traditional mold fabrication for epoxy-based aerospace components. Tier-1 suppliers are adopting photopolymerizable epoxy resins with cationic curing mechanisms to produce sacrificial tooling inserts overnight rather than machining aluminum masters over weeks. This shift is virtualizing capital equipment requirements and reducing lead times for prototype turbine blade root fittings.
REACH authorization requirements for certain cycloaliphatic diamines are forcing European formulators to qualify bio-based amine alternatives derived from cashew nutshell liquid. ECHA's SVHC candidate list expansion is triggering supply chain audits across coating manufacturers serving the Netherlands and Belgium. Marine protective coating producers are responding by accelerating validation of cardanol-modified phenalkamine curing agents for tank lining applications.
Large wind energy OEMs are consolidating their curing agent supply base from twelve qualified suppliers to four preferred partners with integrated technical service capabilities. Direct long-term agreements are displacing spot purchasing through regional distributors for blade manufacturing facilities in Denmark and Spain. This concentration is most visible in Northern Europe, where Vestas and Siemens Gamesa operations have shifted procurement toward full-system suppliers offering epoxy resin-curing agent-ancillary packages.
Epoxy Curing Agents Market Segmentation
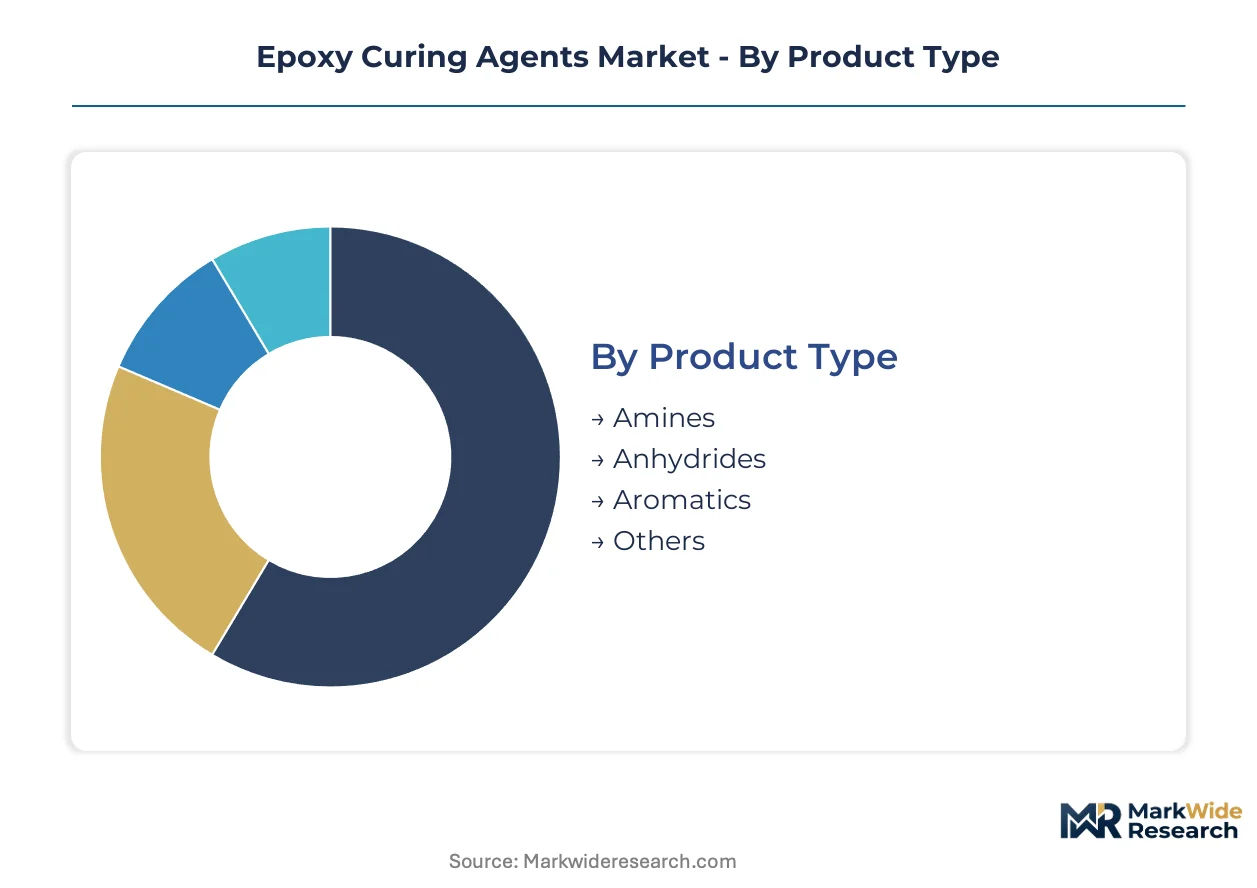
Epoxy curing agent segmentation reflects divergent technical requirements across protective coatings, structural composites, and electronic assemblies. Each dimension—chemistry, application, curing mechanism, and physical form—carries distinct supply chain and formulation implications for producers and compounders.
Product Type:
Mature amine chemistries dominate volume consumption while specialty anhydrides command premium positioning in performance-critical applications.
- Amines:Aliphatic and cycloaliphatic amines constitute the backbone of room-temperature curing systems for construction and marine coatings. Demand concentrates in China, where state-backed infrastructure programs pull through high volumes of standard-grade formulations despite MEE emissions permit tightening at domestic manufacturing facilities.
- Anhydrides:These latent hardeners enable controlled exotherm profiles and elevated glass transition temperatures exceeding 150°C. Electrical laminate producers in Japan specify methyl tetrahydrophthalic anhydride for high-frequency circuit boards where low dielectric loss is mandatory.
- Aromatics:Aromatic amine curing agents deliver superior thermal stability and chemical resistance for chemical processing equipment linings.
- Others:Phenalkamines and polyamide adducts serve niche applications requiring extended pot life or underwater cure capability.
Amines retain volume leadership; anhydrides hold the steepest expansion curve.
End Use Industry:
Application-driven segmentation separates commodity protective coatings from specification-grade aerospace and electronics systems.
- Construction:Infrastructure protective coatings and flooring systems consume the largest amine volumes globally. India's BIS certification requirements for industrial protective coatings are creating qualified supplier gaps that specialty amine producers can exploit.
- Automotive:OEM clearcoats and refinish systems drive demand for low-VOC compatible hardeners. EPA NESHAP enforcement is pushing US refinish shops toward waterborne epoxy-amine systems with compliant curing chemistries.
- Electronics:Encapsulation and underfill applications require ultra-low ionic purity amines. South Korean semiconductor packaging facilities specify electronic-grade cycloaliphatic diamines for advanced flip-chip assemblies.
- Aerospace:Primary structural composites and tooling applications specify anhydride and aromatic amine systems with extensive qualification protocols.
Construction commands absolute volume; electronics demonstrates the most rapid technology turnover.
Curing Technology:
Thermal systems anchor established manufacturing while UV and ambient alternatives reshape processing economics.
- Thermal Curing:Oven-based polymerization remains standard for automotive OEM coatings and aerospace prepregs. German automotive suppliers maintain capital-intensive thermal lines for epoxy powder coating applications on chassis components.
- UV Curing:Photoinitiated cationic polymerization enables line-speed productivity gains and 70% energy reduction versus thermal systems. Electronics assemblers in Taiwan are replacing batch oven processes with UV-curable epoxy dispensing for smartphone camera module bonding.
- Ambient Curing:Room-temperature amine-epoxy reactions dominate field-applied construction coatings and marine maintenance.
- Hybrid Curing:Dual-cure systems combining thermal and UV mechanisms accommodate complex geometries with shadow areas.
Thermal curing retains installed base dominance; UV systems are climbing the fastest.
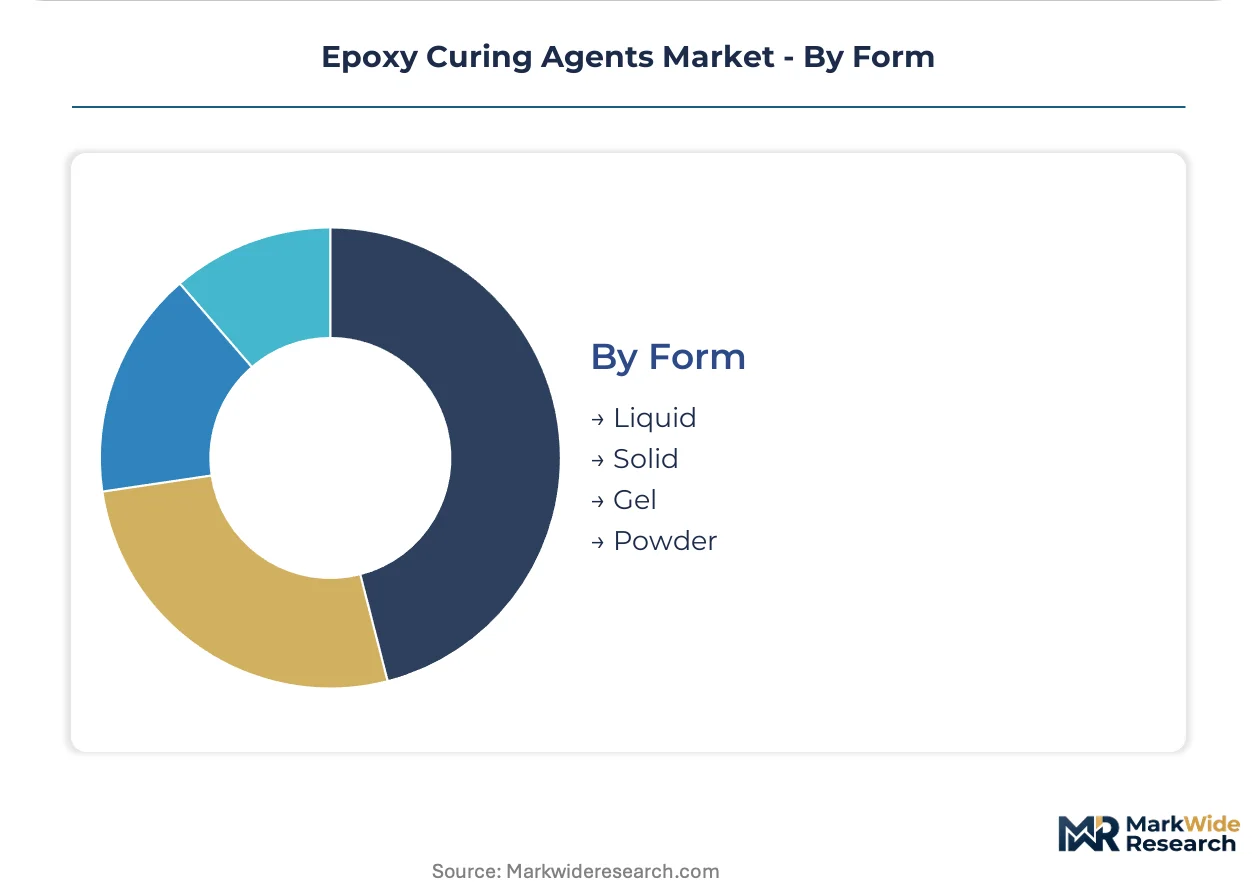
Form:
Physical state determines handling infrastructure, storage requirements, and formulation latitude for compounders.
- Liquid:Low-viscosity amines and reactive diluents enable spray application and high-solids formulation. US Gulf Coast coating manufacturers prefer liquid systems for automated plural-component spray equipment in offshore platform maintenance.
- Solid:Powdered anhydrides and blocked amines provide extended shelf stability and precise metering. Japanese electrical laminate producers utilize solid dicyandiamide latent hardeners for B-stage prepreg manufacturing.
- Gel:Thixotropic formulations support vertical surface application and trowel-grade flooring systems.
- Powder:Dry-blend hardeners serve powder coating compounding and specific aerospace adhesive film applications.
Liquid forms dominate formulation flexibility; solid forms are gaining share fastest in automated compounding operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deep-water port infrastructure underwrites China's dominance in epoxy curing agent throughput, while Hamburg's container terminals anchor European chemical distribution networks for amine intermediates.
China
State-backed infrastructure programs in Jiangsu and Shandong provinces drive sustained consumption of aliphatic amines for construction coatings. MEE dual carbon enforcement has tightened emissions permits at amine manufacturing facilities in Ningbo and Tianjin, accelerating consolidation toward compliant producers. The Yangtze River Delta cluster around Shanghai concentrates domestic epoxy resin capacity expansions that pull through captive curing agent volumes.
United States
Gulf Coast offshore platform maintenance and automotive refinish operations sustain demand for low-VOC compatible hardeners. EPA NESHAP regulations under the Clean Air Act mandate reformulation timelines that push coating manufacturers toward waterborne epoxy systems. Houston-area chemical distributors maintain automated plural-component spray equipment infrastructure serving energy sector protective coatings.
Germany
Electrical laminate producers in Bavaria and Baden-Württemberg specify methyl tetrahydrophthalic anhydride for high-frequency circuit board applications. REACH authorization requirements and ECHA SVHC candidate list expansions trigger supply chain audits across coating manufacturers serving the Ruhr industrial corridor. Frankfurt's logistics hub facilitates just-in-time delivery of high-purity cycloaliphatic diamines to electronics assemblers.
India
Infrastructure investment in Maharashtra and Gujarat generates qualified supplier gaps for industrial protective coatings requiring BIS certification. The central government's PLI scheme for specialty chemicals incentivizes domestic amine intermediate production. Mumbai-Pune manufacturing belt coating formulators seek technical partnerships with curing agent producers to navigate compliance complexity.
Japan
Semiconductor packaging facilities in Kyushu and the Kanto region specify electronic-grade cycloaliphatic diamines for advanced flip-chip assemblies. METI industrial standards enforce ultra-low ionic purity thresholds for encapsulation applications. Osaka-based electrical laminate producers utilize solid dicyandiamide latent hardeners for B-stage prepreg manufacturing serving regional circuit board demand.
Epoxy Curing Agents Market Vendor Landscape
On the supply side, the industry is structured around integrated chemical conglomerates with captive amine intermediate production and specialized hardener formulators serving specification-grade applications. Three archetypes dominate: petrochemical majors with backward integration into propylene derivatives, mid-cap specialists focused on cycloaliphatic and aromatic amine purity grades, and regional compounders distributing standard aliphatic formulations. Capacity expansion and direct technical service partnerships constitute the primary competitive vectors as large coating formulators bypass traditional distribution channels.
Within the integrated systems tier, Huntsman Corporation and Evonik Industries AG exemplify divergent specialization strategies—Huntsman leveraging full epoxy-curing agent-ancillary packages for wind energy OEMs, Evonik occupying a position anchored on high-purity specialty amines for electronics-grade applications. Kukdo Chemical Co., Ltd. represents the Asian integrated model with upstream control over amine intermediates.
| Leading Market Players |
|---|
| Cardolite Corporation |
| Kukdo Chemical Co., Ltd. |
| Huntsman Corporation |
| Aditya Birla Chemicals |
| Westlake Epoxy |
| Evonik Industries AG |
| BASF SE |
| Gabriel Performance Products |
| Olin Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta amine intermediate plants is compressing spot pricing for standard-grade aliphatic curing agents while tightening margins for non-integrated producers. This utilization imbalance simultaneously rewards backward-integrated suppliers with captive propylene derivative supply and pressures independent formulators to absorb feedstock volatility or cede volume.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electronic-grade cycloaliphatic diamines from construction-grade aliphatic formulations and commodity phenalkamine blends. Price differentiation hinges on certification tier—REACH-registered specialty amines command substantial premia over non-registered alternatives—and volume scale, with wind energy OEMs securing multi-year offtake discounts. Cost compression in standard-grade aliphatics is intensifying because propylene oxide derivative supply fluctuates with refinery operating rates. Small-to-mid coating formulators exhibit acute price sensitivity, while aerospace laminators prioritize thermal stability over unit economics.
Supply Chain Analysis
Extended payment terms from large wind energy OEMs are forcing mid-tier curing agent producers to utilize supply-chain finance facilities, elevating working capital intensity across the supplier base. Manufacturing concentrates in China, Germany, and Japan, with the Yangtze River Delta, Bavaria, and Kyushu hosting integrated amine intermediate-to-hardener production. The supply chain draws from propylene oxide, ethylene oxide, and cashew nutshell liquid feedstocks. Single-source vulnerability persists for high-purity cycloaliphatic diamines qualified to semiconductor packaging standards. Distribution runs through direct technical service partnerships that displace regional distributors for large coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation expertise—particularly stoichiometric calculation capability for high-Tg aerospace laminates—represents the scarcest capability in this market, constraining expansion for compounders lacking trained technicians. This skill gap creates asymmetric returns for suppliers investing in captive technical service capacity.
For Market Incumbents: Harden supply security by deepening backward integration into amine intermediates or securing long-term propylene derivative offtake agreements, as feedstock volatility threatens margin stability for non-integrated players. Accelerate REACH registration timelines for novel bio-based amine structures to preempt ECHA authorization bottlenecks that extend commercialization cycles. For New Entrants and Emerging Players: India's BIS-certified industrial protective coatings segment represents the most penetrable entry point, given qualified supplier gaps in Maharashtra and Gujarat infrastructure projects. Waterborne epoxy conversion in US automotive refinish shops offers a second white-space target, as EPA NESHAP enforcement drives demand for compatible modified amine hardeners. Establish direct technical service partnerships with mid-tier coating formulators seeking formulation support without distributor markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic-grade specialty amine production, as ultra-low ionic purity requirements demand dedicated manufacturing assets and quality systems. Over a multi-year horizon, integrated producers with captive intermediate supply and established semiconductor packaging qualifications offer superior viability versus commodity formulators. Monitor consolidation momentum among China's Ningbo and Tianjin amine facilities under MEE dual carbon enforcement as an inflection indicator for regional supply rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Intermediates | Captive propylene derivative supply insulates margin stability from feedstock volatility. |
| Long-term Supply Agreement with Wind OEMs | Direct technical service partnerships displace spot purchasing through regional distributors. |
| Green Manufacturing Transition | Bio-based amine alternatives from cashew nutshell liquid address REACH authorization pressure. |
| Capacity Expansion in India | BIS certification requirements create qualified supplier gaps for infrastructure coatings demand. |
| Joint Venture for Electronic-Grade Production | Ultra-low ionic purity standards favor dedicated assets serving South Korean semiconductor packaging. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at amine manufacturing facilities, procurement leads at downstream coating formulators, and technical R&D directors at epoxy system suppliers; and secondary validation through customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across chemistry type, end-use industry, curing technology, and physical form dimensions.
Forecast inputs incorporated capacity utilization rates at Chinese MEE-regulated facilities, REACH registration timelines for novel amine structures, and wind energy OEM blade manufacturing schedules. Segmentation modeling spanned product chemistry tier, end-use application, curing mechanism type, and regional production hub. CAGRs were derived from regression analysis of historical consumption patterns against projected infrastructure and renewable energy deployment curves, with specific weighting for UV curing technology penetration in electronics assembly.
Practitioners should monitor propylene oxide derivative pricing volatility, ECHA SVHC candidate list expansions, and MEE emissions permit enforcement intensity for early signals requiring forecast reassessment. The analysis reflects assumptions regarding sustained wind turbine blade manufacturing expansion and continued regulatory tightening on VOC emissions. Macroeconomic contraction in construction activity, accelerated substitution by alternative curing chemistries, or divergence in regional regulatory timelines would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market