
 Middle-East and Africa Waterborne Adhesives Market | 2026-2036
Middle-East and Africa Waterborne Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Waterborne Adhesives Market Foresight
Saudi Arabia's industrial chemical corridor is narrowing the supply gap for waterborne adhesive precursors previously imported from European suppliers. Henkel AG & Co. KGaA leverages its regional compounding facilities to serve packaging converters across the Gulf. Dow anchors its position through captive acrylic emulsion supply to Egyptian construction material manufacturers. Sika AG specializes in tile adhesive and flooring applications where humidity resistance specifications are tightening.
Middle-East and Africa waterborne adhesives are aqueous polymer dispersions—typically acrylic, polyurethane, or polyvinyl acetate emulsions with solids content ranging from 40% to 60%—formulated to bond porous and non-porous substrates without volatile organic solvent carriers. These systems serve construction, packaging, and furniture assembly where indoor air quality regulations restrict solvent-based alternatives. Acrylic formulations command premium positioning in pressure-sensitive labeling and textile adhesion due to UV stability and clarity. Polyurethane emulsions represent the fastest-growing chemistry segment as automotive interior trim specifications in Morocco and South Africa shift toward heat-resistant bonding. Ethylene vinyl acetate remains volume-dominant in paper bonding and woodworking applications where cost sensitivity limits formulation flexibility.
Saudi Standards, Metrology and Quality Organization (SASO) and South Africa's National Regulator for Compulsory Specifications (NRCS) enforce VOC emission thresholds that disqualify solvent-based competitors from public infrastructure tenders. Egypt's Environmental Affairs Agency is drafting comparable limits for imported furniture and building products. REACH-aligned substance restrictions from European export markets further filter through to Gulf manufacturing standards via OEM supply chain requirements. Stakeholders must track regulatory harmonization timelines between Gulf Cooperation Council technical committees and African regional economic communities to anticipate certification burdens ahead of contract bidding cycles.
Market Dynamics
Construction procurement across Gulf Cooperation Council states is pivoting toward low-VOC bonding systems as SASO tightens emission thresholds for interior building products, compressing solvent-based alternatives from public infrastructure tenders.
Growth Catalysts
- SASO VOC Limits:Saudi Arabia's emission thresholds for interior building products disqualify solvent-based competitors from NEOM and Red Sea mega-project supply chains.
- Automotive Interior Specifications:Moroccan and South African automotive trim manufacturers are specifying heat-resistant polyurethane emulsions for cabin bonding applications.
- Packaging Converter Demand:Gulf-based flexible packaging producers are converting lines to waterborne acrylics for pressure-sensitive labeling compliant with European export market standards.
Market Restraints
- Acrylic Monomer Volatility:Feedstock price swings for butyl acrylate and 2-ethylhexyl acrylate compress formulation margins for regional compounders dependent on imported precursors.
- European Supply Concentration:Specialty polyurethane dispersion technology remains concentrated among German and Dutch licensors, limiting local production autonomy.
- Humidity Performance Ceiling:Polyvinyl acetate emulsions face technical limitations in Gulf coastal construction where sustained 85%+ relative humidity degrades bond integrity.
Strategic Opportunities
- Egyptian Furniture Export Hub:Cairo-based manufacturers serving European markets require REACH-aligned waterborne systems as the Environmental Affairs Agency drafts comparable VOC limits.
- Tile Adhesive Premiumization:Sika AG's humidity-resistant flooring specifications are creating pull for modified acrylic-urethane hybrids in Saudi residential high-rises.
- Digital Specification Platforms:Construction material distributors in Dubai and Johannesburg are launching online tender portals that filter adhesive eligibility by certification status.
Industry Challenges
- Formulation Chemist Scarcity:Gulf universities produce limited polymer science graduates capable of tuning emulsion stability for 50°C+ storage conditions.
- NRCS Certification Timelines:South Africa's National Regulator for Compulsory Specifications processes interior product approvals in 14-18 month cycles, delaying market entry.
- Legacy Solvent Infrastructure:Egyptian and Nigerian converters maintain capital-intensive solvent recovery systems that slow waterborne line conversion decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Waterborne Adhesives Market |
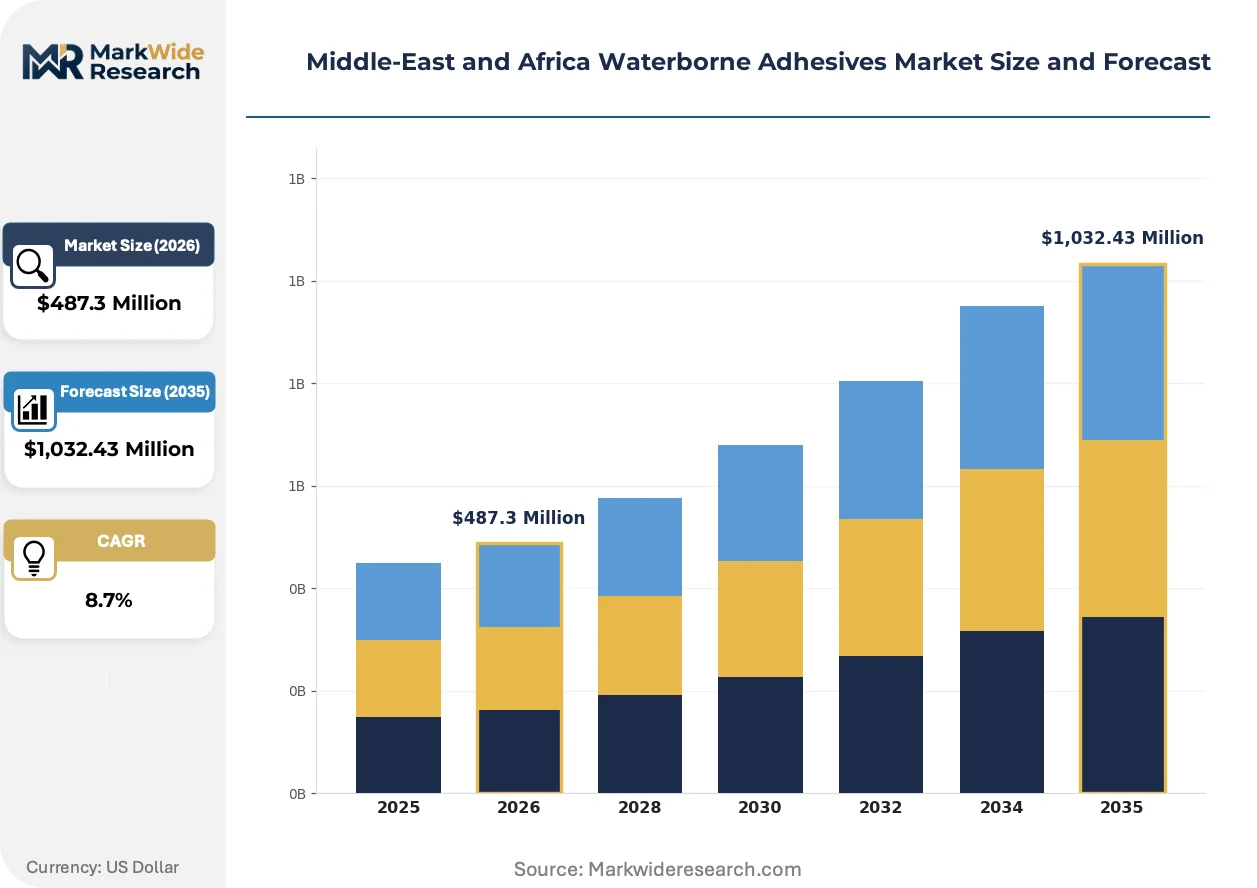
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric, Polyurethane, Acrylic, Ethylene Vinyl Acetate End User: Construction, Automotive, Packaging, Furniture Technology: Water-Based, Solvent-Based, Hot Melt, Reactive Application: Woodworking, Paper Bonding, Textile Adhesion, Labeling |
| Companies Covered | 3M, Arkema Group, Dow, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, Avery Dennison Corporation, Huntsman International, Bostik SA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Waterborne Adhesives Market Shifts & Advancements
Formulation digitization and regulatory harmonization are compressing product development cycles while procurement platforms reshape how specifications reach compounders.
Smart manufacturing systems are digitizing emulsion production workflows across Saudi Arabia's industrial chemical corridor. Regional compounders deploy inline viscosity and particle-size monitoring to reduce batch-to-batch variation. This connectivity is digitizing quality assurance protocols that previously required European technical service visits.
SASO and South Africa's NRCS are converging VOC test methodologies with REACH annex XVII restrictions. Egyptian regulators are drafting comparable limits for imported furniture. Construction material distributors now pre-qualify adhesives against multiple jurisdiction standards before stocking.
Buyer concentration in Gulf mega-projects is compressing supplier qualification timelines. NEOM and Red Sea developers issue consolidated material specifications that bundle waterborne adhesive requirements with concrete and steel standards. Tier-one contractors in Riyadh and Jeddah now maintain pre-approved product lists updated quarterly rather than annually.
Middle-East and Africa Waterborne Adhesives Market Segmentation
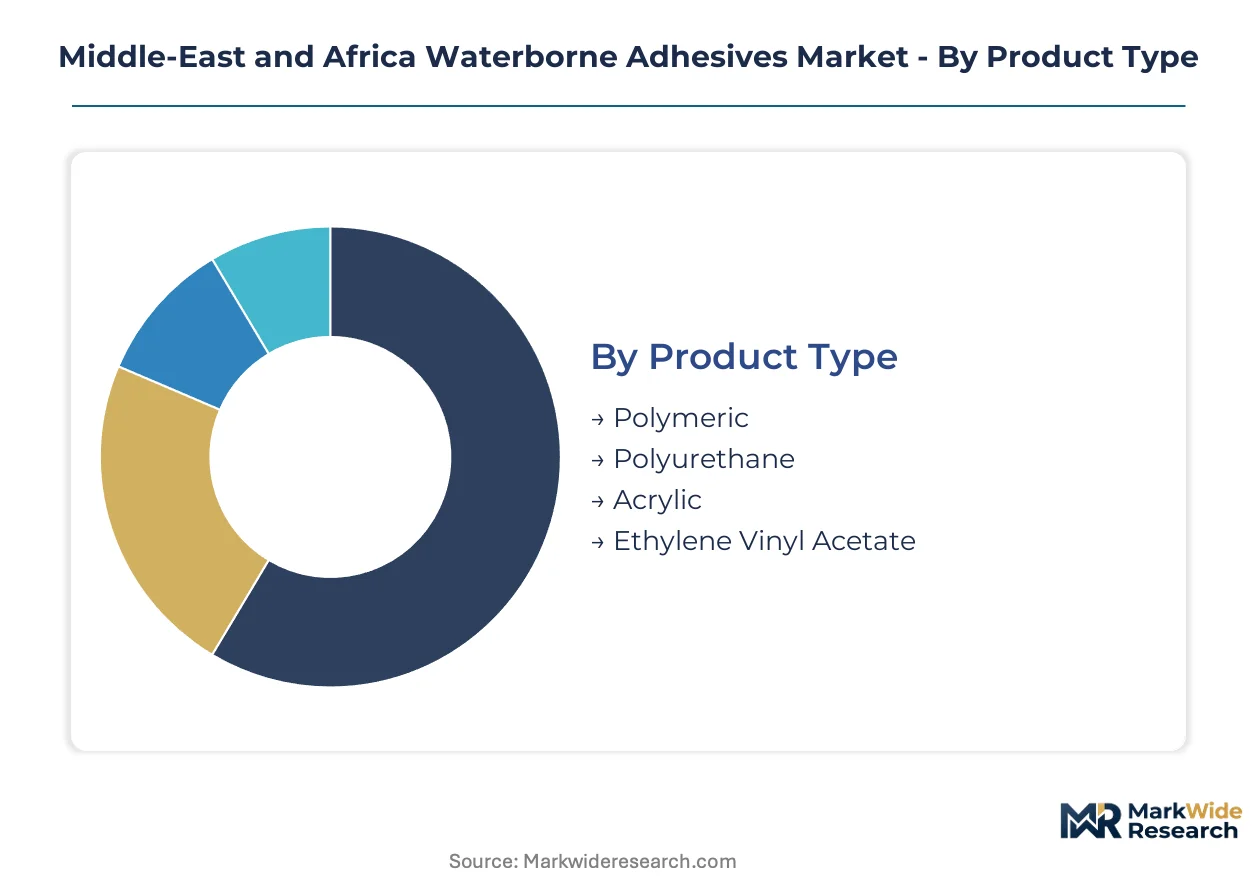
Waterborne adhesive procurement across the Middle-East and Africa fragments across chemistry families, end-use specifications, and application techniques. Each segmentation axis carries distinct certification requirements and margin profiles that compounders must navigate.
Product Type:
Mature commodity chemistries coexist with emerging specialty dispersions as regional formulators balance cost targets against performance specifications.
- Acrylic:Aqueous polymer dispersions with UV-stable backbones serve pressure-sensitive labeling and textile lamination where optical clarity matters. Saudi packaging converters specify these for European export compliance.
- Polyurethane:Heat-resistant emulsion systems with thermosetting crosslink capability bond automotive interior trim in Moroccan and South African assembly plants. SASO-aligned VOC limits accelerate displacement of solvent-based alternatives in this segment.
- Ethylene Vinyl Acetate:Cost-optimized copolymer emulsions dominate paper bonding and woodworking where humidity resistance requirements remain moderate.
- Polymeric:Broad-spectrum synthetic latex dispersions serve general-purpose construction applications across Gulf residential developments.
Ethylene vinyl acetate retains volume leadership; polyurethane holds the steepest expansion curve.
End User:
Customer concentration patterns split between project-driven construction procurement and continuous manufacturing demand from automotive and packaging operations.
- Construction:Low-VOC bonding systems for tile, flooring, and drywall applications face tightening SASO emission thresholds across NEOM and Red Sea mega-projects. Egyptian contractors now pre-qualify adhesives against REACH-aligned import standards.
- Packaging:Flexible film converters in Dubai and Jeddah specify waterborne acrylics for label stock serving European food contact regulations.
- Automotive:Cabin trim manufacturers in Casablanca and Durban specify heat-resistant polyurethane emulsions for dashboard and door panel assembly.
- Furniture:Cairo-based exporters serving EU markets require waterborne systems as Egypt's Environmental Affairs Agency drafts comparable VOC limits to REACH annex XVII.
Construction commands the largest procurement volumes; packaging offers the most standardized specification pathways.
Technology:
Formulation platforms diverge sharply on regulatory eligibility, with water-based systems gaining share as solvent-based alternatives face disqualification from public tenders.
- Water-Based:Aqueous emulsion systems with 40-60% solids content serve all regulated interior applications across Saudi Arabia and South Africa.
- Solvent-Based:Organic carrier systems face exclusion from SASO-compliant infrastructure tenders but persist in legacy Egyptian and Nigerian converter operations.
- Hot Melt:Thermoplastic adhesive blocks serve high-speed packaging lines where waterborne drying speeds limit throughput.
- Reactive:Two-component polyurethane and epoxy systems bond structural composites in specialty construction segments.
Water-based technology anchors regulatory-compliant procurement; reactive systems capture premium structural applications.
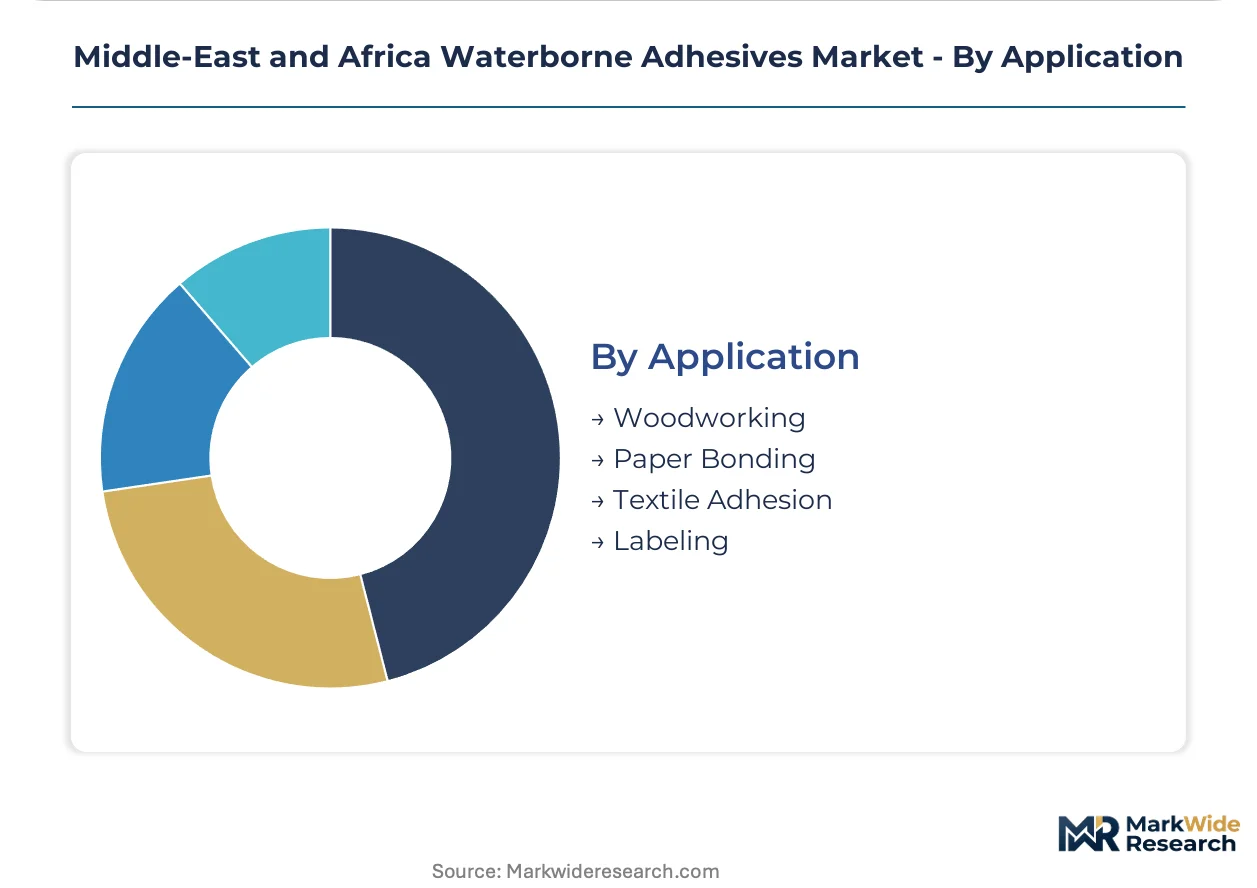
Application:
Substrate-specific performance requirements drive chemistry selection, with porous materials tolerating lower-cost formulations and non-porous surfaces demanding engineered dispersions.
- Paper Bonding:Ethylene vinyl acetate emulsions serve corrugated packaging and bookbinding where cost sensitivity limits formulation investment.
- Labeling:Pressure-sensitive acrylics with tailored tack and peel properties serve beverage and pharmaceutical packaging for European export markets.
- Woodworking:Polyvinyl acetate and ethylene vinyl acetate blends bond furniture components in Egyptian and South African manufacturing hubs.
- Textile Adhesion:Soft-hand acrylic dispersions laminate fabrics and nonwovens for automotive and apparel applications.
Paper bonding maintains the widest installed base; labeling applications generate the highest formulation premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red Sea coastal corridor anchors Saudi Arabia's procurement volumes for waterborne adhesives, with NEOM's linear city development generating concentrated demand for low-VOC bonding systems across construction phases.
Saudi Arabia
NEOM and Red Sea mega-projects drive specification pull for SASO-compliant waterborne systems in tile and flooring applications. The Saudi Standards, Metrology and Quality Organization enforces emission thresholds that disqualify solvent-based alternatives from public tenders. Yanbu's industrial chemical corridor is narrowing precursor supply gaps through localized acrylic emulsion production.
United Arab Emirates
Dubai's flexible packaging converters specify waterborne acrylics for European export compliance in pressure-sensitive labeling segments. The Emirates Authority for Standardization and Metrology aligns VOC test methodologies with REACH annex XVII restrictions. Jebel Ali's logistics hub concentrates distribution for Gulf Cooperation Council states seeking pre-qualified adhesive inventories.
South Africa
Automotive trim manufacturers in Durban specify heat-resistant polyurethane emulsions for cabin bonding applications. The National Regulator for Compulsory Specifications processes interior product approvals through 14-18 month certification cycles. Gauteng's manufacturing belt houses compounders serving furniture exporters requiring REACH-aligned formulations.
Egypt
Cairo-based furniture manufacturers serving European markets require waterborne systems as the Environmental Affairs Agency drafts comparable VOC limits. The Suez Canal Economic Zone attracts adhesive compounders seeking duty-efficient precursor imports. Alexandria's port infrastructure supports raw material flows for regional formulation operations.
Morocco
Casablanca's automotive assembly plants specify polyurethane emulsions for dashboard and door panel bonding. The country's national standards body is harmonizing test protocols with EU technical specifications. Tangier-Med port clusters concentrate logistics for Spanish and French OEM supply chain requirements.
Middle-East and Africa Waterborne Adhesives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precursor supply. The vendor base stratifies between multinational chemical conglomerates with captive emulsion technology and regional compounders dependent on imported monomer feedstocks. Three archetypes dominate: integrated resin producers, formulation specialists, and distribution-anchored blenders. Competitive moves concentrate on backward integration into acrylic monomer supply and strategic licensing of polyurethane dispersion technology.
Among European-headquartered chemical conglomerates, Henkel AG & Co. KGaA, Sika AG, and Dow occupy positions exemplifying distinct strategic archetypes. Henkel represents the integrated formulation specialist with regional compounding infrastructure. Sika anchors the construction-focused tier through humidity-resistant system specialization. Dow exemplifies the resin-integrated player with captive acrylic emulsion supply to Egyptian construction material manufacturers. These three sit within a competitive set where technology access and regulatory certification velocity determine tender eligibility.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| Dow |
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| Avery Dennison Corporation |
| Huntsman International |
| Bostik SA |
| Others |
Supply & Pricing Matrix
Undercapacity in Saudi Arabia's acrylic emulsion production is compressing regional formulator margins while simultaneously elevating pricing power for European precursor suppliers serving Gulf mega-project demand.
Pricing Analysis
SASO VOC emission thresholds dictate the pricing tier structure across the Middle-East and Africa waterborne adhesives market. Three-tier pricing stratifies across REACH-aligned premium formulations, SASO-compliant standard grades, and economy EVA systems for paper bonding. Price differentiation centers on certification level and volume scale, with mega-project contractors commanding 15-20 point discounts against spot buyers. Cost compression in standard-grade acrylics is intensifying because butyl acrylate feedstock volatility feeds directly into formulation economics. Furniture exporters in Egypt exhibit the highest price sensitivity due to thin export margins, while NEOM developers prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and Saudi Arabia dominates supply chain risk calculations for polyurethane dispersion technology. Feedstock concentration centers on Germany, the Netherlands, and Belgium for specialty monomers, while acrylic precursor production clusters in Saudi Arabia's Yanbu corridor and the UAE's Jebel Ali zone. Raw material dependencies rest on butyl acrylate, 2-ethylhexyl acrylate, and specialty isocyanates for urethane crosslinking. Single-source vulnerability from German licensors constrains local production autonomy. Distribution runs through Dubai-based chemical distributors maintaining pre-qualified inventories for Gulf Cooperation Council tender compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in the Middle-East and Africa waterborne adhesives market as NEOM and Red Sea developers consolidate procurement through tier-one contractors with quarterly pre-approved product lists.
For Market Incumbents: Entrench position through captive acrylic monomer supply in Saudi Arabia's industrial chemical corridor and accelerated SASO certification velocity to compress competitor qualification timelines. Defend against emerging regional compounders by locking multi-year offtake agreements with Yanbu precursor producers. Prioritize formulation chemist retention as Gulf universities produce limited polymer science graduates capable of tuning emulsion stability for 50°C+ storage conditions. For New Entrants and Emerging Players: Egyptian furniture export hubs serving European markets represent the most penetrable entry point as the Environmental Affairs Agency drafts REACH-aligned VOC limits. Moroccan automotive trim specifications for heat-resistant polyurethane emulsions offer secondary white-space opportunity with less incumbent saturation. Deploy technical service partnerships with European dispersion licensors to bypass single-source technology constraints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across waterborne adhesive compounding as digitized quality assurance reduces European technical service dependency. Long-term viability favors acquisition targets with backward-integrated precursor supply or established SASO certification pipelines. Monitor Egyptian regulatory harmonization timelines as the inflection signal for Cairo-based manufacturing asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Yanbu corridor expansion narrows European import dependency for Gulf formulators. |
| REACH-Aligned Certification Investment | Egyptian furniture exporters pre-qualify suppliers against EU import standards ahead of domestic regulation. |
| Digital Specification Platform Partnership | Dubai and Johannesburg distributors filter adhesive eligibility by multi-jurisdiction certification status. |
| Polyurethane Dispersion Technology Licensing | German and Dutch licensors enable regional production autonomy for automotive interior specifications. |
| Humidity-Resistant Formulation R&D | Sika AG's flooring specifications pull modified acrylic-urethane hybrids for Saudi coastal construction. |
Research Methodology
The analysis maps acrylic, polyurethane, EVA, and polymeric dispersion sub-sectors, each validated through formulation chemists, procurement managers at packaging converters, construction material distributors, and regulatory affairs specialists at compounders. Primary interviews with plant managers and technical R&D directors combined with secondary validation from SASO technical bulletins, South Africa NRCS filing records, Egyptian Environmental Affairs Agency draft regulations, and Gulf Cooperation Council customs data. Bottom-up volume builds and top-down market sizing triangulated through cross-referencing end-use consumption patterns with precursor import flows.
Fixed assumptions across the analysis window include sustained SASO enforcement intensity, continued NEOM and Red Sea project commitment, and REACH-aligned regulatory convergence in Egyptian export markets. Modeled segmentation dimensions span chemistry family, end-use vertical, application technique, and regional production hub. CAGRs derived from weighted average of historical precursor demand elasticity and project pipeline visibility. Industry-specific forecast inputs incorporated automotive interior specification shifts in Morocco and South Africa, plus packaging converter line conversion rates in Dubai and Jeddah.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, Gulf construction spending cycles, or European export market access would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory harmonization delays, feedstock supply disruptions, or technology licensing access changes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Global Engineering Adhesives Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Global Bone Cement and Glue Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Anti-Corrosion Tape Market