
 North America Construction Adhesives and Sealants Market | 2026-2036
North America Construction Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Construction Adhesives and Sealants Market Analytics
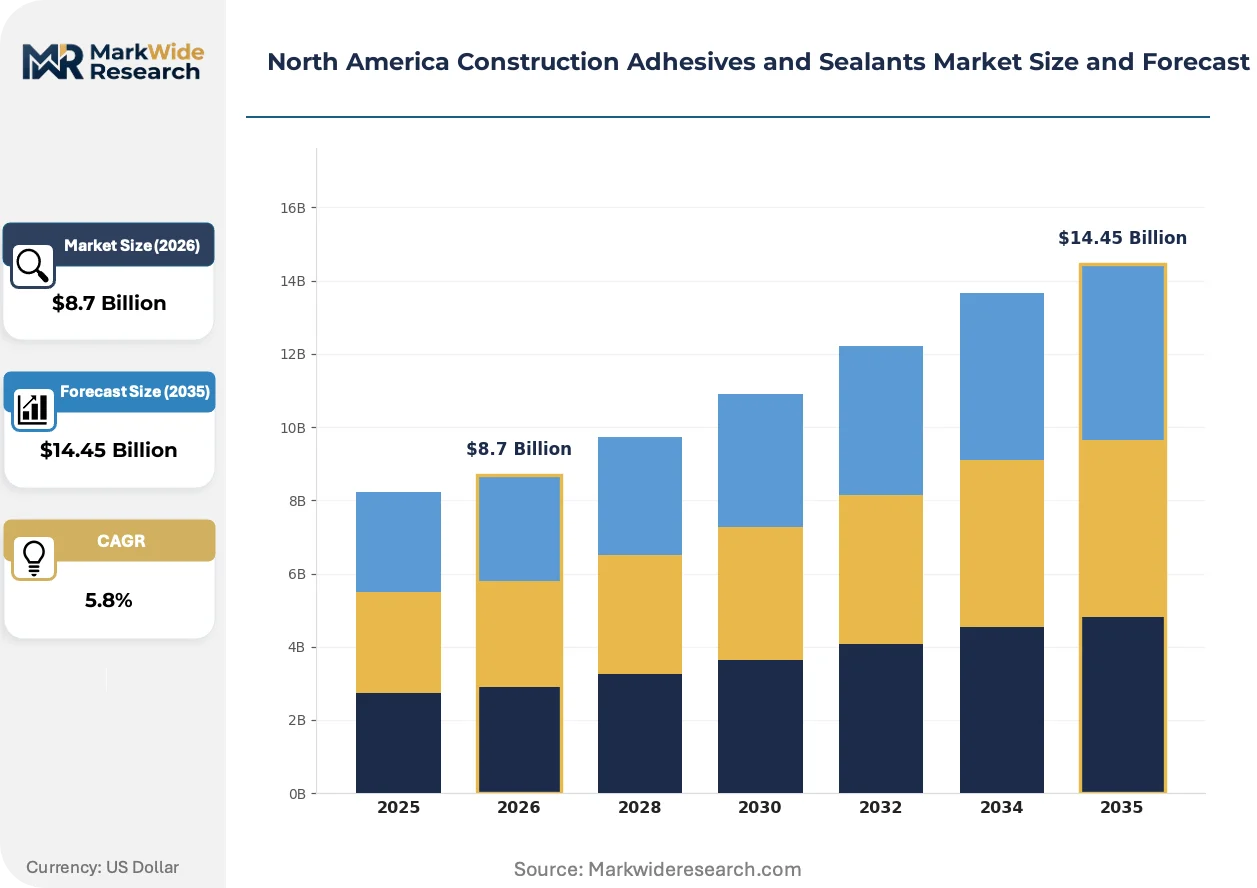
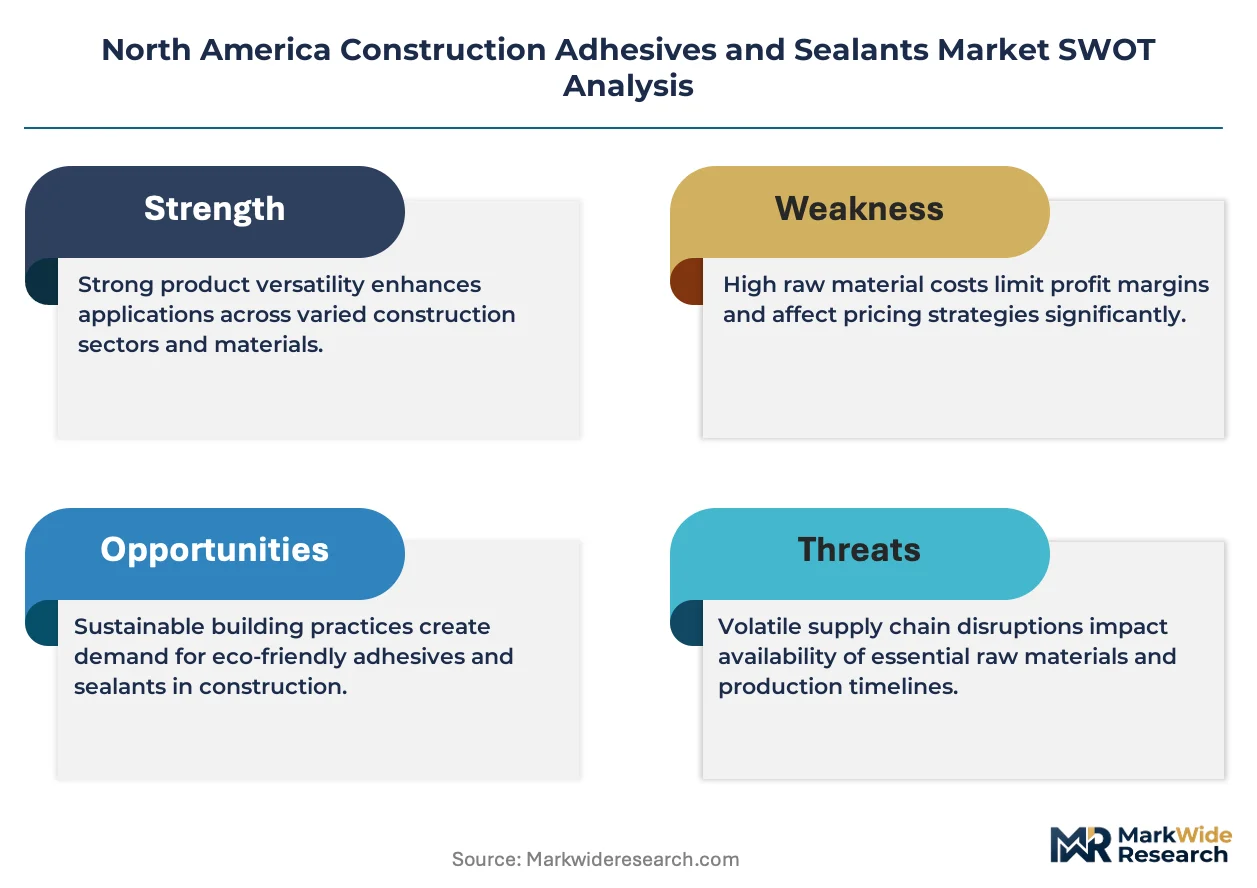
Performance-based warranty and maintenance contracts is restructuring how construction adhesives and sealants are monetized in North America, shifting revenue from unit sales to lifecycle service agreements. H.B. Fuller Company leverages its direct contractor relationships to embed adhesive specification into building envelope service programs. Henkel Corporation sustains R&D intensity in hybrid polymer chemistry that reduces cure-time variability across temperature ranges. Sika AG anchors its position through backward integration into silicone intermediates, securing supply continuity for high-performance sealant grades.
Construction adhesives and sealants comprise formulated polymer systems—typically polyurethane, silicone, acrylic, or epoxy resin bases compounded with fillers, plasticizers, and curing agents—that bond substrates or seal joints against moisture, air, and structural movement in built environments. These materials achieve tensile shear strengths ranging from 200 to 3,000 psi depending on chemistry, with service temperatures spanning minus 40 to 200 degrees Celsius for specialized silicone formulations. Polyurethane formulations dominate residential applications where flexibility and paintability command specification preference, while silicone leads commercial building envelopes demanding UV stability and movement accommodation. The contractor end-user channel generates the deepest margin pools due to bulk procurement scale and specification loyalty, though DIY consumers represent the fastest-growing segment as home improvement retailers expand professional-grade product access.
EPA VOC regulations for architectural coatings and sealants mandate reformulation of solvent-based systems, pushing manufacturers toward waterborne and silyl-modified polymer technologies. OSHA workplace exposure limits for isocyanates in polyurethane production elevate capital requirements for domestic manufacturing compliance. Health Canada's PMRA evaluates biocide-containing sealants under renewed environmental assessment protocols, creating divergence in cross-border product registration strategies. Stakeholders must monitor how evolving federal procurement standards for low-embodied-carbon materials reshape specification criteria across publicly funded infrastructure projects.
Market Dynamics
Performance-based warranty and maintenance contracts is restructuring how construction adhesives and sealants are monetized in North America, shifting revenue from unit sales to lifecycle service agreements. H.B. Fuller Company leverages its direct contractor relationships to embed adhesive specification into building envelope service programs.
Growth Catalysts
- Commercial building retrofit activity:Aging building stock across the United States drives adhesive specification upgrades as energy codes tighten envelope performance requirements.
- EPA VOC emission standards:Evolving regulations for architectural coatings reshape product formulation requirements, accelerating waterborne and silyl-modified polymer adoption.
- Warehouse construction concentration:Demand concentrates in the southeastern United States where logistics facility construction accelerates, pulling high-volume adhesive procurement.
Market Restraints
- Isocyanate compliance costs:OSHA workplace exposure limits for isocyanates in polyurethane production elevate capital requirements for domestic manufacturing compliance.
- Silicone intermediate concentration:Backward integration into silicone feedstock anchors with a limited supplier base, creating supply continuity risk for high-performance sealant grades.
- Cure-time temperature sensitivity:Polyurethane formulations exhibit variability in cure rates across temperature ranges, limiting cold-weather application windows in northern climates.
Strategic Opportunities
- DIY channel expansion:Home improvement retailers expand professional-grade product access, creating margin expansion through direct-to-consumer distribution.
- Low-embodied-carbon procurement:Evolving federal procurement standards for publicly funded infrastructure projects reshape specification criteria toward sustainable material selection.
- Hybrid polymer convergence:Silyl-modified polymer chemistry combines silicone durability with paintability, opening specification in residential applications previously locked to polyurethane.
Industry Challenges
- Biocide registration divergence:Health Canada's PMRA evaluates biocide-containing sealants under renewed environmental assessment protocols, creating cross-border product registration complexity.
- Reformulation capex intensity:Solvent-to-waterborne system transitions require production line retooling and curing equipment upgrades.
- Contractor specification loyalty:Bulk procurement scale concentrates purchasing power with established relationships, raising customer acquisition costs for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Construction Adhesives and Sealants Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Acrylic, Epoxy Application: Residential, Commercial, Industrial, Automotive End User: Contractors, DIY Consumers, Architects, Engineers Packaging Type: Cartridge, Drum, Pail, Sausage |
| Companies Covered | 3M, H.B. Fuller Company, Sika AG, Henkel Corporation, Dow, Arkema, RPM International Inc., Wacker Chemie AG, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Construction Adhesives and Sealants Market Evolving Landscape
Formulation chemistry and procurement models are actively reshaping competitive positioning across the North American construction adhesives and sealants landscape. Three developments warrant particular attention from stakeholders monitoring specification patterns and margin structures.
Hybrid silyl-modified polymer technology is unifying the performance attributes of silicone and polyurethane chemistries into single-component systems. Commercial building envelope contractors are adopting these formulations at accelerating rates where UV stability and paintability must coexist. This unification is compressing the traditional segmentation between residential and commercial specification tiers, enabling single-supplier relationships across project types.
EPA's evolving VOC emission standards for architectural coatings and sealants mandate reformulation of solvent-based systems. The industrial consequence pushes manufacturers toward waterborne technologies and silyl-modified polymer platforms with lower volatile content. Commercial building envelope applications face the most acute compliance pressure, driving accelerated R&D investment in cure-time optimization for waterborne alternatives.
Buying patterns among contractor end-users are compressing specification cycles as performance-based warranty and maintenance contracts displace transactional procurement. Direct manufacturer-to-contractor relationships are replacing distributor intermediaries in the highest-volume segments. This shift is most visible in the southeastern United States warehouse construction corridor, where envelope service programs bundle material supply with installation labor and long-term performance guarantees.
North America Construction Adhesives and Sealants Market Segmentation
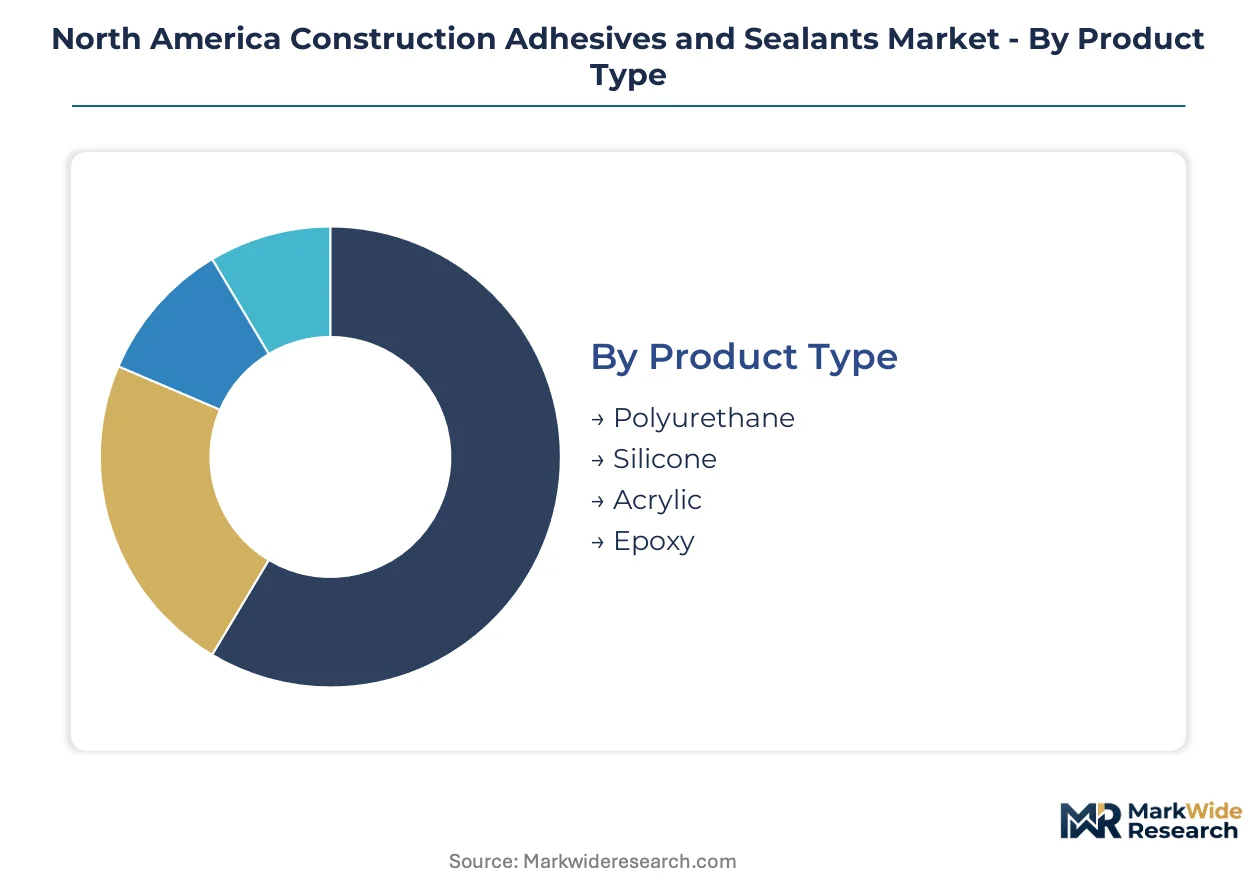
Segmentation in construction adhesives and sealants reveals how specification authority, packaging economics, and end-user procurement power reshape margin structures across project types. Understanding these divides exposes where manufacturers can capture premium positioning versus commodity volume.
Product Type:
Upgrade cycles vary dramatically by chemistry base, with reformulation timelines driven by regulatory pressure and performance warranty demands.
- Polyurethane:Flexible polymer systems bond dissimilar substrates with paintable surface compatibility. Demand clusters in residential framing and subfloor applications across the southeastern United States where warehouse construction pulls high-volume procurement.
- Silicone:UV-stable elastomeric sealants accommodate structural movement in building envelopes while maintaining weather resistance. Commercial retrofit activity in the United States drives specification for high-performance grades demanding supply continuity.
- Acrylic:Waterborne emulsion systems offer lower VOC profiles for interior finishing applications.
- Epoxy:Rigid high-strength formulations anchor structural bonding in industrial flooring and concrete repair.
Volume placements concentrate in Polyurethane; the faster expansion belongs to Silicone.
Application:
Project scale and code compliance intensity create distinct specification tiers that separate commodity from engineered-grade procurement.
- Residential:Single-family and multifamily construction specifies adhesives for subfloor, drywall, and trim installation where flexibility and paintability command preference. The DIY channel expansion through home improvement retailers accelerates professional-grade product access in this segment.
- Commercial:Building envelope performance requirements tighten as energy codes evolve, pulling adhesive upgrades in retrofit and new construction. EPA VOC emission standards reshape formulation requirements for curtain wall and roofing applications.
- Industrial:Heavy-duty bonding and sealing in manufacturing facilities demands chemical resistance and load-bearing capacity.
- Automotive:Assembly and aftermarket applications specify adhesives for panel bonding and weatherstrip sealing.
Revenue depth pools in Commercial; Residential gains share fastest.
End User:
Procurement authority and technical specification control fragment across the value chain, determining who captures margin and locks in supplier relationships.
- Contractors:Bulk procurement scale and specification loyalty generate the deepest margin pools. Performance-based warranty and maintenance contracts embed adhesive supply into long-term service agreements, restructuring monetization from unit sales to lifecycle revenue.
- DIY Consumers:Home improvement retailers expanding professional-grade product access represent the steepest expansion trajectory as direct-to-consumer distribution captures margin previously lost to intermediaries.
- Architects:Design-phase specification authority shapes material selection criteria for publicly funded infrastructure projects.
- Engineers:Technical performance validation and warranty compliance requirements influence adhesive selection in structural applications.
Contractor relationships anchor current revenue; DIY Consumers are climbing the fastest.
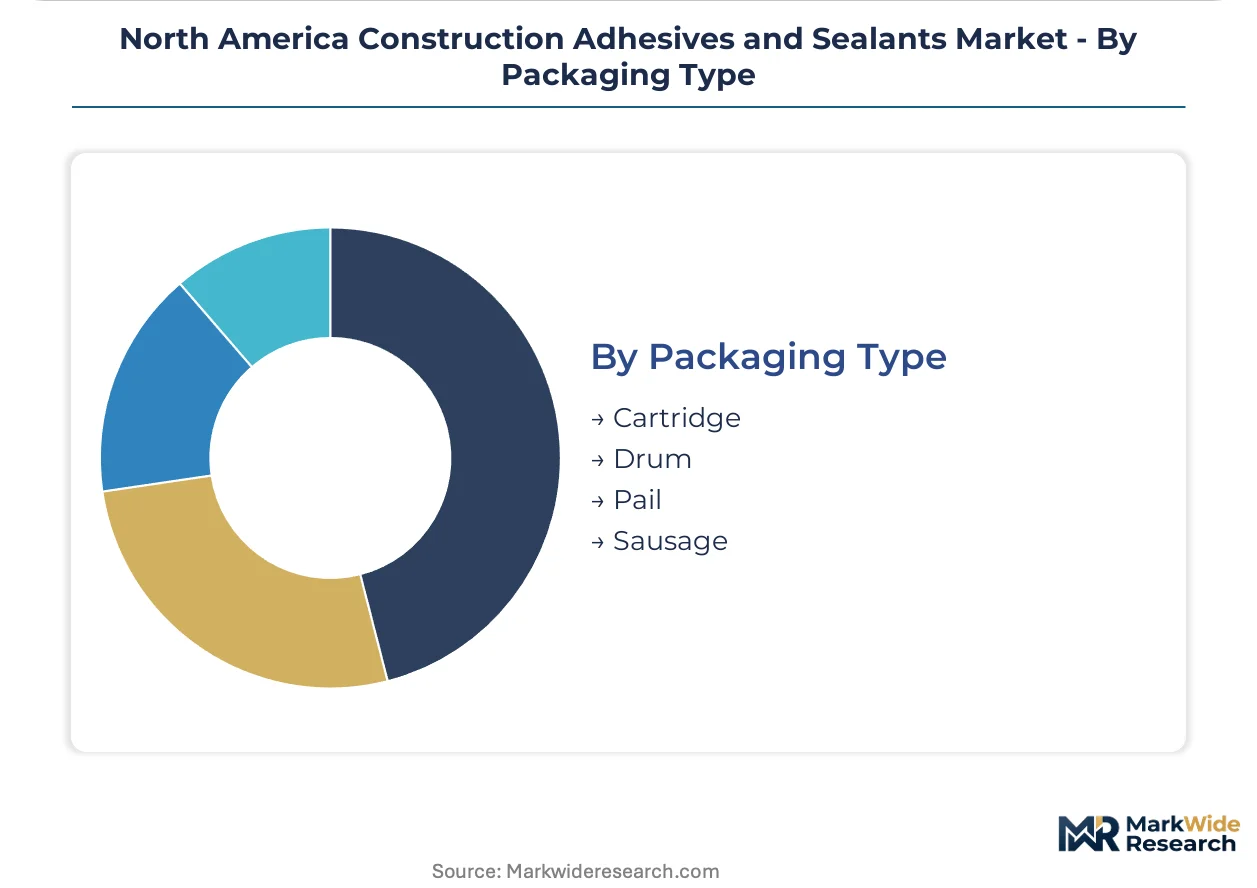
Packaging Type:
Packaging format selection ties directly to application scale, equipment compatibility, and jobsite logistics economics.
- Cartridge:Standard 300ml disposable tubes suit caulking gun application in residential and light commercial finishing. This format dominates DIY retail shelves and small contractor purchases where mobility and minimal waste matter.
- Drum:Bulk liquid containment enables high-volume dispensing in industrial flooring and manufactured housing production.
- Pail:Mid-scale packaging serves commercial contractors applying adhesives with trowel or roller methods.
- Sausage:Foil-wrapped bulk format reduces packaging waste and enables pneumatic dispensing in commercial envelope sealing.
Cartridge shipments lead absolute volume; Sausage packaging expands most quickly in commercial specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States while Canadian and Mexican markets absorb cross-border supply. The three-country configuration creates distinct specification tiers tied to local building codes and environmental regulations.
United States
Warehouse construction in Georgia, Texas, and Florida pulls high-volume polyurethane adhesive procurement. EPA VOC emission standards for architectural coatings mandate waterborne formulation shifts. The Southeast logistics corridor anchors demand concentration where envelope service programs bundle material supply with installation labor.
Canada
Commercial building retrofit activity in Toronto and Vancouver drives silicone sealant specification for energy code compliance. Health Canada's PMRA evaluates biocide-containing sealants under renewed environmental assessment protocols. Ontario's manufacturing base supplies formulated products to Prairie provinces where cold-weather cure-time variability limits polyurethane application windows.
Mexico
Automotive assembly expansion in Nuevo León and Bajío Region specifies structural adhesives for panel bonding. Mexican environmental regulations align with US EPA frameworks while maintaining distinct registration requirements for imported formulations. Mexico City Metro construction anchors infrastructure-grade epoxy demand for concrete repair applications.
North America Construction Adhesives and Sealants Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and application technology. The market structure consolidates around integrated polymer manufacturers with captive resin supply and specialized compounders sourcing intermediates externally. Three archetypes dominate: multinational chemical conglomerates with backward integration into silicone feedstock, mid-scale formulators serving regional contractor networks, and technology licensors monetizing silyl-modified polymer patents. Competitive moves center on strategic partnerships embedding adhesive supply into building envelope service programs and geographic expansion into southeastern US logistics construction corridors.
Among Swiss and German chemical conglomerates, Sika AG and Wacker Chemie AG exemplify the integrated feedstock archetype through upstream control over silicone intermediates. H.B. Fuller Company occupies a position within the direct contractor relationship tier, leveraging specification embedding into long-term service agreements. These three entities represent distinct competitive vectors: captive raw material security, regional formulation proximity, and lifecycle contract monetization.
| Leading Market Players |
|---|
| 3M |
| H.B. Fuller Company |
| Sika AG |
| Henkel Corporation |
| Dow |
| Arkema |
| RPM International Inc. |
| Wacker Chemie AG |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Contractor bulk procurement concentration in the southeastern United States logistics corridor anchors contract-based long-term offtake as the dominant pricing model, with envelope service programs bundling material supply and installation labor into multi-year agreements.
Pricing Analysis
Margin tightening in commercial-grade silicone reflects backward integration scarcity among silicone intermediate suppliers and elevated reformulation costs from EPA VOC compliance. Three-tier pricing structure across premium hybrid polymer, standard polyurethane, and economy acrylic levels separates specification tiers by movement accommodation and UV stability ratings. Cost-down pressure on waterborne formulations accelerates as manufacturers retool solvent-based production lines. DIY consumers exhibit highest price sensitivity, while building envelope contractors with performance warranties show lowest elasticity due to specification lock-in.
Supply Chain Analysis
Return flows of unused sausage-packaged sealants from commercial jobsites feed into regional distributor refurbishment programs, reducing packaging waste recovery costs. Raw material production draws from Germany, Switzerland, and the United States for silicone intermediates, polyurethane isocyanates, and acrylic emulsions. Supply chain risk centers on single-source vulnerability for specialized silyl-modified polymer catalysts. Distribution runs through direct manufacturer-to-contractor relationships displacing traditional distributor intermediaries in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American construction adhesives and sealants market sits in a technology-transition phase as silyl-modified polymer chemistry displaces traditional polyurethane and silicone segmentation in building envelope applications.
For Market Incumbents: Deepen captive supply of silicone intermediates through backward integration or long-term offtake agreements with German and Swiss feedstock producers. Expand R&D investment in cure-time optimization for waterborne alternatives to defend specification position against hybrid polymer entrants as EPA VOC regulations tighten compliance timelines. For New Entrants and Emerging Players: E-commerce direct-to-contractor platforms offer the most penetrable route into the DIY consumer segment, where home improvement retailers currently dominate professional-grade product access. Target southeastern United States warehouse construction corridors with hybrid polymer formulations that unify silicone durability and polyurethane paintability, leveraging specification unification to bypass established contractor loyalty barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale formulators with regional contractor network density in Canada and Mexico, where cross-border registration complexity creates acquisition discounts. Monitor Health Canada PMRA biocide assessment outcomes as an inflection indicator for North American product registration convergence or continued divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | Sika AG and Wacker Chemie AG anchor supply security for high-performance sealant grades. |
| Hybrid Polymer R&D Expansion | Henkel Corporation sustains chemistry investment reducing cure-time temperature variability. |
| Direct Contractor Relationship Programs | H.B. Fuller Company embeds adhesive specification into building envelope service agreements. |
| Waterborne Formulation Transition | EPA VOC compliance mandates accelerate production line retooling and curing equipment upgrades. |
| DIY Channel Distribution Expansion | Home improvement retailers capture margin previously lost to distributor intermediaries. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with building envelope contractors, adhesive formulation R&D directors, commercial procurement managers at logistics developers, and distribution channel partners. EPA enforcement databases, Health Canada PMRA registration records, and ACC industry statistics provided regulatory and volume benchmarks. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts.
Reconciliation of shipment data, formulation capacity utilization, and end-use procurement patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry base, application type, end-user procurement authority, and packaging format. CAGRs derived from weighted average of historical volume elasticity and regulatory-driven substitution rates. Forecast inputs incorporated energy code adoption timelines and federal infrastructure procurement standard evolution.
The model holds under steady EPA VOC enforcement and stable isocyanate supply; deviation in trade policy affecting German or Swiss intermediate imports would shift regional production economics. Practitioners should monitor OSHA isocyanate exposure limit revisions and hybrid polymer patent expiration schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Ocular Sealants and Glues Market