
 North America Laminating Adhesives Market | 2026-2036
North America Laminating Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Laminating Adhesives Market Intelligence
Asset-light equipment leasing programs for adhesive application machinery are reshaping competitive positioning in the North America laminating adhesives market. This allows smaller packaging converters to access advanced bonding technologies without significant capital outlay. H.B. Fuller Company leverages its extensive distribution network to serve these converters. Dow differentiates through its polymer science innovations for high-performance films, while Henkel AG & Co. KGaA specializes in adhesive systems for the flexible packaging industry.
Laminating adhesives are bonding agents designed to join multiple flexible substrates like films, foils, or papers into a single composite. Their primary purpose is to create multi-layer materials with enhanced barrier properties, strength, and durability for specific end-uses. Water-based and reactive technologies are gaining share over traditional solvent-based types due to stricter environmental standards in the region. The flexible packaging segment remains the largest application area by a significant margin.
In the United States, the Food and Drug Administration (FDA) governs adhesives used in food-contact packaging, setting stringent safety standards. The Environmental Protection Agency (EPA) regulates volatile organic compound (VOC) emissions, influencing the formulation of solvent-based products. Health Canada maintains similar oversight for products sold in Canada, creating a harmonized but complex regulatory environment. Adhesive manufacturers must therefore balance performance attributes against evolving sustainability demands.
Market Dynamics
The primary structural force shaping the market is the regulatory mandate to reduce volatile organic compounds (VOCs). This pressure from the EPA in the US and Health Canada is compelling a fundamental technology shift away from solvent-based systems toward water-based and solventless alternatives.
Growth Catalysts
- FDA Regulations:Stricter Food and Drug Administration rules for indirect food additives are pushing demand for advanced, low-migration adhesives in food packaging to ensure consumer safety and compliance.
- Medical Packaging Expansion:The growing need for sterile barrier systems in medical device and pharmaceutical packaging provides a significant demand stream for high-performance laminating adhesives with specific barrier properties.
- Recyclable Packaging Design:A push for circular economy goals is creating demand for new adhesives that facilitate the separation and recycling of multi-layer flexible packaging structures.
Market Restraints
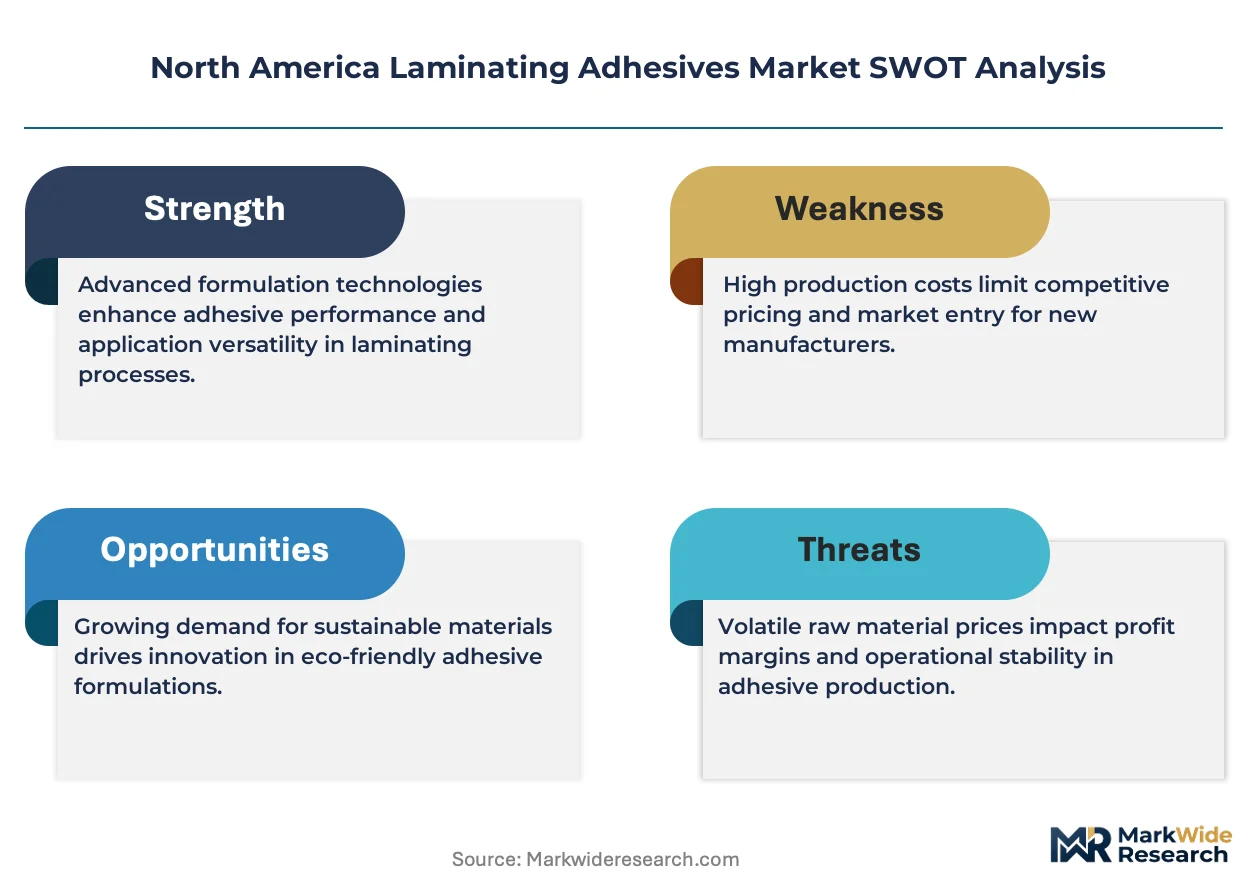
- Raw Material Volatility:Price fluctuations and supply constraints for key feedstocks, such as isocyanates and polyols used in polyurethane adhesives, create margin pressure for manufacturers.
- Performance Gaps:Certain water-based adhesives still exhibit slower curing times and lower initial bond strengths compared to solvent-based counterparts, limiting their use in high-speed converting operations.
- Mono-Material Substitution:The development of advanced mono-material films with inherent barrier properties poses a substitution threat, as these structures can reduce or eliminate the need for lamination.
Strategic Opportunities
- Bio-Based Adhesives:There is a significant opportunity in developing and commercializing laminating adhesives derived from renewable resources like plant-based starches or polylactic acid (PLA) to meet sustainability targets.
- Adhesives for Digital Printing:The rise of digital printing on flexible packaging creates a need for specialized adhesives that are compatible with digitally printed inks and substrates without causing delamination.
- Mexican Manufacturing Sector:Expanding into Mexico's growing food and beverage processing industry offers a new geographic frontier for adhesive suppliers, as local manufacturers upgrade their packaging standards.
Industry Challenges
- Capital Investment for Converters:The transition from solvent-based to solventless lamination requires significant capital expenditure on new application machinery, which is a barrier for smaller converters.
- Technician Skill Gaps:A shortage of operators with the technical expertise to run and maintain advanced solventless and water-based laminating equipment can lead to production inefficiencies.
- Regulatory Fragmentation:Navigating differing VOC regulations between US states and Canadian provinces complicates product formulation and distribution strategies for adhesive manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Laminating Adhesives Market |
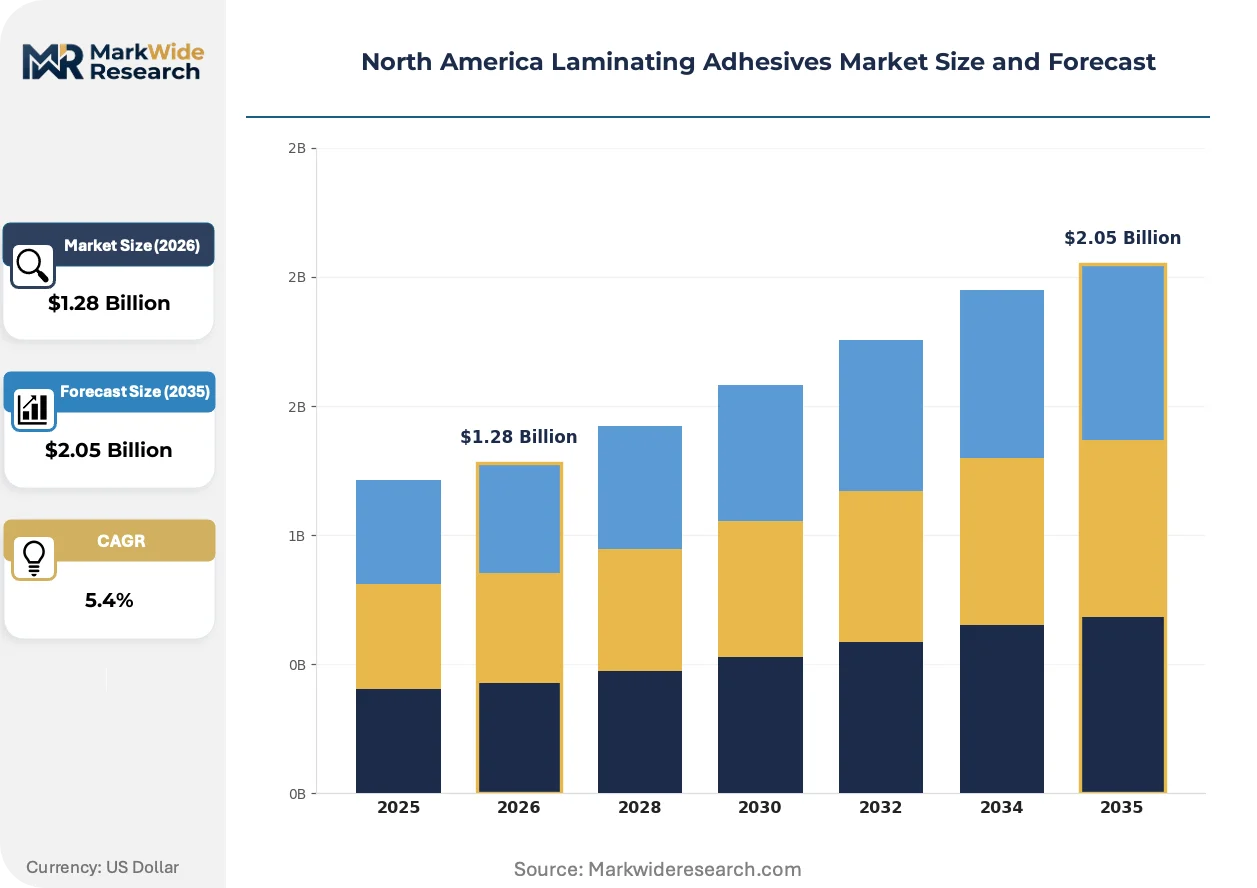
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.05 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Solvent-Based, Water-Based, Reactive, UV Cure Application: Flexible Packaging, Paper Lamination, Textile Lamination, Label Lamination, Decorative Lamination End User: Printing Houses, Packaging Manufacturers, Textile Producers, Labeling Companies Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Dow, 3M, Arkema, Sika AG, DuPont, BASF, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Laminating Adhesives Market Strategic Shifts & Innovations
Material science advancements are converging with sustainability mandates to redefine product development. The focus is on creating adhesives that not only meet stringent performance criteria for flexible packaging but also align with environmental regulations and circular economy principles.
Reactive hot melt adhesives provide immediate bond strength upon application, unlike systems that require longer curing times. Flexible packaging converters are adopting this technology to increase throughput and reduce lead times for finished goods. The technology is collapsing the production cycle by allowing laminated rolls to be slit or processed into pouches almost immediately, minimizing work-in-progress inventory.
The EPA's Clean Air Act continues to be a dominant regulatory influence, setting stringent limits on VOC emissions from industrial sources. This has directly curtailed the market for traditional solvent-based laminating adhesives in North America. The flexible packaging segment is most affected, with manufacturers reformulating products to emphasize solvent-free polyurethane and water-based acrylic technologies to maintain compliance.
A notable shift in purchasing behavior involves converters moving toward smaller, just-in-time order quantities for adhesives. This model disrupts the traditional large-volume, direct-sale channel and benefits specialized distributors who can manage inventory for multiple smaller customers. This trend is most prominent in the US Midwest, where a high concentration of small and mid-sized food packaging converters seek to minimize on-site material storage.
North America Laminating Adhesives Market Segmentation
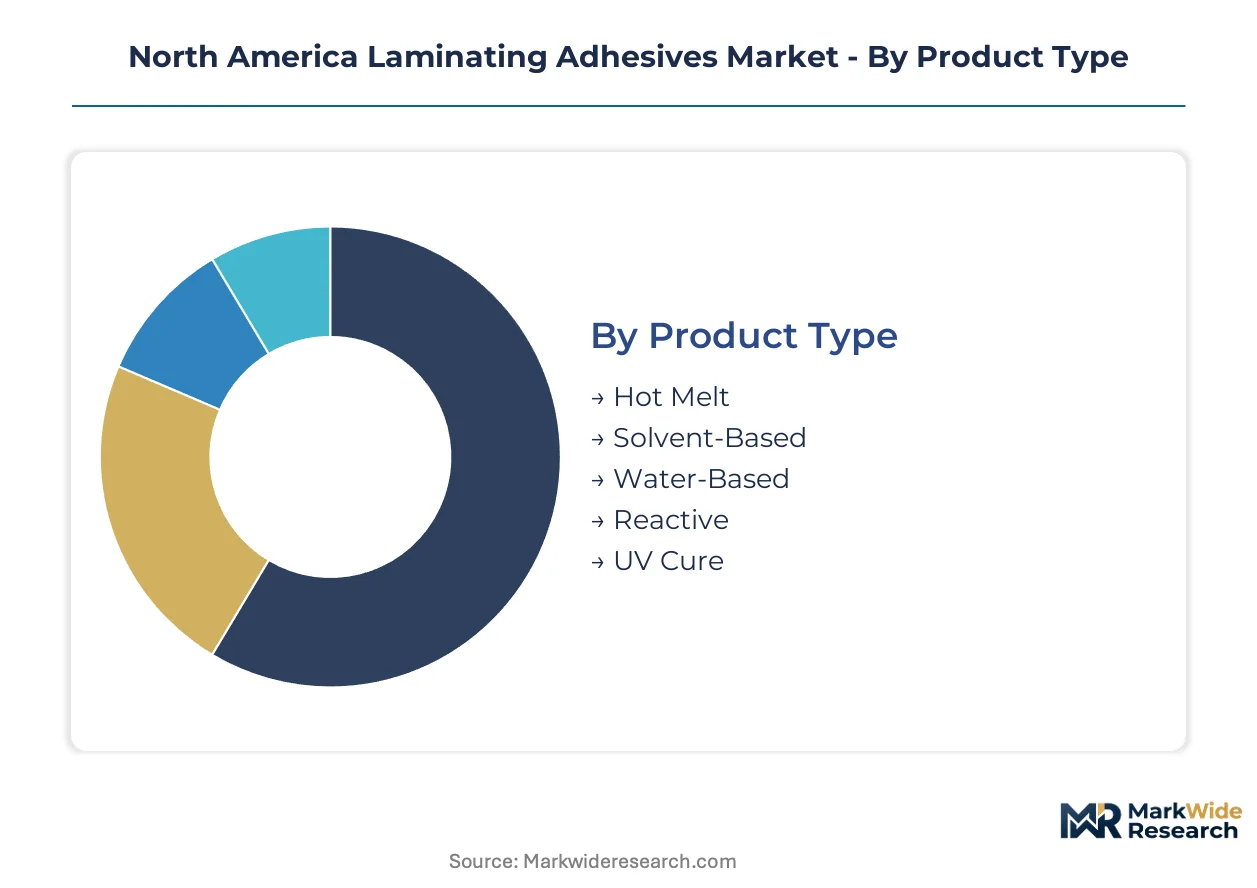
The North America laminating adhesives market exhibits diverse segmentation, reflecting varied technological requirements, application demands, and end-user preferences. Understanding these distinct segments allows manufacturers to tailor product development and distribution strategies for optimal market penetration. Regulatory compliance and performance attributes significantly influence segment growth trajectories across the region.
Product Type:
The product type segmentation differentiates adhesives by their chemical composition and curing mechanisms, influencing processing speeds and environmental impact.
- Hot Melt:These adhesives provide immediate bond strength upon cooling, eliminating the need for extensive drying or curing times. Flexible packaging converters widely adopt hot melt systems to significantly increase throughput and reduce lead times in high-speed lamination processes.
- Water-Based:Formulated with water as the primary carrier, these adhesives minimize volatile organic compound (VOC) emissions, aligning with stricter environmental regulations from the EPA and Health Canada. Demand concentrates within food packaging applications where environmental compliance is paramount.
- Solvent-Based:Traditional formulations utilizing organic solvents provide strong initial tack and excellent bond strength for challenging substrates. Regulatory pressures from the EPA and Health Canada are driving a significant shift away from these systems.
- Reactive:These adhesives cure through a chemical reaction, often involving moisture or heat, forming durable, high-performance bonds. Reactive polyurethanes are gaining traction for multi-layer flexible packaging requiring superior barrier properties.
- UV Cure:Ultraviolet light initiates the curing process for these specialized adhesives, offering rapid solidification and precise control over bond formation. UV cure technologies find niche applications in sensitive material lamination.
Solvent-Based adhesives historically anchored the volume base, while Water-Based types gain share at the steepest rate.
Application:
Application segments highlight the diverse end-uses for laminating adhesives, each with specific performance requirements and regulatory considerations.
- Flexible Packaging:This segment represents the largest application area, encompassing food, medical, and consumer goods packaging that requires multi-layer films for barrier protection and structural integrity. Stricter FDA regulations for food contact materials drive innovation within this critical segment.
- Label Lamination:Adhesives in this category bond protective films to printed labels, enhancing durability, chemical resistance, and aesthetic appeal for various product containers. The demand for high-clarity and tamper-evident labels drives specialized adhesive development.
- Paper Lamination:This application involves bonding films or other papers to paperboard or paper substrates, improving strength, moisture resistance, and printability for packaging and graphic arts. Environmental concerns are pushing for recyclable paper-based laminates.
- Textile Lamination:Adhesives are used to bond multiple textile layers, creating composite fabrics with enhanced properties like waterproofing, breathability, or insulation. Performance demands in apparel and industrial textiles drive product specifications.
- Decorative Lamination:This segment focuses on bonding decorative films to various surfaces, such as furniture, flooring, or automotive interiors, for aesthetic enhancement and surface protection. Durability and visual appeal are key performance indicators.
The market remains heavily skewed towards Flexible Packaging, with Label Lamination presenting specialized growth opportunities.
End User:
The end-user segmentation categorizes the primary businesses that utilize laminating adhesives in their manufacturing processes.
- Packaging Manufacturers:These companies convert raw materials into finished packaging products, applying laminating adhesives to create multi-layer structures for food, pharmaceutical, and consumer goods industries. Their scale dictates significant adhesive volumes.
- Printing Houses:Printing houses often integrate lamination services to enhance the durability and appearance of printed materials, including labels, brochures, and specialized packaging components. Compatibility with various ink systems is crucial.
- Textile Producers:Textile producers use laminating adhesives to create composite fabrics for apparel, automotive, and industrial applications, requiring specific bond strengths and flexibility. Innovation in sustainable textiles influences adhesive choices.
- Labeling Companies:Specialists in label production, these companies apply laminating adhesives to construct multi-layer labels with barrier properties, graphic protection, and specific functionalities. Speed and precision are critical for their operations.
Packaging Manufacturers represent the largest customer base, while Printing Houses increasingly drive innovation in digital print-compatible adhesives.
Distribution Channel:
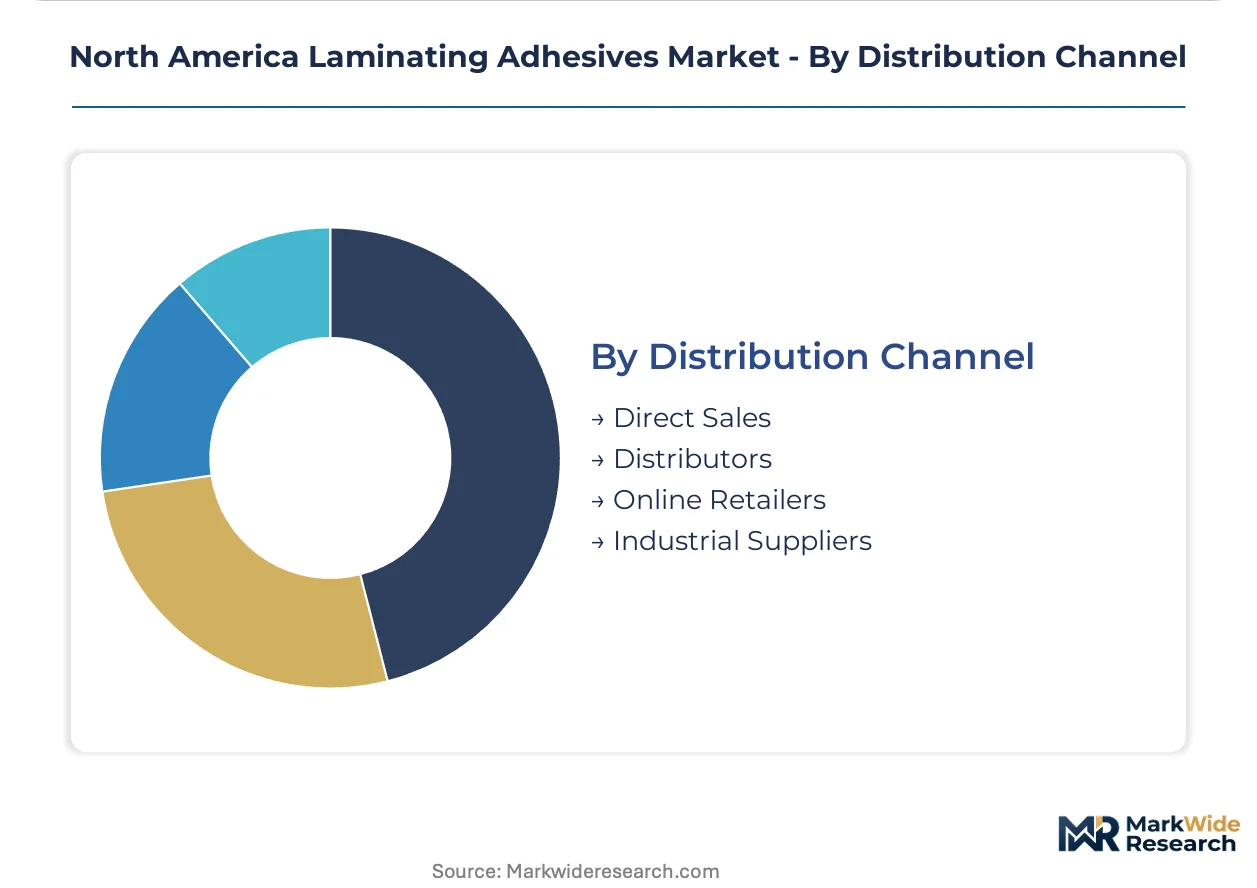
Distribution channels define how laminating adhesives reach the end-users, reflecting varied procurement strategies and service requirements.
- Distributors:These intermediaries manage inventory and logistics for multiple adhesive manufacturers, serving a broad base of small to mid-sized converters. They offer localized support and just-in-time delivery, particularly in the US Midwest.
- Direct Sales:Large-volume end-users, typically major packaging manufacturers, often procure adhesives directly from manufacturers through dedicated sales teams. This channel facilitates customized solutions and long-term strategic partnerships.
- Online Retailers:A nascent but growing channel, online platforms offer convenience and access to a wider range of products, primarily catering to smaller businesses or for specialized, lower-volume adhesive purchases. Digital marketplaces streamline procurement.
- Industrial Suppliers:These suppliers provide a comprehensive range of industrial materials, including adhesives, to various manufacturing sectors. Their broad product catalog caters to diverse industrial needs beyond specialized laminating applications.
The shift towards Distributors reflects evolving procurement patterns, while Direct Sales maintain strategic importance for key accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration within specialized packaging manufacturing clusters drives regional demand for laminating adhesives. These clusters require advanced bonding technologies and increasingly prioritize solvent-free solutions. The North America market reflects a dynamic interplay of regulatory compliance and technological adoption across its key geographic segments.
United States
Demand for laminating adhesives in the United States stems from food and medical packaging applications. Stricter FDA regulations for food contact materials and EPA mandates for VOC emissions influence product development. Packaging manufacturing clusters in the US Midwest are rapidly adopting solvent-free technologies to meet compliance standards.
Canada
Canada's market segment for laminating adhesives prioritizes flexible packaging with enhanced barrier properties for food. Health Canada maintains stringent oversight on product safety and environmental impact. Ontario's food processing sector continuously upgrades its packaging standards, creating consistent demand for advanced adhesive systems.
Mexico
Mexico's growing food and beverage processing industry offers a new geographic frontier for adhesive suppliers. Local regulatory frameworks are adapting to international standards, encouraging the adoption of higher-performance adhesives. The Bajío region, a manufacturing hub, is attracting new adhesive suppliers as local manufacturers upgrade their packaging capabilities.
US Midwest
The US Midwest exhibits a high concentration of small and mid-sized food packaging converters, driving demand for just-in-time adhesive orders. The EPA's Clean Air Act compliance for industrial sources directly impacts adhesive formulation choices. These converters are minimizing on-site material storage by relying on specialized distributors.
US Southeast
The US Southeast experiences strong demand for flexible packaging and advanced bonding technologies across diverse applications. State-level environmental regulations within this region influence adhesive formulations, favoring water-based and solventless options. Packaging manufacturing clusters in the Southeast are integrating asset-light equipment leasing programs to access modern machinery.
North America Laminating Adhesives Market Key Industry Players
Channel-controlling players compete with product-specialist players in the North America laminating adhesives market, reshaping competitive positioning. The market structure features a mix of large integrated chemical companies and specialized adhesive manufacturers. Strategic archetypes include extensive distribution network providers, polymer science innovators, and flexible packaging adhesive system specialists. Dominant competitive moves involve leveraging existing distribution channels and continuous polymer science innovation.
At the scale-driven end, H.B. Fuller Company, a US-based Inc., represents players leveraging extensive distribution networks to serve diverse converters. Dow, another US-based Inc., exemplifies polymer science innovators, differentiating through high-performance films. Henkel AG & Co. KGaA, a Germany-based AG & Co. KGaA, anchors the specialized adhesive systems segment, particularly for the flexible packaging industry.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Dow |
| 3M |
| Arkema |
| Sika AG |
| DuPont |
| BASF |
| Huntsman Corporation |
| Others |
Cost & Logistics Intelligence
Volatile feedstock prices for isocyanates and polyols directly impact margin pools for North America laminating adhesive manufacturers. This upstream cost pressure influences downstream pricing power across the value chain.
Pricing Analysis
FDA compliance and performance attributes create the primary pricing spread in the North America laminating adhesives market. A tiered pricing structure often applies, differentiating based on product formulation, customization, and volume. Raw material volatility, particularly for isocyanates, creates margin pressure for adhesive manufacturers. Smaller packaging converters in the US Midwest exhibit higher price sensitivity compared to large-scale flexible packaging manufacturers requiring specialized, high-performance solutions.
Supply Chain Analysis
Upstream sourcing of critical feedstocks like isocyanates and polyols largely depends on global chemical producers, introducing supply chain vulnerabilities. North America's laminating adhesives market relies heavily on these raw materials, which face significant price volatility. Logistics chokepoints can exacerbate supply constraints for specialized formulations. Downstream distribution primarily runs through specialized distributors serving smaller converters and direct sales channels for large packaging manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America laminating adhesives market represents an early-cycle expansion story, propelled by the accelerating shift towards solvent-free technologies. This transition opens new avenues for innovation and market penetration across diverse applications.
For Market Incumbents: Harden existing distribution networks, especially in the US Midwest, to counter emerging competitive threats from specialized niche players. Invest in advanced polymer science R&D for high-performance, bio-based adhesives to address mono-material substitution risks. Deepen vertical integration into key raw material supply chains to mitigate feedstock price volatility. Focus on supporting converters with technician training to overcome skill gaps in new equipment.
For New Entrants and Emerging Players: Mexico's expanding food and beverage processing industry represents a highly penetrable entry point for specialized adhesive suppliers. Target niche demand for adhesives compatible with digital printing inks and recyclable packaging designs. Partner with equipment leasing providers to offer bundled solutions, lowering capital barriers for smaller converters. Focus on water-based and reactive technologies that align with evolving regulatory mandates.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized manufacturers of advanced water-based and reactive laminating adhesives. These firms offer long-term viability within the market's 5-10 year transition to sustainable packaging solutions. Acquire companies with strong polymer science R&D capabilities for bio-based and recyclable adhesive formulations. The signal to watch is the accelerated adoption rate of solvent-free technologies in key food and medical packaging clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Aligns production with EPA and Health Canada VOC mandates, reducing regulatory compliance risks. |
| Long-term Supply Agreement | Stabilizes feedstock costs for isocyanates and polyols, mitigating raw material volatility. |
| Product Launch (Bio-based Adhesives) | Addresses demand for sustainable packaging solutions and circular economy goals. |
| Distribution Channel Expansion | Improves market reach to small and mid-sized converters in the US Midwest. |
| Joint Venture (Equipment Leasing) | Facilitates converter adoption of advanced solventless application machinery. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings of this analysis. Interviews were conducted with packaging manufacturers, adhesive R&D directors, and regulatory compliance officers. Secondary validation utilized FDA guidance, EPA emissions reports, and industry association publications. A bottom-up and top-down triangulation approach ensured data consistency across all market segments.
The quantitative model was calibrated against historical market performance across the analysis window. Segmentation dimensions included product type, application, end-user, distribution channel, and regional regulatory environment. Compound Annual Growth Rates were derived from an assessment of market drivers and expert projections. Key forecast inputs included raw material price forecasts and anticipated regulatory enforcement timelines.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or trade policies would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological progression. Cross-checking against industry trade body reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
South America Adhesives Market