
 Acid Anhydrides Market | 2026-2036
Acid Anhydrides Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Anhydrides Market Analytics
REACH is hardening the cost-of-entry calculus for European acid anhydride producers, forcing upgrades to purification and emissions-control infrastructure. BASF SE leverages its integrated Ludwigshafen complex to sustain cost advantages across phthalic and maleic anhydride grades. Eastman Chemical Company anchors its position through specialty ester derivatives that command premium positioning in coatings applications.
Acid anhydrides are reactive organic compounds formed by removing water from two carboxylic acid groups, typically manufactured via catalytic oxidation of ortho-xylene or n-butane feedstocks, and serve primarily as chemical intermediates for polyester resins, plasticizers, and pharmaceutical synthesis. Maleic anhydride dominates volume flows due to its ubiquity in unsaturated polyester resins for construction and marine applications, while succinic anhydride from bio-based fermentation routes represents the fastest-expanding margin pool as pharmaceutical and biodegradable polymer demand intensifies. The plastics application segment absorbs the largest share of phthalic anhydride output, though coatings-grade trimellitic anhydride commands superior unit economics in high-performance automotive and industrial finishes.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that constrain phthalic anhydride plant emissions in the United States, while ECHA administers REACH authorization requirements that restrict certain downstream plasticizer chemistries across European value chains. China's MEE implements dual carbon goals that tighten energy-intensity benchmarks for maleic anhydride producers in Shandong and Jiangsu provinces. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where feedstock-flexible or bio-based capacity investments will yield durable returns.
Market Dynamics
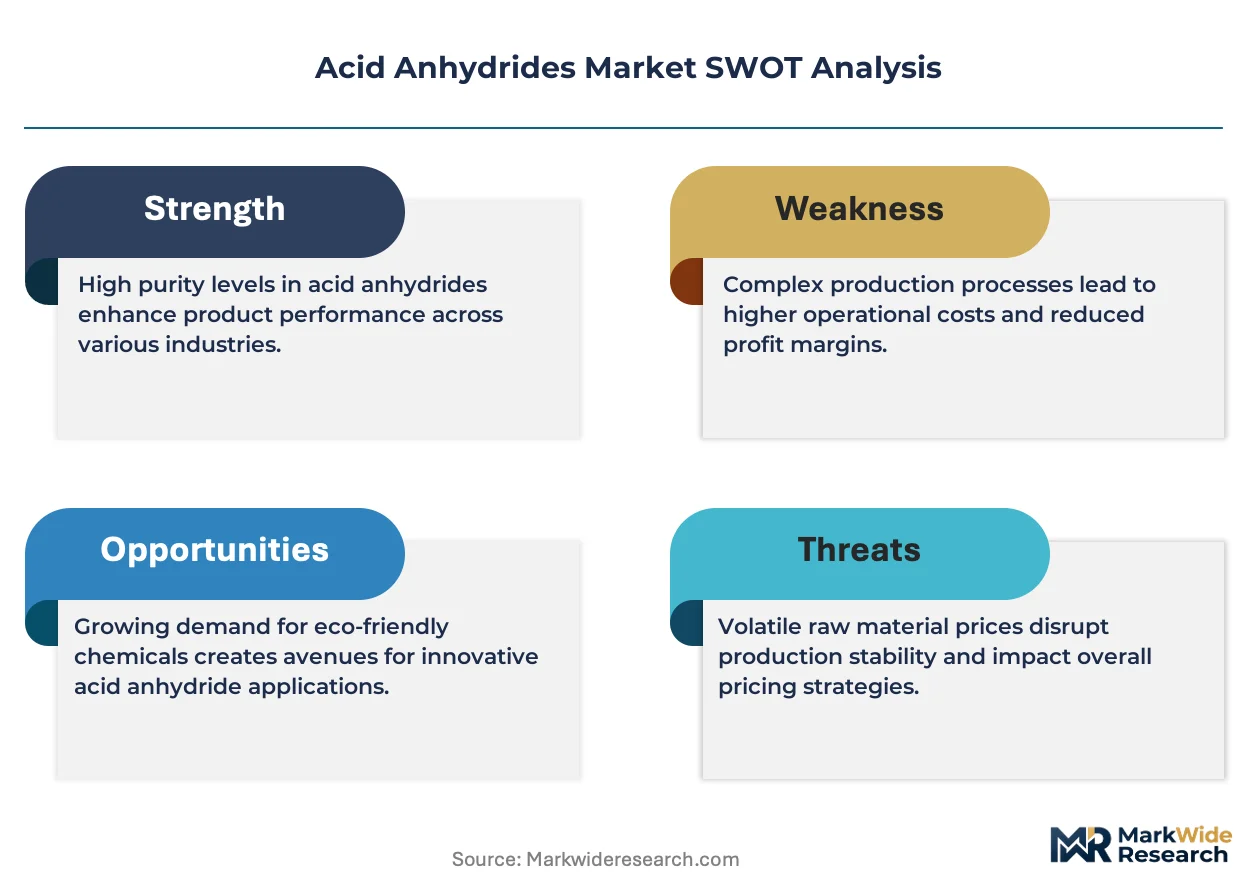
REACH authorization requirements are forcing European phthalic anhydride producers into costly purification upgrades, while China's dual carbon goals compress energy margins for maleic anhydride facilities in Shandong province. This regulatory divergence is fragmenting competitive cost structures across major supply basins.
Growth Catalysts
- Bio-based succinic anhydride fermentation:Pharmaceutical manufacturers are expanding active ingredient synthesis capacity using renewable feedstock routes. This process shift reduces petrochemical dependency for high-purity derivatives.
- Unsaturated polyester resin demand:Construction and marine applications in China absorb expanding maleic anhydride output from domestic crackers. Marine composite hull fabrication drives volume concentration in coastal provinces.
- REACH plasticizer authorization:ECHA restrictions on legacy chemistries are redirecting formulation demand toward trimellitic anhydride alternatives. Coatings-grade producers capture margin premiums from compliance-driven substitution.
Market Restraints
- Ortho-xylene feedstock volatility:Aromatics pricing swings compress phthalic anhydride margin predictability for European crackers. Naphtha-linked cost structures expose producers to refinery output fluctuations.
- Shandong-Jiangsu supply concentration:Over half of China's maleic anhydride capacity clusters in two provinces vulnerable to MEE emissions enforcement. Regional shutdown risk disrupts export contract reliability.
- Biodegradable polymer substitution threat:Polylactic acid and starch-based alternatives displace conventional plasticizer demand in flexible packaging applications. Food-contact regulations accelerate this material pivot.
Strategic Opportunities
- India specialty ester derivatives:CDSCO pharmaceutical manufacturing incentives attract investment in succinic anhydride downstream processing. Domestic active ingredient synthesis reduces import dependency for generic drug producers.
- Automotive coatings electrification:High-performance powder coating demand for EV battery enclosures expands trimellitic anhydride consumption. Thermal stability requirements favor anhydride-cured resin systems.
- EU Green Deal bio-based mandates:Renewable content thresholds in packaging regulations create pull-through for fermentation-derived succinic anhydride. Certification schemes differentiate premium-grade supply.
Industry Challenges
- Catalytic oxidation catalyst replacement cycles:Fixed-bed reactor maintenance demands specialized technical labor scarce in emerging production regions. VAM-based catalyst handling requires certified safety protocols.
- Multi-jurisdiction REACH-EPA-MEE compliance:Divergent purity and emissions standards force producers to maintain parallel quality systems. Documentation burden extends certification timelines for export shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acid Anhydrides Market |
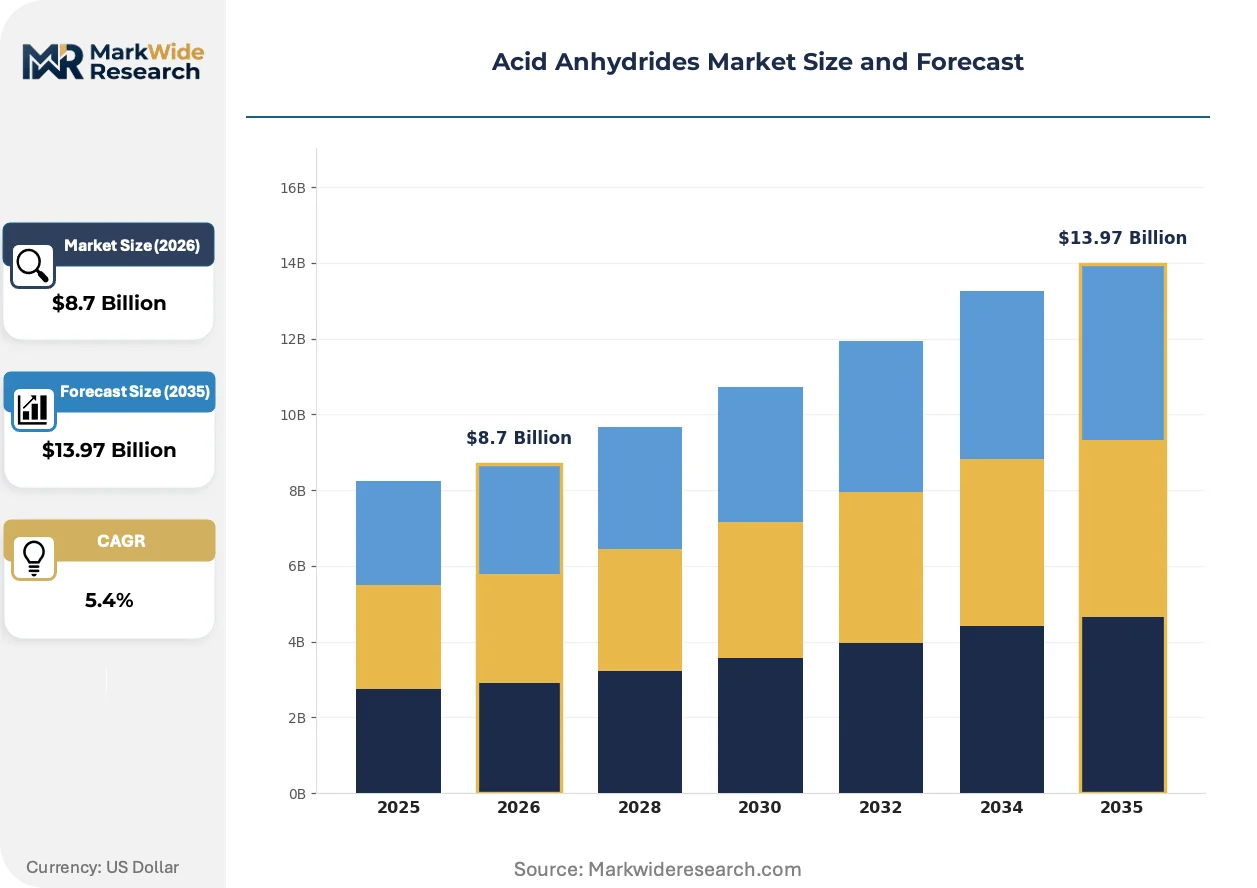
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phthalic Anhydride, Maleic Anhydride, Succinic Anhydride, Trimellitic Anhydride Application: Plastics, Coatings, Adhesives, Dyes End Use Industry: Construction, Automotive, Electronics, Textile Packaging Type: Bags, Drums, Containers, Bulk |
| Companies Covered | Celanese Corporation, BASF SE, Eastman Chemical Company, Huntsman Corporation, SABIC, LANXESS, DuPont, Jubilant Life Sciences, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Anhydrides Market Evolving Landscape
Process intensification and regulatory chemistry substitution are compressing legacy production economics while opening margin pools for bio-based and high-purity grades. Technology convergence between fermentation and petrochemical routes is blurring traditional feedstock boundaries.
Continuous maleic anhydride production via fluidized-bed catalytic oxidation is unifying energy efficiency with output scale for integrated resin producers. Unsaturated polyester compounders in China's coastal provinces adopt these systems to meet MEE intensity benchmarks. The technology is compressing batch-reactor economics for standalone facilities lacking captive offtake.
ECHA's REACH authorization list expansion restricts di(2-ethylhexyl) phthalate plasticizers in medical device and childcare applications. European phthalic anhydride demand is rotating toward trimellitic and tetrahydrophthalic grades with superior migration resistance. Automotive interior specifications now exclude legacy chemistries from supplier qualification.
Pharmaceutical API manufacturers are consolidating procurement around certified bio-based succinic anhydride with full mass-balance documentation. CDSCO and EMA filing requirements now specify renewable feedstock provenance for excipient-grade materials. Indian generic producers lead this specification tightening to secure EU and US export approvals.
Acid Anhydrides Market Segmentation
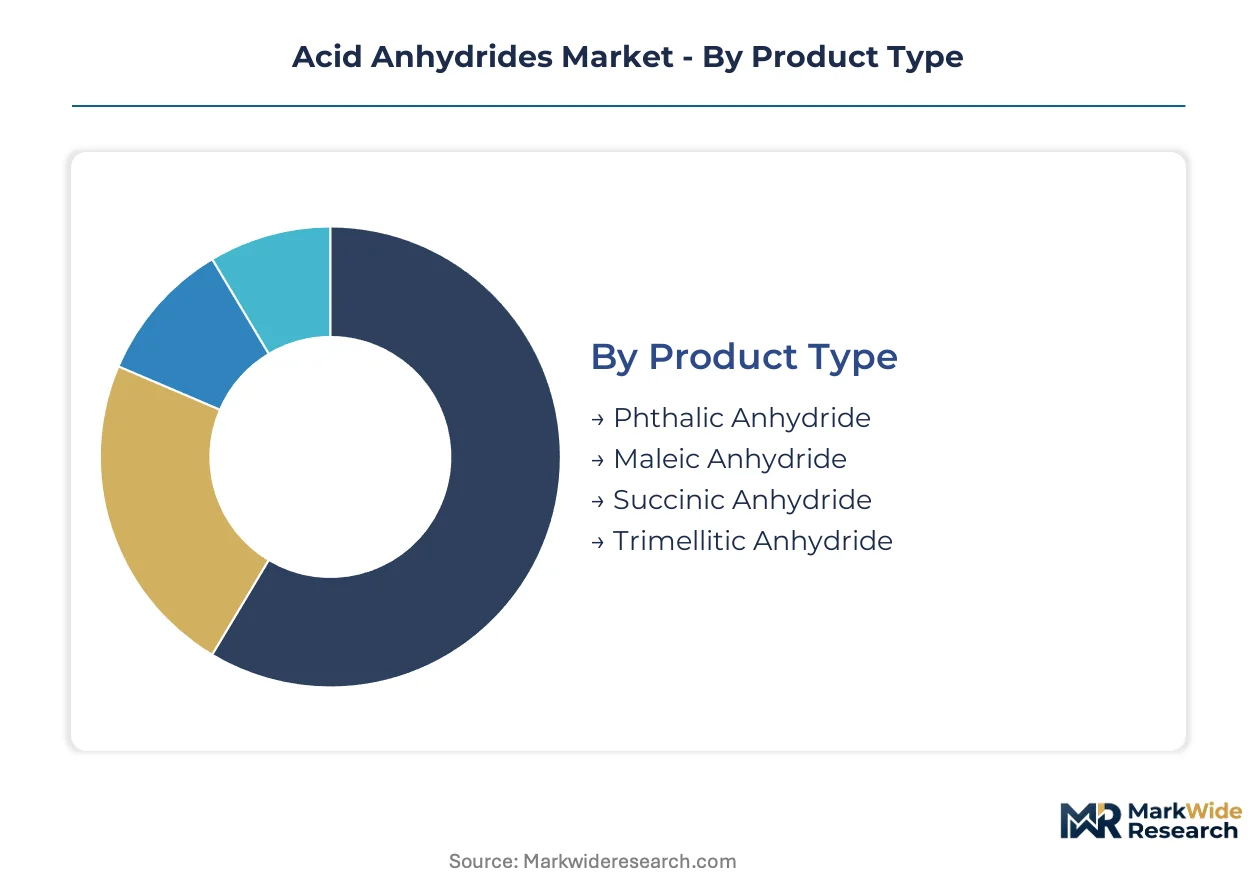
Acid anhydride producers face divergent margin pressures across product grades and application tiers. Segmentation reveals where purification investments yield compliance premiums versus commodity exposure.
Product Type:
Supply concentration clusters around maleic and phthalic anhydride, with fermentation-derived succinic anhydride disrupting traditional feedstock economics.
- Maleic Anhydride:Manufactured via n-butane catalytic oxidation in fluidized-bed reactors, this grade dominates unsaturated polyester resin feedstock for China's marine construction sector. Shandong province crackers absorb over half of domestic output.
- Phthalic Anhydride:Ortho-xylene oxidation yields plasticizer-grade material constrained by EPA NESHAP emissions limits in US facilities and REACH authorization hurdles in Europe. Coatings-grade purification commands cost premiums.
- Succinic Anhydride:Bio-based fermentation routes from renewable carbohydrates serve pharmaceutical API synthesis with mass-balance certification. CDSCO filing requirements now specify renewable provenance for excipient grades.
- Trimellitic Anhydride:High-purity grade for automotive powder coatings with superior thermal stability. EV battery enclosure specifications favor anhydride-cured systems over legacy chemistries.
Today's leader: Maleic Anhydride. Tomorrow's challenger: Succinic Anhydride.
Application:
Cost tier stratification separates commodity plasticizer volumes from specialty coatings margins.
- Plastics:Phthalic anhydride plasticizers face biodegradable polymer substitution from polylactic acid in food-contact flexible packaging. ECHA REACH restrictions accelerate formulation pivot toward trimellitic alternatives.
- Coatings:Trimellitic and tetrahydrophthalic anhydride grades capture premium positioning in automotive OEM finishes. Thermal stability specifications for EV battery housings expand high-performance resin demand.
- Adhesives:Maleic anhydride-grafted polyolefins serve packaging lamination with bonding strength requirements. Construction sector demand concentrates in China's coastal province manufacturing clusters.
- Dyes:Phthalic anhydride derivatives for pigment intermediates face margin compression from Asian supply expansion. Specialty azo chemistry retains niche specification value.
Plastics maintains volume dominance. Coatings delivers margin expansion.
End Use Industry:
Customer type segmentation distinguishes project-driven construction demand from specification-intensive automotive procurement.
- Construction:Unsaturated polyester resins for marine composite hulls and corrosion-resistant piping absorb maleic anhydride volume. China's coastal province shipyards concentrate procurement.
- Automotive:Interior trim specifications now exclude legacy phthalate plasticizers per ECHA authorization lists. Powder coating demand for EV battery enclosures expands trimellitic anhydride consumption.
- Electronics:High-purity succinic anhydride serves semiconductor encapsulant synthesis with ionic contamination limits. Cleanroom-grade packaging commands logistics premiums.
- Textile:Phthalic anhydride-based polyester fiber intermediates face sustainability audit pressure. Bio-based alternatives penetrate premium apparel supply chains.
Construction anchors current volume. Automotive drives specification upgrading.
Packaging Type:
Volume scale determines packaging economics, with bulk shipments dominating integrated resin operations and drums serving specialty chemical distributors.
- Bags:Multi-wall paper packaging for powdered phthalic anhydride flakes in plasticizer compounder shipments. Moisture sensitivity requires vapor barrier specifications.
- Drums:Steel and fiber containers for liquid maleic anhydride in adhesive manufacturer deliveries. UN certification for hazardous material transport adds compliance cost.
- Containers:Intermediate bulk containers for coatings-grade trimellitic anhydride in automotive supplier JIT programs. Returnable packaging reduces per-shipment waste.
- Bulk:Railcar and tanker shipments for captive maleic anhydride transfer to integrated unsaturated polyester resin plants. Shandong province crackers favor pipeline connectivity.
Bulk dominates tonnage economics. Drums sustain specialty distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineering talent clusters in Germany's Rhine-Neckar region and China's Shandong province anchor the industry's technical workforce. These concentrations sustain process optimization capabilities across maleic and phthalic anhydride production routes. Regulatory divergence between EPA, REACH, and MEE frameworks fragments competitive cost structures.
United States
Marine composite hull fabrication and EV battery enclosure coatings drive maleic and trimellitic anhydride consumption. EPA NESHAP emissions standards constrain phthalic anhydride plant operations in Texas and Louisiana. Gulf Coast petrochemical corridors maintain integrated maleic anhydride capacity serving domestic unsaturated polyester resin compounders.
Germany
Automotive OEM powder coating specifications and pharmaceutical API synthesis sustain high-purity trimellitic and succinic anhydride demand. ECHA REACH authorization requirements restrict legacy phthalate plasticizers in medical device applications. BASF SE's Ludwigshafen complex anchors European phthalic anhydride output with integrated purification infrastructure.
China
Construction sector unsaturated polyester resins and marine composite manufacturing absorb expanding maleic anhydride volumes. MEE dual carbon goals tighten energy-intensity benchmarks for Shandong and Jiangsu province crackers. Qingdao and Ningbo coastal clusters concentrate over half of domestic maleic anhydride capacity serving export contract flows.
India
Generic pharmaceutical active ingredient synthesis and specialty ester derivative manufacturing expand succinic anhydride procurement. CDSCO filing incentives attract investment in excipient-grade production with renewable feedstock documentation. Gujarat and Maharashtra chemical corridors develop downstream processing capacity reducing import dependency.
Japan
Semiconductor encapsulant synthesis and high-performance automotive coatings sustain ultra-purity succinic and trimellitic anhydride demand. METI carbon neutrality roadmaps pressure energy-intensive catalytic oxidation facilities. Chubu region chemical producers invest in process intensification to maintain specification leadership in electronics-grade materials.
Acid Anhydrides Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct margin tiers in the acid anhydrides market. Integrated petrochemical majors leverage captive feedstock access and captive offtake to resin operations, while fermentation-based specialists capture premium positioning in pharmaceutical-grade succinic anhydride. Three strategic archetypes dominate: scale-driven commodity producers, purity-focused specialty manufacturers, and bio-based route innovators. Capacity expansion in China's coastal provinces and REACH-driven purification upgrades in Europe represent the dominant competitive moves reshaping regional cost positions.
Among diversified chemical majors with integrated complexes, BASF SE and Eastman Chemical Company exemplify scale-and-scope archetypes spanning multiple anhydride grades and derivative portfolios. Huntsman Corporation occupies a position within the specialty intermediates tier, while SABIC represents Middle Eastern feedstock-advantaged production. Celanese Corporation sits within the acetyls-derived chemistry specialists, and LANXESS exemplifies the European purification-upgrade archetype responding to ECHA authorization requirements. These six entities collectively represent the structural diversity across commodity, specialty, and regulatory-response positioning vectors in the current competitive landscape.
| Leading Market Players |
|---|
| Celanese Corporation |
| BASF SE |
| Eastman Chemical Company |
| Huntsman Corporation |
| SABIC |
| LANXESS |
| DuPont |
| Jubilant Life Sciences |
| Arkema |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement teams and pharmaceutical API manufacturers concentrate demand for high-purity acid anhydride grades, anchoring a contract-based long-term offtake model that rewards certification investment and penalizes spot-market exposure. This buyer concentration amplifies pricing power for REACH-compliant European producers while compressing margins for commodity-grade exporters facing MEE enforcement in Shandong province.
Pricing Analysis
Bundled technical service and certification documentation commands premiums over unbundled commodity transactions, with three-tier pricing structure across pharmaceutical-grade, coatings-grade, and industrial-grade levels. Price differentiation rests on REACH mass-balance certification and CDSCO filing support, with bio-based succinic anhydride capturing the widest spreads. Cost compression in phthalic anhydride plasticizers is intensifying because biodegradable polymer substitution erodes volume leverage. Generic drug manufacturers exhibit highest price sensitivity; EV battery coating formulators show least.
Supply Chain Analysis
Dual-sourcing requirements from automotive and pharmaceutical buyers mandate multi-supplier qualification across China's Shandong-Jiangsu corridor, Germany's Ludwigshafen complex, and India's Gujarat chemical belt. Feedstock dependencies draw from ortho-xylene naphtha streams, n-butane crackers, and renewable carbohydrate fermentation. Single-source vulnerability concentrates in maleic anhydride fluidized-bed catalyst supply. Distribution runs through integrated railcar networks for captive resin operations and specialty chemical distributors for drum-scale pharmaceutical deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acid anhydrides market functions as a geographic-arbitrage play where REACH-driven purification costs in Europe diverge from MEE energy-intensity constraints in China, creating margin dispersion that rewards feedstock-flexible capacity positioning.
For Market Incumbents: Deepen backward integration into n-butane and bio-based carbohydrate feedstocks to insulate margin structures from ortho-xylene volatility and fermentation substrate competition. Prioritize Ludwigshafen-style integrated complexes that capture purification premiums while defending against specialty ester derivative specialists. Lock in long-term offtake with automotive OEMs specifying trimellitic anhydride for EV battery enclosures. For New Entrants and Emerging Players: Specialty chemical distributors represent the most accessible channel partner type for penetrating fragmented coatings compounder markets without captive resin operations. Target India's CDSCO-filing pharmaceutical segment where renewable-provenance succinic anhydride commands specification premiums and import substitution incentives reduce incumbent lock-in. Lead with mass-balance certification and excipient-grade documentation as the primary go-to-market wedge. For Investors and Strategic Acquirers: Integrated petrochemical majors with maleic anhydride captive offtake are the most active acquirer in this space, consolidating fermentation-based succinic anhydride capacity to secure pharmaceutical-grade positioning. Five-to-ten year viability hinges on bio-based route economics achieving cost parity with catalytic oxidation. Acquisition target archetype: pure-play fermentation specialists with CDSCO and EMA filing relationships. Monitor ECHA REACH authorization list expansion as the signal to watch for inflection in plasticizer substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Fermentation-derived succinic anhydride secures pharmaceutical API contracts requiring renewable provenance documentation. |
| REACH Purification Infrastructure Upgrade | Coatings-grade phthalic anhydride producers capture margin premiums from ECHA authorization-driven formulation substitution. |
| Long-term Supply Agreement with Automotive OEMs | Trimellitic anhydride offtake for EV battery enclosure powder coatings locks in specification-driven volume. |
| Joint Venture in Shandong Coastal Cluster | Fluidized-bed maleic anhydride capacity meets MEE dual carbon intensity benchmarks while serving marine resin demand. |
| Green Manufacturing Transition | CDSCO and EMA filing requirements now specify renewable feedstock provenance for excipient-grade materials. |
Research Methodology
Multiple input streams — plant manager interviews at Shandong and Ludwigshafen facilities, procurement lead discussions at automotive OEMs and pharmaceutical API manufacturers, and technical R&D director consultations — were reconciled against customs and trade data, Cefic industry reports, and SEC 10-K chemical segment disclosures. Bottom-up capacity and utilization estimates triangulated with top-down end-use demand modeling across plastics, coatings, adhesives, and pharmaceutical synthesis applications.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning product grade tier, end-use industry concentration, packaging format economics, and regional production hub regulatory intensity. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion schedules, incorporating maleic anhydride fluidized-bed adoption curves and bio-based succinic anhydride fermentation yield improvements as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA REACH authorization scope expansion, MEE enforcement intensity in Shandong-Jiangsu, and biodegradable polymer substitution rates in flexible packaging. Deviation in ortho-xylene-naphtha price correlation or fermentation substrate cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Etidronic Acid Market
Chemicals
Ferric Fluoride Market
Chemicals
1, 4 Butanediol Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Phenylethyl Market
Chemicals
North America Construction Chemicals Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Amine Oxide Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Di Nitro Toluene Market
Chemicals
Hydrazine Market
Chemicals
1,3-Dibromoadamantane Market