
 US Tile Adhesive Market | 2026-2036
US Tile Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
US Tile Adhesive Market Analytics
Southeastern US manufacturing expansion is reshaping supply proximity for major adhesive suppliers. Mapei Corporation leverages its regional blending capacity to serve Florida and Georgia construction corridors. Laticrete International Inc anchors the premium waterproofing segment with specialized thin-set systems for wet-area applications. Custom Building Products competes through broad retail distribution and contractor loyalty programs.
Tile adhesive comprises cementitious, resin, or hybrid binders formulated to bond ceramic, porcelain, and natural stone tiles to substrates, with open time, shear strength, and water resistance as critical performance parameters. The material enables permanent, flexible installation across flooring and vertical surfaces in residential, commercial, and industrial environments. Thin-set formulations dominate volume due to cost efficiency and versatility across standard applications. Epoxy adhesives command premium positioning in industrial and wet-area installations where chemical resistance and zero-shrinkage performance justify higher material cost. Modified polymer technology is expanding fastest as contractors seek extended open times and reduced lippage in large-format tile work.
EPA VOC content limits under 40 CFR Part 59 shape product formulation requirements for interior adhesives, while OSHA workplace exposure standards influence contractor handling protocols and PPE specifications. State-level California Air Resources Board regulations and pending updates to LEED v5 materials criteria are tightening emissions thresholds and rewarding EPD-certified products. Stakeholders must monitor regulatory divergence between federal baseline and state-adopted standards when planning formulation roadmaps and regional SKU strategies.
Market Dynamics
Reformulation pressure from EPA VOC limits under 40 CFR Part 59 is forcing manufacturers to re-engineer solvent-based systems toward water-borne and zero-emission chemistries, reshaping R&D allocation and raw material sourcing across the value chain.
Growth Catalysts
- Single-family housing retrofits:Aging housing stock across the Sun Belt is generating sustained pull for thin-set and modified polymer systems in kitchen and bathroom renovations.
- OSHA workplace exposure standards:Stricter contractor handling protocols are accelerating professional-grade product adoption over consumer DIY alternatives in commercial installations.
- Modified polymer technology:Extended open times and reduced lippage characteristics are capturing share in large-format tile work across premium residential and hospitality verticals.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production and freight cost swings compress margins for cementitious adhesive formulations.
- Epoxy raw material concentration:Bisphenol-A and amine hardener supply chains cluster with Gulf Coast petrochemical producers, exposing formulators to hurricane-related disruption.
- California Air Resources Board thresholds:Divergent state-level emission limits complicate national SKU rationalization and inventory planning.
Strategic Opportunities
- Florida waterproofing corridor:Humidity-driven mold-resistant specifications in multifamily construction create pull for specialized thin-set and membrane-integrated systems.
- LEED v5 materials criteria:Pending EPD certification rewards offer first-mover advantage for manufacturers with verified lifecycle data.
- Pro-channel digital procurement:Contractor loyalty platforms and direct-to-crew mobile ordering are bypassing traditional distributor markups in metropolitan construction markets.
Industry Challenges
- Certified installer scarcity:Epoxy and large-format substrate preparation techniques require specialized training that outpaces vocational pipeline output.
- Reformulation timeline compression:California's accelerating VOC phase-down schedules force product redevelopment cycles that strain technical service resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tile Adhesive Market |
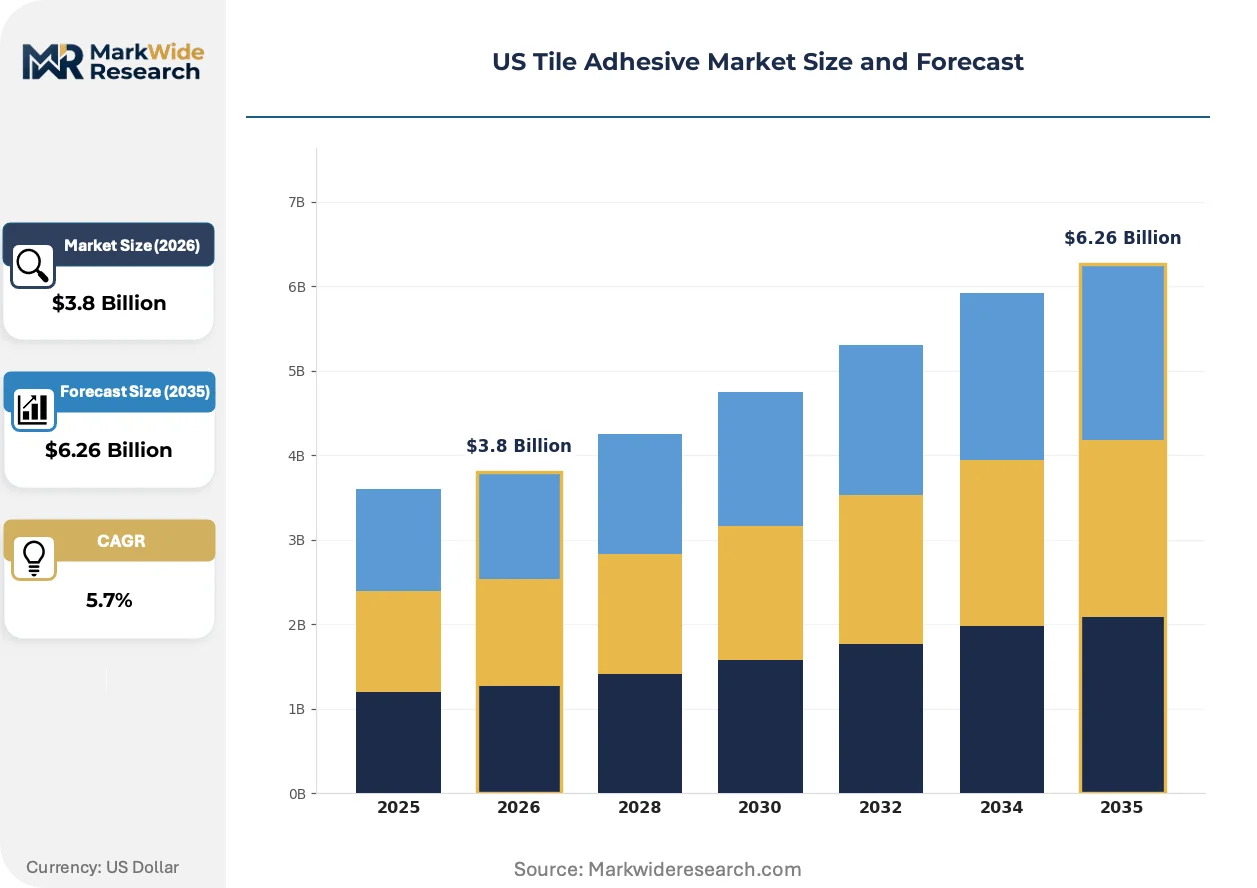
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-set, Epoxy, Organic, Modified Application: Flooring, Wall Installation, Wet Areas, Outdoor End User: Residential, Commercial, Industrial, DIY Technology: Cement-based, Reaction Resin, Solvent-based, Hybrid |
| Companies Covered | Laticrete International Inc, Mapei Corporation, Bostik Inc, Custom Building Products, Henry Company, Ardex Group, Sika Corporation, Weber, Dunlop Adhesives, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tile Adhesive Market Evolving Landscape
Material science advances and specification-driven procurement are converging to redefine performance benchmarks and channel economics across the US tile adhesive value chain.
Modified polymer thin-set technology is migrating from traditional unmodified cementitious formulations in commercial flooring specifications. Multifamily developers and hospitality contractors are specifying polymer-modified systems for crack-isolation and extended open-time performance on accelerated construction schedules. The shift is compressing demand for basic cementitious products in projects above 10,000 square feet.
EPA enforcement of 40 CFR Part 59 Subpart M is tightening VOC content verification for interior adhesives sold in residential and commercial buildings. Manufacturers face expanded record-keeping obligations and third-party testing requirements that elevate compliance costs for smaller formulators. Water-based acrylic and hybrid systems are capturing specification share in California and Northeast corridor projects ahead of federal baseline adoption.
Large-format tile specifications are reshaping contractor adhesive selection criteria across luxury residential and commercial segments. Projects specifying tiles exceeding 24 inches on any dimension require enhanced bond strength and reduced shrinkage characteristics that favor premium modified thin-set and epoxy systems. This specification creep is most visible in Texas and Florida metropolitan markets where open-concept designs dominate new construction.
US Tile Adhesive Market Segmentation
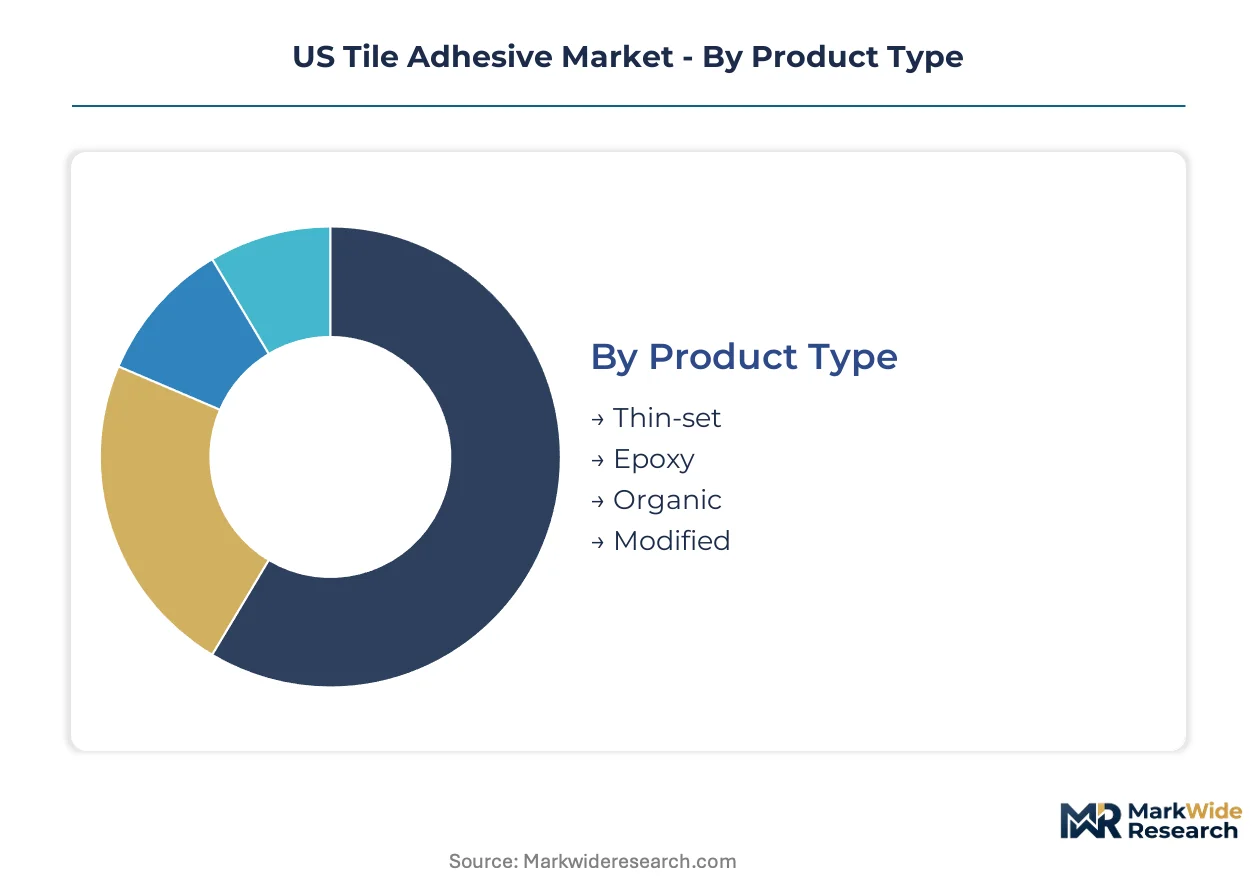
Tile adhesive specification varies sharply by installation environment and performance requirements, creating distinct service and technical support needs across each segment. Contractors and distributors must match product chemistry to substrate conditions, moisture exposure, and tile format to avoid failure liability and callback costs.
Product Type:
After-sales service intensity runs highest for epoxy and modified systems, where applicator training, substrate testing, and warranty support separate premium suppliers from commodity competitors.
- Thin-set:Portland cement-based formulations with sand aggregate provide economical bonding for standard ceramic and porcelain tiles. Demand concentrates in Sun Belt residential retrofits where cost-conscious contractors favor proven performance on concrete substrates.
- Epoxy:Two-component reaction resin systems deliver zero-shrinkage bonds and chemical resistance for industrial floors and commercial kitchens. Florida and Texas hospitality projects specify these for 24/7 operational environments where downtime carries steep revenue penalties.
- Organic:Natural resin and bitumen-based adhesives serve specialized acoustic and vibration-dampening applications in multifamily construction.
- Modified:Polymer-enhanced cementitious systems extend open time and improve flexibility for large-format tile work.
By volume, thin-set leads. By growth pace, modified formulations are climbing the fastest.
Application:
Cost tier stratification separates commodity flooring work from premium wet-area and outdoor specifications requiring enhanced waterproofing membranes.
- Flooring:High-traffic commercial installations specify modified thin-set and epoxy for crack isolation and point-load distribution. Demand clusters in Texas metropolitan retail and logistics construction where accelerated schedules favor fast-cure systems.
- Wall Installation:Vertical applications require non-sag formulations with enhanced thixotropy for large-format porcelain. Premium residential towers in Miami and Atlanta drive specification of extended open-time products.
- Wet Areas:Shower pans, steam rooms, and pool decks mandate waterproof thin-set integrated with liquid-applied membranes. Florida multifamily developers face mold-resistant building code requirements that elevate material specifications.
- Outdoor:Freeze-thaw resistant formulations serve plaza and terrace installations in northern climate zones.
Flooring commands the largest volume share. Wet areas show the steepest specification upgrade trajectory as code enforcement tightens.
End User:
Customer type determines procurement channel, with professional contractors demanding bulk pricing and technical field support while DIY segments prioritize retail availability and simplified application.
- Residential:Single-family renovation and new construction generate steady pull for standard thin-set and entry-level modified systems. Sun Belt housing markets in Arizona, Nevada, and Georgia concentrate volume.
- Commercial:General contractors on hospitality, healthcare, and retail projects specify warrantied systems with certified installer networks. Procurement runs through pro-channel distributors with project-specific submittal support.
- Industrial:Food processing, pharmaceutical, and heavy manufacturing facilities specify chemical-resistant epoxy with documented slip resistance and cleanability credentials.
- DIY:Home center retail channels serve bathroom and kitchen refresh projects with pre-mixed and simplified application products.
Residential end-use leads in unit volume. Commercial specifications are gaining share fastest as pro-channel loyalty programs consolidate contractor purchasing.
Technology:
Supply concentration in cement production and petrochemical feedstocks shapes regional cost structures and formulation availability across technology platforms.
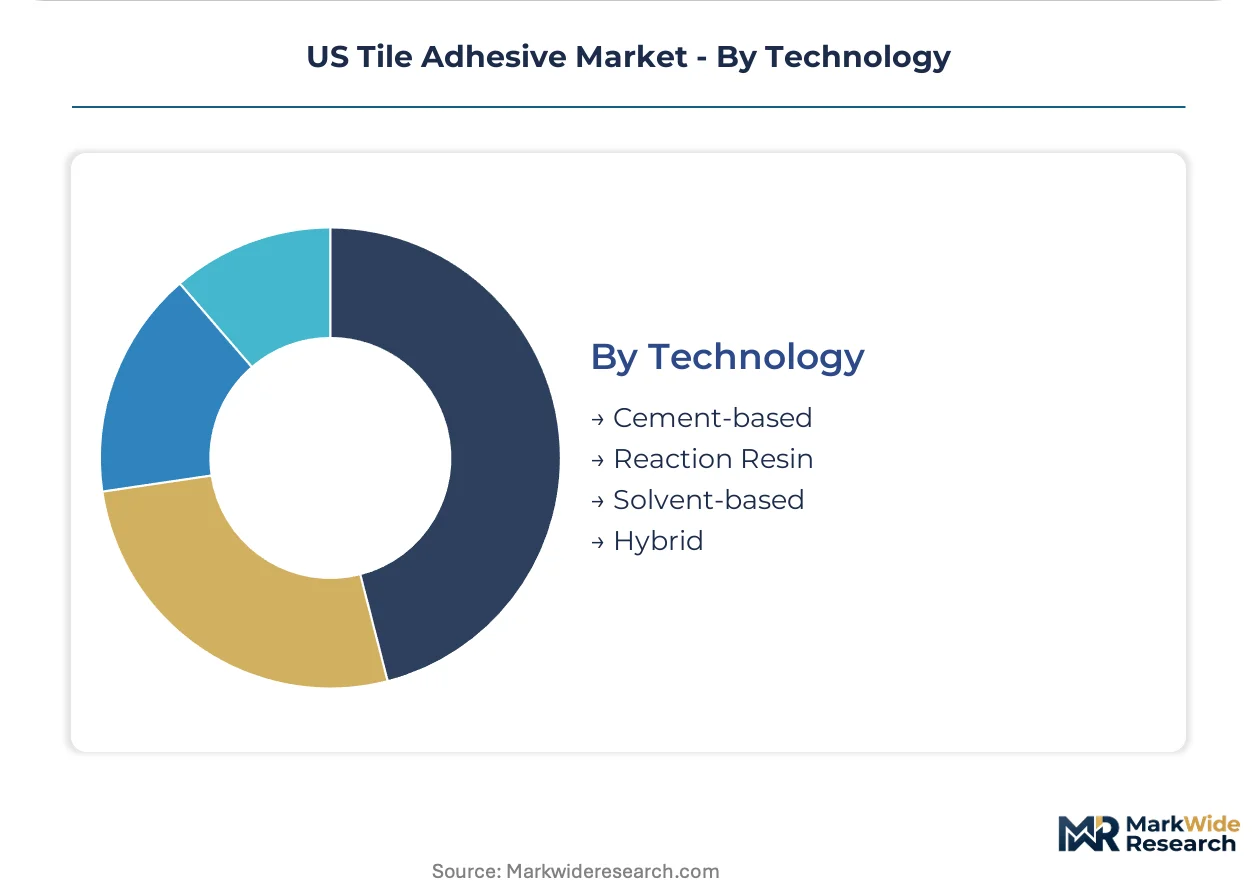
- Cement-based:Unmodified and polymer-modified Portland cement systems dominate unit economics and distribution reach. Clinker sourcing from southeastern US kilns supports regional blending operations serving Florida and Georgia construction corridors.
- Reaction Resin:Epoxy and polyurethane chemistries command premium positioning where chemical resistance and zero-shrinkage performance justify material cost multiples. Bisphenol-A and amine hardener supply chains cluster with Gulf Coast producers.
- Solvent-based:Legacy formulations face EPA VOC phase-down pressure under 40 CFR Part 59, with water-borne replacements capturing specification share in California and Northeast markets ahead of federal adoption.
- Hybrid:Acrylic-cement and silane-modified systems bridge performance gaps for specialized crack-isolation and rapid-return-to-service applications.
Cement-based technology leads in volume penetration. Reaction resin systems are expanding most quickly in industrial and wet-area specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeastern blending operations cluster near Georgia and Florida construction corridors, positioning regional supply within four-hour delivery windows of the Sun Belt's densest project activity. Texas and California operate as independent demand poles with distinct regulatory timelines and specification cultures.
Southeast
Florida multifamily construction drives waterproofing-grade thin-set consumption as humidity-resistant building codes tighten. EPA Region 4 enforcement of 40 CFR Part 59 shapes interior adhesive formulations sold across Georgia, Alabama, and the Carolinas. Mapei Corporation's Dalton, Georgia blending campus supplies modified polymer systems to Atlanta and Orlando metropolitan buildouts.
Southwest
Texas single-family housing starts concentrate demand for standard cementitious thin-set in Dallas-Fort Worth and Houston exurbs. OSHA regional offices in Dallas and Houston monitor contractor handling compliance on commercial hospitality projects. Large-format tile specifications in Austin and San Antonio premium residential towers favor extended open-time modified systems.
West Coast
California Air Resources Board VOC thresholds under 50 grams per liter force accelerated reformulation of solvent-based legacy products ahead of federal baselines. CARB's 2027 phase-down timeline compresses product development cycles for manufacturers serving Los Angeles and San Francisco Bay Area construction. Water-based acrylic systems capture specification share in Seattle and Portland multifamily retrofits as Washington and Oregon adopt California-aligned emission standards.
Mid-Atlantic
New York Metro commercial renovation generates steady pull for epoxy systems in 24/7 operational environments where downtime carries revenue penalties. EPA Region 2 record-keeping requirements elevate compliance costs for smaller formulators serving Philadelphia and Baltimore contractor channels. Custom Building Products' distribution network anchors retail and pro-channel supply across the Northeast corridor.
Mountain West
Denver and Phoenix residential construction combines freeze-thaw cycling with extreme aridity, demanding flexible modified thin-set formulations for outdoor terrace and plaza installations. Colorado and Arizona state environmental agencies track federal VOC baselines without California-style acceleration. Regional distributors stock hybrid acrylic-cement systems for rapid-return-to-service specifications in ski resort hospitality renovations.
US Tile Adhesive Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in binder chemistry and aggregate sourcing. The US tile adhesive sector structures around three strategic tiers: multinational construction chemical conglomerates with captive raw material positions, regional blending specialists serving pro-channel distributors, and retail-focused formulators competing on shelf presence and contractor loyalty programs. Consolidation pressure runs highest among mid-scale formulators lacking either backward integration into polymer modifiers or forward control over specification relationships. Capacity expansion and geographic SKU rationalization dominate competitive moves as manufacturers navigate divergent state-level emission standards.
Among US-based and European-anchored suppliers, Laticrete International Inc, Mapei Corporation, and Custom Building Products occupy distinct archetype positions. Laticrete exemplifies the premium waterproofing specialist with certified installer network dependency. Mapei represents the scale-integrated multinational with regional blending proximity to Sun Belt demand. Custom Building Products anchors the retail-pro hybrid tier, competing through broad distribution reach and contractor loyalty platforms rather than technical specification depth. These three patterns—specialist certification, scale integration, and channel breadth—structure competitive positioning across residential renovation and commercial new construction verticals.
| Leading Market Players |
|---|
| Laticrete International Inc |
| Mapei Corporation |
| Bostik Inc |
| Custom Building Products |
| Henry Company |
| Ardex Group |
| Sika Corporation |
| Weber |
| Dunlop Adhesives |
| Others |
Value Network & Pricing Analysis
Portland cement price volatility compresses margin structures across formulation tiers while simultaneously forcing geographic concentration of blending operations near southeastern US kilns. This input-cost instability widens spreads between commodity thin-set and premium modified systems as manufacturers pass through energy-intensive clinker expenses.
Pricing Analysis
EPA 40 CFR Part 59 dictates the pricing tier structure across interior adhesive categories, separating water-based systems meeting Subpart M limits from legacy solvent-bearing formulations facing compliance penalties. Price differentiation rests on certification burden and regional regulatory alignment, with California CARB-tier products commanding premiums over federal-baseline alternatives. Cost compression in standard cementitious thin-set is intensifying because freight-adjusted clinker sourcing favors scale-integrated multinationals. Residential renovation contractors exhibit highest price sensitivity, while commercial hospitality developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Upstream polymer modifier and amine hardener production clusters in the United States Gulf Coast, China, and Germany, creating feedstock dependencies for premium formulation tiers. Raw material sourcing draws from southeastern US Portland cement kilns, Texas petrochemical complexes, and imported bisphenol-A derivatives. Single-source vulnerability runs through Gulf Coast hurricane exposure disrupting epoxy hardener availability. Distribution runs through pro-channel distributors with project submittal capabilities and retail home center networks serving DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installer pipeline gaps constrain premium segment expansion, creating acquisition targets among technical training providers and field service organizations that can close capability scarcity.
For Market Incumbents: Build certification-network moats by acquiring regional training academies and expanding warrantied installer coverage in Florida and Texas metropolitan corridors. Cement-based formulation scale in the Southeast defends against margin erosion from Portland cement price swings. Prioritize backward integration into polymer modifier production to reduce Gulf Coast petrochemical dependency. For New Entrants and Emerging Players: Mountain West freeze-thaw specification gaps offer white-space entry with hybrid acrylic-cement systems for Denver and Phoenix outdoor terrace markets. Pro-channel digital procurement platforms remain underpenetrated outside coastal metropolitan construction corridors, enabling direct-to-crew mobile ordering plays. Target certified installer scarcity as a service-layer wedge rather than competing on formulation chemistry alone. For Investors and Strategic Acquirers: CARB's 2027 VOC phase-down timeline reshapes the acquisition landscape toward water-borne technology specialists with verified EPD certification pathways. Long-term viability favors scale-integrated formulators with captive southeastern blending capacity over asset-light distributors. Monitor EPA Region 4 enforcement intensity as the signal indicating compliance-cost acceleration for smaller legacy formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Modifiers | Captive supply of modified thin-set inputs reduces Gulf Coast petrochemical exposure. |
| EPD Certification Investment | Verified lifecycle data captures LEED v5 specification rewards ahead of competitor filings. |
| Pro-Channel Digital Platform Launch | Direct-to-crew mobile ordering bypasses traditional distributor markups in metropolitan markets. |
| Regional Blending Capacity Expansion | Dalton, Georgia-style campuses position supply within four-hour delivery windows of Sun Belt demand. |
| Certified Installer Network Acquisition | Technical training providers close capability scarcity constraining epoxy and large-format segments. |
Research Methodology
The analysis maps thin-set, epoxy, organic, and modified formulation sub-sectors, each validated through contractor interviews, distributor procurement leads, blending plant managers, and regulatory compliance officers. Primary fieldwork combined with secondary validation from EPA 40 CFR Part 59 filings, CARB regulatory updates, SEC construction chemical disclosures, and Portland cement trade association data. Bottom-up project pipeline assessments triangulate against top-down housing start and commercial construction forecasts.
Assumptions held single-family housing retrofit intensity and EPA enforcement patterns fixed while varying state-level VOC adoption timelines and clinker energy cost trajectories across the projection horizon. Segmentation modeling spanned product chemistry, application environment, end-user procurement channel, and technology platform. CAGRs derive from volume-weighted segment growth rates applied to baseline consumption estimates. Forecast inputs incorporated Sun Belt humidity-driven waterproofing specifications and large-format tile adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational construction chemical conglomerates would shift outcomes through accelerated price competition. Cross-checking against National Association of Home Builders remodeling indices and Dodge Construction Network commercial starts data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market