
 Global Curing Agents Market | 2026-2036
Global Curing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Curing Agents Market Foresight
REACH registration and EPA TSCA qualification is bifurcating the competitive landscape into compliant multinationals and regionally constrained suppliers. BASF SE leverages its integrated amine production network across Ludwigshafen and Antwerp to sustain feedstock security for European coatings customers. Huntsman International LLC anchors its position through specialized cycloaliphatic amine portfolios serving aerospace laminators in the United States and Germany. Evonik Industries AG differentiates via high-purity polyamide technologies that dominate wind blade manufacturing specifications in Northern Europe.
Curing agents are reactive chemicals—typically amines, anhydrides, or mercaptans—that crosslink epoxy resins through addition or catalytic mechanisms, achieving Shore D hardness values above 80 and glass transition temperatures ranging from 60°C to 180°C depending on molecular architecture. Their primary industrial purpose is to transform liquid thermoset precursors into dimensionally stable solids for structural bonding, protective coatings, and fiber-reinforced composites. Amine-based systems lead volume consumption across construction and marine applications due to room-temperature reactivity and established supply chains, while anhydride formulations command premium positioning in electronics assembly where low ionic content and extended pot life are mandatory. UV-cure technology represents the fastest-expanding technology segment, displacing thermal ovens in automotive electronics and reducing energy intensity for adhesive line operators.
EPA oversight under TSCA Section 5 governs new chemical introductions for U.S. curing agent manufacturers, while REACH authorization in the European Union restricts certain aromatic amines classified as Substances of Very High Concern. China's MEE enforces GB standards on volatile organic compound emissions from industrial coatings, directly constraining solvent-containing formulations and redirecting procurement toward solvent-free and waterborne epoxy systems. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments made for one geography may not transfer cleanly to another, fragmenting product development roadmaps and qualification timelines.
Market Dynamics
REACH authorization and EPA TSCA Section 5 enforcement are bifurcating supply chains, forcing formulators to maintain parallel product portfolios for European and American qualification pathways.
Growth Catalysts
- Wind blade manufacturing:Northern European offshore wind farms specify high-purity polyamide curing systems for 80-meter-plus rotor blades. MEE GB standards on VOC emissions accelerate solvent-free epoxy adoption across Chinese fabrication yards.
- REACH compliance investment:Multinational coatings houses are consolidating procurement around pre-registered amine suppliers, creating volume premiums for compliant chemistries in German and Belgian industrial clusters.
- UV-cure technology:Automotive electronics assemblers in Germany and Japan are replacing thermal oven lines with LED-curable adhesive systems, cutting energy intensity and floor space requirements.
Market Restraints
- Feedstock concentration:Cycloaliphatic amine precursors depend on captive refinery streams from Ludwigshafen and Antwerp, exposing coating formulators to naphtha-cracker maintenance cycles.
- Anhydride ionic purity limits:Electronics-grade formulations require sub-10 ppm chloride content, restricting qualified suppliers to three specialized Japanese and German producers.
- Aliphatic amine substitution pressure:Mercaptan-based systems achieve comparable cure speeds at lower viscosity, threatening room-temperature epoxy applications in marine maintenance.
Strategic Opportunities
- India infrastructure buildout:PLI scheme incentives for domestic wind turbine manufacturing create first-mover advantage for amine suppliers establishing local blending capacity.
- Waterborne epoxy convergence:MEE GB 30981-2020 VOC limits and EPA NESHAP coating rules simultaneously favor aqueous curing agent dispersions, rewarding dual-qualification investments.
- Saudi giga-project fabrication:NEOM and Red Sea tourism developments specify high-performance protective coatings for coastal infrastructure, importing Northern European formulation expertise.
Industry Challenges
- Formulation chemist scarcity:Amine-epoxy stoichiometry optimization and pot-life prediction require specialized rheology expertise concentrated in aging German and Japanese technical workforces.
- Dual-registration timeline compression:REACH SVHC screening and EPA PMN review cycles now overlap for new aromatic amine introductions, stretching R&D-to-revenue intervals to 48-60 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Curing Agents Market |
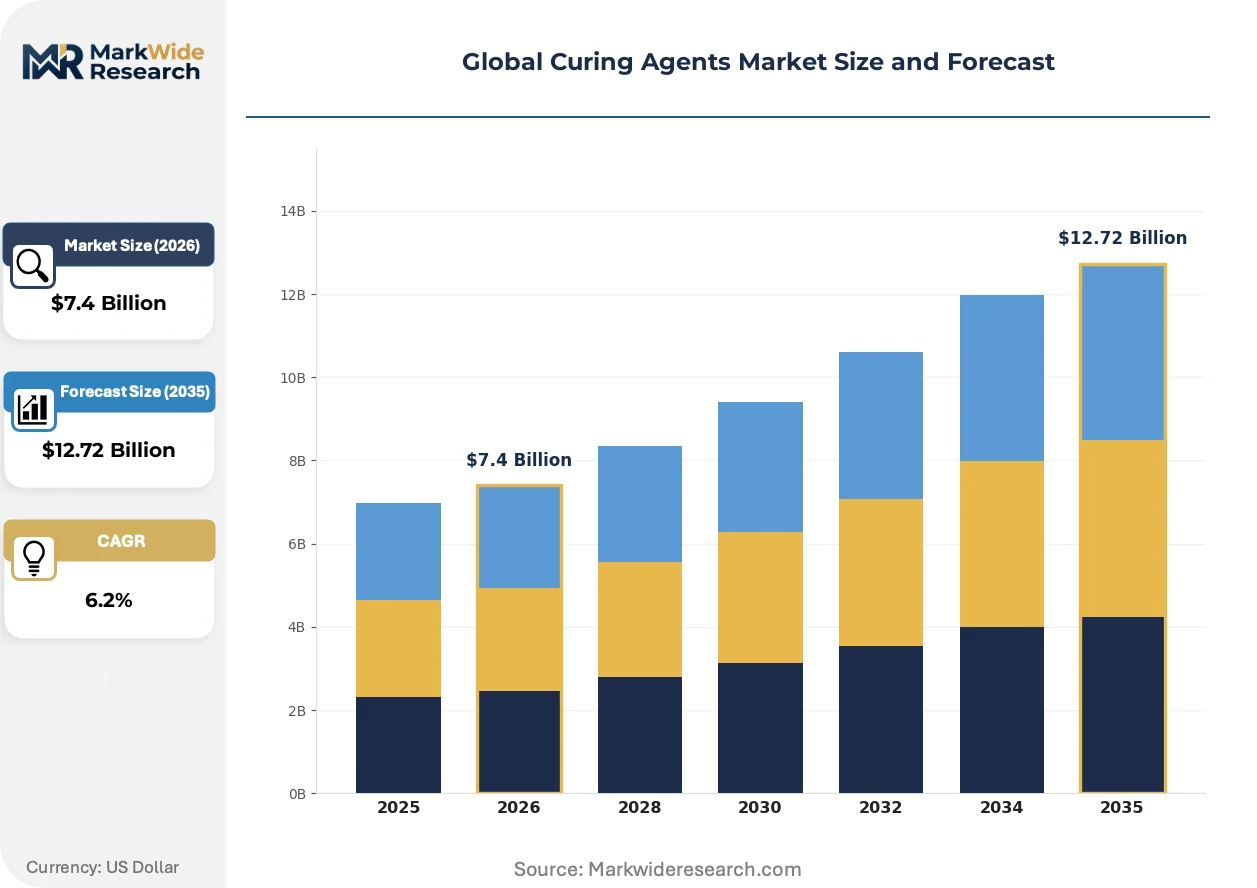
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amine, Anhydride, Phenolic, Polyamide, Polymercaptan, Others Application: Coatings, Adhesives, Composites, Sealants, Electronics, Marine Technology: Thermal, UV, Moisture Cure, Two-Component, Radiation, Solvent-Free End User Industry: Construction, Aerospace, Electronics Assembly, Marine Fabrication, Wind Energy |
| Companies Covered | Evonik Industries AG, BASF SE, Huntsman International LLC, Hexion Inc., Mitsubishi Chemical Corporation, Cardolite Corporation, Aditya Birla Chemicals, Atul Ltd, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Curing Agents Market Shifts & Advancements
Formulation chemistry is pivoting toward ambient-cure systems that eliminate thermal processing, while regulatory divergence between jurisdictions fragments product development roadmaps.
Photoinitiated cationic epoxy systems are displacing thermal anhydride curing in automotive underhood electronics, where German Tier-1 suppliers prioritize LED-curable adhesives for sensor module assembly. These systems achieve full cure in 3-5 seconds versus 30-minute oven cycles, compressing line changeover intervals and enabling cellular manufacturing layouts.
ECHA REACH authorization for cyclohexylamine derivatives is tightening impurity specifications for European coating applications, forcing reformulation of legacy construction-grade hardeners. German marine coating houses are qualifying bio-based amine alternatives from rapeseed oil derivatives to preempt authorization restrictions on fossil-derived cycloaliphatics.
Specification-driven consolidation is concentrating procurement authority among European wind OEM technical teams, who now mandate supplier audits for amine purity certificates before blade mold release. Tier-2 coating formulators in Denmark and Spain are losing direct mill relationships as Vestas and Siemens Gamesa centralize qualified supplier lists around three certified amine blenders.
Global Curing Agents Market Segmentation
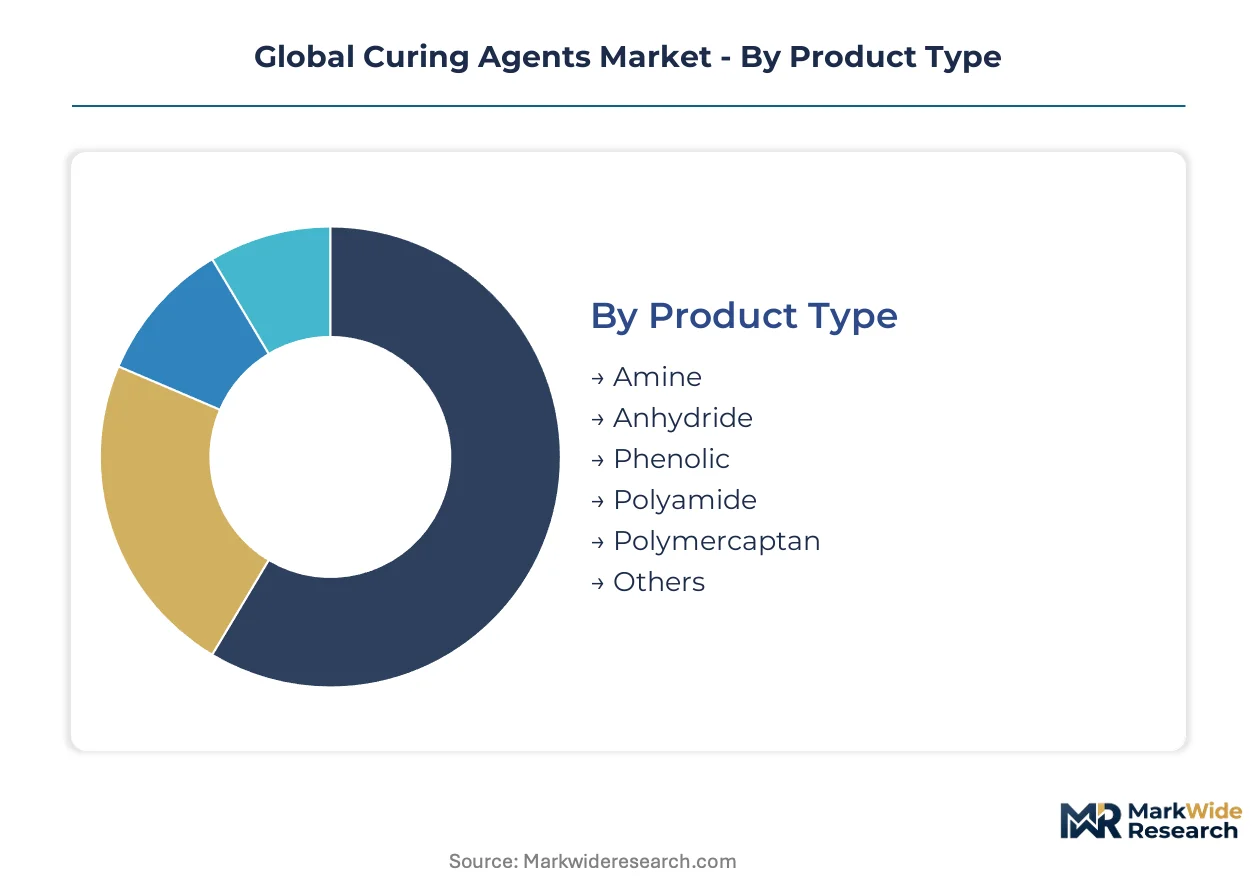
Curing agent formulations diverge sharply in margin capture based on purity thresholds and regulatory qualification burdens. Product type and end-use industry classifications reveal where value concentrates versus where volume commoditizes.
Product Type:
Margin pools sit heaviest in specialty amine derivatives where REACH pre-registration and EPA TSCA clearance create supplier scarcity.
- Amine:Aliphatic and cycloaliphatic variants dominate construction and marine maintenance due to ambient-temperature reactivity. Chinese wind blade fabricators in Jiangsu and Guangdong provinces specify high-purity grades for 80-meter rotor laminates, with MEE GB standards accelerating solvent-free formulation shifts.
- Anhydride:Electronics-grade methyltetrahydrophthalic anhydride requires sub-10 ppm chloride content for semiconductor encapsulation. German and Japanese producers in Ludwigshafen and Kashima maintain tight qualification lists for automotive sensor module suppliers.
- Phenolic:High-temperature resistance suits brake lining and friction material applications in Indian automotive clusters.
- Polyamide:Reactive dimer acid derivatives serve corrosion-resistant pipeline coatings across Saudi coastal infrastructure projects.
- Polymercaptan:Rapid cure kinetics at low temperature threaten aliphatic amine share in shipyard maintenance schedules.
- Others:Latent catalysts and imidazole accelerators fill niche aerospace pre-preg specifications.
Amine holds installed capacity. Polymercaptan is rotating up the share rankings.
Application:
Volume concentration tracks infrastructure spending cycles, with coatings commanding the largest absolute tonnage.
- Coatings:Protective and marine coatings absorb the majority of amine curing agent volume. German industrial clusters around Hamburg and Rotterdam port authorities specify high-solids epoxy systems for offshore platform maintenance, with REACH SVHC screening narrowing qualified hardener suppliers.
- Electronics: Underfill and encapsulant applications demand anhydride and cationic UV systems with ultra-low ionic content. Japanese Tier-1 automotive electronics assemblers in Nagoya and Toyota City are replacing thermal oven lines with LED-curable adhesives, compressing cure cycles from 30 minutes to under 10 seconds.
- Composites:Wind turbine blade manufacturing pulls high-purity polyamide systems into Northern European supply chains.
- Adhesives:Structural bonding in aerospace laminators favors controlled exotherm formulations.
- Sealants:Construction joint applications prioritize elongation and weathering resistance.
- Marine:Ballast tank and cargo hold coatings face IMO PSPC compliance deadlines.
Coatings maintains volume leadership. Electronics is climbing the fastest on value per kilogram.
Technology:
Energy intensity differentials separate thermal legacy systems from emerging cure mechanisms.
- Thermal:Conventional oven curing remains entrenched in heavy industrial coating lines. German automotive suppliers in Stuttgart and Wolfsburg maintain capital-intensive thermal infrastructure for high-throughput primer applications, though operating cost pressures mount.
- UV:Photoinitiated cationic systems achieve full cure in 3-5 seconds for electronics assembly. Japanese LED-curable adhesive installations in Osaka and Kyoto manufacturing parks are displacing thermal ovens, cutting floor space requirements and energy intensity.
- Moisture Cure:Alkoxy-silane terminated polymers serve construction sealant applications.
- Two-Component:Meter-mix-dispense systems dominate high-performance structural adhesives.
- Radiation:Electron beam curing penetrates thick sections for aerospace composite tooling.
- Solvent-Free:MEE GB 30981-2020 VOC limits and EPA NESHAP rules simultaneously favor 100% solids formulations.
Thermal holds installed capacity. UV is gaining share fastest on capital efficiency.
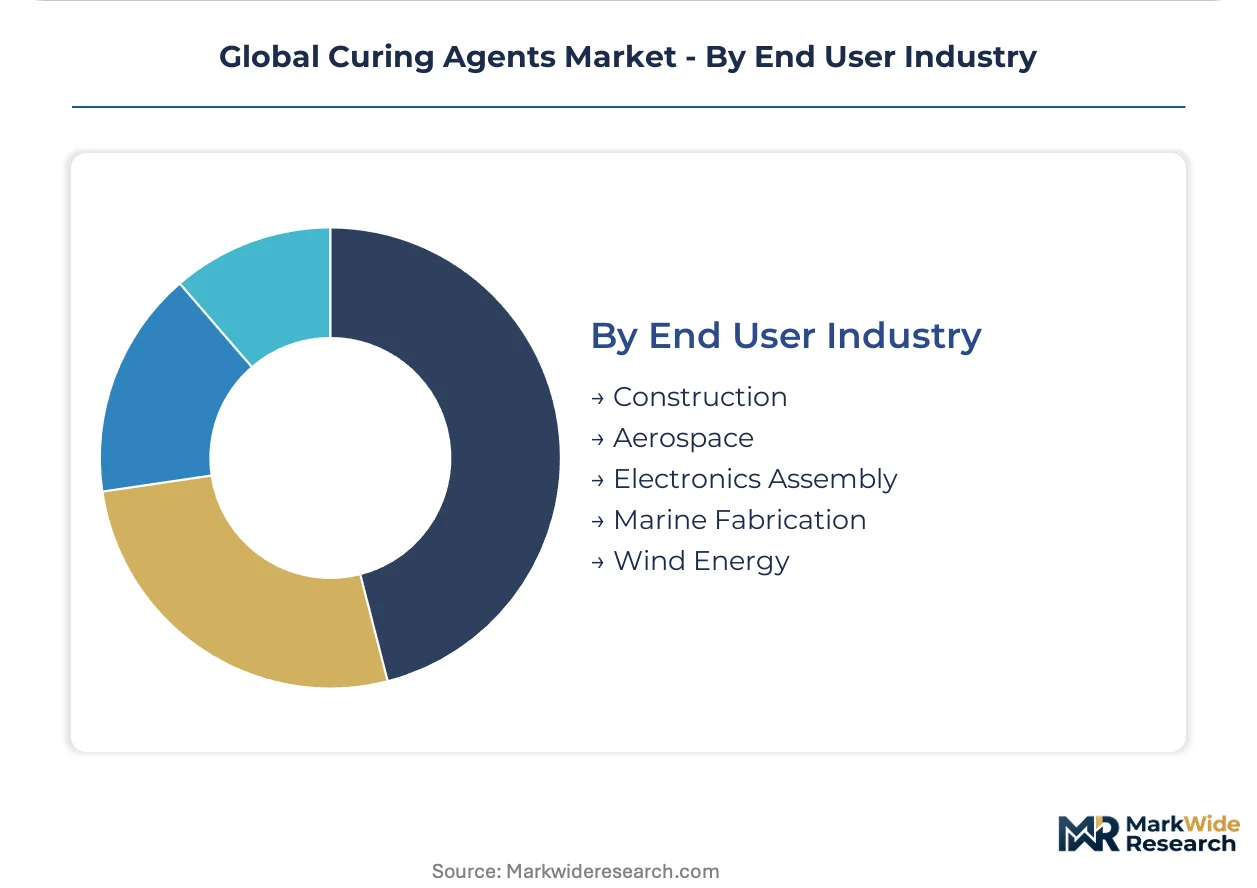
End User Industry:
Specification authority concentrates in wind OEM technical teams and aerospace prime contractors.
- Wind Energy:Offshore blade manufacturing specifications mandate amine purity certificates before mold release. Vestas and Siemens Gamesa centralize qualified supplier lists around certified blenders in Denmark and Germany, squeezing Tier-2 Spanish and Italian formulators out of direct mill relationships.
- Electronics Assembly:Semiconductor packaging and automotive sensor modules drive anhydride and UV-cure demand. Japanese and German substrate assemblers enforce sub-5 ppm sodium specifications for flip-chip underfill, restricting qualified chemistry sources to three specialized producers.
- Construction:Infrastructure resilience standards tighten in India and Saudi Arabia, pulling in Northern European formulation expertise.
- Aerospace:Primary structure pre-pregs require qualified tack and drape characteristics.
- Marine Fabrication:Newbuild and repair yards in South Korea and China face IMO environmental compliance deadlines.
Wind Energy holds installed capacity. Electronics Assembly is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed renewable energy targets and tightening VOC emission standards are redirecting procurement flows across major industrial economies. Infrastructure resilience mandates and electronics manufacturing expansion create divergent demand profiles by geography.
China
Wind turbine fabrication in Jiangsu and Guangdong provinces consumes high-purity polyamide curing systems for 80-meter-plus rotor blades. MEE GB 30981-2020 VOC limits accelerate solvent-free epoxy adoption across coastal shipyards. Qingdao and Shanghai industrial clusters now mandate supplier audits for amine purity certificates before mold release authorization.
Germany
Automotive electronics assemblers in Stuttgart and Wolfsburg prioritize LED-curable adhesive systems for sensor module production. REACH authorization for cyclohexylamine derivatives tightens impurity specifications for coating applications. Ludwigshafen and Hamburg chemical clusters sustain integrated amine production networks serving European coatings customers.
United States
Aerospace laminators in the Pacific Northwest and Texas specify specialized cycloaliphatic amine portfolios for structural composite bonding. EPA TSCA Section 5 enforcement governs new chemical introductions for domestic curing agent manufacturers. Houston and Charleston industrial corridors concentrate marine coating formulation expertise for offshore platform maintenance.
India
PLI scheme incentives for domestic wind turbine manufacturing create procurement pull for amine suppliers establishing local blending capacity. BIS certification requirements for industrial coatings constrain import-dependent formulators. Gujarat and Maharashtra industrial zones attract Northern European technical partnerships for high-performance protective coating specifications.
Japan
Semiconductor packaging and automotive sensor module producers in Nagoya and Toyota City enforce sub-5 ppm sodium specifications for flip-chip underfill applications. METI industrial standards favor UV-cure technology adoption in electronics assembly lines. Osaka and Kyoto manufacturing parks displace thermal ovens with LED-curable adhesive installations.
Global Curing Agents Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive feedstock security and specialized amine blenders serving specification-driven end users. Market structure concentrates around three to five qualified suppliers per premium application segment, with volume commoditization in construction-grade formulations. Strategic archetypes include vertically integrated petrochemical majors, purity-focused specialty chemical houses, and regional blending operations serving wind OEM technical teams. Dominant competitive moves encompass dual-qualification investments for REACH and EPA compliance, plus geographic expansion into Indian and Saudi fabrication corridors.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries AG exemplify archetypes built on captive production networks and high-purity specialization respectively. Huntsman International LLC occupies a position bridging cycloaliphatic amine technology with aerospace and electronics qualification pathways. Mitsubishi Chemical Corporation and Wacker Chemie AG represent Japanese and German specialty chemical houses with concentrated expertise in electronics-grade formulations. Cardolite Corporation and Atul Ltd sit within the regional specialist tier, serving construction and marine maintenance applications with localized formulation capabilities.
| Leading Market Players |
|---|
| Evonik Industries AG |
| BASF SE |
| Huntsman International LLC |
| Hexion Inc. |
| Mitsubishi Chemical Corporation |
| Cardolite Corporation |
| Aditya Birla Chemicals |
| Atul Ltd |
| Wacker Chemie AG |
| Others |
Supply & Pricing Matrix
Capacity utilization at Ludwigshafen and Antwerp naphtha crackers shapes both supply concentration and price floors for European amine producers, with maintenance turnarounds triggering spot premium spikes that ripple through German coatings clusters.
Pricing Analysis
Certification level (REACH-registered/EPA-cleared versus unregistered) creates the primary spread between specialty and commodity tiers. Contract-based long-term offtake dominates procurement for wind OEMs and aerospace laminators, while spot transactions persist in construction maintenance. Price differentiation stems from purity grade and dual-jurisdiction registration burden. Cost compression in electronics-grade anhydrides is intensifying because Japanese and German producers restrict qualified supplier lists. Marine coating formulators exhibit highest price sensitivity; semiconductor packaging houses prioritize ionic purity over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites feedstock security for Chinese wind blade fabricators sourcing cycloaliphatic amine precursors. Production concentrates in Germany, China, and Japan, with Ludwigshafen and Kashima maintaining tight control over high-purity grades. Raw material flows draw from refinery naphtha streams, ethylene oxide derivatives, and dimer acid feedstocks. Single-source vulnerability runs through Japanese producers of sub-10 ppm chloride anhydrides. Distribution runs through qualified supplier lists managed by Vestas and Siemens Gamesa technical teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation optimization support represent a recurring-revenue layer expanding faster than base chemical volumes, as wind OEMs outsource amine-epoxy stoichiometry expertise.
For Market Incumbents: Compound defensibility through captive backward integration into cycloaliphatic amine precursors at Ludwigshafen-scale crackers, while accelerating REACH-EPA dual-qualification timelines to outpace regionally constrained suppliers. Mercaptan substitution pressure in marine maintenance demands pot-life extension R&D investment. Certification investment serves as the priority lever against unregistered Asian imports. For New Entrants and Emerging Players: Anchor in Indian wind turbine manufacturing corridors where PLI scheme incentives outrun local blending capacity, targeting Gujarat and Maharashtra industrial zones with BIS-compliant aqueous curing agent dispersions. Technical partnerships with Northern European formulation houses provide fastest route to specification authority. White-space concentration sits with waterborne epoxy convergence serving dual MEE-EPA compliance requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty amine blenders serving qualified supplier lists for wind and electronics OEMs, where multi-year formulation contracts reduce churn. Long-term viability favors purity-focused houses with captive feedstock security over regional construction-grade commodity players. Watch REACH SVHC expansion timelines as inflection signal for consolidation pressure on legacy aromatic amine portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | Ludwigshafen-scale producers secure cycloaliphatic amine feedstock against maintenance cycle volatility. |
| Dual-Qualification Investment | Simultaneous REACH-EPA clearance opens procurement pathways for German coatings houses and US aerospace laminators. |
| Waterborne Formulation Development | Aqueous curing agent dispersions align with MEE GB 30981-2020 and EPA NESHAP rule convergence. |
| Technical Service Contract Expansion | Amine-epoxy optimization support deepens stickiness with specification-driven wind OEM technical teams. |
| Indian Blending Capacity Establishment | Local production meets PLI scheme procurement pull for domestic wind turbine manufacturing clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and Cefic industry reports, combining interviews with plant managers at European amine production facilities, procurement leads at wind OEMs and aerospace laminators, distribution channel partners in coatings clusters, and technical R&D directors at specialty chemical houses. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down capacity assessments across Ludwigshafen, Antwerp, and Kashima production hubs.
Segmentation dimensions modeled span grade tier (electronics-grade versus industrial-grade), end-use industry (wind energy, electronics assembly, marine fabrication, construction), technology type (thermal, UV, solvent-free), and regional production hub. CAGRs derive from regression analysis of historical consumption intensity against macro drivers including infrastructure investment cycles and renewable energy deployment rates across the analysis window. Industry-specific forecast inputs incorporate naphtha cracker operating rates and REACH authorization timeline assumptions.
Material uncertainties — regulatory divergence between jurisdictions, feedstock concentration at single-site crackers, and substitution pressure from mercaptan systems — sit outside the modeled envelope. Forecasts reflect assumptions about continued specification authority concentration among wind OEM technical teams and sustained LED-cure adoption in automotive electronics. Practitioners should keep alternative scenarios live as ECHA SVHC screening protocols and MEE enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Methyl Salicylate Market