
 Global Construction Adhesive Tapes Market | 2026-2036
Global Construction Adhesive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Adhesive Tapes Market Analysis
REACH compliance is shifting the cost-of-entry calculus for adhesive tape suppliers serving European construction. 3M Company leverages its materials science depth to sustain premium positioning in structural bonding applications. Tesa SE anchors its competitive stance through automotive-to-construction technology transfer, while Sika AG dominates concrete-adjacent tape systems with its construction chemicals heritage.
Construction adhesive tapes are pressure-sensitive adhesive systems laminated to flexible backings, typically 0.05 to 2.0 mm in caliper, engineered for permanent or temporary bonding of building materials under site conditions. Their primary industrial purpose is to replace mechanical fasteners in air-barrier continuity, vapor control, and structural glazing applications where thermal bridging must be eliminated. Double-sided tapes command the strongest margin pools in curtainwall and fenestration assembly, where structural silicone compatibility determines specification. Specialty tapes, including butyl and acrylic foam variants, are outpacing commodity segments in commercial retrofit work where irregular substrates demand conformability.
FDA oversight of indirect food-contact adhesives, EPA VOC regulations under Clean Air Act Title I, and EU F-Gas Regulation restrictions on blowing agents for foam tapes collectively constrain formulation choices and regional product portfolios. ECHA substance-of-very-high-concern listings for certain phthalate plasticizers are forcing PVC-backed tape producers toward bio-based or non-phthalate alternatives. Stakeholders must monitor evolving building code adoption of passive house standards, as these specifications will determine which adhesive chemistries and backing constructions achieve specification lock-in across major construction markets.
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are compressing formulation cycles for adhesive tape producers, forcing rapid chemistry pivots before 2030 compliance deadlines lock in supplier qualification lists.
Growth Catalysts
- Passive house code adoption:Germany's federal building efficiency standards now require continuous air-barrier systems, mandating structural acrylic tapes over mechanical fasteners in envelope assemblies.
- REACH SVHC restrictions:ECHA's phthalate listings are accelerating bio-based plasticizer R&D, creating first-mover advantage for suppliers with validated non-PVC constructions.
- Retrofit infrastructure stimulus:France's MaPrimeRénov program is channeling renovation subsidies toward deep energy retrofits, concentrating specification demand for conformable butyl foam tapes on irregular masonry substrates.
Market Restraints
- Petrochemical input volatility:Acrylic monomer and polypropylene backing prices fluctuate with naphtha cracking margins, compressing gross margins for non-integrated tape converters.
- Specialty adhesive supply concentration:Structural silicone-compatible pressure-sensitive adhesives rely on a narrow German and Japanese supplier base, creating qualification bottlenecks for curtainwall projects.
- Technical performance ceilings:Current acrylic foam tapes face adhesion degradation above 80°C surface temperatures, limiting application in metal roofing assemblies in southern climates.
Strategic Opportunities
- India's green building acceleration:GRIHA certification adoption in commercial real estate is opening specification pathways for low-VOC air-barrier tapes in Bangalore and Hyderabad construction corridors.
- Modular construction integration:Offsite panel manufacturers require peel-and-seal joint systems that maintain bond integrity through transport vibration and thermal cycling.
- Brazil's ANVISA medical-adjacent crossover:Cleanroom tape formulations developed for pharmaceutical manufacturing are transferring to high-performance hospital construction applications.
Industry Challenges
- Adhesion science talent scarcity:Formulation chemists with simultaneous expertise in viscoelastic modeling and construction-site durability testing command premium compensation, constraining R&D bandwidth at mid-tier suppliers.
- Multi-jurisdiction certification timelines:Achieving simultaneous ETA (European Technical Assessment) and ICC-ES (US) listings for structural glazing tapes extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Adhesive Tapes Market |
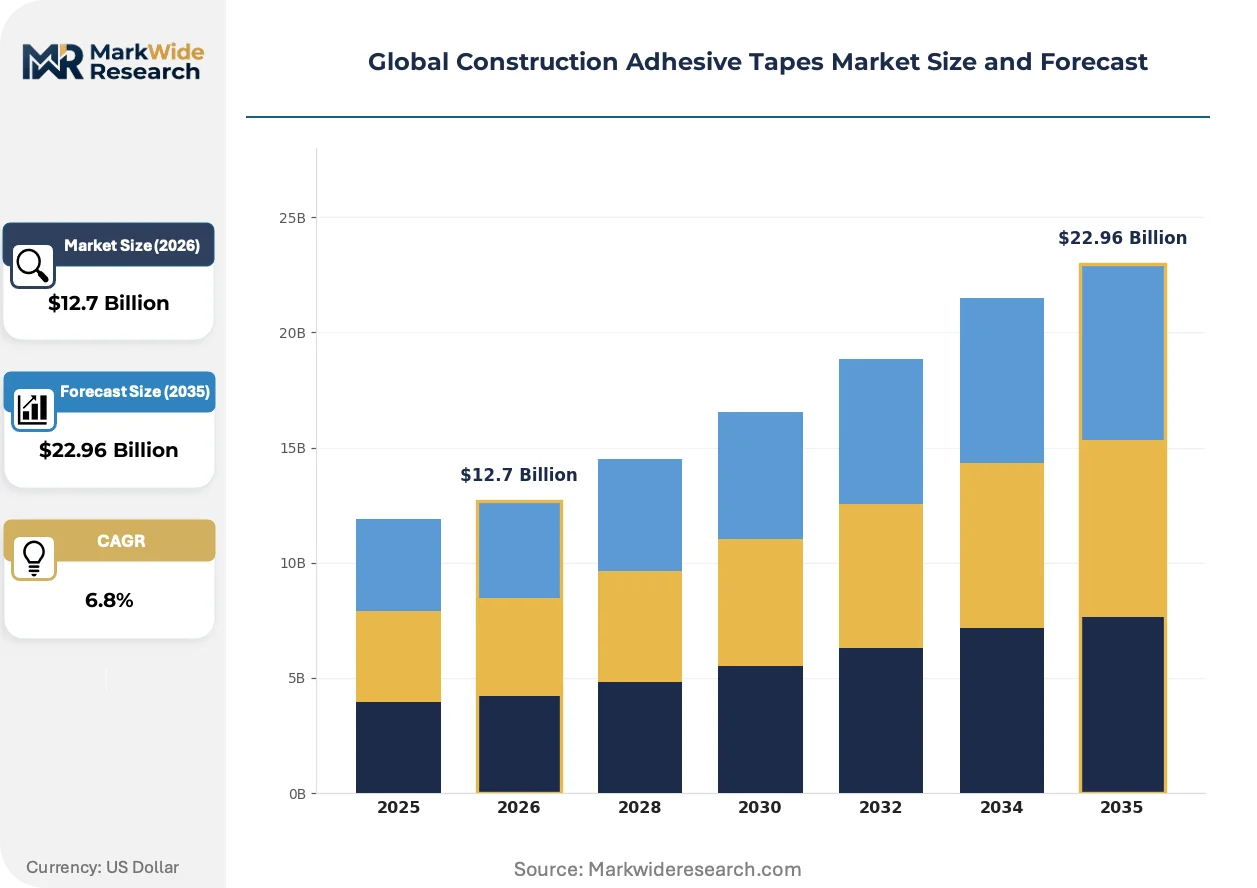
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Tapes, Double-Sided Tapes, Specialty Tapes, Waterproof Tapes Application: Building & Construction, Automotive Assembly, Electrical, Packaging Material: Polypropylene, PVC, Paper, Foam End User: Contractors, DIY Enthusiasts, Manufacturing, Retail |
| Companies Covered | 3M Company, Nitto Denko Corporation, Tesa SE, Scapa Group Ltd, Berry Global Inc., Sika AG, Intertape Polymer Group, Nichiban Co., Ltd., Lohmann GmbH & Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Adhesive Tapes Market Emerging Trajectories
Electrification of building systems and tightening thermal performance codes are reshaping material specifications across commercial construction, with adhesive technologies displacing mechanical attachment in critical load-bearing and barrier applications.
Pressure-sensitive adhesive tapes with integrated graphene thermal conductivity layers are electrifying heat-spreader applications in building-integrated photovoltaics and LED facade systems. Façade engineers in Nordic markets are specifying these constructions for junction-box thermal management. The technology is compressing traditional mechanical heat-sink attachment methods in curtainwall integration.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of release liners and low-surface-energy bonding tapes used in membrane roofing. Tape manufacturers serving the German and Benelux markets are accelerating silicone and olefinic adhesive platform development. The F-Gas Regulation's hydrofluorocarbon phase-down is simultaneously constraining blowing-agent choices for foam tape production.
Specification authority is migrating from general contractors to envelope commissioning agents who demand third-party-validated adhesion data across substrate temperature ranges. This behavioral shift is displacing traditional distributor-led product recommendation in commercial retrofit projects. The pattern is most visible in the Netherlands and Denmark where building physics consulting dominates procurement decisions.
Global Construction Adhesive Tapes Market Segmentation
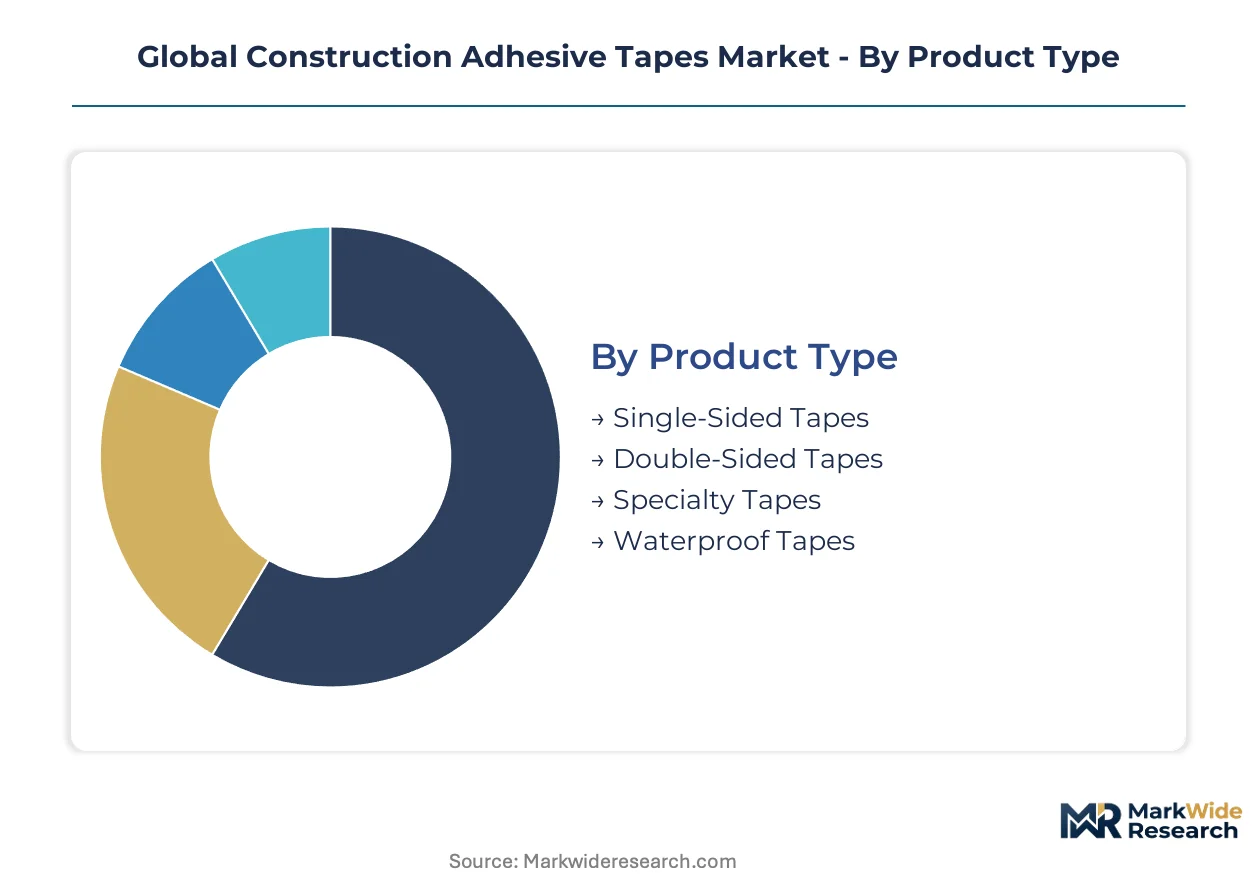
Segmentation in construction adhesive tapes reveals how specification authority migrates across buyer types and application contexts. Product chemistry, backing construction, and end-use durability requirements create distinct margin pools that suppliers must navigate strategically.
Product Type:
Buyers select tape constructions based on load-bearing requirements and substrate compatibility rather than price alone.
- Double-Sided Tapes:Pressure-sensitive adhesive systems on both faces of foam, film, or tissue carriers enable structural glazing and curtainwall panel bonding without thermal bridging. Demand concentrates in Germany's commercial retrofit corridor where passive house air-barrier continuity mandates displace mechanical fasteners.
- Specialty Tapes:Butyl and acrylic foam variants engineered for irregular masonry substrates and extreme temperature cycling command specification in deep energy renovation projects. France's MaPrimeRénov subsidies are channeling volume toward conformable high-performance constructions.
- Single-Sided Tapes:Conventional masking and surface protection applications in standard construction finishing work.
- Waterproof Tapes:EPDM and butyl rubber laminates for membrane roofing and foundation waterproofing.
Double-sided tapes lead on scale; specialty tapes lead on momentum.
Application:
Volume distribution tracks capital expenditure cycles across durable goods manufacturing and built environment investment.
- Building & Construction:Envelope sealing, structural bonding, and air-barrier systems in commercial and residential builds. Germany's federal efficiency standards and the EU Green Deal's embodied carbon rules are concentrating specification demand for low-VOC acrylic formulations in retrofit-intensive markets.
- Automotive Assembly:Trim attachment, wire harnessing, and NVH damping applications leveraging construction-grade adhesive platforms adapted from building envelope chemistry.
- Electrical:Insulation and cable management in building-integrated systems.
- Packaging:Secondary protective wrapping and temporary holding during transport.
Building and construction dominates absolute volume; automotive assembly offers technology transfer upside.
Material:
Backing selection determines thermal stability, conformability, and compliance posture under evolving chemical regulations.
- Foam:Acrylic and polyethylene foam carriers provide viscoelastic energy dissipation for structural glazing and irregular substrate bonding. ECHA phthalate SVHC listings are accelerating bio-based foam development as PVC alternatives face qualification pressure.
- Polypropylene:Lightweight, moisture-resistant film backings for general-purpose masking and temporary protection.
- PVC:Legacy backing facing substitution pressure from REACH Annex XVII restrictions and plasticizer disclosure mandates.
- Paper:Crepe and flatback constructions for paint masking and low-stress temporary bonding.
Foam backings command the steepest expansion trajectory; polypropylene retains the broadest installed base.
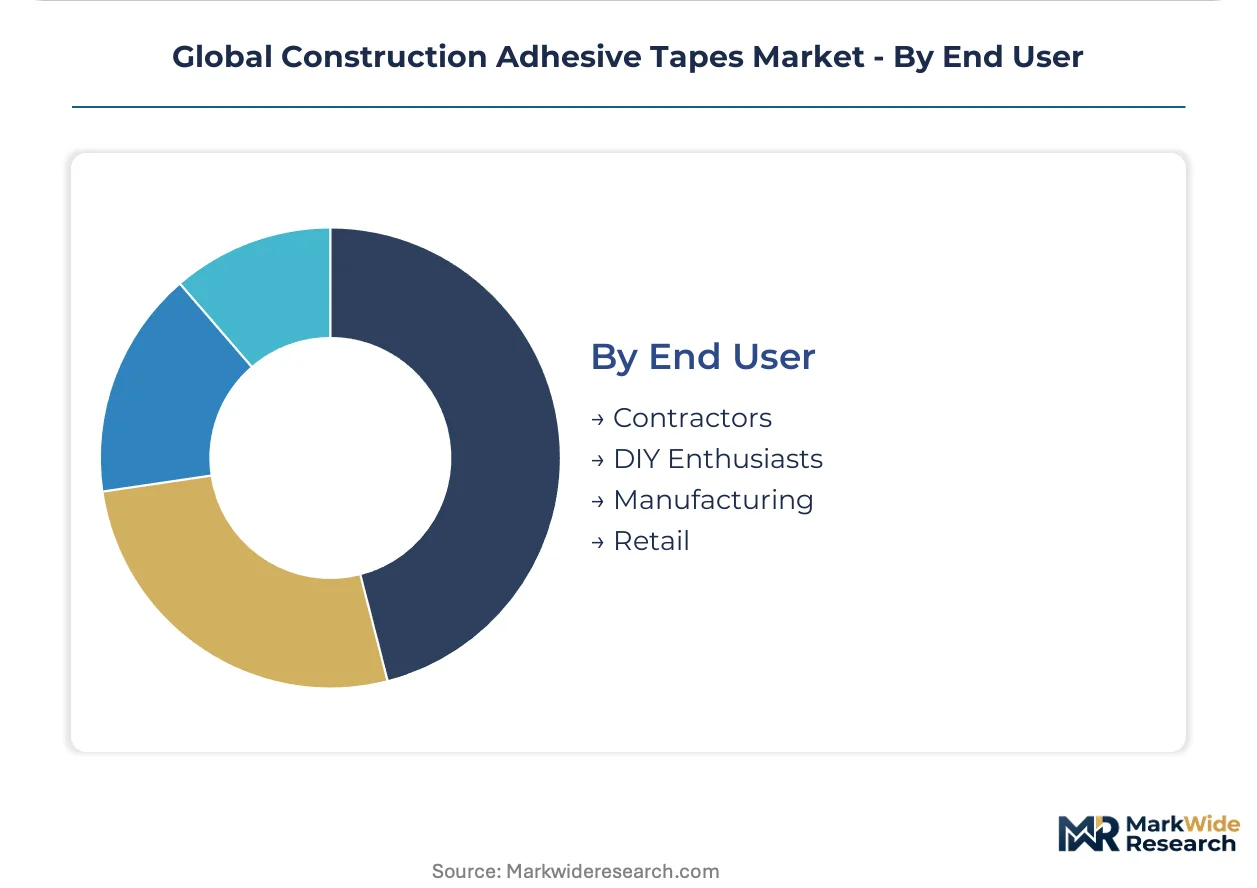
End User:
Procurement behavior diverges sharply between specification-driven commercial channels and price-sensitive consumer segments.
- Contractors:Commercial envelope specialists and general construction firms purchasing through distribution with ETA and ICC-ES certification requirements. Netherlands and Denmark building physics consultants are displacing distributor recommendations with third-party-validated adhesion data.
- Manufacturing:Offsite panel producers and modular construction integrators requiring peel-and-seal joint systems with transport-vibration durability.
- DIY Enthusiasts:Retail channel purchasers for home repair and small-scale renovation.
- Retail:Big-box and specialty hardware store distribution for consumer-grade applications.
Contractors drive specification value; manufacturing offers systems-integration partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction adhesive tape manufacturing originated in Germany's industrial belt during the post-war building boom, where chemical conglomerates first commercialized pressure-sensitive systems for structural glazing. That heritage now distributes across five concentrated national markets where regulatory stringency and retrofit intensity determine specification authority.
Germany
Deep energy renovation mandates under the federal Building Energy Act concentrate demand for passive house-certified acrylic tapes in the Rhine-Ruhr corridor. ECHA REACH SVHC restrictions on phthalate plasticizers force PVC-backed producers toward bio-based alternatives. The Stuttgart-Mannheim manufacturing cluster hosts formulation R&D for structural silicone-compatible adhesives.
United States
Commercial envelope commissioning agents in Chicago and New York displace distributor recommendations with third-party-validated adhesion data. EPA Clean Air Act Title I VOC regulations constrain formulation choices for curtainwall applications. The Pacific Northwest's mass timber construction surge drives specification for peel-and-seal joint systems in modular panel assembly.
France
MaPrimeRénov subsidies channel renovation investment toward conformable butyl foam tapes on irregular masonry substrates. EU Green Deal embodied carbon disclosure mandates compress supplier qualification timelines ahead of 2030 deadlines. The Lyon-Grenoble corridor concentrates demand for high-performance air-barrier systems in alpine climate zones.
China
GRIHA-equivalent green building certification adoption in Shanghai and Shenzhen commercial real estate opens specification pathways for low-VOC formulations. The country's national chemical regulator enforces GB standards for construction adhesive emissions. The Yangtze River Delta manufacturing base supplies acrylic monomer feedstock for regional tape converters.
India
Bangalore and Hyderabad construction corridors drive specification for air-barrier tapes as GRIHA certification penetrates commercial real estate. BIS standards for construction adhesive performance create compliance thresholds for imported formulations. The Delhi-Mumbai Industrial Corridor infrastructure stimulus concentrates modular construction demand for transport-durable bonding systems.
Global Construction Adhesive Tapes Market Vendor Landscape
The competitive structure tilts toward diversified materials science conglomerates with construction chemicals heritage. Market participation splits between integrated adhesive manufacturers and specialized tape converters, with qualification bottlenecks favoring incumbents with ETA and ICC-ES certification depth. Three archetypes dominate: construction chemicals heritage players leveraging concrete-adjacent specification authority; diversified industrial conglomerates with materials science depth; and automotive-to-construction technology transfer specialists. Competitive moves center on bio-based formulation R&D acceleration and multi-jurisdiction certification timeline compression.
Within the construction chemicals heritage tier, Sika AG anchors specification authority in concrete-adjacent tape systems. Among diversified materials science conglomerates, 3M Company occupies a position exemplifying premium-tier structural bonding applications through materials science depth. On the automotive-to-construction transfer vector, Tesa SE represents technology migration from trim attachment and NVH damping into building envelope chemistry.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| Tesa SE |
| Scapa Group Ltd |
| Berry Global Inc. |
| Sika AG |
| Intertape Polymer Group |
| Nichiban Co., Ltd. |
| Lohmann GmbH & Co |
| Others |
Supply Flow & Price Mechanics
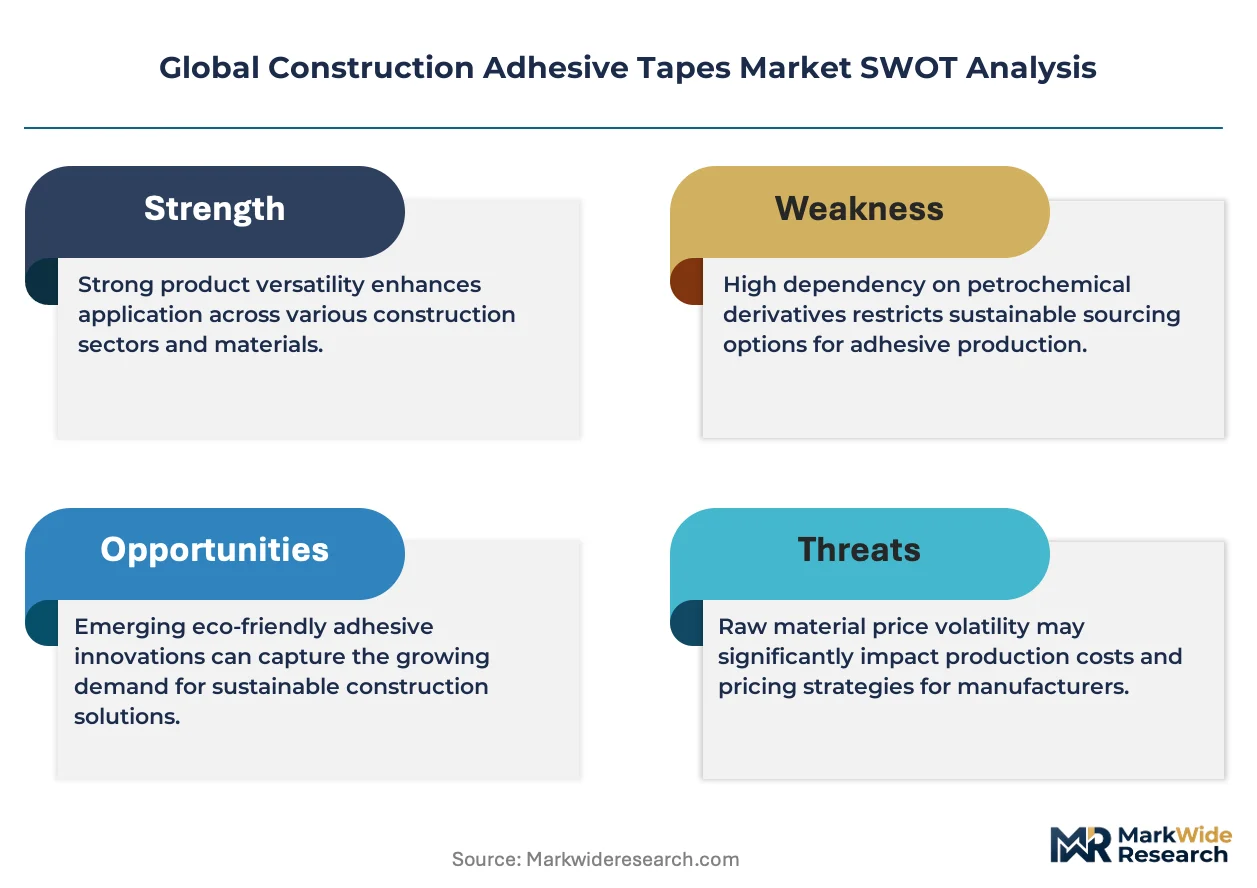
Naphtha cracking margins and acrylic monomer spot indices cascade through construction adhesive tape supply chains, compressing gross margins for non-integrated converters while concentrating pricing power among German and Japanese structural adhesive specialists with captive feedstock positions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ETA-certified structural glazing tapes from general-purpose masking grades. Price differentiation hinges on certification depth and volume scale, with passive house-qualified acrylic foam commanding substantial premiums over commodity polypropylene constructions. Cost compression in the standard tier is intensifying because petrochemical input volatility erodes converter margins. DIY retail channels exhibit the highest price sensitivity, while envelope commissioning agents in the Netherlands and Denmark prioritize validated adhesion data over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle modular construction integrator demand for transport-durable peel-and-seal systems, while distribution partnerships serve contractor procurement through building physics consultants. Supply concentrates in Germany's Stuttgart-Mannheim cluster for structural silicone-compatible adhesives, Japan for precision-coated release liners, and China's Yangtze River Delta for acrylic monomer feedstock. Raw material dependencies encompass naphtha-derived acrylic monomers, polypropylene backing films, and butyl rubber sealant feedstocks. Single-source vulnerability characterizes structural pressure-sensitive adhesive supply, with qualification bottlenecks at German and Japanese specialty chemical producers. Distribution runs through envelope specialist distributors in retrofit-intensive European markets and big-box retail for consumer-grade applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction adhesive tape markets present geographic-arbitrage opportunities where EU Green Deal compliance costs in Germany and France exceed India's GRIHA certification thresholds by substantial margins, enabling low-VOC formulation producers to capture specification premiums in emerging green building corridors.
For Market Incumbents: Cement specification lock-in through accelerated ETA and ICC-ES certification timeline compression, defending against mid-tier converters exploiting REACH SVHC transition windows. Prioritize backward integration into acrylic monomer supply to offset naphtha margin volatility. Deepen R&D bandwidth in bio-based plasticizer platforms ahead of ECHA phthalate restriction enforcement. For New Entrants and Emerging Players: EU Green Deal embodied carbon disclosure mandates in France and Germany open a window for non-PVC foam tape specialists with validated bio-based constructions. Target India's Bangalore-Hyderabad construction corridor where GRIHA certification penetration lags European passive house standards. Pursue technology licensing partnerships with automotive NVH tape producers seeking construction sector diversification. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification timelines extend product launch cycles beyond 18 months, straining mid-tier supplier R&D economics. Favor acquisition targets with dual ETA-ICC-ES qualification depth and established envelope commissioning agent relationships. Monitor adoption velocity of passive house standards in national building codes as the inflection signal for specialty tape demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive feedstock secures margin stability against naphtha cracking volatility. |
| Multi-Jurisdiction Certification Acceleration | Parallel ETA and ICC-ES pathways compress 18-24 month qualification timelines. |
| Bio-Based Plasticizer Platform Development | ECHA SVHC restrictions on phthalates create first-mover specification advantage. |
| Envelope Commissioning Agent Partnership | Netherlands and Denmark procurement shifts favor third-party-validated adhesion data. |
| Modular Construction Systems Integration | Offsite panel manufacturers require transport-vibration durable peel-and-seal joint systems. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with envelope commissioning agents, construction chemical R&D directors, modular construction procurement leads, and building physics consultants with secondary validation from ECHA REACH substance listings, EU Green Deal policy documents, national building code adoption records, and customs trade data for acrylic monomer and tape backing materials. Bottom-up segment sizing and top-down macro constraint checks ensured triangulation integrity.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling spanning product chemistry, backing construction, application durability requirements, and regional regulatory stringency clusters. CAGRs derived from elasticity-adjusted demand curves incorporating retrofit stimulus intensity, passive house code adoption velocity, and petrochemical input cost trajectories. Industry-specific forecast inputs encompassed ECHA SVHC listing timelines and national green building certification penetration rates.
Revisions become necessary when REACH Annex XVII restrictions expand beyond PFAS and phthalates, embodied carbon disclosure mandates accelerate ahead of 2030 deadlines, or structural silicone-compatible adhesive supply concentrates further. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and retrofit subsidy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
Butyl Adhesive Market