
 Industrial Adhesives Market | 2026-2036
Industrial Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Adhesives Market Intelligence
Automotive OEMs is unwinding legacy mechanical fastening commitments across vehicle platforms. Henkel AG & Co. KGaA leverages its polyurethane portfolio to anchor European electric-vehicle assembly lines. H.B. Fuller competes through hot-melt specialization in North American packaging conversion. Sika AG dominates construction-grade reactive systems in Swiss infrastructure and adjacent markets.
Industrial adhesives are non-metallic substances formulated from synthetic polymers, tackifying resins, and curing agents that develop structural or semi-structural bonds through chemical crosslinking, thermal activation, or moisture exposure, typically achieving shear strengths from 1 MPa to over 30 MPa depending on chemistry and substrate preparation. Their primary purpose is to replace or supplement mechanical fasteners in load-bearing assemblies, sealing joints, and enabling dissimilar-material joining across temperature and chemical exposure ranges. Epoxy formulations lead in aerospace and electronics applications where thermal stability and dielectric performance command premium positioning, while water-based acrylics capture share in packaging as converters face solvent-emission scrutiny. Reactive polyurethane systems represent the fastest-growing technology category as manufacturers pursue cure-on-demand flexibility for mixed-material automotive bodies.
EPA regulates volatile organic compound emissions from adhesive manufacturing and application under Clean Air Act Title V permitting, while REACH restricts hazardous substance content in formulations sold across Europe. OSHA mandates hazard communication and exposure limits for isocyanate-containing polyurethane systems in US fabrication facilities. The EU Green Deal and associated F-Gas Regulation are accelerating solvent-phase displacement. Stakeholders must decide whether to prioritize bio-based feedstock development or advanced reactive curing equipment as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
Automotive OEMs are dismantling mechanical fastening hierarchies as mixed-material chassis architectures demand bonding solutions that tolerate coefficient-of-thermal-expansion mismatches between aluminum, carbon fiber, and high-strength steel.
Growth Catalysts
- EU Green Deal solvent-phase displacement:REACH volatile organic compound thresholds are compelling formulators to accelerate water-based and hot-melt platform development for European packaging converters.
- Electric-vehicle battery pack assembly:Thermal interface materials and structural adhesives for cell-to-pack architectures are pulling demand from cylindrical and prismatic cell manufacturers in China and Germany.
- China domestic manufacturing scale:Advanced bonding applications in electronics assembly and renewable energy infrastructure are concentrating procurement volumes with local specialty chemical producers.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate precursor costs fluctuate with propylene and benzene derivative markets, compressing formulation margin stability.
- Specialty curing agent supply concentration:Aliphatic amine and anhydride hardener production clusters in the US Gulf Coast and Rotterdam-Antwerp corridor create geographic vulnerability.
- Mechanical fastening residual preference:Aerospace primary structures and heavy-equipment weldments retain specification inertia where bonded joints lack decades of field failure data.
Strategic Opportunities
- India electronics manufacturing expansion:PLI scheme incentives for semiconductor and mobile device assembly are creating first-mover positioning for conformal coating and die-attach adhesive suppliers.
- UV-LED curing convergence:Instant-on solid-state polymerization is enabling just-in-time bonding stations that eliminate solvent storage and thermal oven footprints.
- Swiss infrastructure refurbishment cycle:Sika AG's domestic dominance in construction-grade reactive systems provides template for specification capture in tunnel lining and bridge deck rehabilitation.
Industry Challenges
- Formulation chemist talent scarcity:Polymer synthesis and rheology expertise pools concentrate at legacy German and Japanese chemical conglomerates, constraining mid-tier competitor R&D velocity.
- Multi-jurisdiction certification timelines:EPA Clean Air Act Title V permitting, OSHA isocyanate exposure compliance, and REACH SVHC notification create 18-36 month product launch cycles.
- Legacy dispensing equipment incompatibility:Hot-melt and reactive polyurethane systems demand precision metering and temperature control that obsolete pneumatic extrusion infrastructure at tier-two fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Adhesives Market |
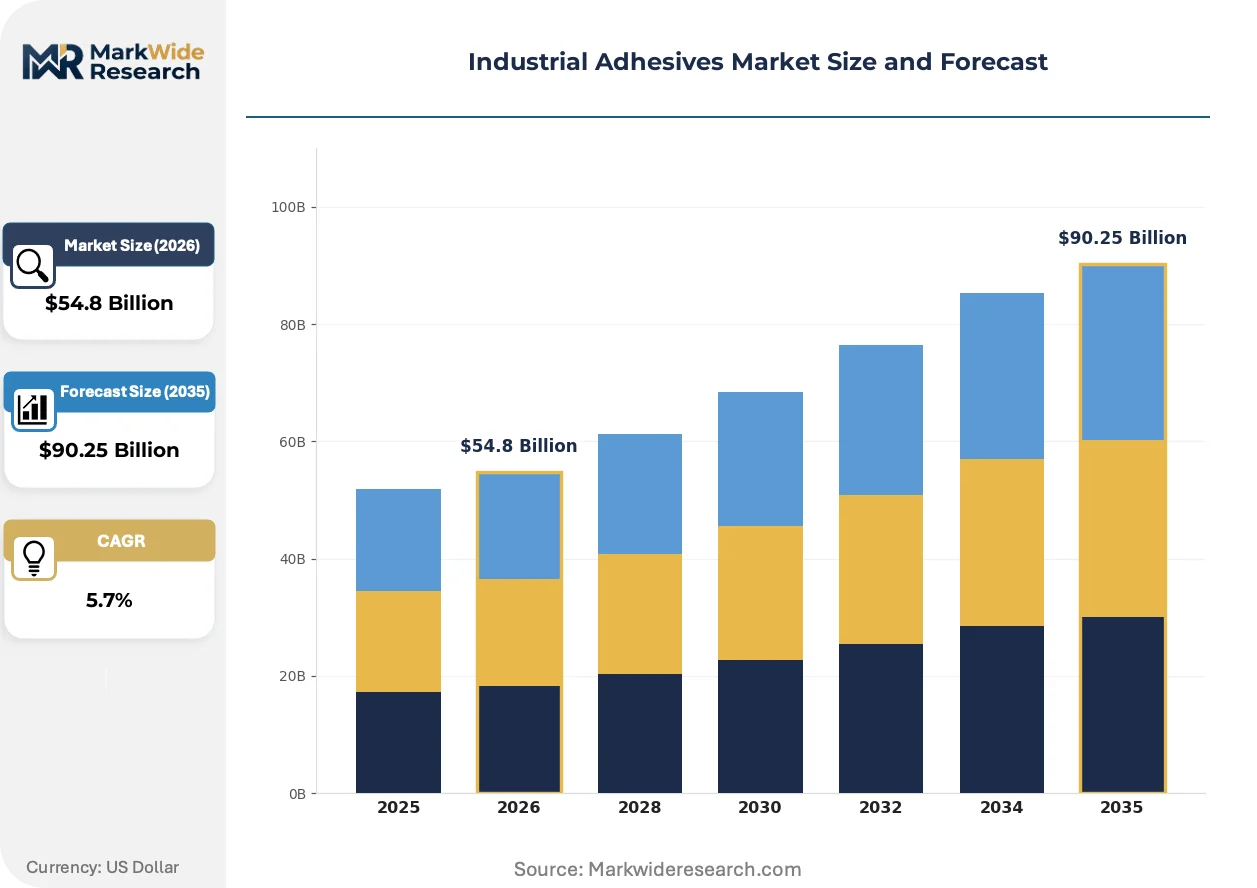
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $90.25 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone Application: Automotive, Construction, Electronics, Packaging End User: Manufacturing, Automotive OEMs, Food & Beverage, Aerospace Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller, BASF SE, Dow, Huntsman Corporation, Sika AG, 3M, Arkema S.A., Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Adhesives Market Strategic Shifts & Innovations
Bio-based feedstock substitution and on-demand curing architectures are rewriting formulation priorities, while regulatory thresholds harden faster than equipment replacement cycles can accommodate.
Reactive polyurethane systems are fragmenting the automotive body-in-white adhesive landscape by enabling cure-on-demand flexibility that accommodates mixed-material joining cycles. BMW and Mercedes-Benz assembly plants in Germany and Alabama are specifying two-component PUR for aluminum-to-composite bonding. The technology is fragmenting incumbent epoxy and acrylic market positions by eliminating thermal oven requirements and reducing work-in-process inventory.
REACH authorization and restriction procedures are tightening hazardous substance content limits for formulations sold across Europe. ECHA SVHC candidate list expansion is forcing reformulation of legacy polychloroprene and solvent-based neoprene contact cements. Packaging converters in Italy and Poland are responding by migrating water-based acrylic platforms despite 15-20% bond strength trade-offs on high-recycled-content substrates.
Buyer consolidation among tier-one automotive suppliers is compressing adhesive vendor qualification timelines and unbundling technical service from material pricing. Magna, Continental, and Bosch procurement organizations are implementing direct material cost-plus pricing models that strip historical formulation support margins. This pattern is most visible in German and Mexican supplier parks where OEM platform commonality concentrates purchasing leverage.
Industrial Adhesives Market Segmentation
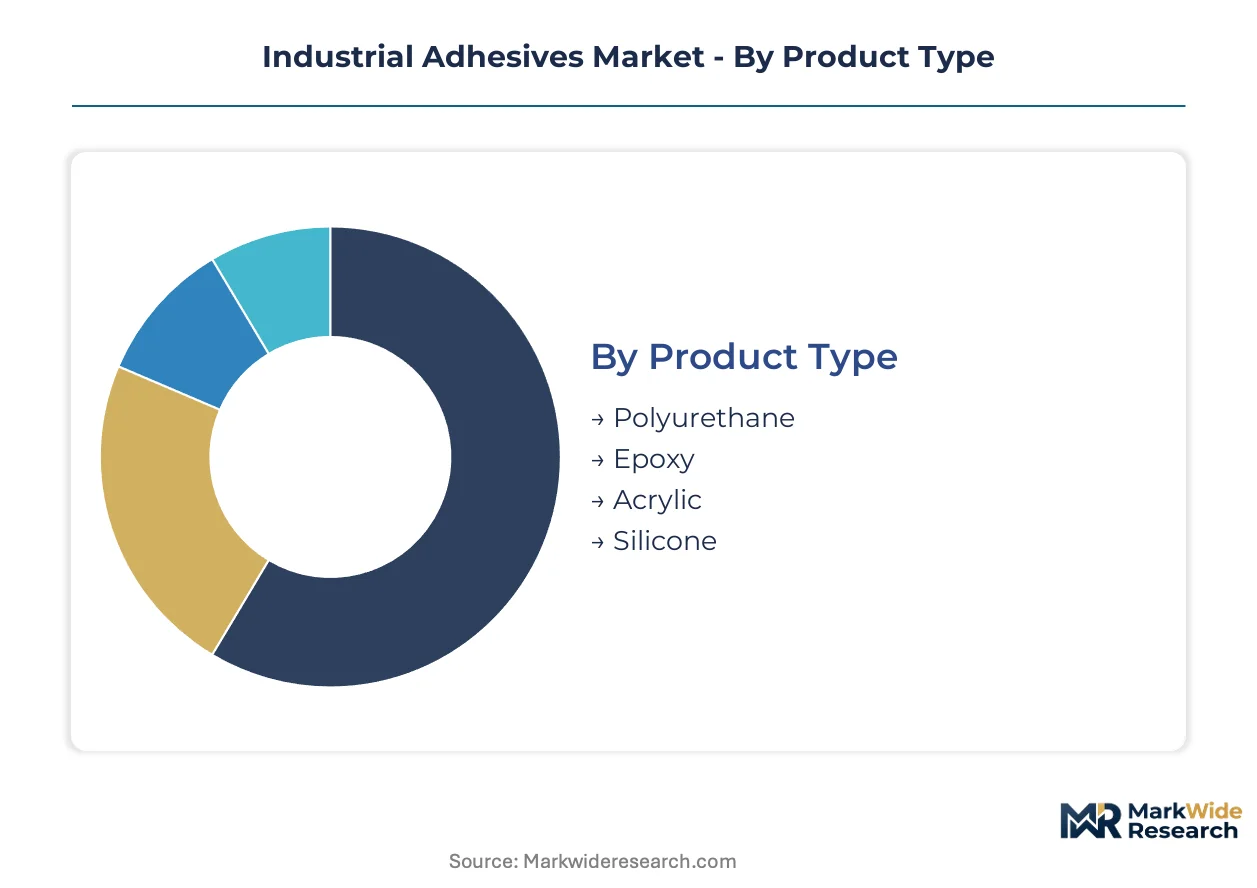
Adhesive selection criteria vary sharply across end-use environments, with thermal cycling demands, regulatory exposure, and substrate compatibility driving portfolio diversification. Formulators must balance cure speed, bond strength, and compliance costs when positioning products across these four segmentation dimensions.
Product Type:
Polyurethane and epoxy formulations face the most intense substitution pressure as reactive acrylics and modified silicones encroach on traditional structural applications.
- Polyurethane:Two-component systems cure through isocyanate-hydroxyl reactions, achieving 15-25 MPa shear strength with flexibility down to -40°C. Automotive OEMs in Germany and Alabama specify PUR for aluminum-to-composite bonding in electric-vehicle platforms, displacing thermal-cure epoxies.
- Epoxy:Amine-cured bisphenol-A and bisphenol-F resins deliver 30+ MPa tensile strength and 180°C service temperature. Aerospace electronics and wind turbine blade manufacturers in China concentrate procurement for dielectric and fatigue-resistant applications.
- Acrylic:Cyanoacrylate and anaerobic formulations dominate threadlocking and medical device assembly with rapid fixture times.
- Silicone:RTV and heat-cure systems seal photovoltaic modules and automotive lighting with UV stability and 200°C continuous exposure tolerance.
Epoxy anchors the volume base in structural applications while polyurethane gains share at the steepest rate through automotive lightweighting adoption.
Application:
Cost tier differentiation separates specification-grade automotive and aerospace bonding from commodity packaging and construction applications.
- Automotive:Body-in-white structural adhesives must accommodate coefficient-of-thermal-expansion mismatches between aluminum, carbon fiber, and high-strength steel. BMW and Mercedes-Benz assembly plants specify reactive systems for mixed-material chassis.
- Construction:Reactive polyurethane and epoxy systems bond concrete, masonry, and engineered wood in Swiss tunnel lining and bridge deck rehabilitation where Sika AG dominates specification capture.
- Electronics:Conformal coatings and die-attach materials protect semiconductor packages from moisture and thermal shock.
- Packaging:Water-based acrylics and hot-melt EVA capture corrugated and flexible film conversion as Italian and Polish converters face REACH solvent-emission thresholds.
Construction commands the highest per-kilogram pricing while electronics expands most quickly through semiconductor packaging densification.
End User:
Customer type concentration creates divergent service models, with automotive OEMs demanding technical integration support and manufacturing sectors prioritizing unit cost.
- Manufacturing:General industrial fabricators apply hot-melt and water-based systems in furniture, appliance, and textile assembly where pneumatic dispensing equipment remains prevalent.
- Automotive OEMs:Tier-one suppliers at Magna, Continental, and Bosch procurement organizations negotiate direct material cost-plus pricing that strips historical formulation support margins.
- Food & Beverage:FDA-compliant adhesives seal carton and label applications with migration limits on aromatic amine content.
- Aerospace:Primary structures retain mechanical fastening preference where bonded joints lack decades of field failure data, limiting adhesive penetration to interiors and secondary assemblies.
Automotive OEMs drive the steepest technology migration while manufacturing provides the broadest volume foundation across regional markets.
Technology:
Supply concentration in curing agent production clusters shapes geographic availability and lead time reliability for reactive and solvent-based platforms.
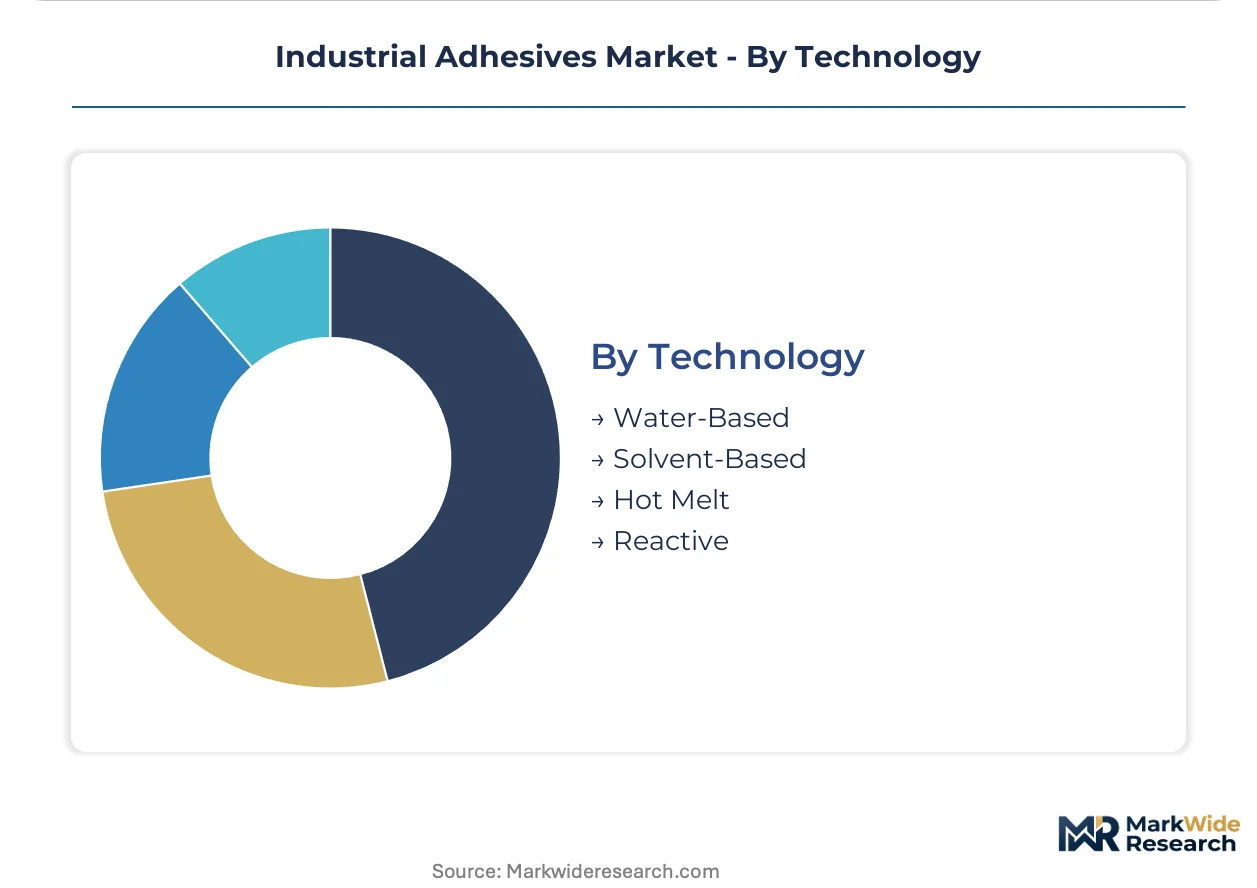
- Water-Based:Acrylic and polyurethane dispersions eliminate solvent storage and VOC permitting burdens. Packaging converters in Italy and Poland accept 15-20% bond strength trade-offs on high-recycled-content substrates to meet EU Green Deal thresholds.
- Solvent-Based:Neoprene and polychloroprene contact cements face ECHA SVHC candidate list pressure, forcing reformulation of legacy footwear and furniture assembly products.
- Hot Melt:EVA and metallocene polyolefin systems dominate North American packaging conversion through H.B. Fuller's specialization in automated dispensing integration.
- Reactive:Two-component polyurethane and epoxy systems enable cure-on-demand flexibility that eliminates thermal oven requirements and reduces work-in-process inventory at mixed-material automotive facilities.
Hot melt and water-based platforms anchor existing installed base volumes while reactive systems climb the fastest through automotive and electronics precision bonding requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical production for adhesive curing agents clusters in the US Gulf Coast and Rotterdam-Antwerp corridor, creating geographic vulnerability that shapes regional procurement strategies. Formulators must navigate diverging regulatory timelines across jurisdictions while serving automotive OEMs expanding mixed-material assembly.
United States
Automotive OEMs in Alabama and Michigan specify reactive polyurethane systems for electric-vehicle platforms, displacing thermal-cure alternatives. EPA Clean Air Act Title V permitting governs VOC emissions from adhesive manufacturing facilities. The US Gulf Coast concentration of aliphatic amine hardener production exposes supply chains to hurricane-season disruption.
Germany
BMW and Mercedes-Benz assembly plants drive specification of two-component PUR for aluminum-to-composite bonding in body-in-white applications. REACH authorization procedures tighten hazardous substance content limits for formulations sold across Europe. The Stuttgart-Munich corridor anchors automotive adhesive qualification and technical service operations.
China
Domestic manufacturing scales advanced bonding applications in electronics assembly and renewable energy infrastructure, concentrating procurement with local specialty chemical producers. MEE enforcement of dual carbon goals accelerates solvent-phase displacement in packaging conversion. The Yangtze River Delta hosts expanding capacity for conformal coatings and die-attach materials serving semiconductor packaging.
Switzerland
Sika AG dominates construction-grade reactive systems in domestic tunnel lining and bridge deck rehabilitation, providing template for specification capture. Swissmedic maintains alignment with EU REACH SVHC notification requirements despite non-membership. The Swiss infrastructure refurbishment cycle sustains premium pricing for epoxy and polyurethane structural bonding systems.
India
PLI scheme incentives for semiconductor and mobile device assembly create first-mover positioning for conformal coating and die-attach adhesive suppliers. BIS certification requirements extend product launch timelines for imported formulations. Maharashtra and Karnataka electronics manufacturing clusters drive procurement concentration for UV-curable and thermally conductive platforms.
Industrial Adhesives Market Key Industry Players
Concentration sits with diversified chemical conglomerates commanding integrated resin and curing agent production. The vendor base spans three tiers: global formulators with captive feedstock access, regional specialists in application-specific technologies, and private-label converters serving commodity packaging segments. M&A activity targets UV-curable technology assets and bio-based feedstock platforms, while capacity expansion concentrates in China and India to serve localized automotive and electronics demand.
Among German chemical conglomerates, Henkel AG & Co. KGaA and BASF SE exemplify the integrated-formulator archetype with captive supply chains spanning polyurethane and epoxy chemistries. Sika AG represents the construction-specialist position, anchoring specification capture in European infrastructure refurbishment. These three entities occupy positions that illustrate how geographic proximity to automotive OEM technical centers and regulatory expertise create defensive moats against mid-tier competitors lacking comparable formulation breadth.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller |
| BASF SE |
| Dow |
| Huntsman Corporation |
| Sika AG |
| 3M |
| Arkema S.A. |
| Avery Dennison Corporation |
| Others |
Cost & Logistics Intelligence
Capacity utilization at aliphatic amine and anhydride hardener facilities in the US Gulf Coast and Rotterdam-Antwerp corridor shapes both supply concentration and price floors for reactive adhesive systems. Automotive OEM procurement consolidation and REACH compliance costs feed back into supplier margin structures, compressing mid-tier formulators while rewarding integrated producers with captive feedstock access.
Pricing Analysis
Volume-discount tiering structures separate automotive OEM direct contracts from tier-two fabricator spot purchases. Three-tier pricing stratification across specification-grade, commercial-grade, and commodity-grade formulations reflects certification burden and technical service bundling. Pricing pressure intensifies as Magna, Continental, and Bosch procurement organizations implement cost-plus models that strip historical formulation support margins. Manufacturing sectors exhibit highest price sensitivity due to pneumatic dispensing equipment legacy and pneumatic extrusion infrastructure obsolescence, while aerospace and electric-vehicle battery pack assemblers tolerate premium positioning for thermal stability and dielectric performance.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive body-in-white assembly where cure-on-demand polyurethane systems eliminate thermal oven work-in-process, while strategic stockpiling persists among packaging converters hedging water-based acrylic supply against REACH-driven solvent-phase displacement timelines. Feedstock concentration in China, Germany, and the US Gulf Coast creates geographic vulnerability for isocyanate precursors and epoxy resins. Raw material dependencies on propylene derivatives, benzene streams, and bio-based polyols expose formulators to petrochemical volatility. Single-source vulnerability concentrates in specialty curing agent production clusters. Distribution runs through integrated chemical conglomerates with captive resin production and regional specialists serving application-specific niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers. REACH authorization timelines and multi-jurisdiction certification requirements embed switching costs that protect qualified suppliers from rapid displacement.
For Market Incumbents: Compound specification capture in electric-vehicle battery pack assembly and Swiss infrastructure refurbishment by deepening captive supply of aliphatic amine hardeners. Threats from emerging bio-based feedstock platforms and UV-LED curing equipment specialists demand accelerated R&D in on-demand curing architectures. Capacity addition in the Yangtze River Delta and Maharashtra electronics clusters anchors regional procurement relationships against local specialty chemical producers. For New Entrants and Emerging Players: Anchor in India PLI scheme electronics manufacturing incentives where BIS certification gaps create first-mover windows for conformal coating and die-attach adhesive suppliers. White-space targets include UV-curable platforms for just-in-time bonding stations and thermally conductive materials for semiconductor packaging densification. The most penetrable segment is tier-two automotive fabricators with obsolete pneumatic extrusion infrastructure requiring precision metering upgrades. Go-to-market angle should emphasize equipment-integrated dispensing solutions that reduce solvent storage footprints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with backward integration into curing agent production and established REACH regulatory expertise. Long-term viability rests on bio-based feedstock substitution capabilities and UV-LED curing convergence assets. Acquisition target archetype includes regional specialists in reactive polyurethane systems with automotive OEM qualification relationships. Signal to watch is MEE enforcement acceleration of dual carbon goals in China packaging conversion, which would intensify solvent-phase displacement timelines and reward water-based platform investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curing Agent Production | Captive supply of aliphatic amines insulates margin stability against US Gulf Coast hurricane disruption. |
| UV-LED Curing Equipment Convergence | Instant-on solid-state polymerization eliminates thermal oven footprints at BMW and Mercedes-Benz assembly plants. |
| Long-term Supply Agreement with Tier-One Automotive | Direct material cost-plus contracts with Magna and Continental procurement secure volume commitment. |
| Green Manufacturing Transition to Bio-Based Feedstocks | EU Green Deal thresholds accelerate solvent-phase displacement in Italian and Polish packaging conversion. |
| Joint Venture in Yangtze River Delta Capacity | Localized production of conformal coatings serves China semiconductor packaging densification demand. |
Research Approach
Cross-validation between primary interviews with adhesive formulators, automotive OEM procurement leads, and plant engineers anchors the qualitative findings against secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up and top-down triangulation reconciles facility-level capacity assessments with macroeconomic demand modeling across automotive, construction, electronics, and packaging end-use segments.
Sensitivity analysis frameworks test forecast robustness across petrochemical feedstock volatility scenarios and regulatory timeline acceleration assumptions. Segmentation dimensions modeled include product chemistry tier, application environment, end-user procurement sophistication, and curing technology architecture. CAGRs derive from historical trajectory analysis adjusted for technology substitution rates and OEM platform commonality effects. Industry-specific forecast inputs incorporate electric-vehicle production ramp schedules and semiconductor packaging density trends.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH enforcement and automotive lightweighting adoption; material deviation would warrant model refresh. Forecasts reflect documented assumptions regarding curing agent supply concentration and buyer consolidation trajectories. Specific risk factors that could revise projections include aliphatic amine production cluster disruption, MEE dual carbon goal acceleration, and aerospace primary structure bonding specification inertia erosion. Revision becomes warranted when UV-LED curing equipment penetration crosses threshold adoption rates among tier-two fabricators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Malaysia Adhesives Market