
 North America Bone Glue Market | 2026-2036
North America Bone Glue Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bone Glue Market Analytics
Natural collagen formulations are realigning cost structures as surgeons shift away from conventional mechanical fixation in outpatient settings. Stryker leverages its integrated trauma portfolio to bundle bone adhesive systems with implant hardware. Zimmer Biomet anchors its position through R&D intensity focused on next-generation crosslinking chemistries. DePuy Synthes competes by controlling distribution channels across major integrated delivery networks.
North America bone glue encompasses biocompatible adhesive systems formulated from collagen matrices, synthetic cyanoacrylates, or fibrinogen-thrombin combinations, designed to achieve mechanical fixation between bone segments or between bone and prosthetic surfaces without traditional screws or plates. These materials typically set within 30 to 120 seconds under physiological conditions and must demonstrate shear strengths exceeding 1 MPa for load-bearing orthopedic applications. Synthetic polymers currently occupy the largest revenue pool due to reproducible manufacturing and extended shelf stability, while biochemical crosslinking technology represents the fastest-expanding segment as manufacturers pursue tunable curing kinetics. Fibrin adhesives sustain premium positioning in cartilage reconstruction applications where bioresorbability within 14 days matches healing timelines.
FDA 510(k) clearance pathways and ISO 10993 biocompatibility standards govern product entry, with the former dictating clinical evidence requirements and the latter defining cytotoxicity and sensitization testing matrices for implantable adhesives. Health Canada's Medical Devices Directorate maintains parallel but distinct classification rules that create incremental compliance burdens for cross-border suppliers. The US IRA's hospital reimbursement adjustments indirectly shape demand by altering site-of-service economics for outpatient bone procedures. Stakeholders must monitor pending FDA guidance on degradable synthetic polymer characterization, as this will determine which formulation platforms secure accelerated review status.
Market Dynamics
FDA's tightening biocompatibility protocols for synthetic polymer formulations are forcing manufacturers to revalidate entire product lines, compressing margins while accelerating R&D spend on next-generation crosslinking platforms.
Growth Catalysts
- Outpatient surgical migration:Ambulatory surgery centers across the United States are expanding arthroscopic procedures, creating pull-through demand for rapid-setting fibrin adhesives that eliminate hardware removal surgeries.
- ISO 10993-5 cytotoxicity testing harmonization:Streamlined biocompatibility matrices reduce regulatory friction for collagen-based platforms entering the Canadian market through Health Canada's Medical Devices Directorate.
- Crosslinking chemistry advances:Tunable curing kinetics in biochemical platforms enable surgeons to match adhesive set times to specific bone density variations encountered in spinal fusion applications.
Market Restraints
- Bovine-derived collagen supply concentration:Overreliance on North American abattoir sourcing creates vulnerability to herd health cycles and export restriction volatility from primary processing states.
- Synthetic monomer cost exposure:Cyanoacrylate formulations face input pressure from specialty chemical supply chains concentrated in Gulf Coast petrochemical corridors.
- Mechanical fixation substitution resilience:Titanium screw-and-plate systems retain preference in load-bearing trauma cases where shear strength requirements exceed 2 MPa thresholds.
Strategic Opportunities
- Pediatric orthopedic white space:Resorbable adhesive platforms tailored to growth-plate-sparing procedures remain underdeveloped across United States children's hospitals.
- Veterans Health Administration procurement reform:Centralized purchasing mandates for trauma systems create channel consolidation opportunities for integrated adhesive-implant bundles.
- Cartilage reconstruction bioresorbability matching:14-day degradation profiles align with chondrocyte migration timelines, opening sports medicine applications in Midwest collegiate athletic programs.
Industry Challenges
- Polymer characterization expertise scarcity:Degradable synthetic formulation development requires specialized rheology and degradation kinetics talent concentrated in limited academic medical centers.
- 510(k) predicate device pathway erosion:FDA's narrowing acceptance of historical mechanical fixation comparisons extends clinical evidence timelines for novel adhesive platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bone Glue Market |
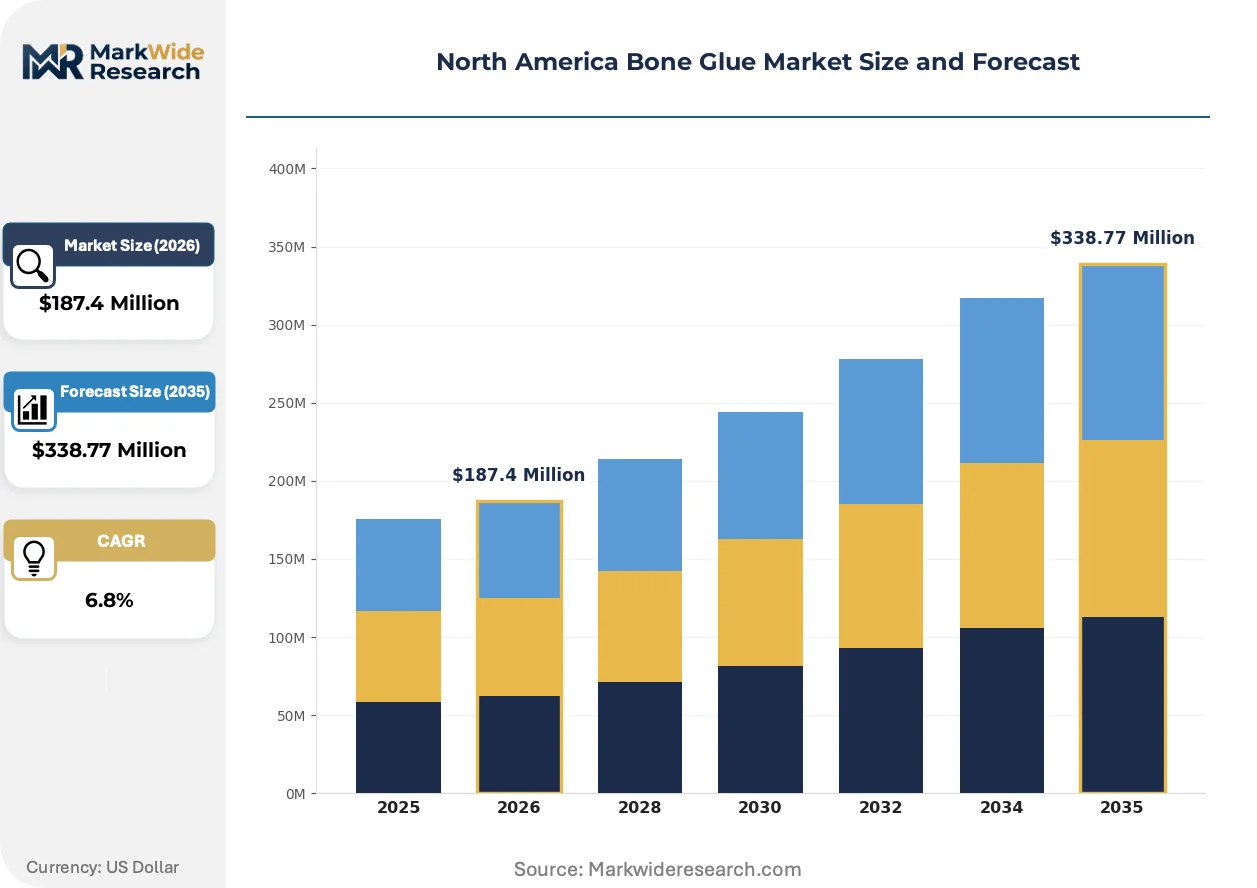
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Collagen, Synthetic Polymers, Cyanoacrylate, Fibrin Adhesives End User: Orthopedic Hospitals, Dental Clinics, Surgical Centers, Veterinary Practices Technology: Cold Adhesive, Hot Melt, Biochemical Crosslinking, UV Curing Application: Bone Repair, Cartilage Reconstruction, Tissue Engineering, Wound Closure |
| Companies Covered | Stryker, Zimmer Biomet, DePuy Synthes, Smith & Nephew, Heraeus Medical, CryoLife, Arthrex, Cardinal Health, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bone Glue Market Evolving Landscape
Biochemical crosslinking platforms are compressing the performance gap between natural and synthetic formulations, while regulatory science advances and procurement centralization reshape competitive access.
Photoinitiated collagen crosslinking is rewriting fixation economics by enabling on-demand curing through arthroscopic delivery channels. Outpatient orthopedic clinics in Texas and Florida surgical corridors are adopting these platforms at twice the rate of inpatient settings. The technology is compressing procedure times and eliminating hardware removal costs from bundled payment calculations.
Health Canada's pending alignment with FDA degradation kinetic characterization standards is forcing dual-track validation studies for cross-border suppliers. Manufacturers now face parallel but distinct biocompatibility testing matrices that extend market entry timelines by eight to twelve months. Synthetic polymer platforms with existing FDA 510(k) clearance bear the heaviest compliance burden as they pursue Health Canada Medical Devices Directorate licensing.
Integrated delivery networks are consolidating procurement authority for orthopedic adhesives into centralized supply chain functions, displacing surgeon-driven preference selection. Hospital purchasing cooperatives in the Northeast are negotiating sole-source agreements for trauma adhesive systems. This concentration is most visible in metropolitan surgical corridors where three health systems control over sixty percent of joint reconstruction volume.
North America Bone Glue Market Segmentation
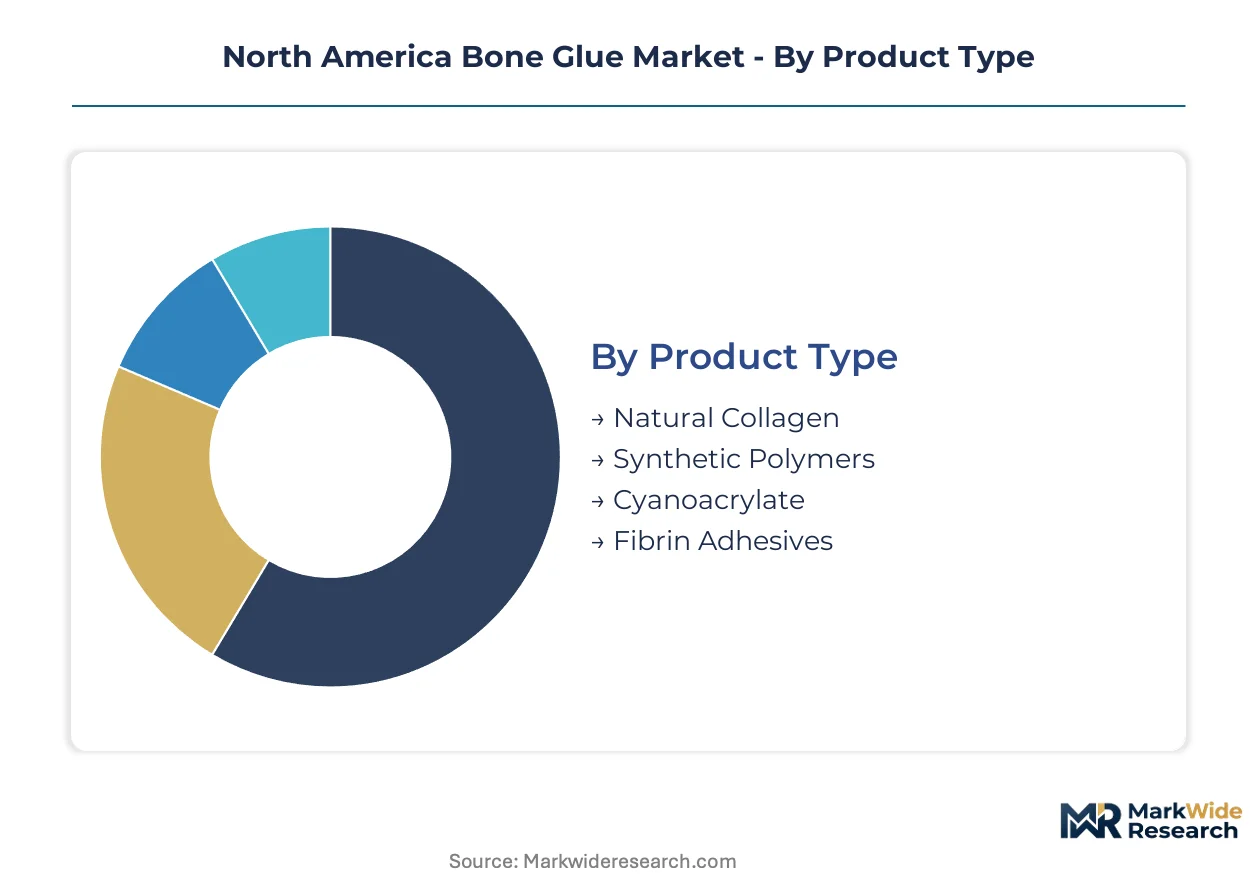
Segmentation in bone adhesives reveals divergent performance requirements across clinical settings. Product chemistry, curing technology, and end-user infrastructure create distinct competitive battlegrounds with margin profiles that reward specialized formulation expertise.
Product Type:
Synthetic polymers command volume leadership through manufacturing scale, while natural formulations capture premium positioning in bioresorbable applications.
- Natural Collagen:Derived from bovine or porcine extracellular matrices, these formulations achieve osteoconductive integration with host bone tissue. Demand concentrates in Northeast academic medical centers where cartilage reconstruction protocols favor 14-day resorption profiles matching chondrocyte migration timelines.
- Synthetic Polymers:Reproducible polyurethane and methacrylate platforms deliver shelf stability exceeding 24 months with shear strengths tunable between 1-4 MPa. Midwest surgical corridors favor these for spinal fusion procedures where batch-to-batch consistency reduces revision risk.
- Cyanoacrylate:Rapid polymerization within 30 seconds suits emergency trauma applications; FDA 510(k) pathways favor these for wound closure adjuncts.
- Fibrin Adhesives:Autologous and pooled plasma derivatives carry premium pricing in sports medicine; Texas and Florida outpatient clinics drive adoption for arthroscopic delivery.
Today's leader: Synthetic Polymers. Tomorrow's challenger: Natural Collagen.
End User:
Site-of-service economics fragment procurement authority, with integrated delivery networks consolidating purchasing power away from individual surgeon preference.
- Orthopedic Hospitals:High-volume joint reconstruction centers in metropolitan corridors anchor demand for bundled adhesive-implant systems. Medicare reimbursement adjustments under the IRA reshape site-of-service economics, compressing margins for suppliers lacking integrated trauma portfolios.
- Surgical Centers:Ambulatory facilities across the United States expand arthroscopic procedures, creating pull-through demand for rapid-setting fibrin adhesives that eliminate hardware removal surgeries from bundled payments.
- Dental Clinics:Maxillofacial applications favor small-volume cyanoacrylate kits; Health Canada licensing requirements create cross-border friction for collagen-based entrants.
- Veterinary Practices:Companion animal orthopedic surgery adopts human-grade formulations at reduced regulatory burden; regional distributors control access.
Procurement consolidation favors Surgical Centers. Orthopedic Hospitals retain pricing power through volume commitment.
Technology:
Curing mechanism selection determines capital equipment requirements and procedure workflow integration.
- Biochemical Crosslinking:Enzyme-mediated or pH-triggered platforms enable tunable set times matched to bone density variations. Spinal fusion applications in United States academic centers drive R&D intensity as manufacturers pursue shear strength parity with mechanical fixation.
- UV Curing:Photoinitiated collagen platforms enable on-demand curing through arthroscopic channels; Texas and Florida outpatient adoption runs twice the inpatient rate.
- Cold Adhesive:Room-temperature storage simplifies logistics for rural surgical access; limited penetration in load-bearing applications.
- Hot Melt:Thermal activation restricts use to open procedures; niche positioning in trauma stabilization.
Biochemical Crosslinking claims the steepest expansion trajectory. UV Curing penetrates fastest in ambulatory settings.
Application:
Clinical indication dictates mechanical requirements and bioresorption timelines, segmenting formulation strategies.
- Cartilage Reconstruction:Fibrin and collagen platforms with 14-day degradation profiles align with chondrocyte migration; Midwest collegiate athletic programs drive sports medicine volume.
- Bone Repair:Load-bearing trauma and joint reconstruction demand shear strengths exceeding 1 MPa; synthetic polymer dominance persists where titanium hardware substitution faces resistance above 2 MPa thresholds.
- Tissue Engineering:Scaffold-adhesive combinations for regenerative applications concentrate in NIH-funded research corridors; commercial scale remains limited.
- Wound Closure:Cyanoacrylate adjuncts for superficial approximation; lowest-margin segment with commodity pricing pressure.
Bone Repair anchors revenue concentration. Cartilage Reconstruction expands most quickly through sports medicine penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan surgical corridors spanning the Northeast and Midwest anchor North American bone glue demand through high-volume joint reconstruction centers and expanding ambulatory networks.
United States
Orthopedic hospitals in Boston, New York, and Chicago metropolitan areas drive concentrated consumption of synthetic polymer formulations for spinal fusion procedures. FDA 510(k) clearance pathways and evolving biocompatibility guidance under ISO 10993 standards shape product entry timelines. Texas and Florida surgical corridors exhibit fastest adoption of photoinitiated collagen platforms in outpatient arthroscopic settings.
Canada
Health Canada's Medical Devices Directorate maintains distinct classification rules creating incremental compliance burdens for cross-border suppliers entering Ontario and Quebec markets. Parallel biocompatibility testing matrices extend market entry timelines for synthetic polymer platforms with existing US clearance. Toronto and Vancouver academic medical centers concentrate demand for fibrin adhesives in cartilage reconstruction protocols.
Mexico
COFEPRIS regulatory harmonization efforts with FDA standards accelerate multinational manufacturer facility investments in Baja California and Nuevo León medical device corridors. Growing private hospital networks in Mexico City and Monterrey expand access to advanced orthopedic adhesives for joint reconstruction. Cost-sensitive procurement patterns favor synthetic polymer formulations with extended shelf stability.
North America Bone Glue Market Competitive Landscape
Global majors compete with regional champions across integrated trauma portfolios and specialized adhesive platforms. The vendor base stratifies into three tiers: diversified orthopedic conglomerates with bundled hardware-adhesive systems, mid-scale specialists focused on crosslinking chemistry innovation, and niche fibrin adhesive suppliers serving sports medicine channels. Dominant competitive moves include procurement consolidation through integrated delivery network sole-source agreements and R&D partnerships targeting tunable curing kinetics.
Among diversified orthopedic conglomerates, Stryker, Zimmer Biomet, and DePuy Synthes exemplify contrasting strategic archetypes. Stryker occupies a position emphasizing integrated trauma portfolio bundling. Zimmer Biomet represents R&D intensity focused on next-generation formulation chemistry. DePuy Synthes exemplifies distribution channel control across major hospital networks. These three entities collectively illustrate how scale, specialization, and channel access define competitive positioning in adhesive-implant combination markets.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| DePuy Synthes |
| Smith & Nephew |
| Heraeus Medical |
| CryoLife |
| Arthrex |
| Cardinal Health |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Photoinitiated collagen crosslinking is compressing production economics while concentrating supply authority among integrated delivery networks that negotiate sole-source adhesive-implant bundles. This technology shift simultaneously reduces per-procedure material costs and elevates procurement consolidation, reshaping how manufacturers allocate margin across formulation innovation versus channel access investments.
Pricing Analysis
Input-cost pass-through from bovine-derived collagen and specialty cyanoacrylate monomers is intensifying margin pressure across natural formulation tiers. Three-tier pricing structure across premium fibrin adhesives, standard synthetic polymers, and economy cyanoacrylate kits differentiates by biocompatibility certification grade and set-time performance. Cost compression in economy segments is intensifying because Gulf Coast petrochemical corridor volatility disrupts synthetic monomer supply. Ambulatory surgery centers exhibit highest price sensitivity due to bundled payment constraints, while academic medical centers absorb premium positioning for cartilage reconstruction protocols.
Supply Chain Analysis
Cold-chain logistics and temperature-controlled freight costs are elevating landed costs for fibrin adhesive platforms requiring frozen distribution. Raw material sourcing draws from North American abattoir networks for collagen matrices, Gulf Coast petrochemical complexes for cyanoacrylate monomers, and pooled plasma processing facilities for fibrinogen-thrombin components. Single-source vulnerability concentrates in bovine-derived collagen supply from primary processing states facing herd health cycle disruptions. Distribution runs through integrated delivery network procurement consortia that have displaced traditional distributor relationships in metropolitan surgical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's pending guidance on degradable synthetic polymer characterization functions as a regulatory compounder, accelerating demand for validated crosslinking platforms that secure expedited review pathways.
For Market Incumbents: Anchor market position through backward integration into collagen processing and captive supply of crosslinking reagents. Invest in ISO 10993-5 cytotoxicity testing infrastructure ahead of Health Canada alignment mandates. Defend against mid-scale specialists by controlling GPO contract access across Veterans Health Administration procurement channels. For New Entrants and Emerging Players: Pediatric orthopedic surgeons represent an underserved buyer archetype with unmet need for growth-plate-sparing resorbable platforms. Target sports medicine channels in Midwest collegiate athletic programs where 14-day bioresorbability profiles command premium positioning. Pursue white-label manufacturing partnerships with established trauma portfolio holders to bypass 510(k) predicate device pathway erosion. For Investors and Strategic Acquirers: Roll-up economics work for biochemical crosslinking specialists because polymer characterization expertise scarcity concentrates in limited academic medical centers. Five-to-ten-year viability hinges on FDA clearance velocity for tunable curing kinetics platforms. Monitor Health Canada Medical Devices Directorate licensing timelines as inflection indicator for cross-border supply consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Biochemical Crosslinking Platform | Expedited review status under pending degradable polymer guidance accelerates market entry timelines. |
| Hospital System Partnership for Trauma Adhesive Bundles | Sole-source agreements with Northeast integrated delivery networks displace competitor hardware-implant combinations. |
| Backward Integration into Bovine Collagen Processing | Captive supply from North American abattoir networks insulates against export restriction volatility. |
| Reimbursement Strategy for Outpatient Arthroscopic Delivery | IRA site-of-service economics favor rapid-setting adhesives that eliminate hardware removal costs. |
| CE Marking Pathway for Synthetic Polymer Export | EU MDR biocompatibility alignment opens parallel revenue streams beyond FDA-cleared indications. |
Research Methodology
Multiple input streams — orthopedic surgeon interviews, hospital procurement committee discussions, biomedical engineer technical assessments, and GPO contracts manager consultations — were reconciled against FDA 510(k) filing databases, Health Canada Medical Devices Directorate licensing records, CMS Medicare reimbursement data, and ISO 10993 biocompatibility standard documentation. Bottom-up demand modeling from procedure volume estimates was cross-validated through top-down manufacturer revenue triangulation across synthetic polymer, natural collagen, and fibrin adhesive product categories.
Historical volume trajectories were cross-referenced against expert panel inputs from regulatory affairs specialists and trauma portfolio strategists to construct analytical frameworks across product chemistry, curing technology, end-user infrastructure, and application indication dimensions. CAGRs were derived from segmented growth rate reconciliation throughout the projection horizon. Forecast inputs incorporated evolving FDA biocompatibility guidance timelines, IRA reimbursement adjustment impacts, and Health Canada-PMRA regulatory harmonization progress.
Underlying measurement precision varies by segment; synthetic polymer volumes carry tighter precision than emerging biochemical crosslinking platforms where commercial scale remains limited. Forecasts reflect assumptions regarding regulatory clearance velocity, procurement consolidation rates, and supply chain disruption frequency that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market