
 US Antifouling Yacht Coatings Market | 2026-2036
US Antifouling Yacht Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
US Antifouling Yacht Coatings Market Intelligence
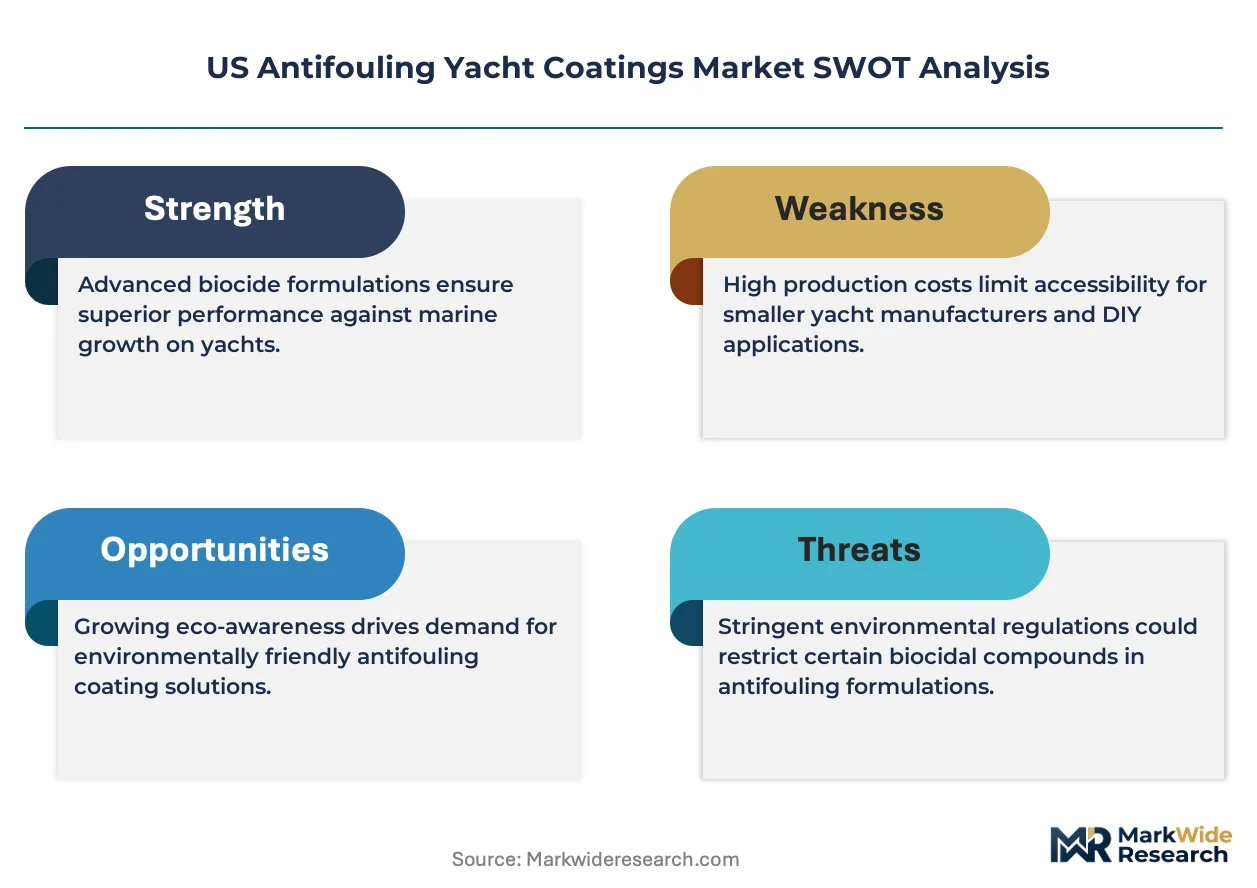
EPA VGP compliance certification is rotating supplier eligibility toward low-biocide and biocide-free portfolios. AkzoNobel leverages its Intersleek silicone technology to dominate premium yacht maintenance channels. Hempel A/S anchors its position through deep shipyard partnerships along the Gulf Coast. PPG Industries competes on water-based formulation scale across Pacific Northwest boat-building centers.
US antifouling yacht coatings are specialized marine protective layers engineered to prevent biofouling organism attachment through controlled biocide release or non-stick surface chemistry, with film thickness typically ranging 150-400 microns and active service lives of 12-36 months depending on fouling intensity and operating regime. Self-polishing copolymer systems dominate commercial vessel applications where predictable abrasion rates align with dry-docking schedules, while biocide-free silicone variants capture margin pools in superyacht segments where port-state environmental scrutiny intensifies. Water-based formulations sustain growth in OEM boat manufacturing as VOC thresholds tighten, whereas solvent-based epoxy primers retain structural share in heavy-duty commercial yacht maintenance cycles.
Federal oversight from EPA under the Clean Water Act Vessel General Permit and state-level enforcement by California DTSC through Safer Consumer Products regulations collectively constrain copper pyrithione and zinc oxide deployment, forcing reformulation investments. The US Coast Guard adds inspection-layer compliance for documented vessels operating in federally controlled waters. Stakeholders must monitor pending EPA reassessment of copper-based antifouling under the Federal Insecticide, Fungicide, and Rodenticide Act, as this single regulatory action would force immediate portfolio restructuring across the value chain.
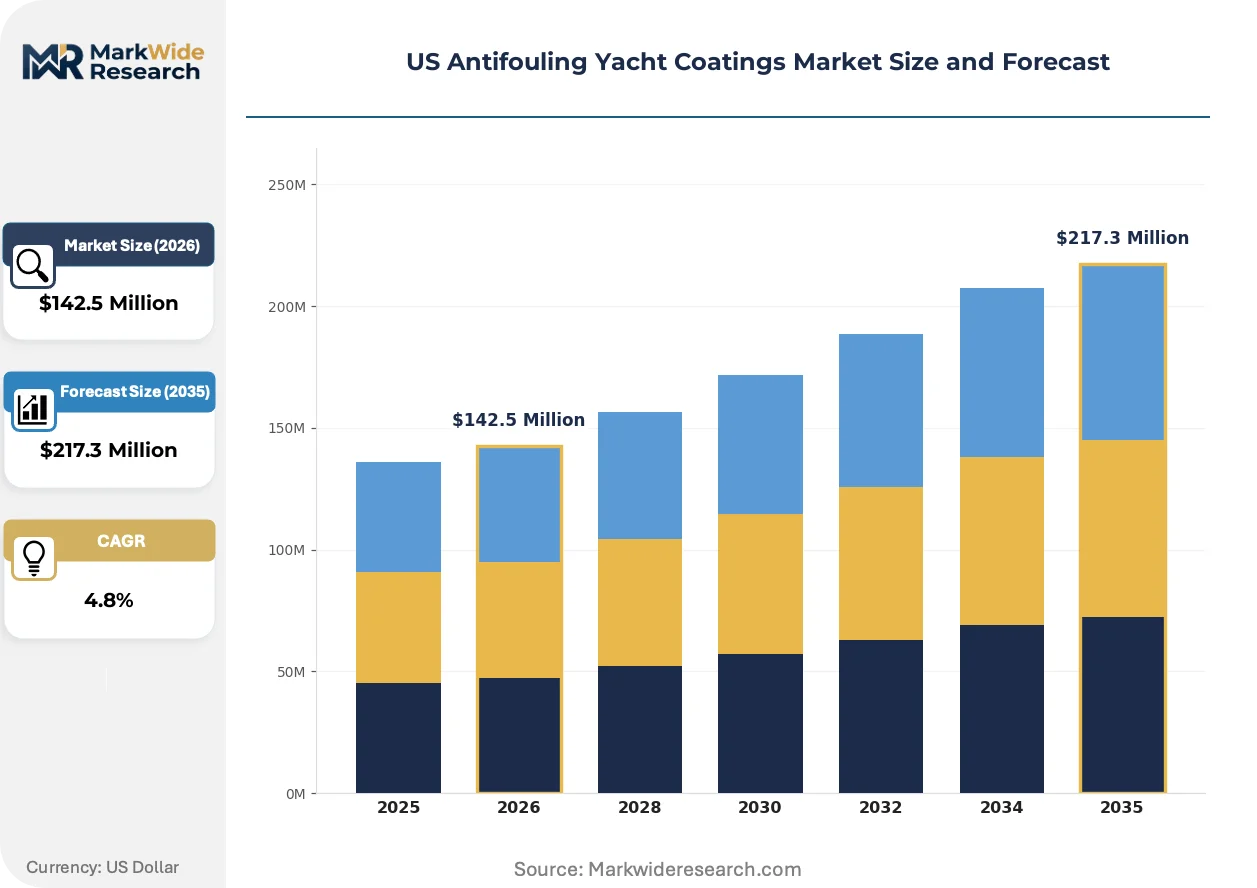
Market Dynamics
EPA's pending copper reassessment under FIFRA is forcing immediate portfolio restructuring across the value chain, compressing legacy biocide reliance while accelerating silicone-hybrid and copper-free formulation investments.
Growth Catalysts
- Florida recreational fleet expansion:The state's documented vessel registrations exceed 950,000 units, creating concentrated dry-docking demand that absorbs premium antifouling systems at 18-24 month reapplication cycles.
- EPA Vessel General Permit tightening:Biocide discharge limits in federally controlled waters are rotating supplier eligibility toward low-biocide portfolios, disqualifying legacy copper-heavy formulations from documented yacht maintenance channels.
- Silicone-hybrid surface chemistry:Non-stick fouling release systems are capturing margin pools in superyacht segments where port-state environmental scrutiny intensifies and hull cleaning frequency compresses operating costs.
Market Restraints
- Copper pyrithione input volatility:Primary biocide raw material sourcing concentrates among three global chemical suppliers, exposing US formulators to price swings and forced reformulation costs when EPA thresholds shift.
- Silicone resin supply concentration:Specialty polymer feedstock production clusters in Northeast US and Gulf Coast petrochemical corridors, creating geographic vulnerability to hurricane disruption and logistics bottlenecks.
- California DTSC Safer Consumer Products enforcement:State-level zinc oxide restrictions add compliance layer beyond federal VGP requirements, fragmenting formulation standards across US jurisdictions and raising SKU complexity.
Strategic Opportunities
- Pacific Northwest water-based OEM penetration:Washington and Oregon boat-building centers face tightening VOC thresholds that favor water-based formulation scale, displacing solvent-based primers in new construction.
- US Coast Guard inspection-layer compliance services:Documented vessel operators require certified coating application documentation, creating attachable compliance service revenue beyond product sales.
- Silicone-ceramic hybrid convergence:Hard foul-resistant surface technologies are opening service-life extension claims in commercial charter fleets where dry-docking frequency directly determines operating economics.
Industry Challenges
- Applicator certification bottlenecks:EPA-certified marine coating applicator programs face 6-9 month training backlogs, constraining service capacity during seasonal maintenance windows in Southeast shipyard clusters.
- Legacy hull substrate incompatibility:Silicone-hybrid systems require complete epoxy primer removal from existing copper-based coatings, doubling labor intensity and customer switching friction in refit markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Antifouling Yacht Coatings Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Cleaning, Hard Paint, Soft Antifouling, Biocide-Free Application: Commercial Vessels, Recreational Boats, Cargo Ships, Yacht Maintenance End User: Boat Owners, Shipyards, Manufacturing Companies, Marine Service Providers Formulation: Water-Based, Solvent-Based, Hybrid, Epoxy |
| Companies Covered | AkzoNobel, Hempel A/S, Jotun A/S, PPG Industries, Sherwin-Williams, RPM International, Nippon Paint Holdings, Chugoku Marine Paints, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Antifouling Yacht Coatings Market Strategic Shifts & Innovations
Antifouling chemistry is diverging into two parallel development tracks: biocide-controlled release systems optimizing for regulatory compliance, and biocide-free surface engineering targeting environmental certification premiums.
Silicone-hybrid fouling release technology is bifurcating competitive positioning between premium superyacht maintenance and emerging commercial charter applications. Superyacht owners in Florida and California are adopting these systems at accelerated 12-18 month evaluation cycles. The technology is compressing traditional self-polishing copolymer margins while enabling 36-48 month service life claims that reshape dry-docking economics.
EPA's pending FIFRA reassessment of copper-based antifouling is compressing formulation timelines across the supplier base. The industrial consequence is immediate R&D redirection toward copper pyrithione alternatives and zinc oxide reduction strategies. Southeast US shipyards serving documented recreational fleets are most affected, with suppliers pre-positioning biocide-free portfolios ahead of enforcement dates.
Buyer preference is rotating toward bundled compliance documentation in Pacific Northwest and Gulf Coast maintenance channels. Independent boatyards are displacing product-only transactions with certified application packages that include EPA discharge permit alignment. This pattern is most visible in California and Washington state markets where DTSC and state water board enforcement creates liability exposure for uncertified work.
US Antifouling Yacht Coatings Market Segmentation
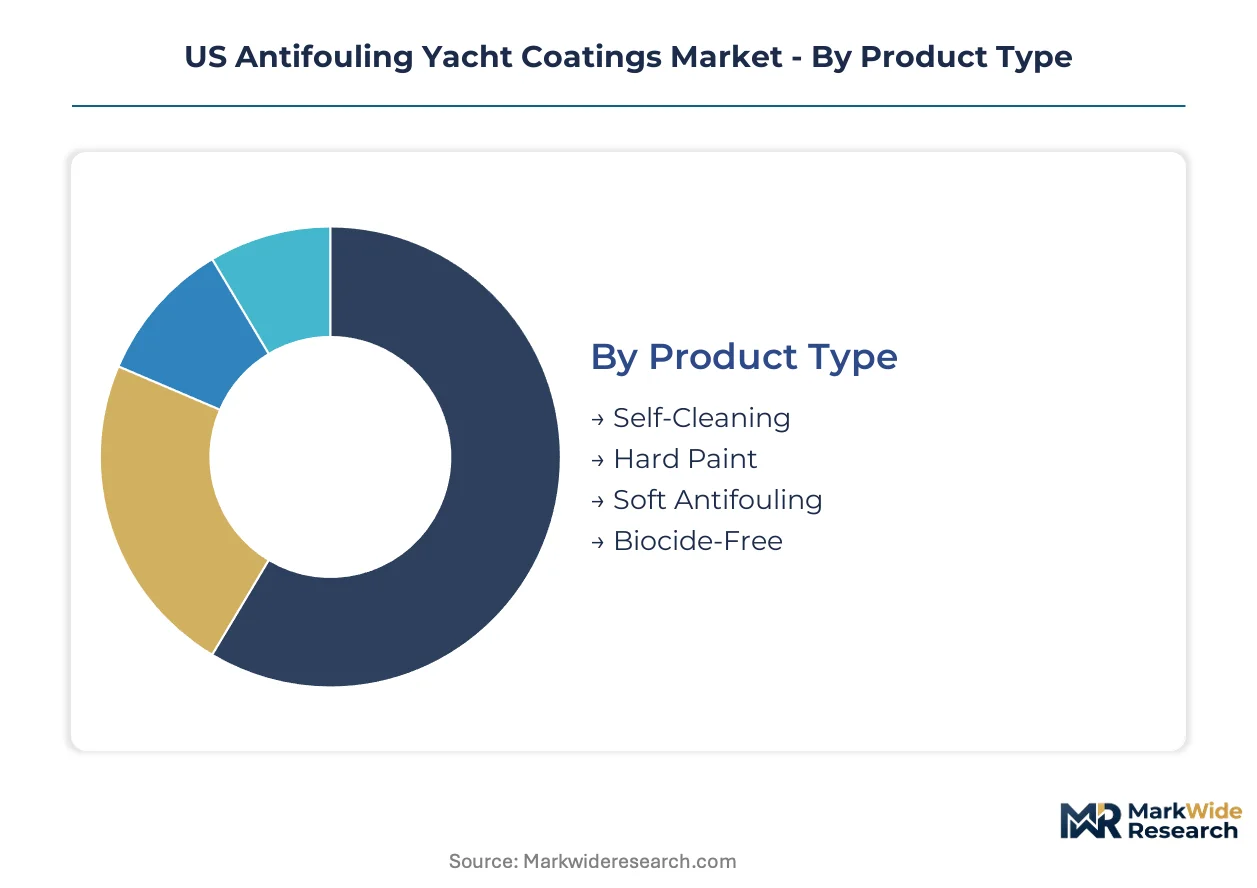
Antifouling yacht coating segments face divergent substitution pressures as EPA VGP compliance rotates demand toward biocide-free alternatives while legacy formulations retain entrenched positions in cost-sensitive maintenance channels. Understanding segment boundaries reveals where reformulation investments concentrate and which customer groups drive premium pricing.
Product Type:
Self-polishing and controlled-release systems face the strongest substitution threat from silicone-hybrid fouling release technologies as superyacht owners accelerate evaluation cycles.
- Self-Cleaning:Controlled-release copolymer systems maintain predictable abrasion rates that align with scheduled dry-docking intervals. Florida recreational fleets absorb these formulations at 18-24 month reapplication cycles, though EPA copper reassessment is compressing their regulatory runway.
- Hard Paint:Epoxy-modified ablative coatings deliver durable film integrity for commercial charter operations in high-fouling Southeast US waters. California DTSC zinc oxide restrictions fragment formulation standards, forcing state-specific SKU proliferation.
- Soft Antifouling:Low-abrasion vinyl formulations suit seasonal recreational craft with limited operating hours.
- Biocide-Free:Silicone-hybrid surface chemistry captures environmental certification premiums in port-state scrutinized segments.
Self-Cleaning retains volume leadership; Biocide-Free holds the steepest expansion curve.
Application:
Customer procurement patterns split between OEM specification lock-in and aftermarket maintenance flexibility, with geography determining regulatory exposure intensity.
- Commercial Vessels:Documented fleet operators require Coast Guard-certified coating documentation, creating attachable compliance service revenue. Gulf Coast shipyards anchor demand for heavy-duty epoxy primer systems with 24-36 month service life requirements.
- Recreational Boats:California and Florida boat owners drive water-based formulation scale as VOC thresholds tighten in Pacific Northwest manufacturing centers. EPA VGP discharge limits disqualify legacy copper-heavy formulations from documented maintenance channels.
- Cargo Ships:Bulk carrier dry-docking schedules favor predictable self-polishing abrasion rates.
- Yacht Maintenance:Refit markets face substrate incompatibility friction when transitioning from copper-based to silicone-hybrid systems.
Recreational Boats commands the broadest geographic footprint; Commercial Vessels generates the highest compliance-attach revenue per hull.
End User:
Certification requirements fragment addressable market access, with EPA-certified applicator bottlenecks constraining service capacity during seasonal maintenance windows.
- Boat Owners:Independent recreational operators in Southeast US clusters prioritize cost-per-season over lifecycle economics, sustaining legacy biocide demand despite regulatory headwinds. Seasonal maintenance windows concentrate purchasing decisions into compressed Q1-Q2 periods.
- Shipyards:Deep partnerships along the Gulf Coast and Pacific Northwest determine formulation specification lock-in for new construction. Washington and Oregon centers face tightening VOC thresholds that favor water-based scale.
- Manufacturing Companies:OEM boat builders specify coating systems during hull fabrication.
- Marine Service Providers:Independent applicators face 6-9 month EPA certification backlogs.
Shipyards control specification authority for newbuild coatings; Boat Owners drive aftermarket volume concentration.
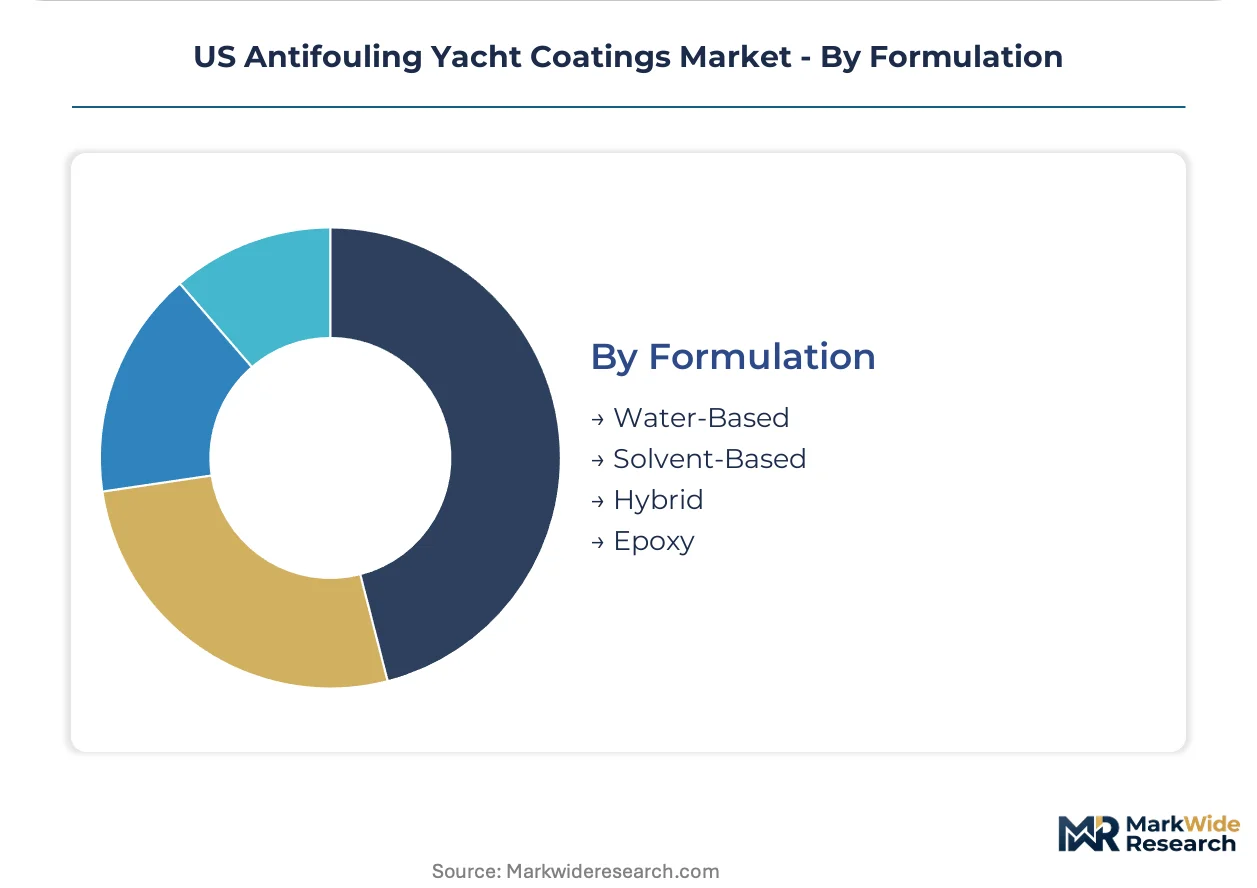
Formulation:
Environmental compliance layering creates formulation complexity, with federal and state thresholds operating on divergent timelines.
- Water-Based:Low-VOC acrylic dispersions sustain growth in OEM boat manufacturing as Washington and Oregon thresholds tighten. Pacific Northwest boat-building centers displace solvent-based primers in new construction through regulatory preference.
- Solvent-Based:Epoxy and polyurethane systems retain structural share in heavy-duty commercial maintenance cycles. Gulf Coast shipyards serving documented recreational fleets specify these formulations for substrate adhesion reliability.
- Hybrid:Water-reducible alkyd modifications bridge performance and compliance requirements.
- Epoxy:High-build primer systems provide barrier protection for hull substrates in aggressive fouling environments.
Solvent-Based maintains installed base dominance; Water-Based climbs the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VGP compliance deadlines and state-level biocide restrictions are redistributing demand intensity across US coastal zones, concentrating premium formulation procurement in jurisdictions with overlapping federal and environmental enforcement layers.
Southeast (Florida/Georgia)
Florida's 950,000 registered vessels generate concentrated dry-docking demand at 18-24 month reapplication cycles. EPA discharge limits in federally controlled waters disqualify legacy copper-heavy formulations from documented maintenance channels. Miami-Fort Lauderdale shipyard clusters absorb premium silicone-hybrid systems as superyacht refit volume concentrates in South Florida.
Pacific Northwest (Washington/Oregon)
Washington and Oregon boat-building centers face tightening VOC thresholds that favor water-based formulation scale in new construction. State water board enforcement creates liability exposure for uncertified coating applications, displacing solvent-based primers. Seattle-Tacoma manufacturing corridors specify low-VOC acrylic dispersions during hull fabrication.
California
DTSC Safer Consumer Products regulations add zinc oxide restrictions beyond federal VGP requirements, fragmenting formulation standards and raising SKU complexity. Recreational boat owners in San Diego and Newport Beach drive water-based scale as environmental scrutiny intensifies. Los Angeles-Long Beach port-state enforcement elevates demand for bundled compliance documentation.
Gulf Coast (Texas/Louisiana)
Deep shipyard partnerships anchor heavy-duty epoxy primer demand for commercial charter operations with 24-36 month service life requirements. Hurricane disruption vulnerability in Gulf Coast petrochemical corridors creates silicone resin supply concentration risk. Houston-Galveston maintenance channels retain structural share for solvent-based systems in substrate adhesion-critical applications.
Northeast (New England/Mid-Atlantic)
Seasonal recreational craft with limited operating hours sustain low-abrasion vinyl formulation demand in compressed Q1-Q2 maintenance windows. EPA-certified applicator training backlogs constrain service capacity during peak seasonal demand. Newport and Annapolis yacht service centers pre-position biocide-free portfolios ahead of pending enforcement dates.
US Antifouling Yacht Coatings Market Key Industry Players
Listed leaders compete with private specialists across formulation technology tiers, creating a consolidated premium segment alongside fragmented mid-market supply. The vendor base clusters around three strategic poles: integrated chemical conglomerates with marine divisions, standalone coating specialists with deep shipyard relationships, and regional applicator networks with certification-layer service attach. Dominant competitive moves include portfolio diversification into biocide-free alternatives and geographic expansion through EPA-certified applicator program licensing.
Within the integrated chemical tier, AkzoNobel N.V. and BASF SE exemplify scale-driven formulation breadth, while Hempel A/S occupies a position as a private specialist with concentrated marine coating heritage. These three anchors represent distinct competitive archetypes: the diversified conglomerate leveraging cross-divisional R&D, the focused specialist capturing premium margins through application expertise, and the hybrid player balancing industrial scale with segment-specific technical service depth.
| Leading Market Players |
|---|
| AkzoNobel |
| Hempel A/S |
| Jotun A/S |
| PPG Industries |
| Sherwin-Williams |
| RPM International |
| Nippon Paint Holdings |
| Chugoku Marine Paints |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day silicone resin lead times concentrate pricing power among Gulf Coast and Northeast US petrochemical suppliers, compressing margin flexibility for formulators while EPA copper reassessment accelerates biocide-free portfolio transitions. Inventory cycles for copper pyrithione feedstock run tighter as three global chemical suppliers throttle availability ahead of regulatory thresholds.
Pricing Analysis
Certification level (EPA VGP-compliant vs. legacy formulations) creates the primary spread between premium silicone-hybrid systems and commodity copper-based alternatives. Three-tier pricing structure separates superyacht maintenance bundles from standard recreational refits and economy seasonal applications. Cost compression in legacy biocide tiers is intensifying because EPA discharge limits disqualify copper-heavy formulations from documented vessel channels. Independent recreational operators in Florida and Georgia exhibit highest price sensitivity, while commercial charter fleets in the Gulf Coast absorb premium pricing for extended service-life claims.
Supply Chain Analysis
Hurricane corridor vulnerability through Houston-Galveston petrochemical clusters exposes silicone resin availability to seasonal disruption. Specialty polymer feedstock production centers on the US Gulf Coast, Northeast petrochemical corridors, and imported Japanese silicone intermediates. Raw material dependencies include copper pyrithione biocides, zinc oxide pigments, and epoxy resin binders. Single-source vulnerability concentrates among three global copper pyrithione suppliers. Distribution runs through EPA-certified applicator networks and direct shipyard partnerships along coastal maintenance corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US antifouling yacht coatings market sits in early-cycle expansion as silicone-hybrid penetration accelerates from superyacht refit channels into commercial charter applications. EPA regulatory tailwinds are compressing legacy biocide runway while opening margin pools for biocide-free portfolios.
For Market Incumbents: Fortify Gulf Coast and Pacific Northwest shipyard partnerships before applicator certification backlogs constrain seasonal service capacity. Deepen backward integration into silicone resin supply through Northeast petrochemical corridor offtake agreements. Accelerate R&D redirection toward copper pyrithione alternatives ahead of EPA FIFRA enforcement dates. For New Entrants and Emerging Players: Differentiate on bundled compliance documentation services that attach to coating sales in California and Washington state markets. Target water-based formulation scale in Pacific Northwest OEM boat-building centers where VOC thresholds tighten fastest. Pursue EPA-certified applicator licensing as the primary go-to-market angle to bypass incumbent specification lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming marine coating divisions facing portfolio restructuring pressure. Long-term viability hinges on biocide-free technology ownership and regional applicator network density. Watch EPA copper reassessment publication timing as the critical inflection signal for immediate portfolio revaluation across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Biocide-Free Portfolio Expansion | EPA VGP compliance rotates supplier eligibility toward low-biocide alternatives in documented vessel channels. |
| EPA-Certified Applicator Licensing | Six-to-nine-month training backlogs create attachable service revenue and specification control in Southeast clusters. |
| Silicone Resin Backward Integration | Hurricane vulnerability in Gulf Coast petrochemical corridors demands captive supply security for formulation continuity. |
| Pacific Northwest OEM Partnership | Washington and Oregon VOC thresholds favor water-based scale in new construction specification lock-in. |
| Compliance Documentation Bundling | California DTSC and state water board enforcement elevates liability exposure for uncertified coating applications. |
Research Approach
A spread of perspectives from marine coating formulators, shipyard procurement directors, EPA compliance officers, and recreational fleet operators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA VGP discharge records, US Coast Guard vessel documentation databases, state water board enforcement actions, and customs import data for specialty resin feedstocks. Bottom-up hull-count modeling triangulated against top-down formulation value estimates across the projection horizon.
Segmentation dimensions modeled include product type (self-cleaning, hard paint, soft antifouling, biocide-free), application channel (OEM new construction versus aftermarket refit), formulation chemistry (water-based, solvent-based, hybrid), and regional regulatory cluster (federal VGP waters, California DTSC jurisdiction, Pacific Northwest VOC thresholds). CAGRs derived from hull stock growth projections, reapplication cycle compression, and premium formulation penetration curves. Industry-specific inputs encompass Florida vessel registration trajectories, superyacht dry-docking frequency trends, and silicone-hybrid service-life validation data.
The analysis sits within stated boundaries; outcomes outside EPA enforcement timing assumptions or hurricane disruption severity would require recalibration. Forecasts reflect documented regulatory trajectories and vessel fleet growth assumptions. Practitioners should keep alternative scenarios live as EPA FIFRA reassessment conclusions and state-level biocide restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
China Marine Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Heavy Duty Glass Coating Market
Coatings
Extrusion Coating Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Global Conformal Coatings Market
Coatings
Polyester Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Cladding Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Global Smart Coating Market