
 Polyester Hot Melt Adhesives Market | 2026-2036
Polyester Hot Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Hot Melt Adhesives Market Intelligence
Automotive interior assembly is shifting toward polyester hot melt adhesives as manufacturers reduce mechanical fasteners and solvent-based bonding systems. Henkel AG & Co. KGaA leverages its automotive OEM relationships to sustain formulation leadership across Europe and Asia. H.B. Fuller Company anchors its position through specialized high-temperature grades that compete in under-the-hood applications where thermal cycling demands exceed conventional adhesive limits.
Polyester hot melt adhesives are thermoplastic compositions formed through polycondensation of dicarboxylic acids with diols, typically exhibiting melt viscosities between 2,000 and 50,000 mPa·s at application temperatures of 120°C to 200°C, designed to provide rapid green strength without solvent curing in automated production environments. Rigid formulations dominate current volume owing to their established use in furniture edgebanding and packaging consolidation, while elastic grades represent the fastest-expanding category as wearable electronics and flexible automotive trim demand fatigue-resistant bond lines. High viscosity variants command margin premiums in coating applications where controlled flow prevents substrate bleed-through on porous textiles and nonwoven materials.
EPA regulates volatile organic compound emissions from adhesive production facilities under NESHAP standards, while REACH mandates disclosure of isocyanate and phthalate content in imported formulations, effectively filtering non-compliant suppliers from European market access. FDA indirect food contact regulations under 21 CFR 175.105 shape product development for labeling adhesives used in primary food packaging. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as California's Safer Consumer Products program already probes alternative chemistries that could displace incumbent polyester formulations in sensitive applications.
Market Dynamics
Automotive OEMs are systematically eliminating mechanical fasteners from interior assemblies, creating structural pull for polyester hot melt adhesives that bond dissimilar substrates without curing delays or solvent emissions. This transition compresses bonding cycle times while forcing adhesive suppliers to certify formulations against increasingly stringent thermal and VOC specifications.
Growth Catalysts
- REACH Phase-Out of Solvent-Based Alternatives:ECHA's tightening volatile organic compound thresholds under Annex XVII are disqualifying legacy contact cements from European automotive interior contracts, redirecting specification authority toward compliant thermoplastic options.
- Wearable Electronics Assembly:Fatigue-resistant elastic polyester grades are capturing specification wins in flexible circuit lamination where cyclic bending demands exceed conventional adhesive capabilities.
- Automated Dispensing Integration:German component manufacturers in Baden-Württemberg are retrofitting production lines with precision hot melt applicators that eliminate clamping stations and reduce work-in-process inventory.
Market Restraints
- Petrochemical Feedstock Volatility:Purified terephthalic acid and adipic acid prices fluctuate with crude oil benchmarks, compressing margin predictability for formulation houses lacking backward integration into diacid production.
- High-Temperature Performance Ceiling:Polyester chemistry degrades above 150°C continuous service temperature, excluding the adhesive from powertrain applications where polyamide and polyimide alternatives dominate.
- Specialty Diol Supply Concentration:European producers depend on a limited number of butanediol and hexanediol suppliers in the Rhine-Ruhr industrial corridor, creating geographic concentration risk for raw material security.
Strategic Opportunities
- India PLI Scheme for Electronics Manufacturing:Production-linked incentives for mobile device and component assembly are attracting contract manufacturers that require localized adhesive supply chains with REACH-equivalent compliance documentation.
- Bio-Based Diol Substitution:Fermentation-derived 1,3-propanediol from renewable feedstocks is reaching cost parity with petroleum-based glycols, enabling carbon footprint differentiation for sustainability-mandated procurement.
- Medical Device Textile Lamination:FDA 21 CFR 175.105 compliant polyester grades are penetrating surgical drape and gown manufacturing where gamma sterilization compatibility and skin contact safety create specification stickiness.
Industry Challenges
- Formulation Chemist Talent Scarcity:Polycondensation expertise and rheology optimization for automated application systems reside with aging technical workforces in European and Japanese specialty chemical clusters.
- Multi-Regulatory Certification Overlap:Simultaneous compliance with EPA NESHAP, REACH SVHC disclosure, and FDA indirect food contact requirements extends product development timelines and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Hot Melt Adhesives Market |
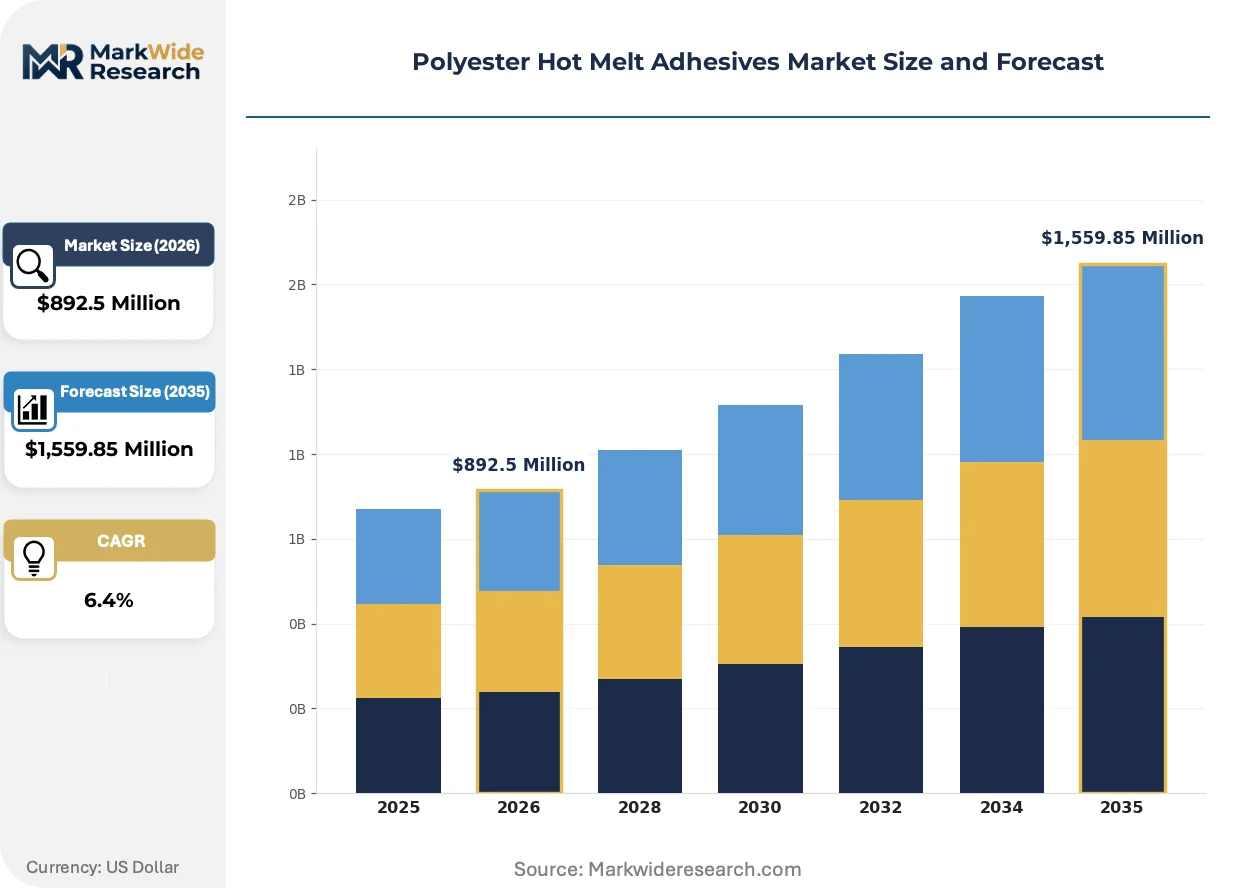
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,559.85 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Viscosity, High Viscosity, Elastic, Rigid End User: Packaging, Automotive, Electronics, Furniture Application: Labeling, Bonding, Coating, Sealing Technology: Hot Melt Extrusion, Spray Application, Film Coating, Injection Molding |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, 3M Company, Arkema (Bostik), Dow Inc., Evonik Industries AG, Jowat SE, Avery Dennison Corporation, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Hot Melt Adhesives Market Strategic Shifts & Innovations
Reactive polyester hot melt technology is collapsing the traditional trade-off between thermoplastic processing speed and thermoset bond durability, enabling structural load-bearing applications previously reserved for two-part epoxies.
Hybrid copolyester formulations incorporating latent curing agents are integrating into automotive composite bonding operations where crashworthiness requirements demand cohesive failure modes rather than adhesive interface failure. Tier 1 suppliers in Stuttgart and Wolfsburg are qualifying these grades for carbon fiber reinforced plastic roof module attachment, compressing the competitive window for conventional polyurethane reactive hot melts. The technology is integrating quality control protocols that monitor viscosity drift during heated hose delivery, preventing off-ratio application that previously required destructive testing.
REACH restriction proposals targeting microplastic release from textile finishing operations are redirecting research investment toward hydrolytically stable polyester compositions that resist environmental degradation. ECHA's 2023 restriction roadmap specifically flags synthetic polymer-based textile coatings, forcing adhesive developers to document biodegradation pathways or secure polymer of low concern status. German technical textile manufacturers are responding by pre-qualifying suppliers with completed OECD 306 biodegradation dossiers ahead of anticipated enforcement windows.
Automotive interior procurement teams are consolidating adhesive specification authority from individual plant engineers to central commodity managers with pan-regional portfolios. This concentration compresses supplier negotiation cycles from quarterly to annual frameworks while elevating technical service capabilities as a selection criterion above unit pricing. The shift is most visible in Volkswagen Group and BMW sourcing organizations where adhesive approval now requires simultaneous validation across German, Mexican, and Chinese production facilities.
Polyester Hot Melt Adhesives Market Segmentation
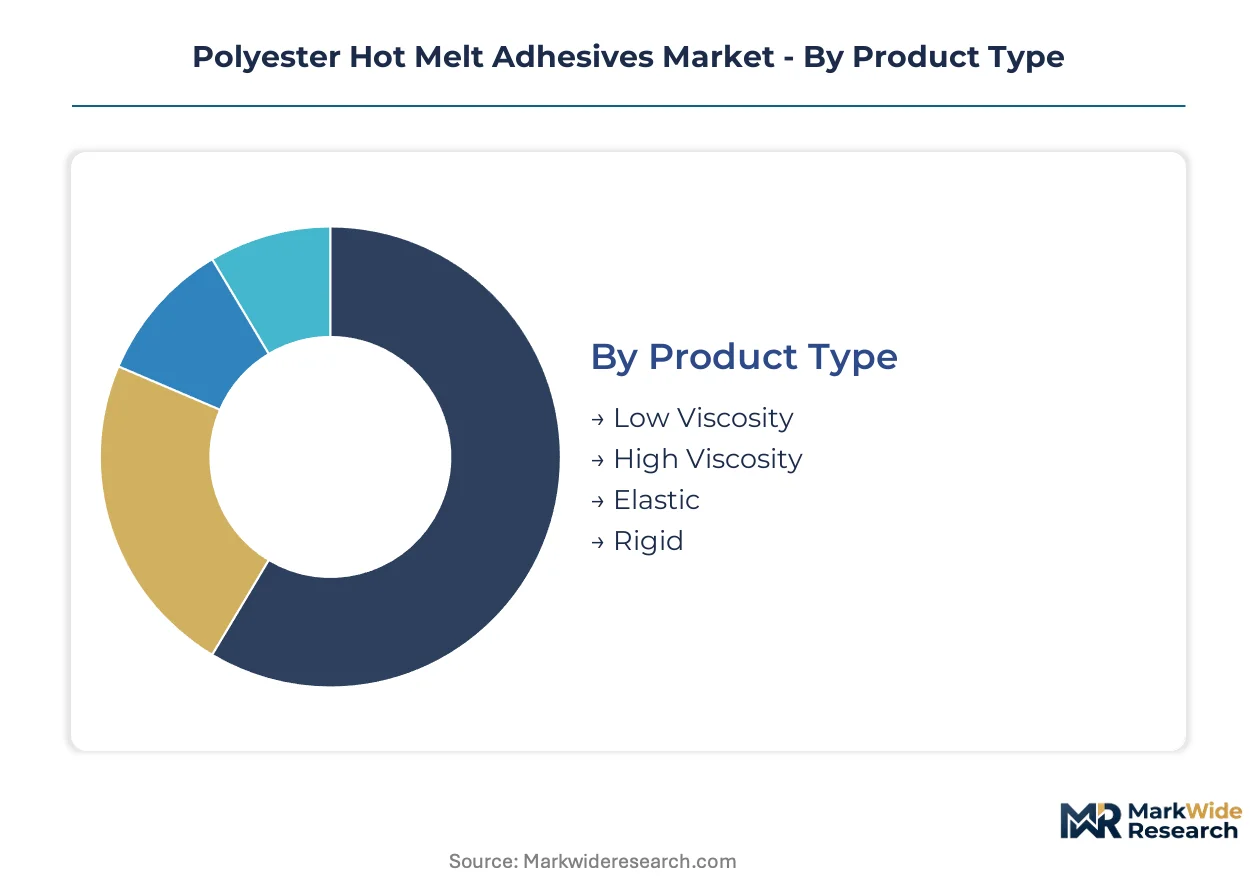
Polyester hot melt adhesives demand diverges sharply across viscosity grades, end-use durability requirements, and application equipment constraints. Capital allocation decisions favor segments with automated dispensing compatibility and regulatory pre-certification that compress customer qualification timelines.
Product Type:
High viscosity and elastic formulations demand the heaviest upfront investment in precision extrusion equipment and rheology testing infrastructure.
- High Viscosity:Melt viscosities exceeding 20,000 mPa·s at 180°C enable controlled flow on porous textiles without substrate bleed-through. Demand concentrates in German technical textile lamination where coating weight precision determines bond line integrity.
- Elastic:Polybutylene terephthalate copolyesters and aliphatic polyester-amide hybrids deliver fatigue resistance across 10,000+ bend cycles. Wearable electronics manufacturers in Shenzhen and Stuttgart specify these grades for flexible circuit lamination where cyclic loading exceeds conventional adhesive capabilities.
- Low Viscosity:Formulations between 2,000 and 8,000 mPa·s suit high-speed labeling applicators on beverage packaging lines.
- Rigid:High crystallinity homopolyesters provide rapid green strength for furniture edgebanding and corrugated board consolidation.
Rigid formulations absorb the bulk of installed capacity; elastic grades are expanding most quickly.
End User:
Automotive and electronics procurement teams now consolidate specification authority from plant engineers to central commodity managers, elevating technical service capabilities above unit pricing in supplier selection.
- Automotive:Interior trim bonding and carbon fiber reinforced plastic module attachment dominate specification wins. OEMs in Wolfsburg and Stuttgart systematically eliminate mechanical fasteners, redirecting contracts toward REACH-compliant thermoplastic options that bond dissimilar substrates without curing delays.
- Electronics:Mobile device assembly and flexible circuit lamination drive fatigue-resistant grade adoption. India's PLI scheme for electronics manufacturing attracts contract manufacturers requiring localized supply chains with REACH-equivalent compliance documentation.
- Packaging:High-speed labeling and case sealing operations favor low-viscosity formulations with FDA 21 CFR 175.105 indirect food contact approval.
- Furniture:Edgebanding and veneer lamination sustain volume demand for rapid-crystallizing rigid grades.
Automotive absorbs the bulk of installed capacity; electronics is climbing the fastest.
Application:
Bonding and coating applications command premium margins through specification stickiness, while labeling competes on throughput efficiency and raw material cost position.
- Bonding:Structural assembly of dissimilar substrates in automotive interiors and composite modules. Crashworthiness requirements in German Tier 1 supplier specifications favor cohesive failure modes over adhesive interface failure.
- Coating:Technical textile lamination and nonwoven saturation demand viscosity stability across heated hose delivery systems. Quality control protocols monitor drift prevention to eliminate destructive testing requirements.
- Labeling:Pressure-sensitive conversion and primary food packaging applications require FDA-compliant formulations with clean removability characteristics.
- Sealing:Filter assembly and medical device packaging leverage rapid green strength without solvent emissions.
Bonding commands the bulk of specification authority; coating is gaining share fastest.
Technology:
Equipment integration costs separate mass-market adoption from specialty applications, with hot melt extrusion and spray application requiring distinct capital commitments.
- Hot Melt Extrusion:Continuous slot-die and roller coating systems dominate technical textile and furniture manufacturing. Baden-Württemberg component manufacturers retrofit production lines with precision applicators that eliminate clamping stations.
- Spray Application:Robotic spray systems penetrate automotive interior assembly where complex geometries defy contact bonding methods. Viscosity stability across temperature cycling prevents nozzle clogging in automated cells.
- Film Coating:Pre-cast adhesive films enable clean room assembly of medical devices and electronics where particulate contamination risks exclude molten application.
- Injection Molding:Overmolding and insert bonding applications in automotive structural components remain limited by polyester thermal performance ceilings.
Hot melt extrusion retains the bulk of installed equipment base; spray application is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for electronics manufacturing concentrates contract manufacturer demand in Karnataka and Tamil Nadu. Special economic zones in Shenzhen and Stuttgart anchor automotive and wearable electronics assembly. German automotive clusters drive REACH-compliant formulation requirements across European supply chains.
United States
Automotive interior assembly plants in Michigan and Tennessee eliminate mechanical fasteners from dashboard and trim modules. EPA NESHAP standards enforce volatile organic compound thresholds at adhesive production facilities. Detroit-area Tier 1 suppliers consolidate specification authority toward central commodity managers with pan-regional portfolios.
Germany
Carbon fiber reinforced plastic roof module attachment in Wolfsburg and Stuttgart demands hybrid copolyester formulations with crashworthy cohesive failure modes. ECHA's REACH Annex XVII tightens disclosure requirements for isocyanate and phthalate content. Baden-Württemberg component manufacturers retrofit production lines with precision hot melt applicators that eliminate clamping stations.
China
Wearable electronics manufacturers in Shenzhen specify fatigue-resistant elastic grades for flexible circuit lamination exceeding 10,000 bend cycles. MIIT enforces GB standards for industrial chemical emissions that parallel REACH-equivalent compliance documentation. Yangtze River Delta contract assemblers attract localized adhesive supply chains serving mobile device export markets.
India
Mobile device assembly under the PLI scheme concentrates demand in Karnataka and Tamil Nadu manufacturing corridors. BIS certification requirements filter non-compliant imported formulations from domestic market access. Chennai and Bengaluru electronics parks require localized technical service capabilities as a supplier selection criterion above unit pricing.
Japan
Precision electronics and automotive component bonding in Nagoya and Osaka demands viscosity stability across automated dispensing systems. METI oversees JIS standards for industrial adhesive performance and environmental compliance. Chubu region manufacturers integrate quality control protocols monitoring viscosity drift during heated hose delivery.
Polyester Hot Melt Adhesives Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with formulation houses dominating specification-driven automotive and electronics applications while regional compounders serve packaging and furniture markets. The vendor base organizes into three tiers: multinational chemical conglomerates with backward integration into diacid production, mid-cap European and Japanese specialists with polycondensation expertise, and emerging Asian compounders competing on throughput scale. Consolidation pressure intensifies as automotive OEMs reduce approved supplier lists from dozens to single-digit frameworks. Capacity expansion in bio-based diol fermentation and reactive hot melt technology licensing represent the dominant competitive vectors.
Among European-based formulation specialists, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify contrasting strategic positions within the adhesive hierarchy. Henkel occupies a position anchored in automotive OEM relationships that sustain formulation leadership across compliance-heavy European and Asian markets. H.B. Fuller sits within the high-performance tier, representing specialists competing in under-the-hood and elevated-temperature applications where thermal cycling demands exceed conventional adhesive limits. Both companies illustrate how technical service capabilities and multi-regulatory certification portfolios now outweigh unit pricing in procurement decisions by centralized automotive commodity managers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M Company |
| Arkema (Bostik) |
| Dow Inc. |
| Evonik Industries AG |
| Jowat SE |
| Avery Dennison Corporation |
| Sika AG |
| Others |
Cost & Logistics Intelligence
Purified terephthalic acid spot benchmarks cascading through polyester hot melt adhesive supply chains stratify pricing across three tiers: premium formulations for REACH-compliant automotive contracts, standard grades for packaging consolidation, and economy options for furniture edgebanding. German automotive OEMs absorb margin premiums for certified low-VOC grades while Asian packaging converters negotiate volume discounts on commodity rigid formulations.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over contract pricing as automotive Tier 1 suppliers in Stuttgart and Wolfsburg expedite qualification batches for new carbon fiber reinforced plastic modules. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and thermal performance tier, with FDA 21 CFR 175.105 compliance adding specification stickiness. Cost compression in economy rigid grades intensifies because Chinese compounders expand capacity for furniture export markets. Packaging converters in Yangtze River Delta manufacturing zones exhibit highest price sensitivity, while German medical device textile laminators accept premium positioning for gamma sterilization compatibility.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen Group and BMW central commodity managers, bypassing distribution layers for formulation customization and technical service bundling. Manufacturing concentrates in Germany, China, and Japan, with Baden-Württemberg and Stuttgart anchoring European supply for REACH-compliant grades. Feedstock chains draw from purified terephthalic acid, adipic acid, and specialty diol streams tethered to Rhine-Ruhr petrochemical infrastructure. Single-source vulnerability in butanediol and hexanediol supply from limited European producers creates geographic concentration risk. Distribution runs through authorized technical distributors for mid-tier packaging and furniture accounts requiring localized application support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty diol fermentation capacity constraints prop pricing power for backward-integrated formulation houses, limiting supply elasticity across the projection horizon. This supply-constrained structure favors incumbents with captive feedstock positions and multi-regulatory certification portfolios.
For Market Incumbents: Deploy reactive hot melt technology licensing to capture specification wins in automotive composite bonding where crashworthiness requirements displace conventional polyurethane alternatives. Add fermentation-derived 1,3-propanediol capacity in European biorefinery corridors to secure bio-based grade feedstock independence. Emerging Asian compounders with price-competitive rigid formulations threaten margin position in furniture edgebanding; defend through technical service bundling and heated hose delivery system integration for automated dispensing lines. For New Entrants and Emerging Players: Indian electronics contract manufacturers under the PLI scheme represent the most penetrable buyer archetype, requiring localized REACH-equivalent compliance documentation that filters established European suppliers. Target medical device textile lamination in Chennai and Bengaluru manufacturing parks where FDA 21 CFR 175.105 certification creates specification stickiness against commodity competitors. Pursue joint venture structures with German technical textile manufacturers seeking biodegradation dossier completion ahead of ECHA microplastic enforcement windows. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European specialists with polycondensation expertise and aging technical workforces in Nagoya and Osaka industrial clusters. Long-term viability hinges on reactive technology adoption curves and bio-based feedstock cost parity achievement. Monitor ECHA restriction proposal advancement on synthetic polymer textile coatings as inflection indicator for hydrolytically stable formulation R&D returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Diol Production | Fermentation-derived 1,3-propanediol capacity secures carbon footprint differentiation for sustainability-mandated automotive procurement. |
| Reactive Hot Melt Technology Licensing | Hybrid copolyester formulations with latent curing agents penetrate structural load-bearing applications previously reserved for two-part epoxies. |
| Multi-Regulatory Certification Investment | Simultaneous EPA NESHAP, REACH SVHC, and FDA compliance compresses customer qualification timelines for centralized commodity managers. |
| Precision Applicator Equipment Integration | Heated hose delivery system partnerships with Baden-Württemberg component manufacturers eliminate clamping stations and reduce work-in-process inventory. |
| India PLI Scheme Localization | Chennai and Bengaluru technical service capabilities satisfy contract manufacturer supplier selection criteria above unit pricing. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving adhesive formulation chemists, automotive Tier 1 procurement directors, technical textile plant managers, and medical device quality assurance leads. Cefic sector reports, ECHA restriction dossiers, EPA NESHAP compliance databases, and SEC 10-K disclosures from listed chemical conglomerates provided demand-side validation. Bottom-up production capacity estimates triangulated against top-down end-use consumption models across automotive interior assembly, electronics lamination, and packaging conversion segments.
Granularity-level modeling deployed viscosity grade, end-use durability requirement, and application equipment constraint as primary segmentation dimensions, with regional regulatory cluster and certification tier as cross-cutting variables. CAGRs derived from regression analysis of historical production data and forward projection of automotive fastener elimination rates, electronics PLI scheme capacity buildout, and REACH phase-out enforcement timelines. Automotive OEM specification consolidation trends and wearable electronics bend cycle reliability requirements served as industry-specific demand drivers.
Revisions become necessary when ECHA microplastic restriction enforcement accelerates, bio-based diol cost parity achievement diverges from baseline assumptions, or automotive thermal specification ceilings shift toward powertrain applications. Forecasts reflect documented assumptions regarding petrochemical feedstock price correlation, regulatory harmonization pace, and equipment automation adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Silane Coupling Agents Market