
 Global Graphite Coatings Market | 2026-2036
Global Graphite Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graphite Coatings Market Foresight
ISO 12944 corrosion-protection certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Imerys Graphite & Carbon leverages captive graphite mining assets to sustain raw material cost advantages across European supply chains. Asbury Carbons anchors North American distribution through integrated carbon processing infrastructure and longstanding foundry relationships.
Graphite coatings comprise suspensions of crystalline or synthetic graphite particles in aqueous or solvent-based binders, engineered to deliver lubricity, thermal stability, and electrical conductivity at operating temperatures exceeding 400°C. Their primary industrial purpose centers on reducing wear in metal-forming dies, protecting substrates from oxidative corrosion, and managing heat flux in battery thermal management systems. Dispersion formulations command premium positioning in electronics fabricator supply chains where uniform film thickness governs performance, while spray coating technologies dominate metal fabrication shops seeking rapid throughput over precision. Chemical vapor deposition occupies a specialized niche serving aerospace manufacturers requiring conformal graphite layers on complex geometries.
EPA NESHAP standards and REACH Annex XVII restrictions on chromium trioxide are forcing reformulation of legacy anti-corrosion systems toward graphite-based alternatives. ECHA substance evaluation protocols extend compliance timelines but raise registration costs for European market entrants. Stakeholders must monitor evolving battery safety standards from China's SAMR and India's BIS, as thermal runaway testing protocols will determine qualification requirements for graphite coatings in next-generation energy storage architectures.
Market Dynamics
Automotive electrification is restructuring procurement priorities across the graphite coatings value chain, with OEM specifications for thermal interface materials in battery packs now overriding traditional die-lubricant demand from metal-forming operations.
Growth Catalysts
- EPA NESHAP VOC thresholds:US metal fabricators are accelerating graphite coating adoption as chromium trioxide systems face phase-out under tightened air quality standards.
- Electric vehicle battery thermal management:Cell manufacturers specify graphite-based phase-change materials to control heat flux during fast-charging cycles.
- China:Domestic steel processors and battery producers account for concentrated demand pull, with SAMR safety protocols mandating flame-retardant coating specifications in energy storage systems.
Market Restraints
- Flake graphite supply concentration:Spherical graphite precursor availability hinges on Chinese mining and processing capacity, creating single-source vulnerability for anode coating supply chains.
- ECHA registration timelines:REACH substance evaluation protocols extend market entry barriers for novel aqueous dispersion formulations.
- Silicon anode substitution:Next-generation lithium-ion designs incorporating silicon-carbon composites threaten to compress graphite coating volume in premium battery segments.
Strategic Opportunities
- India BIS thermal runaway standards:Emerging battery safety mandates create qualification windows for graphite fire-barrier coatings in domestic energy storage manufacturing.
- Direct-to-fabricator digital channels:Specialty coating producers are bypassing traditional distributor networks to serve precision metal-forming shops with customized dispersion formulations.
- Aerospace chemical vapor deposition:Conformal graphite layer requirements for turbine blade thermal protection represent uncaptured value in aviation MRO services.
Industry Challenges
- ISO 12944 certification timelines:Corrosion-protection qualification protocols demand 12-18 month validation cycles that delay new supplier entry.
- Formulation chemist scarcity:Expertise in high-temperature binder chemistry for aqueous graphite suspensions concentrates among retiring specialists at established European coating houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graphite Coatings Market |
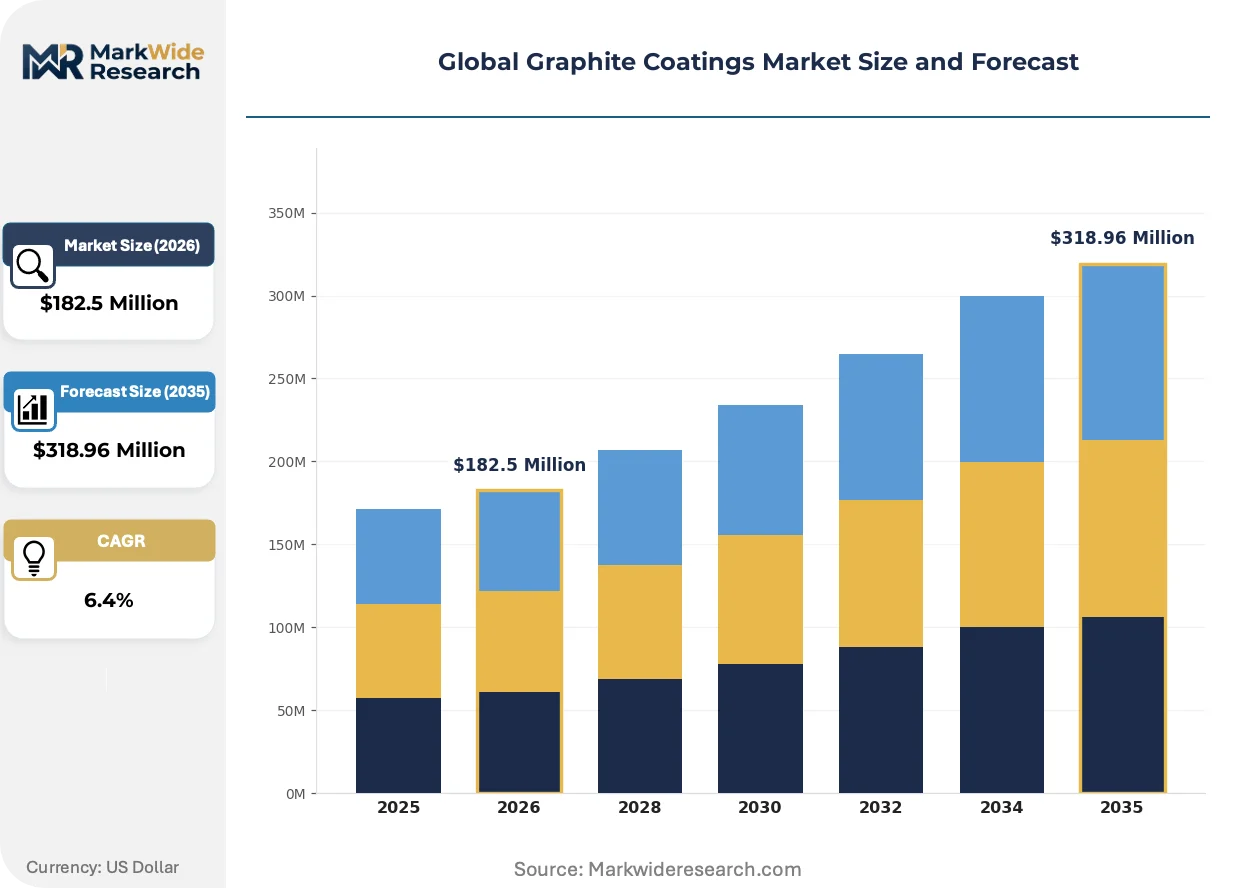
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $318.96 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Dispersion, Paste, Film Coating, Spray Coating Technology: Electrostatic Spray, Air Spray, Dip Coating, Roll Coating, Chemical Vapor Deposition Application: Friction Reduction, Corrosion Protection, Lubrication, Heat Shielding, Electrical Conductivity End Use Industry: Automotive OEMs, Aerospace Manufacturers, Electronics Fabricators, Metal Fabrication Shops, Energy Equipment Producers |
| Companies Covered | Final Advanced Materials, BECHEM, Asbury Carbons, Imerys Graphite & Carbon, Van Sickle Paint Mfg. Company, Mersen, Elcora Advanced Materials Corp., Whitford, CONDAT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graphite Coatings Market Shifts & Advancements
Formulation science and application equipment are converging to expand graphite coating performance envelopes, with aqueous systems gaining ground against solvent-based alternatives across multiple industrial end-uses.
Water-based graphite dispersions with engineered particle size distributions are displacing solvent-borne formulations in automotive underbody corrosion protection. Tier-1 suppliers to German and Japanese OEMs have completed qualification of these systems for salt-spray resistance specifications. The shift is compressing VOC compliance costs while opening coating operations to regions with stringent air quality enforcement.
REACH Annex XVII restrictions on hexavalent chromium compounds are forcing reformulation of legacy anti-corrosion primers across European metal fabrication. ECHA substance evaluation protocols have extended transition timelines but raised registration burdens for alternative coating developers. Marine and offshore infrastructure contractors face the most acute compliance pressure given salt-exposure performance requirements.
Integrated coating-service contracts are consolidating procurement for precision metal-forming operations in Germany and the United States. Die shops now source graphite lubricants bundled with application equipment maintenance and film thickness monitoring rather than purchasing materials alone. This bundling is most advanced among automotive stamping operations serving electric vehicle platform launches.
Global Graphite Coatings Market Segmentation
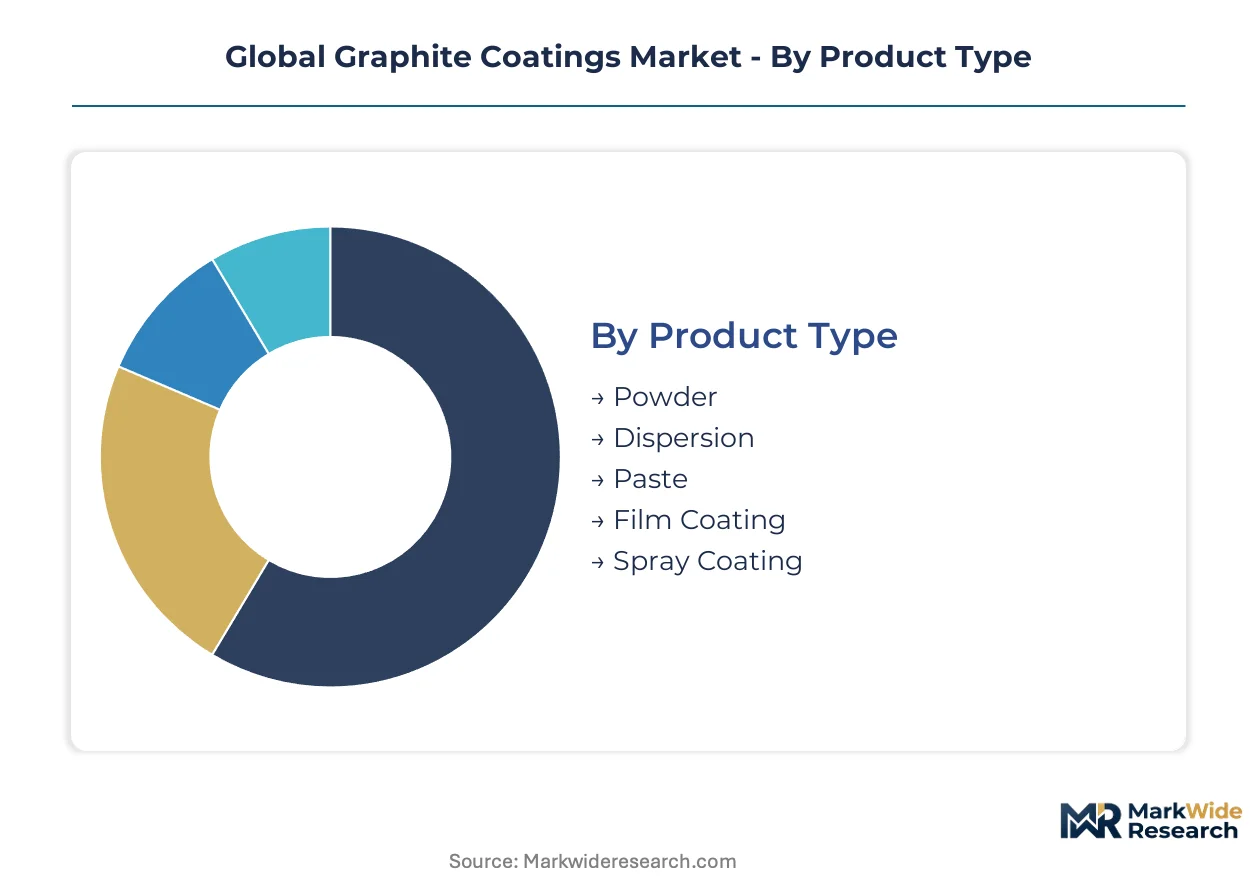
Graphite coatings traverse divergent commercial channels depending on formulation physics and application precision requirements. Powder and paste formulations flow through industrial distributors serving metal fabrication clusters, while dispersion and film coatings reach electronics fabricators through direct technical sales relationships.
Product Type:
Dispersion formulations command premium positioning through specialty chemical distributors and direct channels to precision manufacturers, whereas powder and spray coatings move through bulk industrial supply networks serving high-volume metal processors.
- Dispersion:Engineered aqueous or solvent-based suspensions with controlled particle size distributions enable uniform film thickness critical for electronics thermal interface materials. Electronics fabricators in South Korea and Taiwan specify these formulations for battery pack thermal management, with qualification protocols from BIS and SAMR driving formulation standardization.
- Spray Coating:Ready-to-apply aerosol or pump-dispensed systems prioritize throughput over precision in automotive underbody and metal-forming applications. German and Japanese OEMs have completed salt-spray qualification of water-based variants, compressing VOC compliance costs for Tier-1 suppliers.
- Powder:Dry graphite concentrates blended on-site with carrier fluids serve foundries and forges seeking cost-flexible lubrication.
- Paste:High-viscosity compounds target die-casting and extrusion operations requiring localized, thick-film deposition.
- Film Coating:Pre-cured graphite layers laminated onto substrates serve aerospace thermal protection systems with exacting thickness tolerances.
By volume, Powder leads. By growth pace, Dispersion is ahead.
Technology:
Application method selection hinges on substrate geometry complexity and throughput economics, with cost tier differentiation separating precision deposition systems from commodity coating operations.
- Electrostatic Spray:Charged particle deposition delivers exceptional transfer efficiency and film uniformity for automotive and electronics applications. Japanese automotive OEMs specify electrostatic systems for battery enclosure coating, with METI energy-efficiency guidelines favoring reduced overspray technologies.
- Chemical Vapor Deposition:Conformal graphite layer formation on complex turbine blade geometries commands aerospace MRO premiums. FAA airworthiness directives for thermal barrier maintenance are expanding qualification requirements for CVD service providers.
- Air Spray:Conventional compressed-air atomization dominates metal fabrication shops prioritizing equipment accessibility over film precision.
- Dip Coating:Immersion application serves high-volume fastener and small-component corrosion protection with minimal labor intensity.
- Roll Coating:Continuous web processing enables electrode and heat-spreader manufacturing for energy storage systems at scale.
By installed base, Air Spray leads. By technology upgrade rates, Chemical Vapor Deposition is climbing the fastest.
Application:
Customer type concentration varies sharply by functional requirement, with automotive procurement offices driving friction-reduction volumes and electronics quality departments governing electrical conductivity specifications.
- Friction Reduction:Solid-film lubricants reduce wear in metal-forming dies and electric drivetrain components operating above 400°C. Chinese steel processors and battery manufacturers account for concentrated demand pull, with SAMR flame-retardant mandates expanding coating specifications.
- Thermal Management:Phase-change and heat-spreading formulations control heat flux during EV fast-charging cycles. EPA NESHAP thresholds are accelerating graphite adoption as chromium trioxide alternatives face phase-out.
- Corrosion Protection:Barrier coatings protect marine and offshore infrastructure from salt-exposure degradation.
- Lubrication:General-purpose die-release and forming lubricants serve metal-stamping operations across automotive supply chains.
- Electrical Conductivity:Uniform conductive layers enable current collection in battery electrodes and electronic interconnects.
By revenue concentration, Friction Reduction leads. By specification intensity, Thermal Management is gaining share fastest.
End Use Industry:
Geography and maturity shape procurement patterns, with established automotive clusters in Germany and Japan contrasting against emerging battery manufacturing corridors in India and Southeast Asia.
- Automotive OEMs:Electric drivetrain thermal interface specifications now override traditional die-lubricant demand, with integrated coating-service contracts bundling materials, equipment maintenance, and film monitoring. German stamping operations serving EV platform launches have advanced this procurement model furthest.
- Electronics Fabricators:Semiconductor and battery cell manufacturers specify dispersion-grade coatings for thermal management and electrical performance. Taiwan and South Korea fabrication clusters drive qualification protocols for next-generation energy storage architectures.
- Aerospace Manufacturers:Turbine blade thermal protection and airframe corrosion prevention require conformal CVD layers and film coatings meeting FAA and EASA certification.
- Metal Fabrication Shops:Job shops and production forges prioritize cost-efficient powder and paste lubrication for general metal-forming.
- Energy Equipment Producers:Power generation and grid infrastructure manufacturers specify corrosion-resistant coatings for high-temperature operational environments.
By procurement volume, Automotive OEMs lead. By specification evolution pace, Electronics Fabricators show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA NESHAP VOC thresholds and REACH Annex XVII chromium restrictions are accelerating graphite coating procurement across automotive and industrial clusters. Battery safety mandates from China's SAMR and India's BIS are reshaping thermal management specifications in energy storage manufacturing corridors.
China
Domestic battery manufacturers and steel processors concentrate graphite coating consumption in Jiangsu and Shandong provinces. SAMR flame-retardant specifications for energy storage systems mandate qualified thermal barrier formulations. The Yangtze River Delta battery fabrication cluster drives dispersion-grade coating qualification at scale.
United States
Metal fabricators in Michigan and Ohio accelerate graphite adoption as chromium trioxide systems face EPA NESHAP phase-out. Tier-1 automotive stamping operations bundle coating services with equipment maintenance contracts. The Southeast EV battery corridor emerging in Georgia and Tennessee specifies thermal interface materials for fast-charging architectures.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg have completed salt-spray qualification of water-based graphite underbody coatings. ECHA registration timelines extend market entry for novel aqueous dispersions. The Ruhr industrial belt integrates coating-service contracts for precision metal-forming operations serving electric platform launches.
India
BIS thermal runaway standards create qualification windows for graphite fire-barrier coatings in domestic battery manufacturing. Maharashtra and Gujarat fabrication clusters seek REACH-compliant alternatives for export-oriented automotive components. The Tamil Nadu electronics corridor drives dispersion-grade specification for semiconductor thermal management.
Japan
METI energy-efficiency guidelines favor electrostatic spray systems with reduced overspray for battery enclosure coating. Kansai and Chubu automotive clusters specify graphite-based phase-change materials for thermal flux control. Nagoya-area die shops source bundled lubricant and application equipment maintenance contracts.
Global Graphite Coatings Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and captive raw material access. The vendor base stratifies into three tiers: integrated mining-to-coating houses, independent dispersion compounders, and regional application-service providers. Two dominant competitive moves are reshaping positioning: backward integration into flake graphite mining to secure spherical precursor supply, and forward integration into coating-application services to capture die-shop maintenance contracts.
Within the mining-integrated tier, Imerys Graphite & Carbon and Asbury Carbons exemplify divergent geographic anchoring strategies. Among European specialty compounders, Final Advanced Materials and BECHEM occupy positions emphasizing REACH-compliant aqueous formulations. Mersen represents the diversified industrial materials archetype spanning carbon products across multiple high-temperature applications.
| Leading Market Players |
|---|
| Final Advanced Materials |
| BECHEM |
| Asbury Carbons |
| Imerys Graphite & Carbon |
| Van Sickle Paint Mfg. Company |
| Mersen |
| Elcora Advanced Materials Corp. |
| Whitford |
| CONDAT Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between spherical graphite processors and battery manufacturers lock in both raw material access and price visibility across multi-year procurement cycles. These arrangements concentrate pricing power with mining-integrated suppliers while insulating downstream coating compounders from flake graphite spot volatility.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified suppliers in this market. Three-tier pricing structure across ISO 12944-certified premium, REACH-compliant standard, and uncertified economy levels governs procurement negotiations. Pricing pressure stems from silicon anode substitution threats compressing graphite coating volumes in premium battery segments. Metal fabrication shops exhibit highest price sensitivity due to commoditized die-lubricant demand, whereas electronics fabricators prioritize film uniformity over unit cost.
Supply Chain Analysis
China and Mozambique anchor global flake graphite extraction, with spherical graphite processing clustering in Shandong and Heilongjiang provinces. Coating formulations draw from synthetic graphite precursors, aqueous binder chemistries, and solvent carrier systems. Single-source vulnerability concentrates in Chinese spherical graphite capacity, creating chokepoint exposure for anode coating supply chains. Distribution runs through specialty chemical distributors serving precision manufacturers and bulk industrial networks supplying high-volume metal processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The graphite coatings market functions as a defensive-moat arena where regulatory entrenchment through ISO 12944 certification creates durable barriers against unqualified competitors. Switching costs for qualified coating formulations in automotive and aerospace procurement channels reinforce incumbent positioning.
For Market Incumbents: Fortify captive spherical graphite supply through backward integration into African mining assets or long-term offtake partnerships. Accelerate REACH-compliant aqueous dispersion R&D to preempt ECHA registration timeline extensions that threaten formulation portfolios. For New Entrants and Emerging Players: Anchor in India's BIS thermal runaway qualification windows for fire-barrier coatings serving domestic battery manufacturing corridors. Target precision metal-forming shops in Germany's Ruhr belt with bundled coating-service contracts that bypass established distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mining-integrated coating houses with captive flake graphite assets and established automotive OEM qualifications. Monitor silicon-carbon composite anode penetration rates in South Korean battery cell manufacturing as the critical inflection signal for graphite coating demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Imerys and Asbury anchor European and North American supply security through captive flake graphite extraction. |
| REACH-Compliant Aqueous Formulation Development | ECHA substance evaluation protocols extend registration timelines for solvent-based alternatives. |
| Integrated Coating-Service Contracts | German automotive stamping operations bundle materials with equipment maintenance and film monitoring. |
| India BIS Thermal Runaway Qualification | Domestic battery safety mandates create entry windows for fire-barrier coating specialists. |
| Chemical Vapor Deposition Capacity Expansion | FAA airworthiness directives expand turbine blade thermal protection requirements for aerospace MRO providers. |
Research Methodology
The analysis maps dispersion-grade, spray, powder, paste, and film coating sub-sectors, each validated through procurement directors at battery manufacturers, coating application engineers, and specialty chemical distributors. Primary interviews with plant managers at metal fabrication shops, R&D directors at European coating houses, and automotive Tier-1 supplier quality engineers combined with secondary validation from customs trade data, ECHA registration databases, SEC 10-K filings, and SAMR technical standards. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include product formulation physics, application technology precision requirements, functional end-use specifications, and geographic regulatory clusters. CAGRs derived from elasticity-adjusted demand curves incorporating EV battery thermal management content per vehicle, metal-forming die lubricant replacement cycles, and aerospace MRO service intervals.
Decision-makers should treat outputs as directional under sustained automotive electrification and REACH compliance enforcement assumptions; material deviation in silicon anode substitution rates or Chinese export restrictions would warrant model refresh. Recalibration cycles align with material shifts in battery chemistry roadmaps and evolving EPA NESHAP threshold implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Coating Thickness Gauge Market
Coatings
Tablet Coatings Market
Coatings
Batters and Coatings Market
Coatings
Brazil Automotive OEM Coatings Market
Coatings
Coating Equipment Market
Coatings
Europe Powder Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Solar Reflective Film Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Global Sputter Coater Market
Coatings
Polysiloxane Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
Asia-Pacific Coil Coatings Market