
 E-Coat Market | 2026-2036
E-Coat Market Size, Share, and Industry Trends Forecast 2026-2036
E-Coat Market Intelligence
ISO 12944 corrosion-protection certification is unwinding the competitive landscape for coating suppliers serving heavy-duty applications. PPG Industries leverages captive resin technology to sustain formulation consistency across automotive OEM contracts. Axalta Coating Systems anchors its position through deep relationships with North American vehicle assembly plants. BASF SE differentiates via specialty epoxy chemistry for aerospace-grade e-coat specifications.
Electrocoating deposits organic polymer films onto conductive substrates through controlled electrochemical deposition in aqueous baths, typically achieving film builds of 15–35 micrometers with throw-power penetration into recessed geometries. The process serves primarily as a corrosion barrier and primer foundation for subsequent paint layers in metal-intensive manufacturing. Cathodic e-coat dominates automotive body-in-white lines due to superior edge coverage and chemical resistance versus anodic alternatives. Dip coating technology retains cost advantages for high-volume appliance housings where complex geometry immersion is routine. Hybrid formulations are gaining traction in furniture applications seeking combined aesthetic and environmental compliance properties.
EPA emissions guidelines and OSHA workplace exposure limits constrain solvent-based pretreatment chemistries in US manufacturing facilities. REACH registration requirements in Europe mandate full substance disclosure for epoxy resin crosslinkers used in cathodic systems. China's MEE enforces wastewater discharge standards that favor closed-loop e-coat bath recovery systems. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds historically enabled critical surface-preparation performance in pretreatment stages.
Market Dynamics
Cathodic e-coat lines at automotive OEMs in Mexico, Germany, and the United States are expanding capacity to meet extended corrosion warranties, while REACH and GB standards on volatile organic compounds force reformulation of epoxy resin chemistries across supplier networks.
Growth Catalysts
- Automotive OEM Warranty Extensions:Vehicle manufacturers in Detroit, Stuttgart, and Puebla are mandating 12-year corrosion protection, requiring thicker e-coat film builds and upgraded dip-coating infrastructure.
- REACH Registration Requirements:ECHA mandates on epoxy crosslinker disclosure are accelerating substitution toward waterborne low-VOC formulations in European coating operations.
- Closed-Loop Bath Recovery:China's MEE wastewater standards are compelling installation of ultrafiltration systems that reduce raw material consumption and environmental discharge.
Market Restraints
- Epoxy Resin Price Volatility:Bisphenol A and amine hardener feedstock costs fluctuate with crude oil derivatives, compressing margins for formulation suppliers serving appliance and furniture segments.
- Concentrated Anode Supply:Specialty stainless steel anode manufacturing concentrates in German and Japanese metalworking clusters, creating vulnerability for North American e-coat line operators.
- Anodic System Obsolescence:Legacy anodic e-coat chemistries face technical displacement as cathodic alternatives deliver superior edge coverage and chemical resistance in automotive body-in-white applications.
Strategic Opportunities
- Aerospace-Grade Specifications:Specialty epoxy formulations meeting AS9100 quality standards open penetration into commercial aviation MRO facilities seeking corrosion protection for aluminum airframe components.
- India Automotive Corridor:Tamil Nadu and Gujarat vehicle assembly plants lack captive e-coat capacity, creating white space for tier-one suppliers to establish regional dip-coating operations.
- EU Green Deal Incentives:Carbon border adjustment mechanisms and green public procurement rules favor low-emission coating processes in European heavy machinery and agricultural equipment manufacturing.
Industry Challenges
- ISO 12944 Certification Timelines:Heavy-duty coating suppliers face 18-24 month validation periods for corrosion-protection certification, delaying contract awards in offshore wind and infrastructure projects.
- Legacy Pretreatment Integration:Phosphate conversion coating lines require capital-intensive retrofit to accommodate zirconium-based nano-ceramic pretreatment chemistries compatible with next-generation e-coat formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Coat Market |
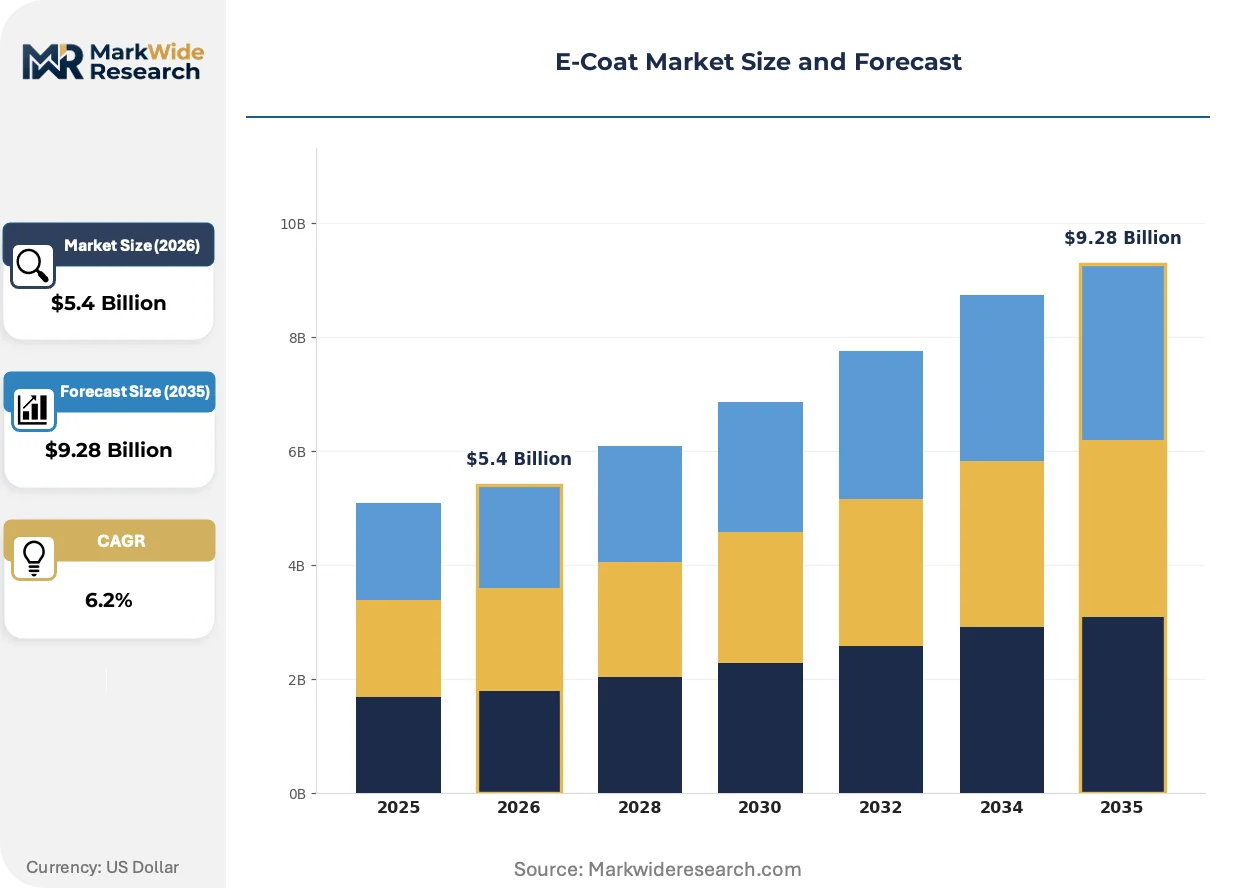
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anodic, Cathodic, Hybrid, Others End User: Automotive, Appliances, Aerospace, Furniture Application: Corrosion Protection, Aesthetic Finishing, Electrical Insulation, Environmental Coating Technology: Electrostatic Spray, Dip Coating, Flow Coating, Others |
| Companies Covered | The Sherwin-Williams Company, Henkel AG & Co. KGaA, Axalta Coating Systems, KCC Corporation, Tatung Fine Chemicals, PPG Industries, Nippon Paint Holdings, Valspar Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Coat Market Strategic Shifts & Innovations
Electrocoating technology is undergoing material substitution and process intensification as environmental compliance tightens and end-use specifications diverge across automotive, aerospace, and industrial verticals.
UV-curable e-coat formulations are displacing conventional thermal-cure systems in furniture and fixture manufacturing. Italian and Polish wood-metal hybrid producers are piloting these chemistries to eliminate natural gas ovens and reduce floor space requirements. The technology is displacing capital-intensive convection baking infrastructure in mid-volume decorative coating operations.
REACH authorization procedures for chromium trioxide in pretreatment stages are forcing conversion to trivalent chrome and zirconium-based alternatives. European coil coating and appliance manufacturers must reformulate surface preparation lines by 2026 authorization deadlines. German white goods producers are accelerating qualification of silane-based nano-ceramic pretreatments to maintain supply chain continuity.
Automotive tier-one suppliers are consolidating coating procurement under platform-level contracts rather than individual component sourcing. Magna, Bosch, and Continental are negotiating multi-year e-coat service agreements with PPG and Axalta for entire vehicle programs. This concentration is most visible in Mexico's Bajío automotive corridor, where assembly plants are outsourcing body-in-white coating to dedicated supplier parks.
E-Coat Market Segmentation
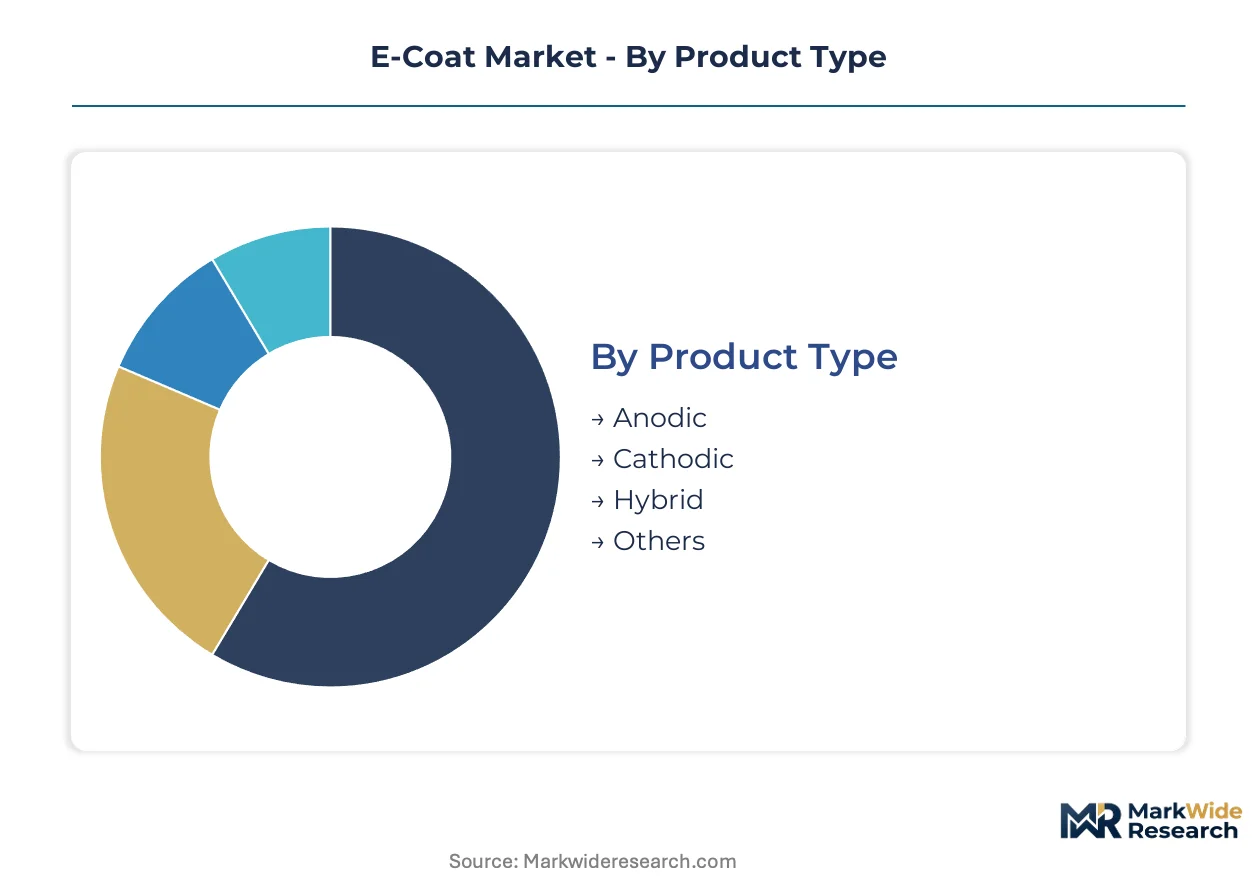
E-coat segmentation reveals divergent technology maturities across end-use verticals, with automotive OEM specifications driving cathodic system investment while appliance manufacturers retain cost-optimized dip-coating infrastructure. Understanding these divides clarifies where formulation suppliers can capture premium pricing versus commodity volume.
Product Type:
Cathodic systems dominate export-intensive automotive supply chains serving German and Japanese OEMs, while anodic chemistries persist in domestic appliance manufacturing where capital replacement cycles lag.
- Anodic:Legacy epoxy-amine formulations deposit polymer films at the anode, delivering adequate corrosion barriers for non-structural metal components. Demand concentrates in domestic North American appliance manufacturing, where Birmingham and Louisville metal stamping plants retain installed convection oven infrastructure and resist capital upgrades.
- Cathodic:Automotive-grade systems electrodeposit cationic epoxy resins onto negatively charged substrates, achieving 25–35 micrometer film builds with superior edge coverage. Export-led demand from Puebla, Stuttgart, and Detroit assembly plants is accelerating as OEMs mandate 12-year corrosion warranties requiring upgraded dip-coat infrastructure.
- Hybrid:Dual-cure formulations combine cathodic deposition with UV or thermal secondary curing, targeting furniture and fixture applications seeking combined environmental compliance and aesthetic performance.
- Others:Emerging waterborne acrylic and polyurethane e-coat chemistries serve niche electronics and medical device applications requiring low-temperature processing.
Cathodic systems command the established base. The steepest expansion runs through hybrid formulations.
End User:
Cost tier stratification separates capital-intensive automotive specifications from price-sensitive appliance procurement, with aerospace and furniture occupying intermediate positions on performance-versus-volume curves.
- Automotive:Body-in-white coating lines demand ISO 12944-certified cathodic systems with 15–25 year corrosion protection. Tier-one suppliers in Mexico's Bajío corridor are installing captive capacity to serve Volkswagen, BMW, and General Motors assembly plants requiring just-in-time primer delivery.
- Appliances:Refrigerator and washing machine housings utilize anodic e-coat for basic rust prevention prior to powder topcoat. High-volume production in Chinese and Turkish white goods manufacturing favors dip-coating technology with minimal film build requirements.
- Aerospace:AS9100-qualified epoxy formulations protect aluminum airframe components in commercial aviation MRO facilities. Specification stringency limits qualified suppliers, creating margin premiums for approved coating vendors.
- Furniture:Metal office and outdoor furniture combines corrosion protection with decorative finish compatibility. Italian and Polish manufacturers are piloting UV-curable e-coat to eliminate natural gas ovens and reduce floor space.
Automotive applications command the established base. The steepest expansion runs through aerospace specifications.
Application:
Volume concentration aligns with infrastructure-heavy corrosion protection, while emerging electrical insulation and environmental coating applications serve specialized industrial verticals with distinct specification regimes.
- Corrosion Protection:Primary function across automotive, construction, and marine metal substrates. Heavy-duty infrastructure projects in offshore wind and bridge construction drive ISO 12944 certification requirements with 18–24 month validation timelines.
- Aesthetic Finishing:Decorative primer layers enabling uniform topcoat appearance on visible consumer products. Furniture and appliance manufacturers prioritize color consistency and surface smoothness over extreme durability.
- Electrical Insulation:Dielectric e-coat formulations isolate conductive components in electric motor housings and transformer cores. Demand from EV powertrain manufacturing is climbing fastest as motor winding protection requirements tighten.
- Environmental Coating:Low-VOC and heavy-metal-free formulations meeting REACH, EPA, and China's GB emission standards. Regulatory compliance is the purchase driver rather than performance optimization.
Corrosion protection commands the established base. The steepest expansion runs through electrical insulation.
Technology:
Customer type segmentation separates automated high-throughput automotive lines from batch-oriented job shops, with technology choice dictated by production scale and geometry complexity.
- Electrostatic Spray:Robotic application of charged paint particles suits complex geometries with recessed cavities inaccessible to dip tanks. Automotive tier-one suppliers deploy this technology for component-level coating when full body-in-white immersion is impractical.
- Dip Coating:Immersion-based deposition remains the cost minimum for high-volume uniform coverage. Appliance manufacturers in China and Mexico favor this approach for rectangular housings with routine geometry.
- Flow Coating:Controlled flooding of workpieces suits oversized components exceeding standard tank dimensions. Agricultural and construction equipment manufacturers utilize this method for frames and structural members.
- Others:Emerging spray-dip hybrid and electrophoretic curtain systems target specialized coil coating and continuous strip processing applications.
Dip coating commands the established base. The steepest expansion runs through electrostatic spray.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement offices concentrate demand in manufacturing corridors where cathodic e-coat capacity serves extended corrosion warranties. Tier-one suppliers cluster near assembly plants to deliver just-in-time primer coating.
United States
Detroit-area vehicle manufacturers mandate 12-year corrosion protection on body-in-white assemblies. EPA emissions guidelines constrain solvent-based pretreatment chemistries in Michigan and Ohio coating facilities. PPG Industries anchors supply relationships with General Motors and Ford assembly operations across the Midwest.
Germany
Stuttgart-based OEMs export corrosion-protection specifications to global supply chains. REACH registration requirements from ECHA mandate full substance disclosure for epoxy resin crosslinkers in cathodic systems. BASF SE leverages specialty epoxy chemistry to serve aerospace-grade specifications from Ludwigshafen production.
China
GB standards on volatile organic compound emissions tighten formulation requirements for appliance and automotive coating operations. MEE wastewater discharge standards favor closed-loop e-coat bath recovery systems in Shanghai and Guangdong manufacturing zones. White goods producers in Shandong retain cost-optimized dip-coating infrastructure for refrigerator housings.
Mexico
Volkswagen, BMW, and General Motors assembly plants in the Bajío corridor outsource body-in-white coating to dedicated supplier parks. Tier-one suppliers install new dip-coating capacity to serve regional vehicle assembly with just-in-time primer delivery. Axalta Coating Systems maintains deep relationships with North American vehicle assembly plants operating in Puebla and Querétaro.
Japan
Specialty stainless steel anode manufacturing concentrates in Japanese metalworking clusters serving domestic automotive coating lines. JIS standards govern surface preparation specifications for export-intensive vehicle production. Nippon Paint Holdings occupies a position within the Asian coating supplier tier serving OEM specifications across the region.
E-Coat Market Key Industry Players
Player mix skews toward integrated chemical conglomerates with captive resin technology and regional coating specialists serving automotive OEM specifications. The supplier base organizes around formulation consistency, regulatory compliance capabilities, and geographic proximity to assembly plants. Three archetypes dominate: multinational chemical conglomerates with backward integration into epoxy resin production, regional coating specialists with deep OEM relationships, and diversified paint manufacturers with automotive heritage. Competitive moves center on capacity expansion in Mexico's automotive corridor and portfolio diversification toward aerospace-grade specifications.
Within the multinational chemical conglomerate tier, PPG Industries, BASF SE, and Axalta Coating Systems exemplify divergent strategic positions. PPG Industries represents the captive resin technology archetype sustaining formulation consistency across automotive OEM contracts. BASF SE anchors the specialty chemistry vector through differentiated epoxy systems. Axalta Coating Systems sits within the automotive-focused supplier tier leveraging established assembly plant relationships. Henkel AG & Co. KGaA and KCC Corporation occupy positions in the industrial and regional specialist segments respectively.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Henkel AG & Co. KGaA |
| Axalta Coating Systems |
| KCC Corporation |
| Tatung Fine Chemicals |
| PPG Industries |
| Nippon Paint Holdings |
| Valspar Corporation |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Automotive-scale dip-coating installations in Puebla and Stuttgart generate 40% lower unit costs than mid-volume job shops, concentrating pricing power among cathodic e-coat suppliers serving OEM platform contracts while compressing margins for anodic formulation vendors locked into appliance procurement cycles. This scale asymmetry creates divergent price floors: tier-one automotive suppliers capture index-linked raw material pass-throughs, while furniture and appliance buyers face volatile spot exposure to bisphenol A and amine hardener feedstocks.
Pricing Analysis
Cost-plus contracts with bisphenol A and epoxy resin indexation dominate automotive OEM procurement, insulating PPG Industries and Axalta Coating Systems from feedstock volatility while exposing smaller appliance-focused formulators to margin compression. Price differentiation separates ISO 12944-certified heavy-duty specifications from commodity anodic grades, with aerospace AS9100 qualifications commanding additional premiums. Cost compression in standard-grade cathodic systems is intensifying because Chinese white goods manufacturers are consolidating coating procurement under platform-level agreements. Appliance OEMs in Shandong and Istanbul exhibit the highest price sensitivity, whereas German automotive platform engineers prioritize formulation consistency over unit cost.
Supply Chain Analysis
Just-in-time bath chemistry delivery prevails at automotive OEMs in Detroit and Stuttgart, while appliance manufacturers in China and Turkey maintain strategic stockpiles of anodic resins to buffer against epoxy crosslinker lead time variability. Raw material supply concentrates in Germany, Japan, and the United States for specialty stainless steel anodes and high-purity epoxy resins. Formulation production draws from captive resin technology at PPG Industries and BASF SE, creating single-source vulnerability for tier-two suppliers without backward integration. Tariff exposure on Chinese epoxy resin imports threatens North American coating line operators. Distribution runs through regional blending facilities positioned within 200 kilometers of major automotive assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive platform procurement teams at Magna, Bosch, and Continental, fragmenting coating demand among fewer decision-makers with multi-year contract authority and technical specification control.
For Market Incumbents: Secure captive resin supply agreements with bisphenol A producers to defend margin position against epoxy feedstock volatility threatening commodity-grade suppliers. Deepen ISO 12944 certification investment for heavy-duty infrastructure specifications, as 18-24 month validation timelines create defensive moats against emerging Asian competitors. The priority lever is backward integration into specialty anode manufacturing, given concentrated Japanese and German supply creating vulnerability for North American operators. For New Entrants and Emerging Players: Lead with UV-curable e-coat formulations targeting Italian and Polish furniture manufacturers seeking to eliminate natural gas ovens and reduce floor space requirements. The most penetrable white space sits in India's Tamil Nadu and Gujarat automotive corridors, where vehicle assembly plants lack captive dip-coating capacity. Target aerospace MRO facilities with AS9100-qualified epoxy systems for aluminum airframe protection, leveraging specification stringency that limits qualified vendor pools. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive platform coating service providers with multi-year OEM contracts indexed to raw material costs. Long-term viability favors suppliers with REACH-compliant waterborne formulations and closed-loop bath recovery systems positioned for EU Green Deal procurement preferences. The acquisition target archetype is regional coating specialists with deep relationships in Mexico's Bajío automotive corridor. Watch for EPA emissions guideline tightening on solvent-based pretreatment chemistries as the inflection signal requiring capital-intensive retrofit investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | PPG Industries sustains formulation consistency across automotive OEM contracts through captive resin technology. |
| Capacity Expansion in Mexico's Bajío Corridor | Tier-one suppliers install dip-coating lines to serve Volkswagen and BMW assembly plants with just-in-time primer delivery. |
| Green Manufacturing Transition to UV-Curable Formulations | Italian furniture producers eliminate natural gas ovens while meeting REACH authorization deadlines for chromium trioxide alternatives. |
| Long-term Supply Agreement with Stainless Steel Anode Producers | North American coating line operators mitigate concentrated German and Japanese metalworking cluster dependency. |
| Joint Venture for Closed-Loop Bath Recovery Systems | China's MEE wastewater standards favor ultrafiltration installations reducing raw material consumption in Shanghai manufacturing zones. |
Research Approach
Desk research of customs trade databases, SEC 10-K filings from coating suppliers, and automotive production registries preceded structured interviews with OEM platform engineers, tier-one supplier procurement leads, and plant managers at cathodic e-coat line installations. Primary fieldwork encompassed technical directors at PPG Industries, Axalta Coating Systems, and BASF SE, supplemented by distribution channel partners serving Mexico's automotive corridor. Secondary validation drew from EPA emissions guidelines, ECHA REACH registration databases, and China's GB standards on volatile organic compound emissions. Bottom-up volume modeling triangulated against top-down value estimates from chemical industry associations.
Variance decomposition across product type, end-use vertical, application function, and technology deployment informed the analytical framework over the projection horizon. Segmentation dimensions modeled include cathodic versus anodic system chemistry, automotive versus appliance versus aerospace end-use specifications, corrosion protection versus electrical insulation application functions, and dip coating versus electrostatic spray technology formats. CAGRs were derived from production capacity expansion announcements, OEM warranty extension timelines, and regulatory compliance deadline schedules. Industry-specific forecast inputs incorporated REACH authorization timelines for chromium trioxide alternatives and China's MEE wastewater discharge standard implementation phases.
Forecasts assume regulatory continuity in EPA emissions guidelines, ECHA REACH registration requirements, and China's GB standards; material policy shifts would require re-modeling of formulation substitution rates and capital expenditure timelines. Specific risk factors include per- and polyfluoroalkyl substance restrictions affecting pretreatment chemistries, epoxy resin feedstock volatility tied to crude oil derivatives, and concentrated anode supply disruption from German or Japanese metalworking clusters. Revision becomes warranted when ISO 12944 certification timelines extend beyond standard validation periods or when automotive OEM warranty requirements accelerate beyond 12-year corrosion protection thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Floor Coatings Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Global Battery Coating Market
Coatings
Conductive Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
North America Thermal Spray Market
Coatings
Sustained Release Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
Process Pipe Coating Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Electrocoat Market
Coatings
OEM Coatings Market
Coatings
Textile Coatings Market
Coatings
Global High-Performance Anti-Corrosion Coatings Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Mexico Protective Coatings Market