
 Water-Based Alkyd Coatings Market | 2026-2036
Water-Based Alkyd Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Based Alkyd Coatings Market Analytics
Modular tinting systems and unbundled base-and-colorant packaging is decoupling volume purchases from fixed-color commitments, letting contractors scale orders to project size. BASF SE leverages its resin chemistry depth to supply alkyd emulsion intermediates across multiple brand channels. PPG Industries anchors North American distribution through architectural store networks with trained specification support. Akzo Nobel N.V. differentiates in European markets through industrial maintenance grades certified for corrosion protection.
Water-based alkyd coatings combine alkyd resin backbones emulsified in water with co-solvent levels below traditional solvent-borne systems, achieving film hardness and gloss retention through oxidative cross-linking of unsaturated fatty acid chains. Interior coatings command stable specification pull from commercial repaint cycles where downtime minimization favors low-odor application. Industrial application represents the fastest-expanding consumption channel as OEMs convert metal finishing lines to meet VOC compliance without sacrificing throughput. Spray technology leads equipment investment in automated finishing installations, while brush and roller methods sustain contractor segment loyalty in residential touch-up work.
EPA VOC regulations and REACH Annex XVII restrictions on hazardous substance content are tightening permissible solvent thresholds, forcing reformulation investments and testing protocols. China's MEE standards on air pollutants from coating operations are accelerating water-based alkyd adoption in Yangtze River Delta manufacturing clusters. ISO 11890 test methods for VOC determination provide the technical baseline for cross-border product qualification and market access. Stakeholders must track evolving substance restriction lists and regional enforcement intensity to align R&D pipelines with compliance timelines.
Market Dynamics
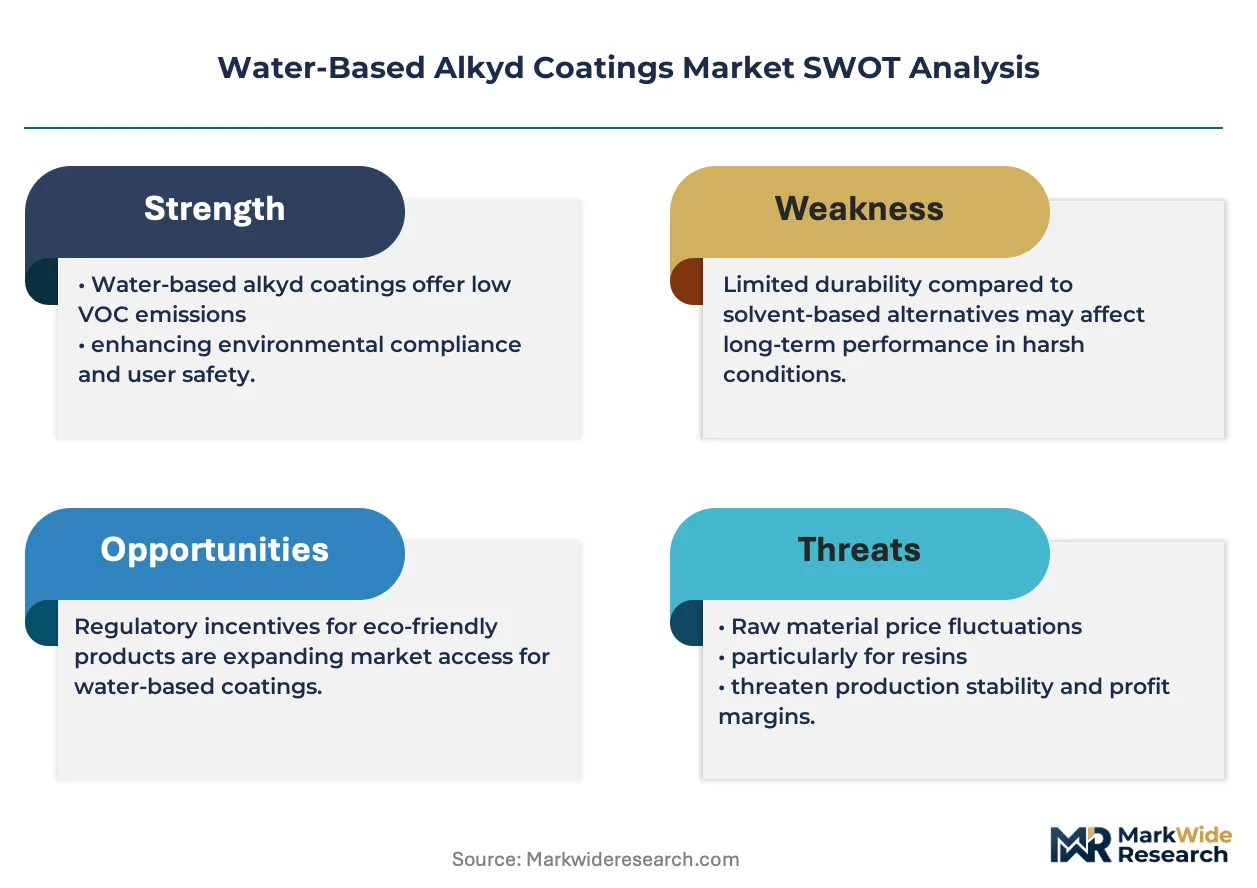
VOC compliance mandates are forcing solvent-to-water conversions across coating manufacturing bases, with reformulation investments now determining competitive positioning in architectural and industrial segments.
Growth Catalysts
- REACH Annex XVII restrictions:Tightening hazardous substance thresholds in Europe are compelling manufacturers to accelerate water-based alkyd development for cross-border market access.
- Metal finishing OEMs:Automotive and appliance producers in Germany and China are converting coating lines to meet emission standards without sacrificing throughput.
- Yangtze River Delta clusters:China's MEE air pollutant standards are concentrating new water-based alkyd capacity in coastal manufacturing hubs.
Market Restraints
- Petrochemical feedstock volatility:Unsaturated fatty acid and alkyd resin intermediate costs fluctuate with palm oil and soybean oil commodity markets.
- Drying time performance gap:Water-based systems require longer oxidative cross-linking periods than solvent-borne alternatives, limiting adoption in high-speed industrial lines.
- Specialty additive supply:Coalescing agents and defoamers for water-based alkyds concentrate among a limited supplier base in Western Europe.
Strategic Opportunities
- US IRA clean manufacturing incentives:Tax credits for low-VOC coating production are attracting capital investment in domestic water-based alkyd capacity.
- Modular tinting systems:Unbundled base-and-colorant packaging lets contractors scale orders to project size, decoupling volume from fixed-color commitments.
- Industrial maintenance corrosion protection:Certified grades for infrastructure refurbishment represent underpenetrated specification pull in European markets.
Industry Challenges
- Formulation chemist scarcity:Expertise in emulsion stability and oxidative cross-linking optimization remains concentrated among senior technical staff approaching retirement.
- ISO 11890 testing protocols:VOC determination standardization creates compliance timeline friction for multi-market product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Based Alkyd Coatings Market |
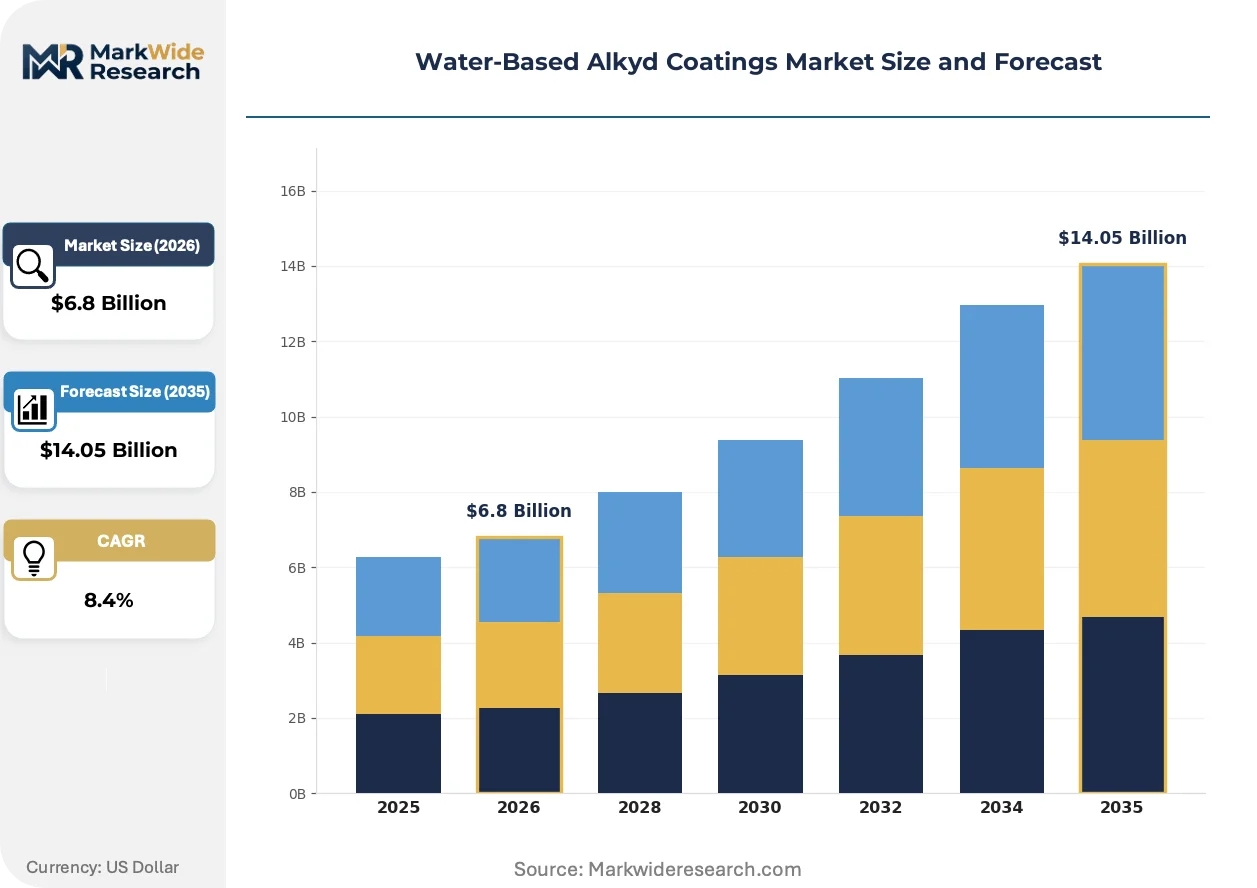
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Coatings, Exterior Coatings, Primers, Sealers Application: Residential, Commercial, Automotive, Industrial End User: Contractors, DIY Enthusiasts, Manufacturers, Distributors Technology: Spray, Brush, Roller, Electrostatic |
| Companies Covered | BASF SE, RPM International, The Sherwin-Williams Company, Kansai Paint, Nippon Paint Holdings, PPG Industries, Axalta Coating Systems, Jotun, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Based Alkyd Coatings Market Evolving Landscape
Reformulation chemistry and application equipment are converging to close the performance gap between water-based and solvent-borne systems, reshaping specification behavior across end-use verticals.
Hybrid alkyd-acrylic emulsion technology is electrifying film formation dynamics in high-gloss architectural coatings. Residential repaint contractors in the United States are specifying these systems for kitchen and trim applications where hardness and block resistance rival solvent alternatives. The technology is electrifying demand migration from traditional alkyd enamels in premium renovation segments.
EPA VOC regulations are tightening permissible solvent thresholds in architectural and industrial maintenance categories. Manufacturers must now validate reformulations through third-party certification to maintain shelf placement in major retail channels. Metal finishing operations in Ohio and Michigan are responding by retrofitting spray booths and accelerating water-based alkyd qualification timelines.
Specification support unbundling from product supply is compressing contractor decision cycles. Architectural store networks now employ trained technical staff who guide coating selection independent of brand loyalty, displacing traditional distributor relationships. This pattern is most visible in German-speaking markets where Baumarkt chains have invested in in-store specification laboratories.
Water-Based Alkyd Coatings Market Segmentation
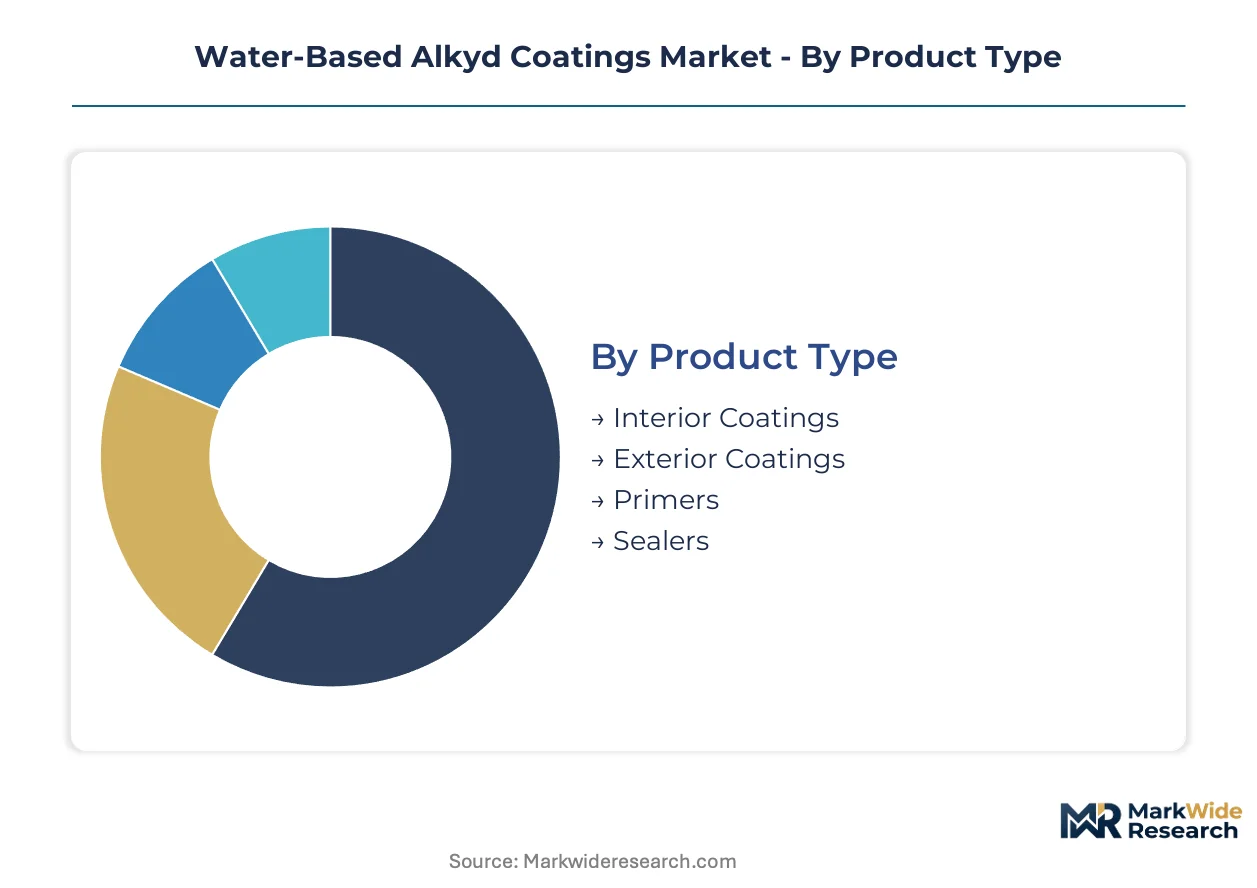
Water-based alkyd coatings demand fragments across formulation chemistry, application method, and procurement channel. Each segment imposes distinct capital requirements and margin structures that determine competitive positioning.
Product Type:
Capital intensity varies sharply across formulation categories, with exterior-grade systems demanding the most substantial R&D and testing infrastructure.
- Interior Coatings:Low-odor formulations with oxidative cross-linking optimized for confined-space application. Demand concentrates in US residential renovation cycles where EPA VOC compliance drives specification pull in kitchen and trim segments.
- Exterior Coatings:Weather-resistant alkyd emulsions with enhanced UV stability and hydrophobic film formation. Germany's architectural refinishing sector absorbs significant volumes for facade restoration projects under REACH substance restrictions.
- Primers:High-build adhesion promoters for substrate sealing in multi-coat systems.
- Sealers:Penetrating alkyd emulsions for porous surface preparation in wood and masonry.
Most installed capacity flows through Interior Coatings. Expansion is steepest in Exterior Coatings.
Application:
Volume concentration and margin profiles diverge across end-use environments, with industrial lines requiring the most specialized qualification protocols.
- Industrial:High-throughput metal finishing systems with automated spray integration and corrosion-grade certification. China's Yangtze River Delta manufacturing clusters are converting solvent lines to meet MEE air pollutant standards.
- Automotive:OEM coating lines with color-matching precision and chip-resistance specifications. Tier-1 suppliers in Germany and the United States are qualifying water-based alkyd primers for non-exterior components.
- Residential:Brush and roller application in renovation and new construction.
- Commercial:Facility maintenance with downtime-minimization requirements.
Industrial application commands the highest specification barriers. Residential renovation delivers the broadest volume base.
End User:
Procurement scale and technical support needs separate contractor-driven demand from direct manufacturer specification.
- Contractors:Professional applicators purchasing through architectural store networks with trained specification support. US Baumarkt-style chains now employ in-store technical staff who guide coating selection independent of brand loyalty.
- Manufacturers:OEM coating line operators with formulation qualification and supply security requirements.
- DIY Enthusiasts:Small-volume retail purchasers through home improvement channels.
- Distributors:Intermediary stocking with regional logistics and credit terms.
Contractor channels absorb the majority of premium-grade volume. Manufacturer direct procurement is expanding most quickly in industrial segments.
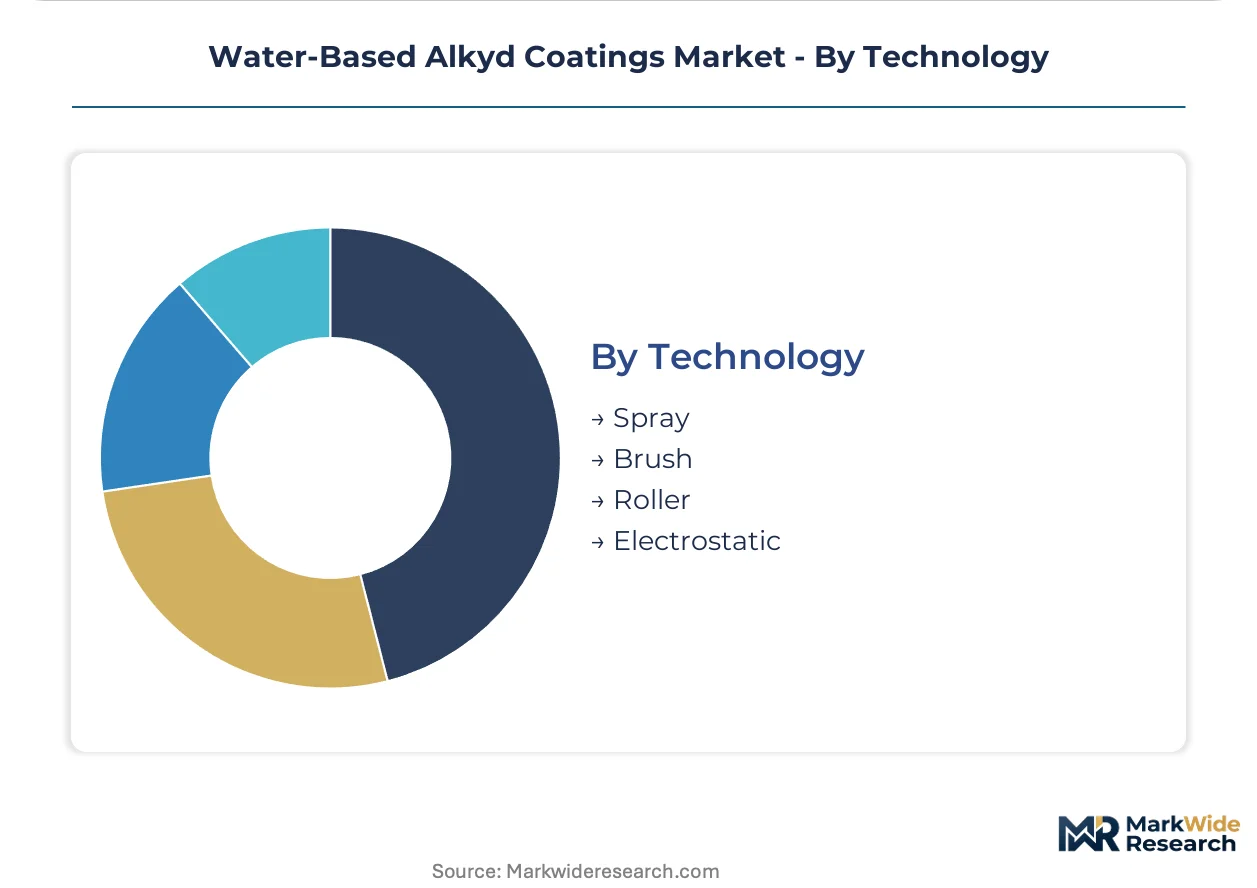
Technology:
Equipment investment and labor substitution potential separate automated from manual application methods.
- Spray:Automated and handheld systems delivering film uniformity at production speed. Metal finishing operations in Ohio and Michigan are retrofitting spray booths to accelerate water-based alkyd qualification timelines.
- Electrostatic:Charged-particle application for complex geometries with material efficiency advantages.
- Brush:Manual application sustaining contractor loyalty in residential touch-up and detail work.
- Roller:Large-surface coverage with lower skill requirements.
Spray technology dominates new equipment investment. Brush methods retain specification share in renovation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water-based alkyd coatings emerged from European resin chemistry traditions in the mid-20th century, with German and Dutch laboratories pioneering emulsion stabilization techniques that enabled industrial-scale production of low-VOC architectural finishes.
Germany
Facade restoration projects in Berlin and Hamburg drive specification pull for exterior-grade alkyd emulsions with enhanced UV stability. REACH Annex XVII substance restrictions compel manufacturers to reformulate corrosion-protection grades for infrastructure maintenance. The Rhine-Ruhr industrial corridor hosts concentrated coating R&D facilities serving cross-border OEM qualification programs.
China
Automotive OEMs in Shanghai and appliance manufacturers in Guangzhou are converting metal finishing lines to meet MEE air pollutant standards without throughput sacrifice. The country's environmental ministry enforces stricter VOC thresholds in Yangtze River Delta manufacturing clusters. Suzhou and Wuxi coating hubs are expanding water-based alkyd capacity to supply converted solvent lines.
United States
Residential renovation cycles in the Midwest and Southeast absorb significant volumes of low-odor interior formulations for kitchen and trim applications. EPA VOC regulations tighten permissible solvent thresholds in architectural categories, forcing third-party certification for retail shelf placement. Ohio and Michigan metal finishing operations are retrofitting spray booths to accelerate water-based alkyd qualification timelines.
Japan
Precision coating requirements for automotive components and electronics housings sustain demand for high-gloss alkyd emulsions with oxidative cross-linking optimization. METI industrial standards encourage low-VOC formulation adoption in manufacturing supply chains. The Nagoya industrial zone concentrates technical coating laboratories serving Tier-1 automotive suppliers.
India
Infrastructure refurbishment projects in Maharashtra and Gujarat generate specification pull for industrial maintenance grades with corrosion protection certification. BIS standards on hazardous substance content in architectural coatings are tightening alignment with international VOC protocols. The Mumbai-Pune manufacturing corridor is attracting coating capacity investments targeting domestic OEM conversion programs.
Water-Based Alkyd Coatings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and specification support depth. The vendor base organizes into three tiers: integrated resin-to-coating manufacturers with captive emulsion chemistry, regional formulators with distribution scale advantages, and niche specialists certified for industrial maintenance applications. Consolidation pressure intensifies as REACH compliance costs and ISO 11890 testing protocols favor players with multi-market product portfolios. Dominant competitive moves include backward integration into alkyd resin intermediates and geographic expansion through architectural store network partnerships.
Among European-integrated chemical conglomerates, BASF SE and Akzo Nobel N.V. occupy positions exemplifying resin-chemistry-depth archetypes, while PPG Industries anchors North American representation through distribution-scale positioning. These three entities represent distinct strategic postures: emulsion intermediate supply across multiple channels, European industrial maintenance certification focus, and architectural specification support unbundling from product supply respectively.
| Leading Market Players |
|---|
| BASF SE |
| RPM International |
| The Sherwin-Williams Company |
| Kansai Paint |
| Nippon Paint Holdings |
| PPG Industries |
| Axalta Coating Systems |
| Jotun |
| Akzo Nobel N.V. |
| Others |
Value Network & Pricing Analysis
EPA VOC regulations and REACH Annex XVII restrictions gate qualified supply for premium-tier water-based alkyd coatings, reserving premium pricing access to manufacturers with validated low-VOC formulations and third-party certification infrastructure. Buyers without compliance documentation face exclusion from major retail channels and OEM qualification programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the water-based alkyd coatings market. Price differentiation hinges on REACH certification grade and volume scale commitments from contractors. Cost compression in economy tiers is intensifying because petrochemical feedstock volatility squeezes unsaturated fatty acid margins. DIY enthusiasts exhibit highest price sensitivity, while industrial OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Reverse-logistics flows for unused tint-base returns and off-specification batches concentrate in Germany and China, where coating hubs operate centralized reformulation facilities. Raw material dependencies draw from palm oil and soybean oil commodity markets, plus specialty coalescing agents from Western European suppliers. Single-source vulnerability for alkyd resin intermediates threatens supply continuity. Distribution runs through architectural store networks with trained specification support displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA VOC tightening and REACH Annex XVII expansion continuously reset qualification barriers and demand thresholds.
For Market Incumbents: Anticipate accelerated solvent-to-water conversion timelines by securing captive supply of alkyd resin intermediates through backward integration into emulsion chemistry. Defend specification position by embedding trained technical staff within architectural store networks before competitor channel capture. Prioritize ISO 11890 testing protocol mastery to compress multi-market product launch cycles. For New Entrants and Emerging Players: Hybrid alkyd-acrylic emulsion technology offers a technology-first wedge into premium residential renovation segments where hardness specifications rival solvent-borne alternatives. Target industrial maintenance corrosion protection grades in European markets where certification gaps persist among regional formulators. Pursue modular tinting system partnerships with Baumarkt-style chains to bypass traditional distributor gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with distribution scale but lacking REACH-compliant product portfolios. Long-term viability favors integrated resin-to-coating manufacturers with multi-market qualification infrastructure. Watch MEE enforcement intensity in Yangtze River Delta clusters as inflection indicator for Chinese capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkyd Resin Intermediates | Captive emulsion chemistry supply secures margin control against petrochemical feedstock volatility. |
| REACH Annex XVII Certification Investment | Validated low-VOC formulations unlock cross-border market access in European industrial segments. |
| Architectural Store Network Partnership | Trained in-store specification staff displace traditional distributor relationships in German-speaking markets. |
| Hybrid Alkyd-Acrylic Emulsion Development | Film hardness parity with solvent-borne systems electrifies demand migration in premium renovation. |
| Modular Tinting System Deployment | Unbundled base-and-colorant packaging lets contractors scale orders to project size without fixed-color commitment. |
Research Methodology
Direct dialogue with coating plant managers, procurement leads at automotive OEMs, architectural store specification staff, and technical R&D directors anchored qualitative grounding. Secondary validation drew from EPA regulatory filings, ECHA substance restriction updates, customs trade data for alkyd resin intermediates, and SEC 10-K disclosures from listed coating manufacturers. Bottom-up volume estimates and top-down value assessments underwent iterative triangulation.
Segment-level projections across formulation chemistry, application method, end-use vertical, and regional production hub fed into the analytical framework across the analysis window. CAGRs derived from regression against historical conversion rates from solvent-borne to water-based systems. Key inputs included MEE enforcement intensity indices for Chinese manufacturing clusters and REACH substance restriction timeline probabilities.
The model holds under stable regulatory enforcement trajectories; deviation in EPA VOC threshold acceleration or ECHA substance list expansion would shift conversion timeline assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Sputter Coater Market
Coatings
Anti Soiling Coating Market
Coatings
Australia Industrial Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Coating Resins Market
Coatings
Global Mirror Coatings Market
Coatings
Transportation Coating Market
Coatings
Global Intumescent Coatings Market
Coatings
Sol Gel Nanocoating Market
Coatings
Topcoat Market
Coatings
Thailand Architectural Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
High Temperature Coatings Market
Coatings
Fluoropolymer Coating Market
Coatings
Hull Coatings Market