
 Cooling Management System Market | 2026-2036
Cooling Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Management System Market Analysis
China is narrowing its domestic supply gap for precision cooling hardware through aggressive fab and data center infrastructure build-outs. Schneider Electric leverages integrated power and cooling architectures to anchor large-scale deployments across Asia-Pacific. Vertiv Holdings sustains engineering density in thermal management through dedicated liquid cooling R&D pipelines. Johnson Controls competes on chiller efficiency ratings and building automation interoperability.
A cooling management system coordinates heat rejection, fluid distribution, and temperature control across industrial, commercial, and digital infrastructure using refrigerant loops, pumped liquids, or forced air with defined set-point tolerances. Chillers dominate installed value in legacy facilities while immersion cooling commands premium positioning for high-density computing loads. Data center applications absorb the fastest capacity additions, though industrial facilities retain the broadest installed base across manufacturing and process industries. Liquid cooling segments attract capital as chip power envelopes exceed air-cooling thresholds.
The US EPA enforces refrigerant transition timelines under AIM Act mandates while the EU F-Gas Regulation imposes production quota cuts that reshape equipment import requirements. China's MEE enforces dual carbon goals that accelerate adoption of low-global-warming-potential refrigerants in new construction. Stakeholders must monitor regulatory divergence across these jurisdictions when configuring product portfolios and certifying equipment for cross-border deployment.
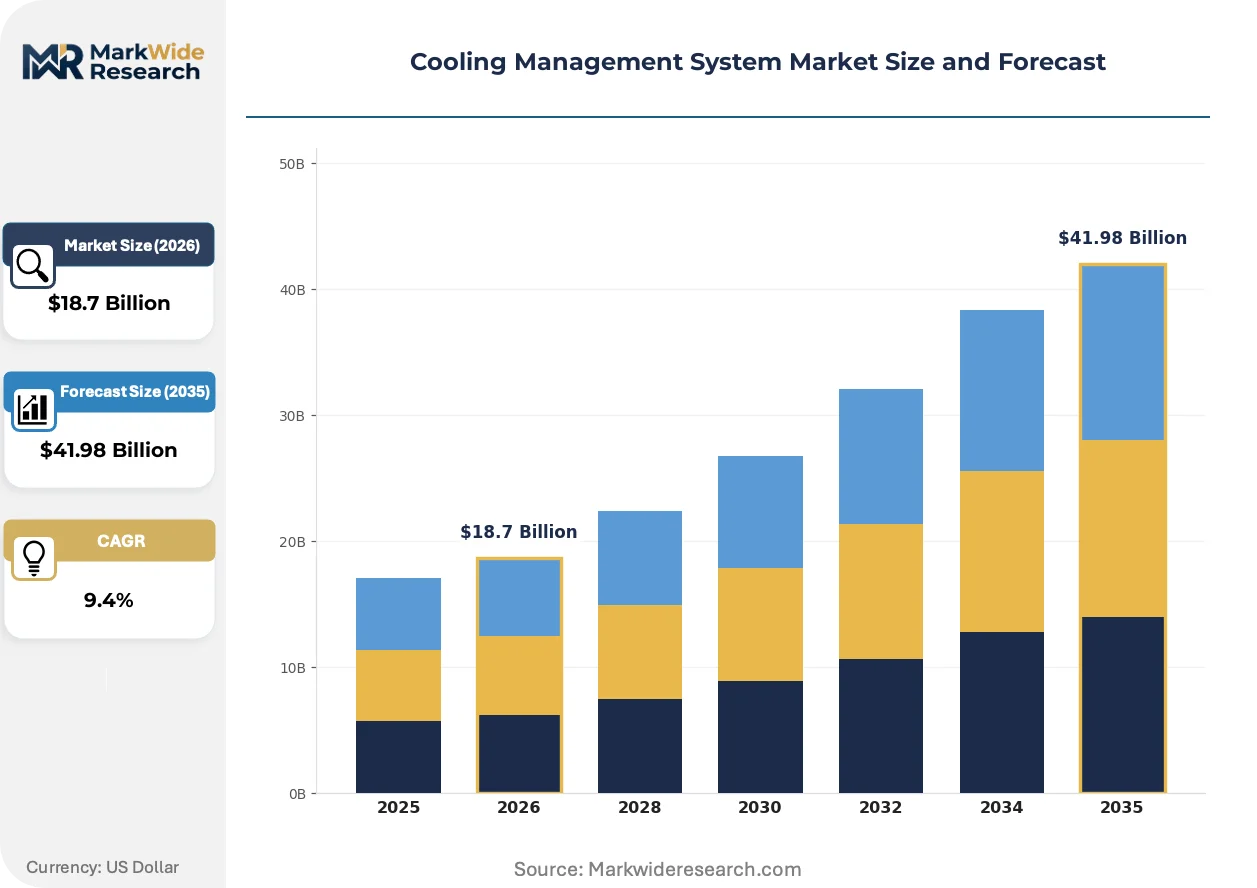
Market Dynamics
Data center thermal loads from AI training clusters are compressing equipment refresh cycles and forcing wholesale architecture shifts from air to liquid cooling, restructuring supplier relationships around integrated thermal-electrical platforms.
Growth Catalysts
- AIM Act refrigerant mandates:The US EPA's phasedown schedules for high-GWP hydrofluorocarbons are accelerating replacement demand for next-generation chiller systems in commercial and industrial facilities.
- Hyperscale data center construction:Cloud operators in China are procuring precision cooling hardware at volume for new campus deployments, concentrating demand for modular chiller and heat exchanger assemblies.
- Immersion cooling technology maturation:Dielectric fluid systems for direct-to-chip thermal management are crossing reliability thresholds that enable deployment in production AI server environments.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and piping manufacturers face margin compression from base metal price swings that resist full pass-through in long-term equipment contracts.
- Refrigerant supply concentration:Low-GWP alternative production remains concentrated among a limited set of chemical suppliers, creating availability risk during quota transition periods under EU F-Gas Regulation.
- Legacy infrastructure lock-in:Existing chilled-water plants in industrial facilities carry sunk capital that delays adoption of distributed liquid cooling architectures despite superior efficiency metrics.
Strategic Opportunities
- India data center build-out:Cloud and colocation operators are greenfielding facilities with native liquid cooling designs, bypassing retrofit constraints that burden mature markets.
- Waste heat recovery integration:District heating networks in Northern Europe are creating pull-through demand for absorption chillers and heat pump couplings that monetize thermal byproducts.
- EU Green Deal industrial decarbonization:Facility energy performance standards are mandating cooling system upgrades as a condition for operational permits in energy-intensive manufacturing.
Industry Challenges
- Thermal-fluid engineering scarcity:The specialized skill set spanning CFD simulation, refrigerant thermodynamics, and control systems integration commands premium compensation and extends project timelines.
- Cross-jurisdictional certification complexity:Equipment manufacturers must navigate divergent safety and efficiency testing protocols across EPA, EU F-Gas, and China's GB standards to serve multinational customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooling Management System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Cooling Towers, Heat Exchangers, Refrigeration Units Application: Data Centers, Industrial Facilities, Residential Buildings, Commercial Spaces Technology: Liquid Cooling, Air Cooling, Evaporative Cooling, Immersion Cooling End User: Telecommunications, Manufacturing, Healthcare, Automotive |
| Companies Covered | Schneider Electric, Vertiv Holdings, Johnson Controls, Rittal GmbH & Co. KG, Emerson Electric, STULZ GmbH, Mitsubishi Heavy Industries, Modine Manufacturing Company, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Management System Market Emerging Trajectories
Cooling system architectures are fragmenting along workload density lines, with divergent technology paths emerging for legacy commercial buildings versus hyperscale compute facilities. Suppliers are repositioning around thermal management as a service capability rather than discrete equipment sales.
Direct liquid cooling is migrating from experimental deployments to standard configurations for AI training clusters. Hyperscale operators are specifying cold-plate and immersion systems as baseline requirements for new server procurements. This technology transition is compressing the addressable market for traditional perimeter CRAC units in high-density zones.
The EU F-Gas Regulation is tightening production quotas for fluorinated gases through 2030, forcing chiller OEMs to redesign compressor and heat exchanger platforms around natural refrigerants and lower-GWP synthetic alternatives. Equipment import certification timelines have lengthened as notified bodies adapt testing protocols, creating near-term supply friction for cross-border deployment.
Facility operators are unbundling cooling infrastructure procurement from general construction contracts, establishing direct relationships with thermal specialists for design-build-performance engagements. This pattern is most pronounced in Northern Virginia and Frankfurt data center clusters, where power density specifications now precede site selection decisions and cooling architecture dictates electrical infrastructure sizing.
Cooling Management System Market Segmentation
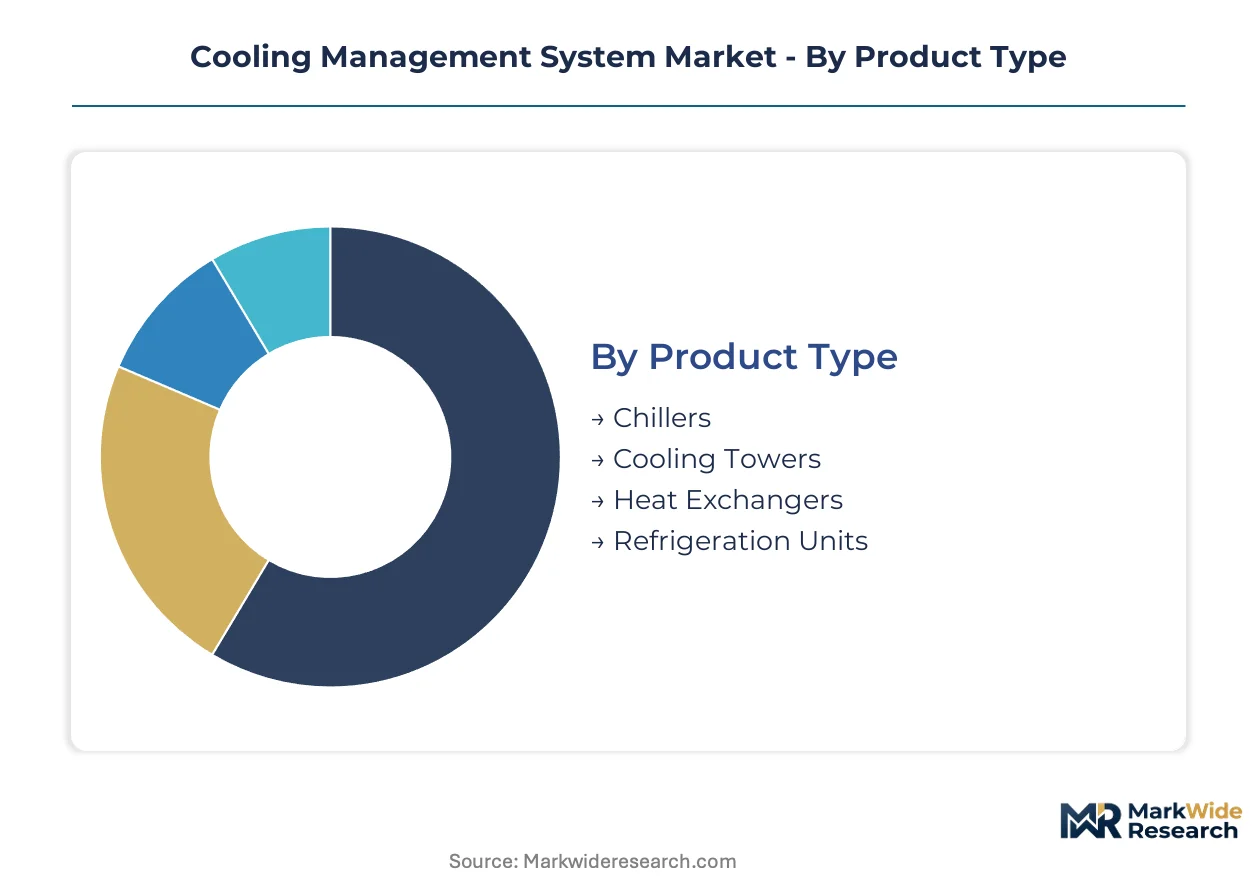
Cooling management system procurement fragments across equipment categories, deployment contexts, and thermal transfer methods. Each segmentation axis reveals distinct competitive dynamics and margin structures that suppliers must navigate.
Product Type:
Mature chiller platforms dominate installed base value while emerging thermal hardware reshapes growth trajectories.
- Chillers:Centralized refrigeration plants using vapor-compression or absorption cycles to generate chilled water for distribution. Industrial facilities in China and Germany absorb the largest capacity additions as process cooling loads expand. EPA AIM Act refrigerant mandates compress replacement cycles for legacy R-134a and R-410A systems.
- Heat Exchangers:Shell-and-tube, plate, and finned-coil assemblies transferring thermal energy between fluid streams. Data center liquid cooling loops in Northern Virginia and Frankfurt specify compact brazed-plate designs for high-efficiency heat rejection. Copper and aluminum input volatility squeezes fabricator margins on long-delivery contracts.
- Cooling Towers:Open-circuit and closed-circuit evaporative heat rejection systems for large-scale industrial and power generation applications.
- Refrigeration Units:Self-contained cooling systems for commercial cold storage, process cooling, and specialized industrial applications.
Chillers retain volume leadership; heat exchangers hold the steepest expansion curve.
Application:
Cost tier differentiation separates mission-critical precision cooling from commodity comfort applications.
- Data Centers:Precision environmental control maintaining tight temperature and humidity tolerances for server reliability. Hyperscale operators in China are greenfielding campuses with native liquid cooling designs that bypass air-cooling retrofit constraints. AI training cluster thermal densities exceed 50 kW per rack, forcing architecture shifts from perimeter CRAC units to direct liquid cooling.
- Industrial Facilities:Process cooling for manufacturing, chemical processing, and energy production with varying redundancy requirements. EU Green Deal industrial decarbonization mandates are conditioning operational permits on cooling system efficiency upgrades in energy-intensive sectors. Sunk capital in existing chilled-water plants delays adoption of distributed liquid architectures.
- Commercial Spaces:Comfort cooling and ventilation for offices, retail, and hospitality with standardized efficiency ratings.
- Residential Buildings:Distributed cooling systems for multi-family and single-family housing with cost-sensitive specification patterns.
Industrial facilities command the broadest installed base; data centers are expanding most quickly.
Technology:
Customer type segmentation separates hyperscale self-operators from facility outsourcing arrangements.
- Liquid Cooling:Pumped dielectric fluids or water-glycol mixtures transferring heat directly from high-power components. Cold-plate and immersion configurations are crossing reliability thresholds for production AI server deployment. Cloud operators now specify liquid cooling as baseline for new server procurements.
- Immersion Cooling:Submersion of entire server assemblies in engineered dielectric fluids for extreme heat flux management. Single-phase and two-phase systems are maturing for hyperscale deployment with simplified maintenance protocols. Dielectric fluid supply concentration among limited chemical suppliers creates availability risk.
- Air Cooling:Conventional forced-air heat rejection using perimeter CRAC units and raised-floor distribution.
- Evaporative Cooling:Adiabatic cooling using water evaporation for energy-efficient heat rejection in suitable climates.
Air cooling retains installed base dominance; immersion cooling is gaining share fastest.
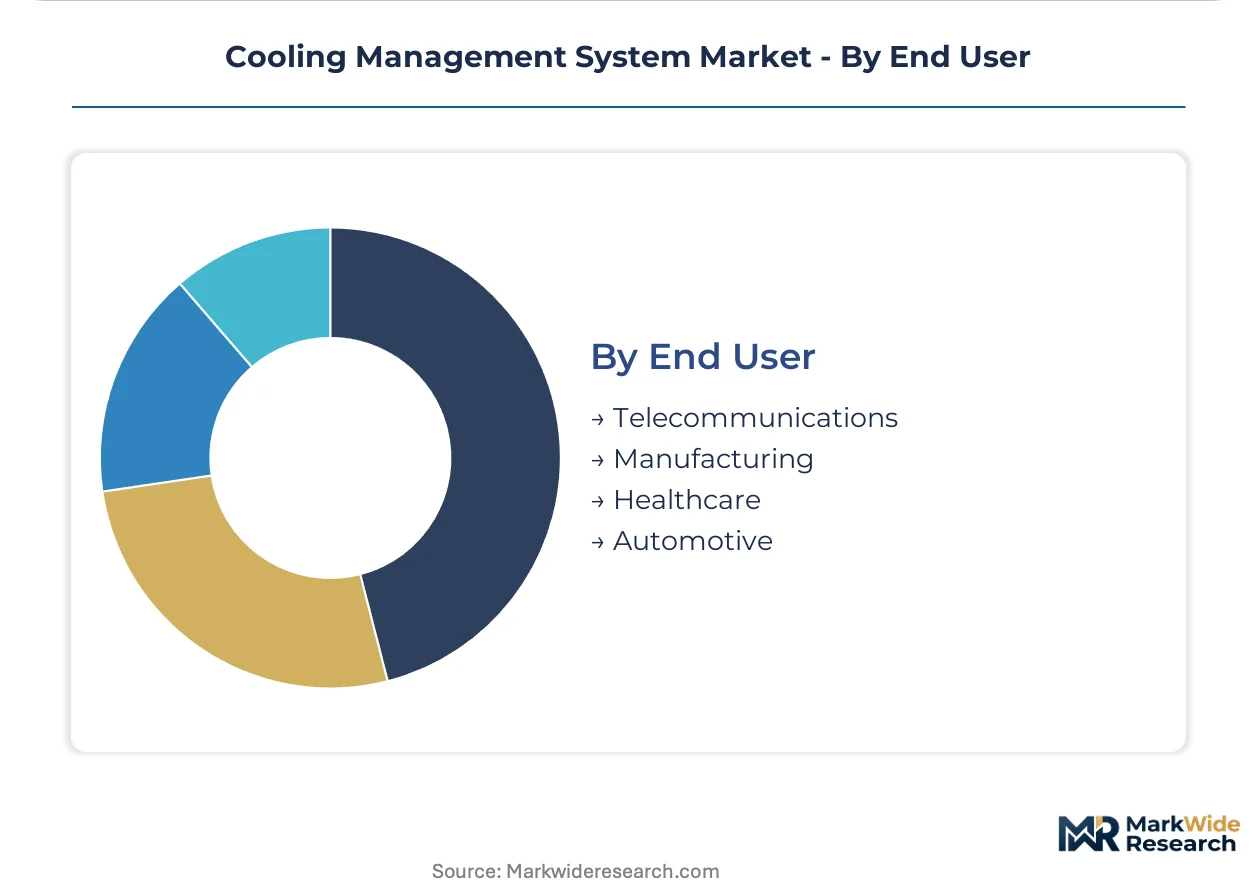
End User:
Geography concentration patterns align end-user demand with regional industrial specialization and digital infrastructure build-outs.
- Telecommunications:Edge computing facilities and central offices requiring reliable thermal management for network equipment. 5G infrastructure densification is driving modular cooling deployments across India and Southeast Asia. Tower operators are specifying integrated power-cooling skids for rapid site commissioning.
- Manufacturing:Process cooling for semiconductors, chemicals, food processing, and heavy industry with continuous-duty requirements. China's dual carbon goals under MEE enforcement are accelerating low-GWP refrigerant adoption in new construction. Thermal-fluid engineering scarcity extends project timelines for complex integrated systems.
- Healthcare:Precision cooling for medical imaging, laboratory environments, and pharmaceutical storage.
- Automotive:Battery thermal management and manufacturing process cooling for electric vehicle production.
Manufacturing retains volume leadership; telecommunications holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chiller and heat exchanger fabrication clusters in China, Germany, and the United States supply the bulk of precision cooling hardware for data center and industrial applications. These three manufacturing basins anchor global equipment availability while regulatory divergence across EPA, EU F-Gas, and China's MEE jurisdictions reshapes cross-border deployment patterns.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are procuring liquid cooling systems at volume for AI training clusters. The EPA's AIM Act refrigerant phasedown mandates are compressing replacement cycles for legacy chilled-water plants in commercial buildings. Ashburn and Loudoun County data center campuses now specify thermal infrastructure before electrical sizing, reversing traditional construction sequencing.
China
Hyperscale cloud campuses in Inner Mongolia and Guizhou are driving chiller and heat exchanger procurement for new data center build-outs. The MEE enforces dual carbon goals that accelerate low-GWP refrigerant adoption in new industrial construction. Alibaba and Tencent facilities in the Yangtze River Delta are deploying native liquid cooling designs that bypass air-cooling retrofit constraints entirely.
Germany
Industrial process cooling loads in the Rhine-Ruhr and Bavarian manufacturing corridors sustain demand for high-efficiency chiller replacements. The EU F-Gas Regulation imposes production quota cuts that force OEMs to redesign compressor platforms around natural refrigerants. Frankfurt data center clusters are unbundling cooling procurement from general construction contracts, establishing direct thermal specialist relationships.
India
Cloud and colocation operators in Maharashtra and Karnataka are greenfielding facilities with native liquid cooling designs that sidestep retrofit burdens. The Bureau of Indian Standards is developing cooling equipment efficiency protocols aligned with EU testing frameworks. Mumbai and Bangalore data center construction is absorbing modular chiller assemblies for rapid site commissioning.
Japan
Semiconductor fabrication facilities in Kyushu and the Kanto region require precision thermal management for advanced node production. METI efficiency standards mandate cooling system upgrades as a condition for industrial operational permits. Tokyo data center operators are specifying integrated power-cooling skids to manage space constraints in dense urban deployments.
Cooling Management System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in heat exchanger and compressor fabrication. The supplier base organizes around three archetypes: integrated power-cooling platform vendors, dedicated thermal management specialists, and diversified industrial conglomerates with chiller divisions. Competitive positioning hardens through M&A activity targeting liquid cooling engineering teams and strategic partnerships binding chip manufacturers to thermal system designers.
Among diversified industrial conglomerates, Schneider Electric, Johnson Controls, and Mitsubishi Heavy Industries occupy positions spanning building automation through precision cooling. These manufacturers exemplify platform breadth that anchors large-scale deployment relationships. Vertiv Holdings and Rittal GmbH & Co. KG represent specialists whose engineering density in thermal management serves as a counterweight to integrated portfolios. STULZ GmbH and Modine Manufacturing Company sit within the component-to-system transition zone, supplying heat rejection hardware that feeds into broader platform configurations.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Holdings |
| Johnson Controls |
| Rittal GmbH & Co. KG |
| Emerson Electric |
| STULZ GmbH |
| Mitsubishi Heavy Industries |
| Modine Manufacturing Company |
| Daikin Industries |
| Others |
Supply Flow & Price Mechanics
Shanghai's precision cooling fabrication cluster anchors global chiller and heat exchanger capacity, concentrating upstream bargaining power among copper and aluminum processors that feed downstream OEM pricing negotiations. This geographic concentration of component supply creates asymmetric cost pass-through dynamics where long-delivery equipment contracts resist full input volatility recovery.
Pricing Analysis
The EPA's AIM Act dictates the pricing tier structure across the cooling management system market, separating premium low-GWP refrigerant platforms from legacy equipment facing accelerated replacement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from hyperscale data center operators. Cost compression in mid-tier chiller segments is intensifying because copper and aluminum input volatility resists contractual pass-through. Industrial facilities in energy-intensive manufacturing prove most price-sensitive due to sunk capital in existing infrastructure, while hyperscale cloud operators in China and the United States demonstrate lowest sensitivity given thermal density mandates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for cooling equipment OEMs navigating cross-border deployment. Manufacturing concentration rests on China, Germany, and the United States for precision chiller fabrication, with heat exchanger component sourcing drawing from Taiwan and South Korea for advanced brazed-plate designs. Copper tubing, aluminum fin stock, and engineered dielectric fluids represent critical input dependencies with concentrated supplier bases. Single-source vulnerability in low-GWP refrigerant chemical production creates availability friction during EU F-Gas quota transition periods. Distribution runs through direct OEM relationships with hyperscale operators and industrial EPC contractors, bypassing traditional HVAC wholesale channels for large-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cooling management system demand sits in early-cycle expansion as AI training cluster thermal densities force wholesale architecture shifts from air to liquid cooling across hyperscale facilities. Native liquid cooling designs in greenfield data centers bypass retrofit constraints that burden mature markets, accelerating procurement velocity for integrated thermal-electrical platforms.
For Market Incumbents: Pre-empt margin erosion in perimeter CRAC units by accelerating cold-plate and immersion cooling R&D pipelines before hyperscale procurement standards solidify. Defensive consolidation through captive supply of copper-aluminum heat exchanger fabrication insulates against base metal volatility that compresses margins on long-delivery contracts. Channel control through direct design-build-performance engagements with Northern Virginia and Frankfurt data center operators locks out modular assembly competitors.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given limited incumbent presence and accelerating cooling load growth from digital infrastructure densification. Greenfield telecommunications edge sites across India offer second-tier white space where integrated power-cooling skids command premium positioning against fragmented local HVAC suppliers. Go-to-market execution through EPC contractor partnerships bypasses capital-intensive direct sales force requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors liquid cooling engineering specialists with demonstrated production deployments at AI server reliability thresholds. Long-term viability across the analysis window hinges on refrigerant transition readiness as EPA and EU F-Gas mandates compress replacement cycles. Acquisition target archetype: thermal-fluid engineering teams with CFD simulation and control systems integration capabilities. The signal to watch is hyperscale server procurement specifications that designate liquid cooling as baseline rather than optional configuration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Redesign | EPA AIM Act compliance secures market access for next-generation chiller deployments in commercial buildings. |
| Liquid Cooling R&D Expansion | Direct-to-chip thermal management capabilities capture hyperscale AI server procurement specifications. |
| Heat Exchanger Backward Integration | Captive copper-aluminum fabrication insulates margins from base metal price volatility. |
| Direct OEM Relationship Formation | Unbundled cooling procurement from general construction contracts locks in design-build-performance engagements. |
| EU F-Gas Certification Investment | Notified body testing protocol alignment accelerates cross-border equipment deployment timelines. |
Methodological Framework
Desk research of equipment manufacturer technical specifications, regulatory filings with EPA and EU bodies, and hyperscale operator procurement disclosures preceded structured interviews with data center engineering directors, thermal management OEM product managers, industrial facility maintenance directors, and EPC contractor procurement leads. Primary fieldwork combined with secondary validation against SEC 10-K filings, customs trade data, and MEE enforcement notices. Bottom-up segment sizing triangulated against top-down market aggregation across product type, application, and technology dimensions.
Assumptions held fixed include refrigerant phasedown schedules under EPA AIM Act and EU F-Gas Regulation, copper-aluminum price band continuity, and hyperscale data center construction cadence in China and the United States. Variables modeled across the projection horizon encompass AI server thermal density trajectories, low-GWP refrigerant availability, and industrial decarbonization mandate stringency. Segmentation dimensions included product type, application context, thermal transfer technology, and end-user industry vertical. CAGRs derived from installed base evolution and replacement cycle compression analysis, with input from chiller efficiency rating trends and liquid cooling adoption curves.
Macroeconomic conditions sit as an overlay; deviation in base metal commodity prices, construction cost inflation, or cross-border trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology reliability maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Outage Management System (OMS) Market