
 Bulgaria ICT Market | 2026-2036
Bulgaria ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria ICT Market Insights
Enterprise software distribution channels across Bulgaria are reconfiguring as multinational vendors deepen direct engagement with mid-market clients. SAP Labs Bulgaria leverages its development center footprint to sustain proximity to regional enterprise buyers. Sirma Group Holding anchors domestic delivery capabilities through specialized government and banking solutions. SiteGround competes in cloud hosting by extending infrastructure presence toward Southeast European markets.
Information and communications technology encompasses the design, deployment, and management of digital systems processing data at speeds from gigabit Ethernet to terabit fiber backbones, with software orchestrating computational workloads across distributed architectures. Bulgaria ICT serves commercial automation, public administration digitization, and connected industrial operations. Software and cloud services capture expanding margin pools as enterprises shift capital expenditure to subscription models. Cybersecurity technology leads growth vectors amid EU-wide resilience mandates and rising threat complexity. Hardware maintains stable demand within government modernization programs and educational infrastructure refreshes.
Bulgaria's ICT sector operates under EU regulatory umbrellas including GDPR data protection standards, NIS2 cybersecurity directives, and CE marking requirements for hardware equipment. The Bulgarian Commission for Personal Data Protection enforces alignment with European frameworks, while BIS certification processes govern telecommunications infrastructure standards. Stakeholders must monitor how EU AI Act implementation timelines reshape algorithmic service deployment obligations across Bulgarian enterprise and public sectors.
Market Dynamics
EU digital sovereignty mandates and NIS2 cybersecurity directives are restructuring vendor compliance obligations across Bulgarian enterprise procurement, compressing sales cycles for non-compliant suppliers while accelerating public sector modernization tenders.
Growth Catalysts
- Banking Digitalization:Bulgarian financial institutions are expanding self-service platforms and API-first architectures, creating sustained demand for core banking modernization and fraud detection systems.
- EU Funding Access:Recovery and Resilience Facility allocations prioritize public administration digitization, channeling investment into e-government infrastructure and interoperable data exchanges.
- Sofia Tech Corridor Concentration:The capital's dense clustering of development centers and engineering talent pools reduces vendor recruitment friction and accelerates solution deployment timelines.
Market Restraints
- Input Cost Volatility:Semiconductor component pricing fluctuations and extended lead times for specialized networking hardware strain project budgeting predictability for systems integrators.
- Regulatory Friction:CE marking compliance timelines and BIS telecommunications certification processes extend product launch schedules for foreign equipment vendors entering Bulgarian procurement channels.
- Substitution Pressure:Open-source software stacks and low-code development platforms erode margins for traditional enterprise application licensing in mid-market segments.
Strategic Opportunities
- Plovdiv-Varna Secondary Hubs:Lower operational costs and improving fiber connectivity in these cities attract delivery center expansion beyond Sofia's saturated talent market.
- EU AI Act Preparation:Early compliance positioning for algorithmic transparency requirements creates advisory and implementation service revenue streams before mandatory enforcement phases.
- Edge-Cloud Convergence:Hybrid architectures combining local data processing with centralized analytics address latency-sensitive industrial IoT applications in manufacturing zones.
Industry Challenges
- Specialized Cybersecurity Skills Gap:Shortages of certified penetration testers and incident response professionals inflate salary costs and extend vendor staffing timelines for security-critical contracts.
- Legacy System Integration Complexity:Government agencies and state-owned enterprises maintain decades-old COBOL and mainframe environments that resist seamless API connectivity with modern cloud services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria ICT Market |
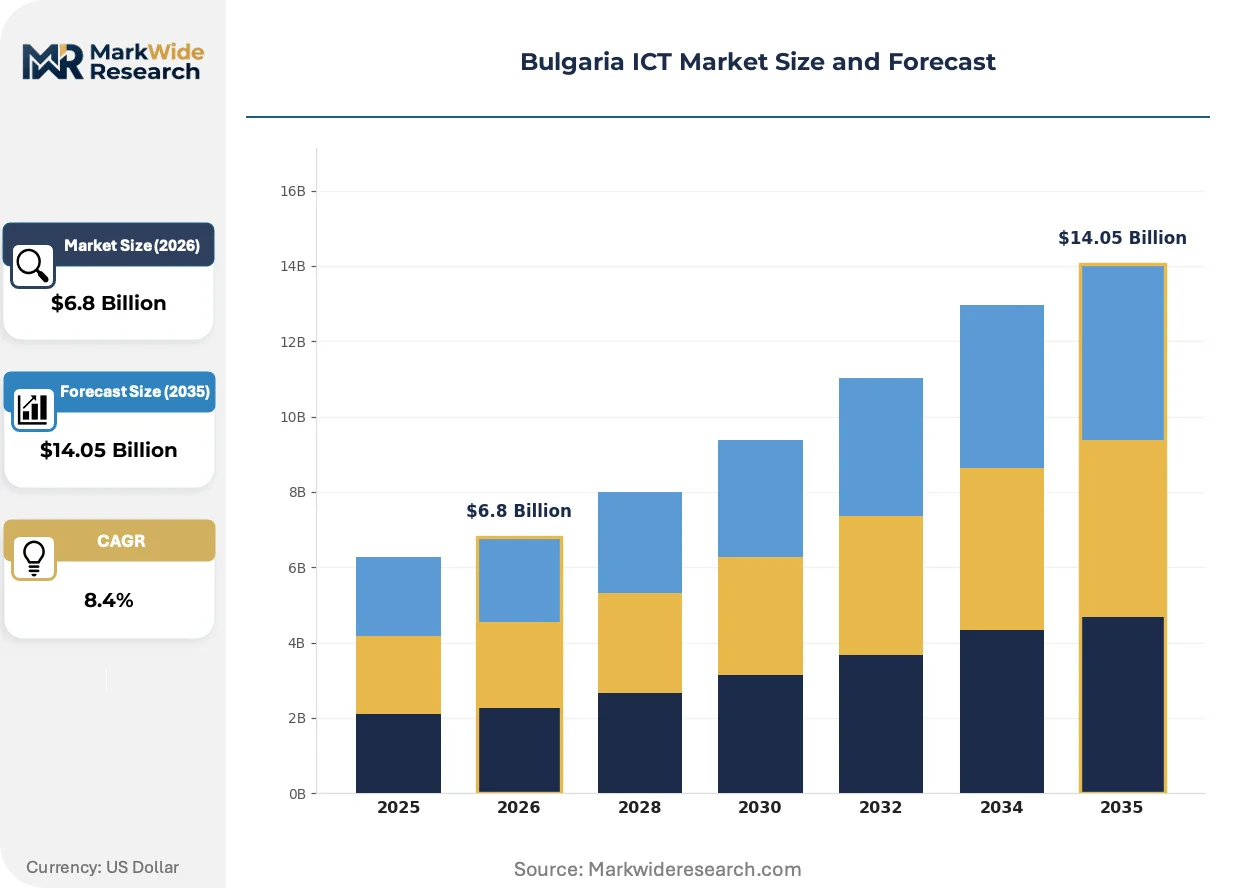
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Network Infrastructure, Cloud Services Technology: AI, IoT, Blockchain, Cybersecurity End User: Enterprise, Government, Education, Healthcare Solution: Managed Services, Professional Services, Consulting, Support |
| Companies Covered | Datecs, Sirma Group Holding, BULPROS, Chaos Group, SiteGround, VMware Bulgaria, SAP Labs Bulgaria, HP Bulgaria, Lexis Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria ICT Market Trends and Innovations
Cloud-native architectures and AI-augmented automation are displacing monolithic software deployments across Bulgarian enterprise environments, with regulatory pressure accelerating security-by-design adoption.
Zero-trust security frameworks are digitizing network perimeter definitions across Bulgarian banking and public sector organizations. The Bulgarian Commission for Personal Data Protection has intensified audit activity following GDPR enforcement templates from European counterparts. Mid-market enterprises are compressing multi-year security roadmaps into eighteen-month implementation cycles to preempt regulatory penalties.
NIS2 directive transposition into Bulgarian national law is mandating incident reporting thresholds and supply chain security obligations for critical infrastructure operators. Energy and transport sector entities face expanded governance requirements that reshape vendor contractual liability clauses. ICT providers are restructuring service agreements to accommodate mandatory breach notification timelines and third-party audit rights.
Subscription consumption models are displacing perpetual licensing across Sofia's enterprise software procurement. Chief information officers in financial services and retail verticals are consolidating vendor relationships around integrated platform suites rather than point solutions. This concentration pattern is most pronounced in banking, where API management and core system modernization budgets are merging under single-vendor strategic partnerships.
Bulgaria ICT Market Segmentation
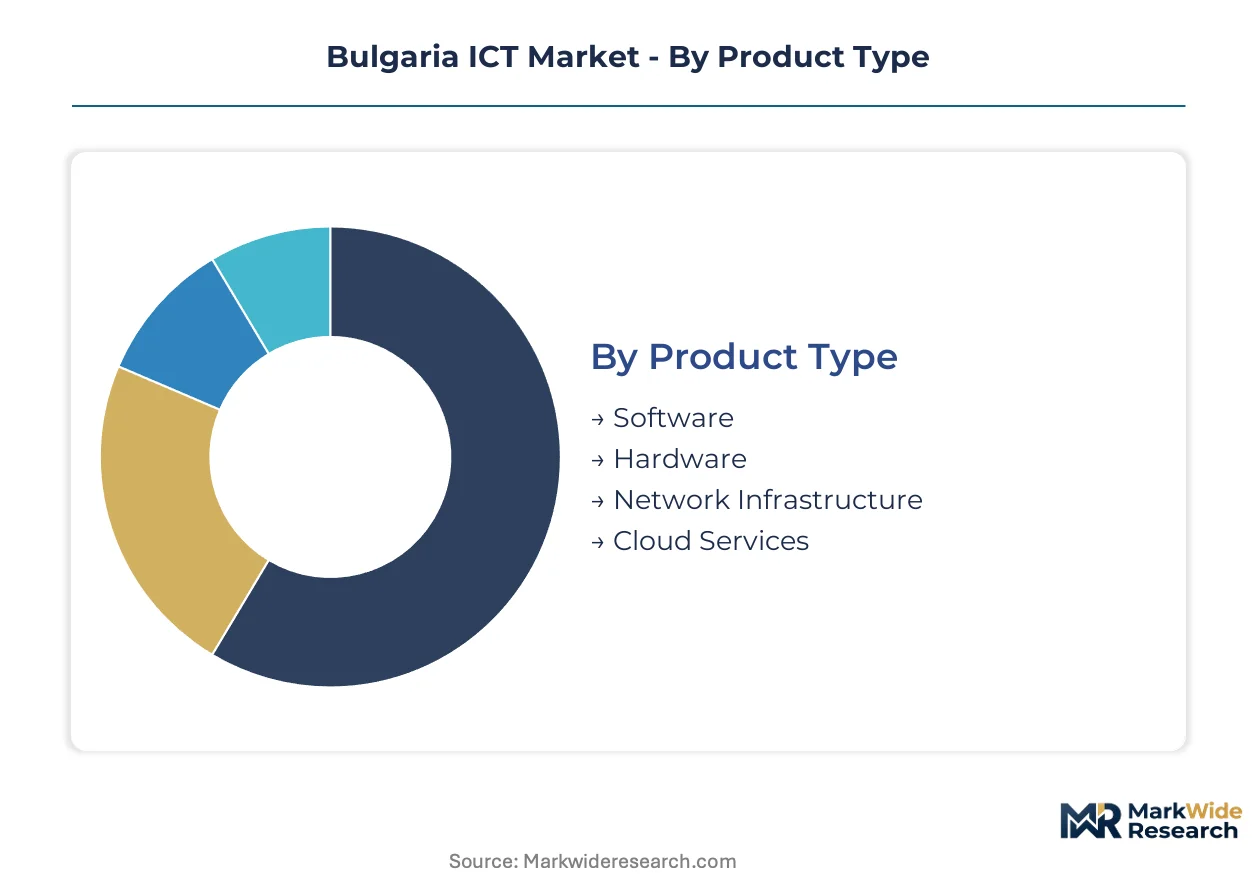
Segmentation reveals how Bulgarian ICT procurement concentrates around EU-funded public modernization and banking digitalization, with distinct technology maturity curves across Sofia's enterprise corridor and secondary city hubs. Understanding these divides exposes where vendor margins compress under open-source pressure versus where compliance mandates sustain premium pricing.
Product Type:
Use-case spectrum spans legacy hardware refresh cycles in education infrastructure through cloud-native subscription models displacing perpetual software licenses in financial services.
- Software:Enterprise resource planning and core banking platforms dominate procurement budgets. Bulgarian financial institutions drive sustained demand for API-first architectures and fraud detection modules as digital service expansion accelerates.
- Hardware:Server infrastructure and networking equipment face extended lead times from semiconductor supply constraints. Government modernization programs and educational infrastructure refreshes provide stable demand anchors despite input cost volatility.
- Network Infrastructure:Terabit fiber backbone investments link Sofia's technology corridor to Plovdiv and Varna secondary hubs.
- Cloud Services:Subscription consumption models displace capital expenditure across mid-market enterprises seeking scalable computational workloads.
Established volume favors Hardware; emerging adoption favors Cloud Services.
Technology:
Cost tier differentiation separates experimental pilot budgets from production-scale deployments, with regulatory compliance timelines determining which innovations exit proof-of-concept phases.
- AI:Algorithmic transparency requirements under EU AI Act implementation reshape deployment obligations. Bulgarian enterprises concentrate advisory and implementation service investments in preparation for mandatory enforcement phases.
- Cybersecurity:Zero-trust frameworks digitize network perimeter definitions across banking and public sector organizations. NIS2 directive transposition mandates incident reporting thresholds and supply chain security obligations that restructure vendor contractual liability clauses.
- IoT:Edge-cloud hybrid architectures address latency-sensitive industrial applications in manufacturing zones.
- Blockchain:Distributed ledger pilots remain confined to banking consortium experiments and supply chain traceability proofs.
Deployment maturity favors Cybersecurity; pilot-stage investment favors Blockchain.
End User:
Customer type determines procurement cycle length, with EU funding access compressing tender timelines for public administration versus extended vendor consolidation negotiations in enterprise verticals.
- Government:Recovery and Resilience Facility allocations channel investment into e-government infrastructure and interoperable data exchanges. Legacy COBOL and mainframe environments resist seamless API connectivity with modern cloud services, complicating modernization roadmaps.
- Enterprise:Chief information officers consolidate vendor relationships around integrated platform suites rather than point solutions. Banking verticals merge API management and core system modernization budgets under single-vendor strategic partnerships.
- Education:Infrastructure refresh cycles sustain hardware demand amid constrained operational budgets.
- Healthcare:GDPR enforcement templates from European counterparts intensify audit activity through the Bulgarian Commission for Personal Data Protection.
Funding velocity favors Government; vendor consolidation intensity favors Enterprise.
Solution:
Margin structure separates recurring revenue streams from project-based engagements, with managed services capturing expanding subscription pools as professional services face pricing pressure from low-code platform proliferation.
- Managed Services:Outsourced infrastructure monitoring and security operations centers address specialized cybersecurity skills gaps. Shortages of certified penetration testers and incident response professionals inflate salary costs, extending vendor staffing timelines for security-critical contracts.
- Professional Services:Systems integration and custom development face margin erosion from open-source software stacks and low-code platforms in mid-market segments.
- Consulting:EU AI Act preparation creates advisory revenue streams before mandatory enforcement phases.
- Support:Maintenance contracts for legacy environments sustain predictable revenue amid modernization complexity.
Recurring stability favors Managed Services; project volatility favors Professional Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Sofia's technology corridor while secondary hubs absorb cost-sensitive delivery operations. This asymmetry shapes vendor location strategies across Bulgarian sub-regions.
Sofia Capital Region
Enterprise software procurement and banking digitalization drive premium-margin engagements. GDPR enforcement through the Bulgarian Commission for Personal Data Protection intensifies compliance service demand. The Mladost business district hosts dense clustering of development centers and multinational R&D facilities.
Plovdiv
Lower operational costs attract delivery center expansion beyond capital saturation. EU Recovery and Resilience Facility allocations channel e-government infrastructure investment. The Trakia Economic Zone improves fiber connectivity to support cloud service node deployment.
Varna
Black Sea port access enables submarine cable landing points for regional data transit. NIS2 cybersecurity directive transposition mandates incident reporting thresholds for critical infrastructure operators. The Varna Free Zone concentrates outsourcing operations serving Southeast European markets.
Burgas
Industrial IoT applications in manufacturing zones generate edge-computing demand. BIS telecommunications certification processes govern equipment standards for port automation systems. The Burgas industrial park anchors logistics technology integration projects.
Ruse
Danube river crossing position supports cross-border data exchange infrastructure with Romania. CE marking compliance timelines extend hardware launch schedules for foreign equipment vendors. The Ruse technology park attracts mid-market enterprise software implementations.
Bulgaria ICT Market Competitive Landscape
Multinational development centers and domestic solution providers split the market between compliance-driven enterprise contracts and cost-optimized delivery services. Vendor concentration remains moderate, with tier-one global technology firms anchoring premium segments while regional specialists capture mid-market share. Three archetypes dominate: EU-regulatory compliance specialists, scale-oriented outsourcing operators, and vertical-focused banking solution providers. Competitive dynamics center on strategic partnerships with financial institutions and geographic expansion toward Southeast European adjacencies.
Within the domestic specialist tier, Sirma Group Holding and Datecs exemplify archetypes anchored in government and banking verticals. Sirma Group Holding occupies a position representing compliance-intensive public sector delivery, while Datecs sits within the hardware-integrated solutions segment. SAP Labs Bulgaria represents the multinational development center archetype, leveraging proximity to regional enterprise buyers. These three entities collectively illustrate how vendor positioning stratifies across regulatory complexity, scale economics, and vertical depth.
| Leading Market Players |
|---|
| Datecs |
| Sirma Group Holding |
| BULPROS |
| Chaos Group |
| SiteGround |
| VMware Bulgaria |
| SAP Labs Bulgaria |
| HP Bulgaria |
| Lexis Solutions |
| Others |
Pricing and Supply Chain Analysis
Semiconductor fabrication concentration in Taiwan and South Korea funnels margin capture toward cloud service providers and enterprise software vendors operating Bulgarian delivery centers, while hardware integrators absorb cost volatility from extended networking equipment lead times.
Pricing Analysis
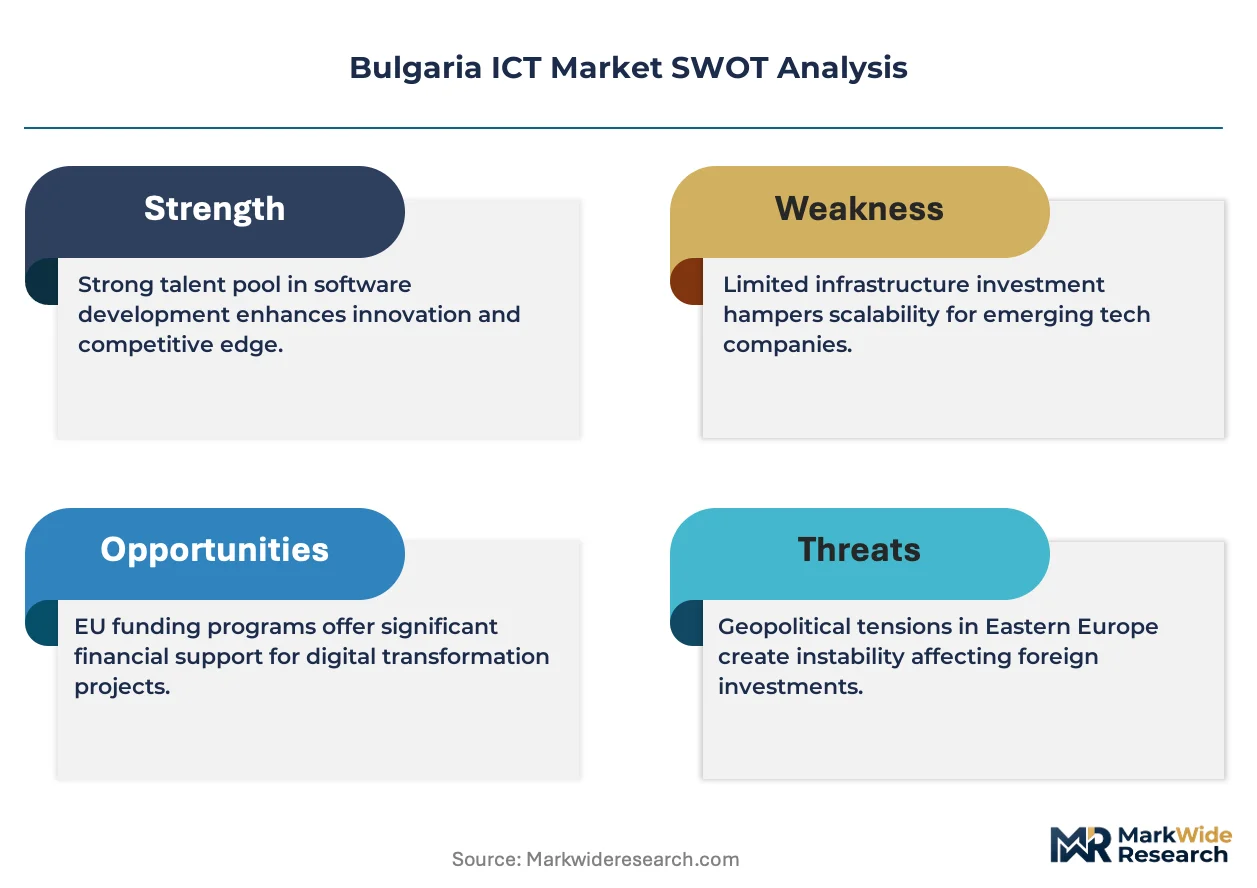
The customization-premium spread separates standard SaaS subscription tiers from configured-to-order enterprise deployments, with API-first banking platforms commanding configuration premiums over off-the-shelf modules. Price differentiation hinges on GDPR compliance certification tier and vertical integration depth in security operations. Pricing pressure stems from open-source substitution in mid-market segments. Government procurement shows lowest price sensitivity due to EU funding access, while education infrastructure buyers face acute budget constraints.
Supply Chain Analysis
EU dual-use technology export controls and US semiconductor restrictions limit advanced GPU and networking silicon flows into Bulgarian systems integration channels. Hardware sourcing draws from Taiwan, China, and Germany for server components, fiber optics, and telecommunications gear. Raw material dependencies center on rare earth processing, advanced lithography equipment, and specialized cooling systems. Single-source vulnerability concentrates in sub-7nm chip fabrication. Distribution runs through Sofia-based value-added resellers and direct multinational vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulgaria ICT traces a cyclical recovery pattern as EU Recovery and Resilience Facility disbursements channel sustained public sector modernization investment through national procurement pipelines.
For Market Incumbents: Pre-empt margin compression from low-code platforms by deepening vertical integration into managed security operations and acquiring certified penetration testing capabilities. Anchor channel control through exclusive API management partnerships with Bulgarian banking consortiums. Threat substitution from open-source ERP stacks demands defensive certification investment in EU AI Act readiness services. For New Entrants and Emerging Players: Plovdiv delivery center saturation gaps offer lower-cost talent acquisition routes outside Sofia's wage inflation zone. White-space targets concentrate in NIS2 compliance advisory for energy sector critical infrastructure operators and edge-cloud hybrid deployments in Burgas manufacturing zones. Go-to-market angle: fixed-price EU AI Act readiness assessments bundled with ongoing managed security subscriptions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional outsourcing operators holding Bulgarian government contracts but lacking cybersecurity certification depth. Long-term viability frames around EU digital sovereignty mandates sustaining compliance-service demand across a five-to-ten year window. Acquisition target archetype: vertical specialists in banking fraud detection with EU regulatory track records. Signal to watch: NIS2 enforcement penalty announcements triggering vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Positions service providers for mandatory algorithmic transparency enforcement phases across Bulgarian banking and public sectors. |
| Plovdiv Delivery Center Expansion | Captures cost arbitrage against Sofia talent saturation while maintaining fiber-connected proximity to EU markets. |
| Zero-Trust Security Platform Integration | Addresses NIS2-mandated network perimeter digitization requirements for critical infrastructure operators. |
| API-First Core Banking Modernization | Consolidates vendor relationships under single strategic partnerships as Bulgarian financial institutions merge modernization budgets. |
| Edge-Cloud Hybrid Architecture Deployment | Serves latency-sensitive industrial IoT applications in Burgas and Trakia Economic Zone manufacturing clusters. |
Research Methodology
Operator-level perspectives from Bulgarian bank CTOs, public sector procurement officers, cybersecurity practice leads, and cloud infrastructure engineers anchored the qualitative base. Primary interview insights combined with secondary validation from EU Recovery and Resilience Facility disbursement trackers, Bulgarian Commission for Personal Data Protection enforcement announcements, NIS2 transposition monitoring, and hyperscaler regional capex disclosures. Bottom-up segment sizing triangulated against top-down EU ICT expenditure benchmarks.
Scenario-bracketing framed projections across conservative, baseline, and accelerated EU funding absorption paths. Segmentation dimensions modeled include product type, technology maturity tier, end-user vertical, solution delivery model, and geographic hub concentration. CAGRs derived from elasticity-adjusted demand curves incorporating EU regulatory compliance timelines and banking digitalization capex cycles. Forecast inputs incorporated semiconductor lead time volatility indices and Sofia-Plovdiv wage differential trajectories.
Practitioners should monitor NIS2 enforcement penalty patterns, EU AI Act implementation delays, and Recovery and Resilience Facility disbursement velocity for early signals of trajectory revision. Forecasts reflect documented assumptions on EU funding continuity and regulatory compliance timeline adherence. Material shifts in EU digital sovereignty enforcement intensity or Bulgarian political commitment to e-government modernization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Quantum Computing Market