
 Information and Communications Technology (ICT) Market | 2026-2036
Information and Communications Technology (ICT) Market Size, Share, and Industry Trends Forecast 2026-2036
Information and Communications Technology (ICT) Market Insights
Southeast Asia's submarine cable and data center build-out is reconfiguring interconnection capacity for cloud service delivery. Microsoft Corporation leverages its hyperscale Azure footprint to anchor enterprise workloads across Singapore, Indonesia, and Vietnam. Huawei Technologies Co. Ltd. competes aggressively on 5G infrastructure tenders, while Amazon Web Services, Inc. extends its region-specific availability zones to capture latency-sensitive applications.
Information and Communications Technology encompasses hardware, software, and services enabling digital data transmission, processing, and storage across networked systems, operating through protocols such as TCP/IP, fiber-optic transmission standards, and virtualization layers that abstract physical compute resources. Cloud Solutions within the product type dimension now carry the largest margin pools as enterprises shift capital expenditure to operational models, while AI Solutions across the technology segment represents the fastest-expanding category as inferencing workloads multiply. Managed Services under service type classification shows structural stickiness due to multi-year outsourcing contracts and embedded operational knowledge.
The Federal Communications Commission in the United States and the Telecom Regulatory Authority of India enforce spectrum allocation and interconnection rules that directly determine market access for equipment vendors and service providers. The EU AI Act imposes conformity assessment obligations on automated decision systems, forcing ICT suppliers to embed audit trails and risk management protocols into platform architectures. Stakeholders must monitor divergence between national AI governance regimes and alignment of cross-border data flow mechanisms to preserve service scalability.
Market Dynamics
Enterprise cloud migration is compressing capital cycles and forcing infrastructure vendors to recalibrate from hardware sales toward recurring service architectures, while sovereign data localization mandates fragment previously unified procurement patterns.
Growth Catalysts
- EU AI Act:Conformity assessment obligations for automated decision systems are embedding audit capabilities into platform architectures, creating upgrade cycles across financial services and public sector deployments.
- India TRAI spectrum reforms:Accelerated 5G auctions and simplified licensing frameworks are lowering barriers for private data center investments and edge computing rollouts.
- Optical silicon photonics:Co-packaged optics in hyperscale data centers are reducing interconnect power budgets, enabling denser compute footprints for AI training clusters.
Market Restraints
- Advanced node semiconductor concentration:Taiwan and South Korea foundries control critical EUV lithography capacity, creating single-source vulnerability for high-performance networking chips.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon coolants is forcing data center operators to retrofit thermal management systems ahead of equipment replacement cycles.
- Copper and rare earth price volatility:Submarine cable and magnet supply chains face input cost pressure from mining concentration in Chile and China.
Strategic Opportunities
- Vietnam submarine cable landing points:New cable systems connecting Singapore to Hong Kong are creating neutral interconnection hubs outside traditional Tokyo-Singapore corridors.
- India PLI scheme for telecom equipment:Production-linked incentives for 5G gear are attracting component assembly and test facilities to Gujarat and Tamil Nadu.
- AI inference at the edge:Convergence of compact neural accelerators with 5G base stations is opening low-latency application stacks for industrial automation and autonomous systems.
Industry Challenges
- Photonics packaging talent scarcity:Co-packaged optics manufacturing requires precision alignment skills concentrated in Japan and Germany, creating recruitment bottlenecks for new facilities.
- Multi-cloud orchestration complexity:Enterprise IT teams struggle with workload portability across proprietary Kubernetes distributions, extending deployment timelines.
- Cross-border data flow fragmentation:Divergent adequacy rulings between EU, India, and ASEAN jurisdictions are forcing redundant infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Information and Communications Technology (ICT) Market |
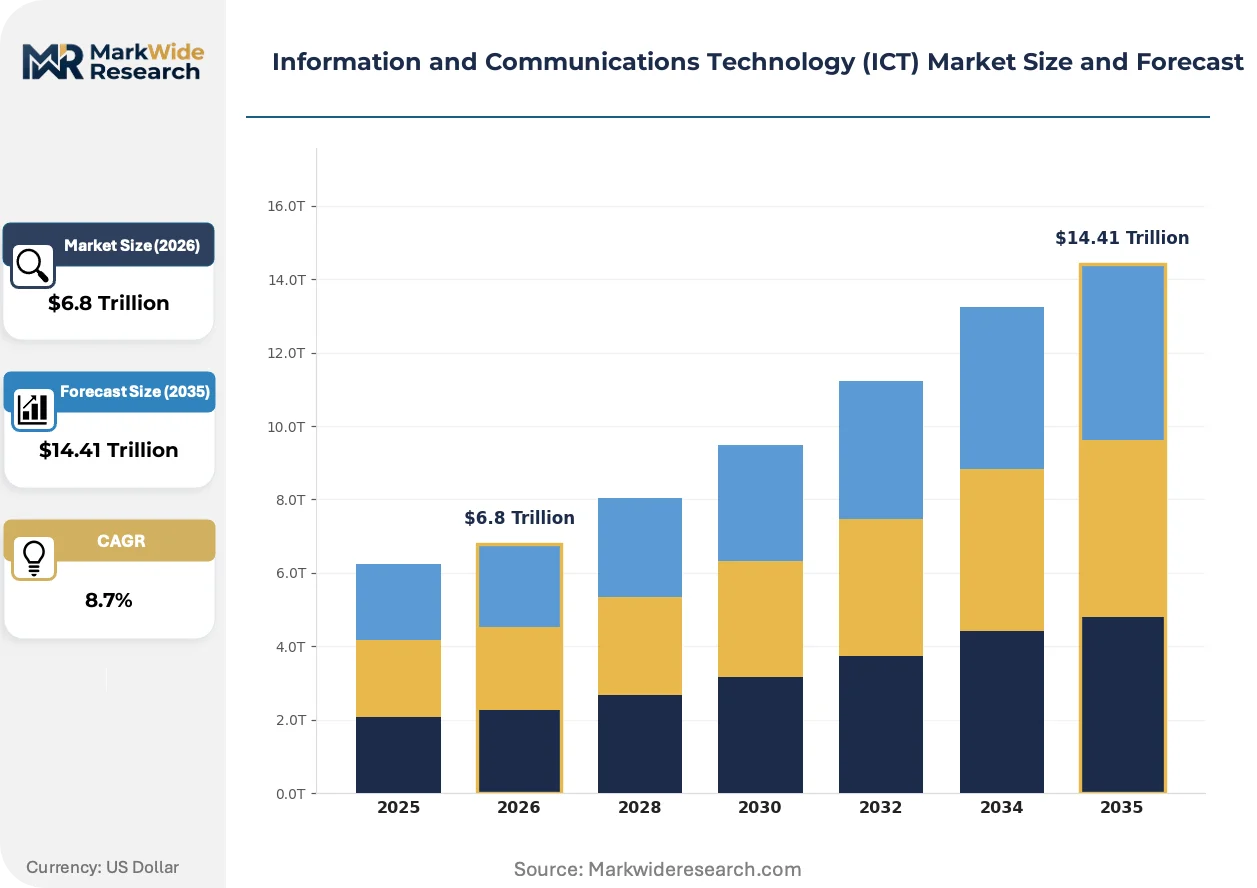
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $14.41 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Networking Equipment, Cloud Solutions, Telecommunication Services, Data Storage Technology: 5G Technology, IoT Devices, AI Solutions, Blockchain End User: Enterprises, Educational Institutions, Government Agencies, Healthcare Providers Service Type: Managed Services, Consulting Services, Technical Support, System Integration |
| Companies Covered | Microsoft Corporation, International Business Machines Corporation, Alphabet Inc., Amazon Web Services, Inc., Oracle Corporation, Cisco Systems, Inc., Accenture PLC, AT&T Inc., Huawei Technologies Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Information and Communications Technology (ICT) Market Trends and Innovations
Computational workloads are redistributing across edge, core, and cloud tiers, forcing infrastructure architectures to accommodate latency requirements that vary by application rather than geography.
Silicon photonics is hybridizing electrical and optical signal processing within single packages. Hyperscale operators in Singapore and Virginia are deploying co-packaged optics in AI training clusters to reduce energy per bit transmitted. This convergence is compressing the market for discrete transceiver modules while expanding demand for precision assembly and test services.
The EU AI Act imposes risk-tiered conformity assessments on automated decision systems deployed in credit scoring and hiring. ICT suppliers must embed technical documentation and human oversight mechanisms into platform architectures. Financial services institutions in Frankfurt and Paris are prioritizing vendors with pre-certified audit trails, creating procurement preference shifts toward established compliance infrastructure.
Consumption-based billing models are displacing perpetual licenses across enterprise software and infrastructure categories. Indian IT services firms and German automotive suppliers are negotiating usage-linked contracts that align payments with actual compute consumption rather than provisioned capacity. This shift is most visible in SaaS-delivered network management tools, where annual recurring revenue metrics are replacing upfront deployment fees as the primary commercial language.
Information and Communications Technology (ICT) Market Segmentation
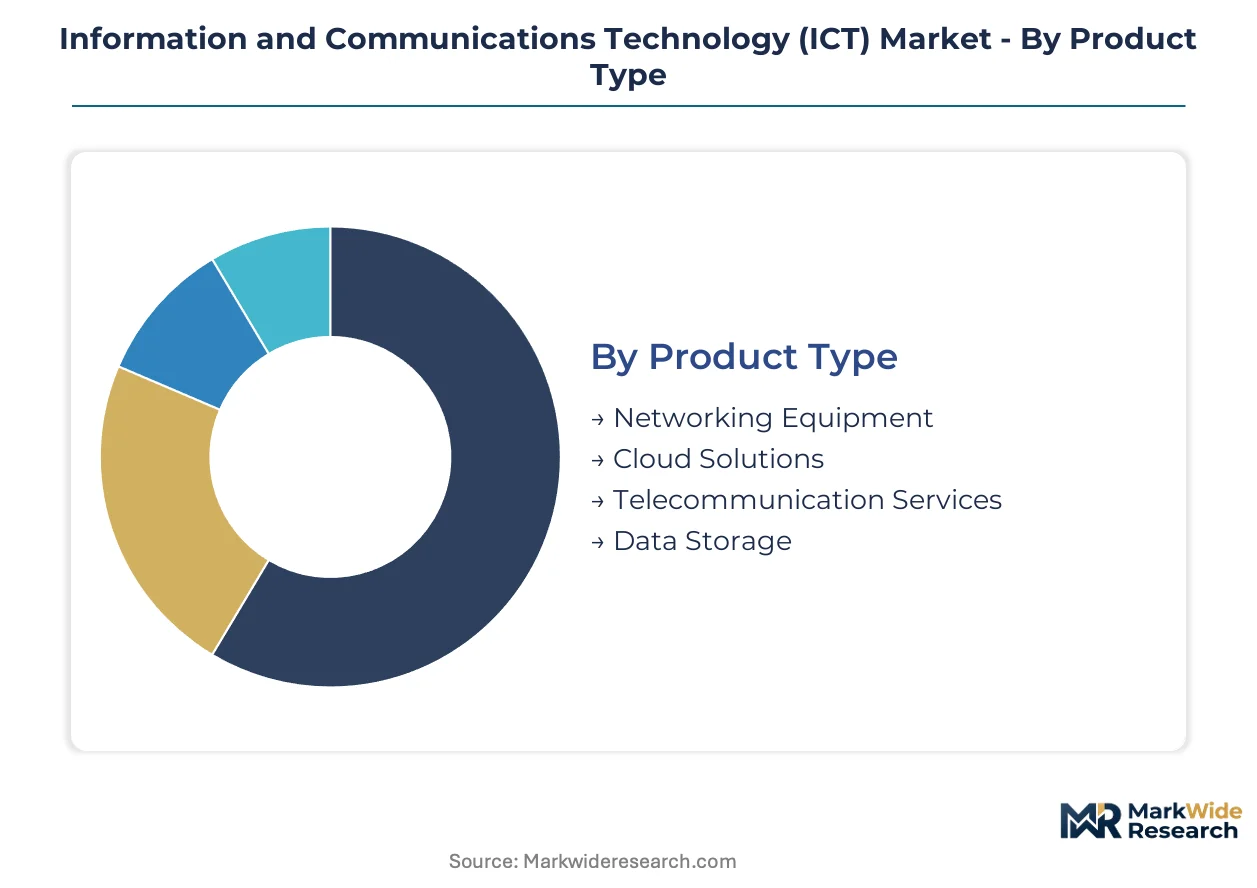
ICT procurement patterns diverge sharply across hardware, software, and service layers, with cloud economics and sovereign data requirements fragmenting traditional vendor relationships. Buyers now optimize across latency, compliance, and operational control rather than single-dimension cost metrics.
Product Type:
Cost tier stratification separates capital-intensive infrastructure from recurring service models, with procurement cycles compressing fastest at the software-defined layer.
- Networking Equipment:Physical routers, switches, and optical transport systems operating at Layer 2-3 of the OSI stack. Demand concentrates in India and Vietnam where 5G backhaul buildouts strain legacy fiber capacity. TRAI spectrum reforms accelerate private network deployments for manufacturing zones.
- Cloud Solutions:Virtualized compute, storage, and platform services delivered via subscription or consumption billing. Enterprises in Frankfurt and Singapore prioritize vendors with pre-certified EU AI Act audit trails, shifting procurement toward established compliance infrastructure.
- Telecommunication Services:Licensed spectrum-based voice and data connectivity. Mobile network operators bundle fixed wireless access for last-mile coverage in suburban India.
- Data Storage:On-premise arrays, software-defined pools, and object storage tiers. Financial services in Paris deploy air-gapped systems for regulatory retention mandates.
Networking Equipment commands the established base. The steepest expansion runs through Cloud Solutions.
Technology:
Application maturity determines deployment velocity, with production-grade implementations separating from pilot-phase technologies.
- 5G Technology:New radio interfaces and core network slicing enabling sub-10ms latency. Manufacturing clusters in Gujarat and Tamil Nadu deploy private 5G for automated guided vehicle coordination under India's PLI scheme incentives.
- AI Solutions:Machine learning training infrastructure and inference-optimized edge deployments. Credit scoring and hiring platforms in Frankfurt embed human oversight mechanisms to satisfy EU AI Act risk-tiered conformity assessments.
- IoT Devices:Sensor networks and actuators transmitting telemetry via LPWAN or cellular. Smart meter rollouts dominate utility procurement in Singapore.
- Blockchain:Distributed ledger systems for supply chain provenance and trade finance. Pilot implementations concentrate in Dubai and Hong Kong trade corridors.
5G Technology anchors current infrastructure spend. AI Solutions are gaining share fastest as inferencing workloads multiply across verticals.
End User:
Customer type dictates solution complexity, with regulated industries demanding embedded compliance versus commercial buyers prioritizing speed-to-deployment.
- Enterprises:Large corporations with dedicated IT procurement functions. Multi-cloud orchestration complexity extends deployment timelines as teams struggle with workload portability across proprietary Kubernetes distributions.
- Government Agencies:Public sector bodies with sovereign data mandates. Indian digitalization programs accelerate connectivity expansion through state-level data center investments.
- Healthcare Providers:Hospital systems and diagnostic networks. HIPAA compliance requirements shape vendor selection for US-based electronic health record platforms.
- Educational Institutions:Universities and K-12 districts. Budget constraints favor consumption-based SaaS over perpetual licenses for learning management systems.
Enterprises represent the deepest installed base. Government Agencies show the steepest budget trajectory through sovereign cloud investments.
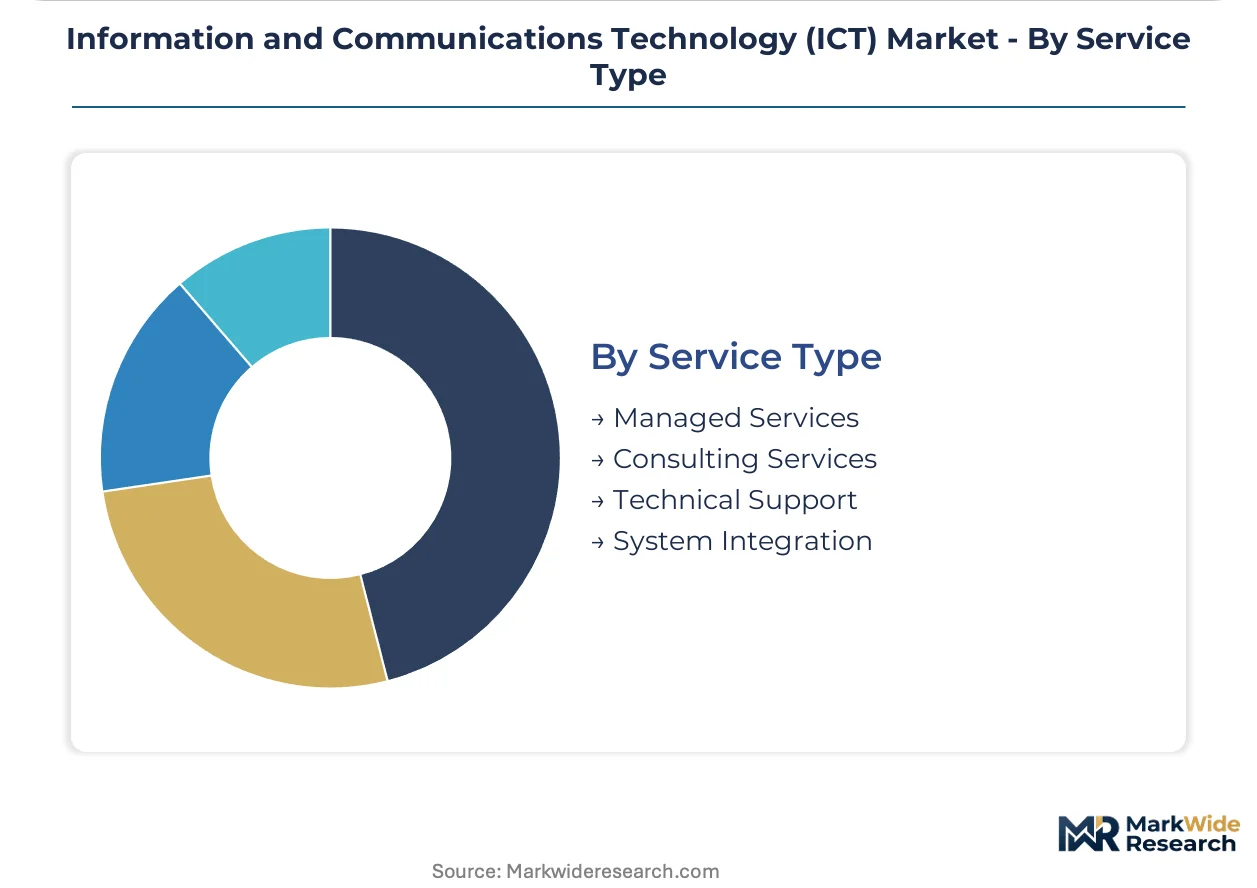
Service Type:
Margin structure separates sticky multi-year relationships from transactional engagements, with embedded operational knowledge creating switching costs.
- Managed Services:Outsourced infrastructure operation and application maintenance. Multi-year contracts with Indian IT services firms demonstrate structural stickiness due to embedded operational knowledge.
- Consulting Services:Advisory engagements for cloud migration and digital transformation. German automotive suppliers negotiate usage-linked contracts aligning payments with actual compute consumption.
- System Integration:Custom development and legacy modernization projects. Fragmented vendor ecosystems extend delivery timelines for ERP consolidation.
- Technical Support:Break-fix and tiered helpdesk operations. Annual recurring revenue metrics displace upfront deployment fees as primary commercial language.
Managed Services commands the recurring revenue base. Consulting Services are climbing the fastest as enterprises renegotiate cloud economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes ICT infrastructure through government digitalization programs and private data center investments, while Germany absorbs compliance-heavy cloud solutions shaped by the EU AI Act, and Singapore functions as an interconnection hub for submarine cable systems serving latency-sensitive workloads across Southeast Asia.
United States
Enterprise cloud migration compresses capital cycles across financial services and logistics sectors. The Federal Communications Commission enforces spectrum allocation rules that determine market access for equipment vendors. Hyperscale data centers in Virginia deploy co-packaged optics to reduce interconnect power budgets for AI training clusters.
Germany
Financial services institutions in Frankfurt prioritize vendors with pre-certified EU AI Act audit trails for credit scoring platforms. The EU F-Gas Regulation forces data center operators to retrofit thermal management systems ahead of replacement cycles. Manufacturing zones in Bavaria negotiate usage-linked contracts aligning payments with actual compute consumption.
India
Government digitalization programs accelerate connectivity expansion through state-level data center investments in Gujarat and Tamil Nadu. The Telecom Regulatory Authority of India enforces simplified licensing frameworks that lower barriers for private 5G deployments. Manufacturing clusters deploy private 5G for automated guided vehicle coordination under the PLI scheme incentives.
Singapore
Submarine cable landing points create neutral interconnection hubs outside traditional Tokyo-Singapore corridors for cloud service delivery. Smart meter rollouts dominate utility procurement for IoT sensor networks. Hyperscale operators anchor enterprise workloads across latency-sensitive applications requiring sub-10ms performance.
Japan
Precision alignment skills for co-packaged optics manufacturing concentrate in established photonics packaging facilities. The Ministry of Economy, Trade and Industry shapes industrial standards for semiconductor and networking equipment. Manufacturing expertise in precision assembly creates recruitment bottlenecks for new optical facilities.
Information and Communications Technology (ICT) Market Competitive Landscape
Capability concentration sits with hyperscale cloud operators possessing pre-certified compliance infrastructure; scale advantage sits with telecom equipment vendors commanding 5G infrastructure tenders. The market structures around three tiers: hyperscale platforms with sovereign cloud offerings, networking specialists with optical transport dominance, and IT services firms with embedded operational knowledge. Consolidation pressures favor recurring service architectures over hardware sales. Competitive moves center on geographic expansion of availability zones and vertical integration into silicon photonics.
Within the hyperscale platform tier, Microsoft Corporation and Amazon Web Services, Inc. exemplify operators extending region-specific availability zones to capture latency-sensitive applications. Huawei Technologies Co. Ltd. occupies a position among networking equipment specialists competing on 5G infrastructure tenders. These three anchors represent distinct strategic archetypes: compliance-forward cloud expansion, infrastructure-centric connectivity plays, and integrated platform-service combinations.
| Leading Market Players |
|---|
| Microsoft Corporation |
| International Business Machines Corporation |
| Alphabet Inc. |
| Amazon Web Services, Inc. |
| Oracle Corporation |
| Cisco Systems, Inc. |
| Accenture PLC |
| AT&T Inc. |
| Huawei Technologies Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Singapore-Hong Kong submarine cable corridor shapes cost dynamics across ICT infrastructure procurement, compressing margins for bandwidth-dependent services while amplifying price differentiation between latency-optimized and standard cloud tiers. Supply concentration in Taiwan and South Korea foundries feeds directly into downstream pricing power for high-performance networking silicon.
Pricing Analysis
Long-term offtake contracts dominate hyperscale data center procurement, locking in capacity for optical transport and compute infrastructure across multi-year horizons. Three-tier pricing structure across premium, standard, and economy levels separates sovereign cloud deployments with embedded compliance from commodity public cloud instances. Price differentiation hinges on certification grade against EU AI Act requirements and geographic delivery cost to edge locations. Cost compression in standard cloud tiers is intensifying because Indian IT services firms negotiate usage-linked contracts aligning payments with actual compute consumption. Government agencies demonstrate lowest price sensitivity due to sovereign mandate requirements, while educational institutions exhibit highest sensitivity favoring consumption-based SaaS over perpetual licenses.
Supply Chain Analysis
Extended payment terms from hyperscale operators strain component suppliers, forcing supply-chain finance facilities to bridge working capital gaps for optical module manufacturers. Critical EUV lithography capacity concentrates in Taiwan and South Korea, while precision photonics packaging skills cluster in Japan and Germany. Raw material dependencies span copper for submarine cables, rare earth elements for magnet assemblies, and specialized substrates for silicon photonics. Single-source vulnerability runs through advanced node semiconductor fabrication, where Taiwan foundries control critical capacity. Distribution runs through direct OEM relationships for networking equipment and channel partners for enterprise software licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale cloud operators and sovereign procurement entities, consolidating demand around vendors with pre-certified compliance infrastructure and fragmenting legacy hardware vendor relationships.
For Market Incumbents: Harden compliance infrastructure against EU AI Act audit requirements to preserve procurement preference among Frankfurt financial services institutions. Deepen captive supply of silicon photonics capacity through precision assembly investments in Japan and Germany facilities. Co-packaged optics manufacturing skills scarcity threatens margin compression for networking equipment vendors lacking in-house alignment capabilities. For New Entrants and Emerging Players: Build out neutral interconnection hubs at Vietnam submarine cable landing points outside traditional Tokyo-Singapore corridors. Target private 5G deployments for manufacturing zones in Gujarat and Tamil Nadu under India's PLI scheme incentives. Go-to-market through system integration partnerships with Indian IT services firms demonstrates lowest barrier to recurring revenue capture. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with embedded operational knowledge in managed services contracts and pre-certified sovereign cloud offerings. Long-term viability rests on recurring service architectures displacing hardware sales across the projection horizon. Acquisition target archetype: IT services firms with multi-year outsourcing relationships and compliance-forward platform capabilities. Signal to watch: divergence between national AI governance regimes forcing redundant infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion of Availability Zones | Microsoft and AWS extend region-specific zones to capture latency-sensitive applications in Singapore and Indonesia. |
| Backward Integration into Silicon Photonics | Hyperscale operators in Virginia deploy co-packaged optics to reduce interconnect power budgets for AI clusters. |
| Compliance Infrastructure Certification | Financial services in Frankfurt prioritize vendors with pre-certified EU AI Act audit trails for credit scoring platforms. |
| Strategic Partnership with Telecom Operators | Huawei competes aggressively on 5G infrastructure tenders leveraging integrated platform-service combinations. |
| Acquisition of Managed Services Specialist | Multi-year contracts with Indian IT services firms demonstrate structural stickiness due to embedded operational knowledge. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, TRAI spectrum auction records, and EU regulatory filings. Interviews with CTOs, IT procurement officers, platform engineers, and channel partners inform demand-side dynamics. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs span deployment model, organization size, vertical integration complexity, regional adoption pattern, and latency requirement tier. CAGRs derive from regression analysis against historical infrastructure investment cycles and projected enterprise cloud migration velocity. Modeled dimensions include product type stratification, technology maturity curves, end-user regulatory exposure, and service type margin structures. Sovereign data localization mandates and AI governance divergence feed into scenario-weighted projections throughout the forecast period.
Practitioners should monitor EU AI Act enforcement patterns, India PLI scheme allocation rounds, and Taiwan semiconductor capacity utilization for early signals of forecast deviation. Forecasts reflect documented assumptions about enterprise cloud migration velocity and hyperscale capex continuity. Macroeconomic contraction, regulatory fragmentation, or optical silicon photonics yield shortfalls would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Next-Generation Communication Devices Market