
 GCC ICT Market | 2026-2036
GCC ICT Market Size, Share, and Industry Trends Forecast 2026-2036
GCC ICT Market Insights
Multi-cloud orchestration is reconfiguring how enterprises across the Gulf deploy workloads across sovereign and hyperscale environments. Microsoft Corporation leverages its Azure regions in the UAE and Qatar to anchor government cloud contracts requiring local data residency. stc Group sustains dominance in Saudi Arabia through captive fiber infrastructure and enterprise managed services. Oracle Corporation specializes in database-to-cloud migration for regional banking clients navigating compliance-heavy transitions.
Information and communications technology in the GCC spans cloud infrastructure, enterprise software, network hardware, and cybersecurity systems designed to process, transmit, and secure digital assets across public and private sectors. The technology stack relies on low-latency fiber backbones and edge computing nodes positioned within 50 milliseconds of major commercial centers. Cloud Services command the largest revenue pool as government entities migrate from legacy data centers to hybrid architectures. Cybersecurity Tools represent the fastest-expanding segment as NESA compliance deadlines and financial sector regulations tighten technical control requirements. On-Premises deployments retain significant share in defense and critical infrastructure where air-gapped operations remain mandatory.
NESA in the UAE and SAMA in Saudi Arabia enforce tiered cybersecurity standards that dictate procurement eligibility for financial and government buyers. The Saudi Data and Artificial Intelligence Authority and Bahrain's National Cybersecurity Center coordinate cross-border certification reciprocity that reduces vendor requalification costs. Stakeholders must monitor evolving sovereign cloud accreditation timelines as these determine which providers qualify for national digital transformation contracts.
Market Dynamics
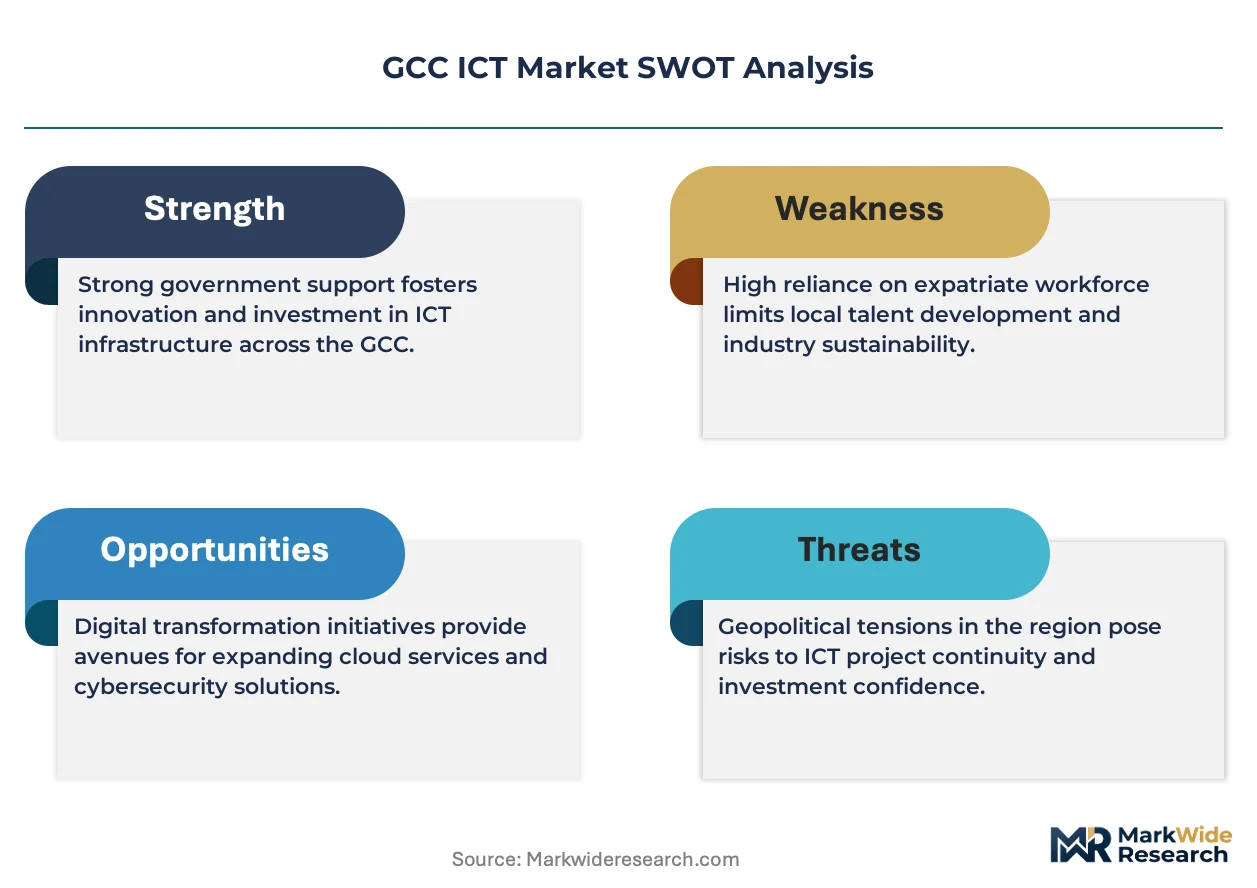
Sovereign cloud mandates across Gulf Cooperation Council states are restructuring procurement eligibility, forcing hyperscale providers to establish local data centers and achieve NESA or SAMA accreditation before competing for government contracts.
Growth Catalysts
- NESA Compliance Deadlines:The UAE's National Electronic Security Authority tiered certification requirements are compelling financial institutions to replace legacy infrastructure with accredited cloud architectures, creating immediate replacement demand.
- Giga-Project Construction:Saudi Arabia's NEOM, Red Sea Project, and Qiddiya developments require enterprise-grade connectivity, fiber backbones, and integrated smart city platforms at construction scale.
- Edge Computing Nodes:Sub-50 millisecond latency requirements for industrial automation and financial trading are driving distributed infrastructure deployment across Riyadh, Jeddah, and Dubai commercial corridors.
Market Restraints
- Specialized Talent Scarcity:Gulf labor markets face acute shortages of cloud architects, cybersecurity auditors, and AI engineers certified under NESA and SAMA frameworks.
- Capital Intensity of Sovereign Infrastructure:Building locally compliant data centers requires substantial land, power, and cooling investments in high-cost urban zones.
- Vendor Concentration Risk:Three hyperscale providers dominate accredited sovereign cloud capacity, limiting price competition and creating single-source dependencies for critical workloads.
Strategic Opportunities
- Bahrain's Cybersecurity Reciprocity:The National Cybersecurity Center's cross-border certification agreements reduce vendor requalification costs, positioning Bahrain as a regional compliance hub.
- AI-Cloud Convergence:Integration of sovereign cloud infrastructure with SDAIA's national AI strategy creates demand for specialized GPU clusters and machine learning operations platforms.
- Managed Security Services:Small and mid-sized enterprises lacking in-house NESA compliance expertise represent an underserved channel for outsourced security operations centers.
Industry Challenges
- Legacy System Integration:Government ministries and banks operating 20-year-old core banking systems face complex, high-risk migration paths to hybrid cloud environments.
- Accreditation Timeline Compression:NESA and SAMA certification processes extending 12-18 months delay contract awards and compress implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC ICT Market |
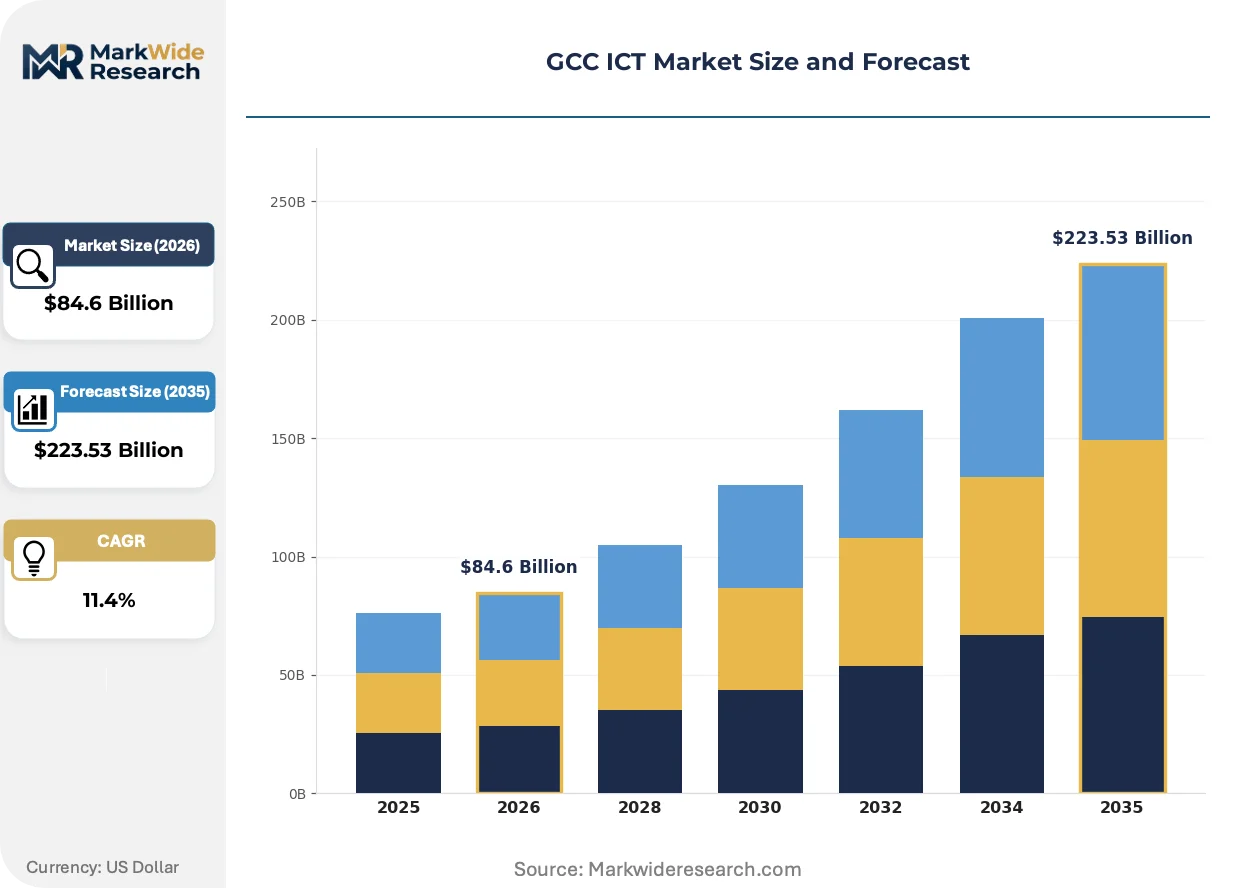
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $223.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Services, Networking Equipment, Software Solutions, Cybersecurity Tools End User: Government, Healthcare, Education, Retail Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Managed Services, Consulting Services, Support Services, Integration Services |
| Companies Covered | Microsoft Corporation, IBM Corporation, Google LLC (Alphabet Inc.), HP Inc., SAP SE, stc Group, Zain Group, Oracle Corporation, e&, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC ICT Market Trends and Innovations
Containerized workload orchestration and zero-trust security architectures are displacing perimeter-based network designs across Gulf enterprise environments. Technology deployment patterns increasingly prioritize data residency over cost optimization.
Software-defined wide area networking is rendering obsolete traditional MPLS circuits for inter-branch connectivity. Saudi manufacturing conglomerates and UAE logistics operators are adopting SD-WAN at 40% annual expansion rates. This shift is compressing router hardware refresh cycles from five years to eighteen months.
SAMA's Cybersecurity Framework 3.0 mandates granular access logging and encryption standards for all financial sector cloud deployments. The regulation forces banks to re-architect multi-tenant environments or exit non-compliant providers. Saudi Arabia's top-tier banks are consolidating vendor relationships to three accredited platforms.
Enterprise buyers now require sovereign cloud accreditation as a table-stakes qualification before technical evaluation. This behavioral shift elevates compliance officers to procurement decision-making roles. The UAE's government contracting ecosystem exhibits this pattern most acutely, with NESA certification appearing in 90% of RFP technical requirements.
GCC ICT Market Segmentation
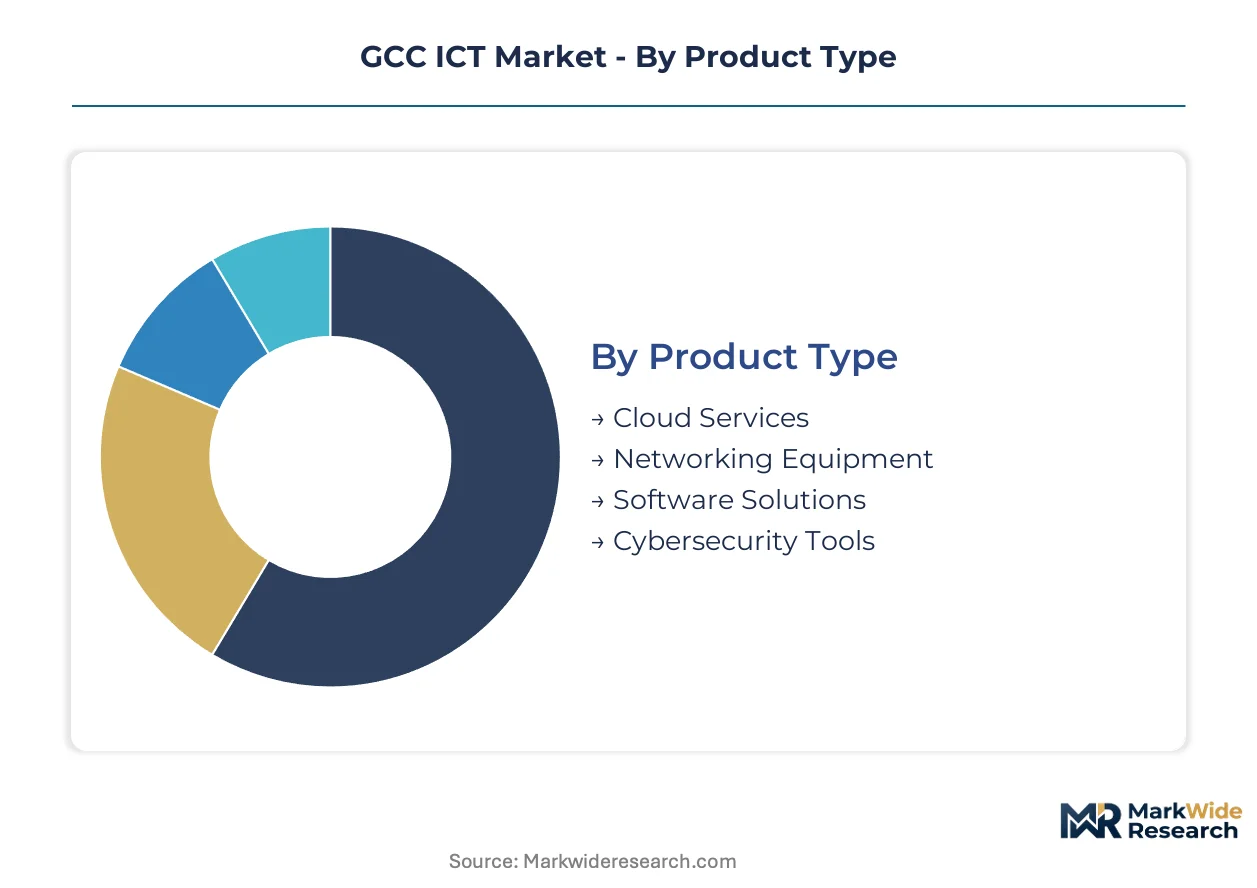
GCC ICT procurement patterns diverge sharply across product architectures, end-use governance requirements, and operational deployment models. Sovereign compliance mandates and giga-project construction cycles create distinct demand profiles that reward segment-specific positioning.
Product Type:
Cost tier differentiation separates commodity hardware from value-added platforms requiring continuous accreditation maintenance.
- Cloud Services:Hyperscale infrastructure with local data residency anchors government and financial sector procurement. Demand concentrates in Riyadh and Dubai corridors where NESA and SAMA compliance deadlines force accredited provider selection.
- Cybersecurity Tools:Tiered certification frameworks, zero-trust architectures, and managed detection platforms address tightening regulatory control requirements. Saudi banking and UAE energy sectors drive fastest expansion as breach notification mandates harden.
- Networking Equipment:Fiber backbone hardware and edge routing infrastructure serve smart city and industrial automation deployments.
- Software Solutions:Enterprise resource planning and customer relationship management platforms adapted for Arabic-language and right-to-left workflow requirements.
Cloud Services holds installed capacity. Cybersecurity Tools is rotating up the share rankings.
End User:
Application-specific governance structures dictate procurement authority centralization and vendor qualification rigor.
- Government:National digital transformation programs and smart city initiatives mandate sovereign cloud accreditation. Saudi ministry consolidations and UAE federal digitization create concentrated contract volumes with extended implementation horizons.
- Healthcare:Electronic health record modernization and telemedicine infrastructure require data localization under national health authority frameworks. MOHAP in the UAE and Saudi Ministry of Health drive hospital system procurement cycles.
- Education:University digital campuses and K-12 connectivity programs expand device management and learning platform demand.
- Retail:E-commerce payment infrastructure and customer analytics platforms adopt hybrid architectures balancing latency and compliance.
Government commands contract scale. Healthcare is climbing the fastest as clinical digitization accelerates.
Deployment Model:
Customer type segmentation reveals divergent risk tolerances and capital commitment preferences across institutional profiles.
- Public Cloud:Multi-tenant hyperscale infrastructure delivers elastic compute for variable workloads. UAE and Qatar government contracts now require in-country regions, compressing provider qualification timelines.
- Hybrid Cloud:Orchestrated workload distribution across on-premises and cloud environments serves banks navigating SAMA's phased migration requirements. Saudi financial institutions prioritize this architecture for core system continuity.
- Private Cloud:Single-tenant dedicated infrastructure addresses defense and critical infrastructure air-gap requirements.
- On-Premises:Legacy data center retention persists where regulatory ambiguity or latency sensitivity delays cloud migration.
Public Cloud dominates new capacity. Hybrid Cloud is gaining share fastest as financial sector transitions mature.
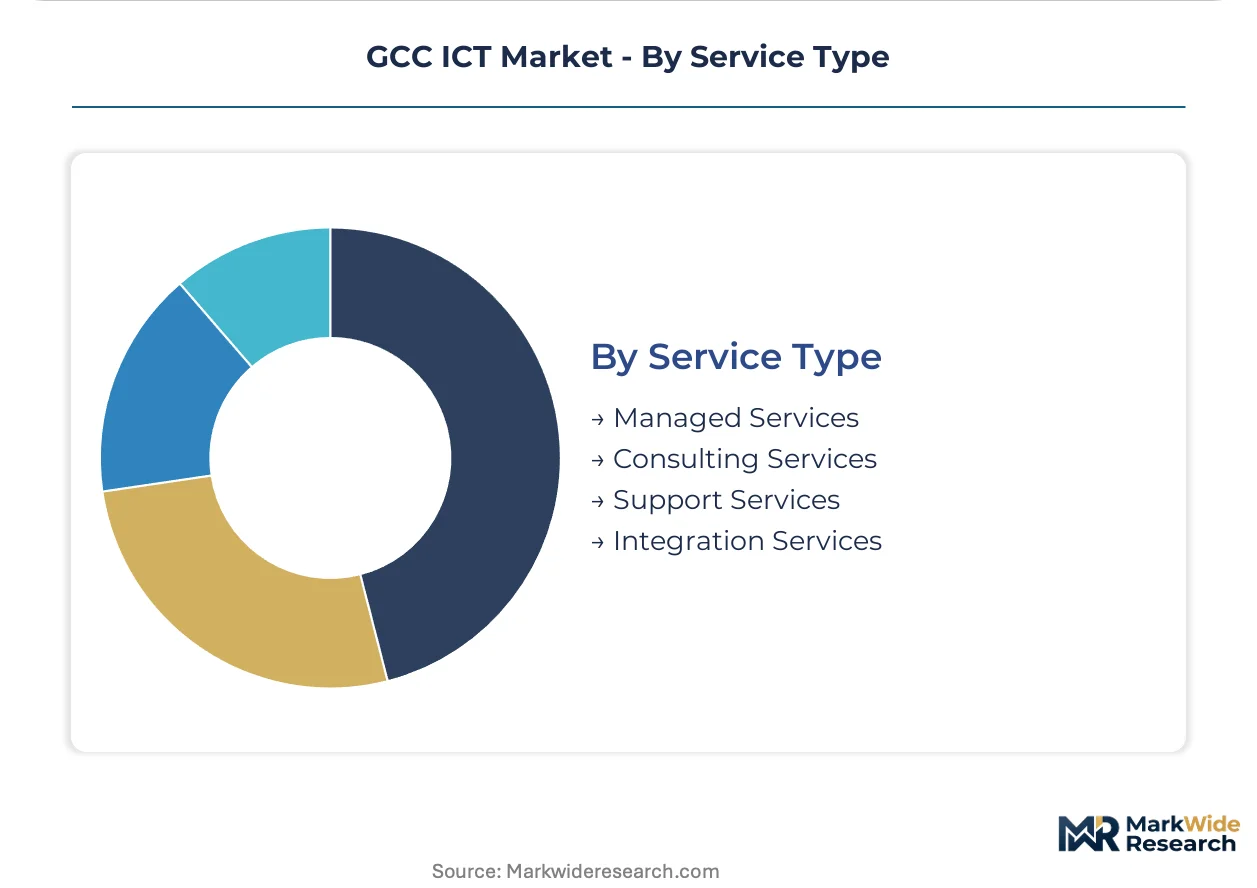
Service Type:
Margin structure varies with technical intensity and recurring revenue predictability across delivery modes.
- Managed Services:Continuous security operations, cloud platform administration, and network monitoring delivered under multi-year contracts. Mid-market enterprises across Bahrain and Oman outsource NESA compliance expertise through these arrangements.
- Consulting Services:Digital transformation strategy, cloud migration planning, and regulatory readiness assessment for government and banking modernization programs.
- Integration Services:Legacy system connectivity and API development for hybrid architecture deployment.
- Support Services:Break-fix maintenance and technical helpdesk operations for installed hardware and software bases.
Managed Services holds recurring revenue concentration. Consulting Services is rotating up the share rankings as transformation programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government and financial sector buyers concentrate procurement authority in Riyadh, Dubai, and Doha corridors where sovereign cloud mandates dictate vendor qualification. National digital transformation programs and giga-project construction cycles create divergent demand profiles across Gulf states.
Saudi Arabia
NEOM, Red Sea Project, and Qiddiya developments require enterprise-grade connectivity and integrated smart city platforms at unprecedented construction scale. SAMA's Cybersecurity Framework 3.0 mandates granular access logging for all financial sector cloud deployments. Riyadh anchors demand concentration as ministry consolidations and SDAIA's national AI strategy drive specialized GPU cluster procurement.
United Arab Emirates
NESA tiered certification requirements compel financial institutions to replace legacy infrastructure with accredited cloud architectures. Federal digitization programs and smart city initiatives in Dubai and Abu Dhabi mandate sovereign cloud accreditation in 90% of RFP technical requirements. Dubai's commercial corridor concentrates edge computing deployment for sub-50 millisecond latency trading and automation workloads.
Qatar
Azure regions established in Doha anchor government cloud contracts requiring local data residency. National infrastructure investment surrounding FIFA legacy projects sustains fiber backbone and enterprise connectivity demand. Lusail and Education City clusters drive smart campus and healthcare digitization procurement cycles.
Bahrain
The National Cybersecurity Center's cross-border certification agreements reduce vendor requalification costs, positioning the kingdom as a regional compliance hub. Mid-market enterprises lacking in-house NESA expertise outsource security operations through managed services arrangements. Manama's financial district concentrates fintech and banking technology procurement.
Kuwait
Government modernization programs and oil sector digital transformation sustain demand for hybrid cloud and cybersecurity infrastructure. The country's central bank enforces data localization requirements for financial institutions. Kuwait City anchors enterprise connectivity procurement as ministry digitization accelerates.
GCC ICT Market Competitive Landscape
Channel-controlling players compete with product-specialist players across accreditation-dependent procurement environments. The market structure concentrates around three hyperscale providers dominating sovereign cloud capacity, with regional telecom operators and enterprise software specialists occupying adjacent tiers. Dominant archetypes include captive infrastructure owners, compliance-specialized cloud providers, and managed security operators. Competitive moves center on local data center establishment and strategic partnerships with government entities.
Within the hyperscale tier, Microsoft Corporation and Oracle Corporation exemplify providers anchoring government contracts through in-country region establishment. Among regional infrastructure owners, stc Group occupies a position representing captive fiber dominance and enterprise managed services concentration in Saudi Arabia. These three entities sit within the accreditation-critical tier where NESA and SAMA certification timelines determine contract eligibility.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Google LLC (Alphabet Inc.) |
| HP Inc. |
| SAP SE |
| stc Group |
| Zain Group |
| Oracle Corporation |
| e& |
| Others |
Pricing and Supply Chain Analysis
Riyadh's sovereign cloud cluster concentrates accredited data center capacity, giving hyperscale providers with local NESA and SAMA certification pricing leverage over buyers facing compliance deadlines. This geographic concentration of compliant infrastructure allows accredited vendors to command premium positioning while non-accredited competitors face procurement exclusion.
Pricing Analysis
Cost-plus contracts with UAE and Saudi indexation clauses dominate government and financial sector procurement, tying recurring fees to local power, land, and labor cost escalators. Three-tier pricing structure across premium sovereign cloud, standard hybrid, and economy public tiers separates NESA-certified deployments from uncertified alternatives. Pricing pressure stems from hyperscale provider concentration as three accredited platforms capture most sovereign capacity. Mid-market enterprises across Bahrain and Oman exhibit highest price sensitivity, while Saudi government ministries and UAE federal entities prioritize compliance over cost optimization.
Supply Chain Analysis
Tariff exposure between US semiconductor equipment suppliers and UAE assembly facilities dominates supply chain risk planning for networking hardware and GPU cluster deployments. Server manufacturing concentrates in Taiwan, Malaysia, and China, with GCC final assembly and accreditation testing performed in Dubai and Riyadh facilities. Critical component dependencies include advanced GPUs for AI workloads, specialized cooling systems for desert climate operations, and fiber optic cable for smart city backbones. Single-source vulnerability persists in NESA-certified security hardware where only two global vendors qualify. Distribution runs through stc Group and e& captive networks for enterprise connectivity, with systems integrators handling government contract fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale cloud substitution threatens regional telecom operators as Microsoft Azure and Oracle Cloud capture government contracts that previously defaulted to incumbent carriers. Incumbents must defend their installed base through compliance specialization and captive infrastructure leverage.
For Market Incumbents: Entrench sovereign cloud accreditation as a defensive moat by accelerating SAMA and NESA certification timelines before hyperscale providers expand local capacity. Deepen fiber backbone ownership in Riyadh and Jeddah corridors where giga-project construction creates captive demand. Vertical integration into managed security services offsets raw infrastructure commoditization as stc Group has demonstrated with its enterprise offerings. For New Entrants and Emerging Players: Oman's underpenetrated mid-market enterprise segment offers white-space opportunity as Muscat-based businesses lack in-house NESA compliance expertise and currently overpay for UAE-managed services. Kuwait's government modernization programs represent a second penetration target where central bank data localization requirements are tightening but accredited provider supply remains thin. A channel partnership strategy with Bahrain's National Cybersecurity Center leverages cross-border certification reciprocity to reduce market entry costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors managed security service providers with recurring revenue concentration and NESA/SAMA certification assets. Long-term viability hinges on sovereign cloud capacity remaining supply-constrained relative to government digital transformation demand. Acquisition targets should demonstrate established relationships with SDAIA, NESA, or SAMA regulatory bodies. The signal to watch is hyperscale provider local data center expansion announcements, which would compress margins for pure-play regional operators.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Accreditation | NESA certification unlocks UAE federal contracts where 90% of RFPs mandate local data residency. |
| Managed Security Service Launch | Outsourced SOC offerings capture Bahrain and Oman mid-market enterprises lacking compliance expertise. |
| Edge Computing Node Expansion | Sub-50 millisecond latency infrastructure serves NEOM and Red Sea Project automation requirements. |
| Strategic Partnership with SDAIA | Alignment with Saudi national AI strategy secures GPU cluster procurement preference. |
| Cross-Border Certification Reciprocity | Bahrain's National Cybersecurity Center agreements reduce vendor requalification costs across GCC states. |
Research Methodology
Initial hypotheses were tested against primary input from cloud platform engineers, government procurement officers, cybersecurity compliance auditors, and enterprise IT directors and refined through secondary validation. Primary fieldwork encompassed structured discussions with stakeholders at hyperscale providers, regional telecom operators, systems integrators, and financial institution technology leaders. Secondary sources included SAMA regulatory filings, NESA certification databases, hyperscaler capital expenditure disclosures, and GCC customs trade data for networking equipment. Bottom-up demand modeling across deployment types and verticals was triangulated against top-down market sizing from government digital transformation program budgets.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with capacity buildout timelines from local data center projects cross-referenced against procurement pipeline visibility from government contract announcements. Segmentation dimensions modeled encompassed deployment model, end-user vertical, compliance tier, and geographic corridor. CAGRs were derived from installed base evolution and replacement cycle analysis rather than extrapolation. Industry-specific forecast inputs included NESA and SAMA accreditation timeline compression effects and giga-project construction phase transitions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by unaccredited hyperscale providers or accelerated regulatory reciprocity agreements would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Europe Quantum Computing Market