
 M2M Connections Market | 2026-2036
M2M Connections Market Size, Share, and Industry Trends Forecast 2026-2036
M2M Connections Market Outlook
China is fragmenting its M2M module production across Shenzhen, Shanghai, and Chengdu to reduce concentration risk in coastal electronics corridors. Huawei Technologies leverages its integrated chipset-to-cloud stack to dominate domestic 5G M2M deployments. Deutsche Telekom sustains pan-European network coverage that anchors industrial IoT contracts with German automotive suppliers. NXP Semiconductors specializes in secure-element integration for automotive M2M gateways, differentiating its hardware against commoditized cellular modules.
Machine-to-machine connections denote direct data exchange between networked devices without human intervention, typically operating over cellular, LPWAN, or short-range protocols with latency tolerances from milliseconds to minutes depending on application criticality. These links enable remote monitoring, automated control, and predictive maintenance across industrial and commercial systems. Cellular technology commands the largest revenue pool due to carrier subscription models and reliable wide-area coverage, while LPWAN segments capture the fastest volume expansion from low-power smart metering and agricultural sensor networks. Edge computing deployments are accumulating margin concentration as manufacturers demand localized data processing to reduce cloud egress costs and meet sovereignty requirements.
The FCC enforces equipment authorization and spectrum compliance that shapes which radio modules gain US market access, while ETSI and 3GPP standards govern European interoperability and security baselines for cross-border M2M traffic. China's MIIT mandates domestic encryption protocols and network access licenses that favor local module vendors in government and critical infrastructure procurement. Stakeholders must monitor evolving spectrum reallocations and cybersecurity certification timelines to avoid stranded hardware investments.
Market Dynamics
EU Cyber Resilience Act mandates now impose hardware-level security certification on all cellular modules entering European industrial automation corridors, forcing module vendors to redesign supply chains around secure-element integration.
Growth Catalysts
- Industrial automation retrofitting:German manufacturing OEMs are deploying LPWAN-enabled sensors across legacy production lines to capture real-time equipment health data without full line replacement.
- FCC equipment authorization rules:Tightened spectrum compliance baselines in the US are filtering out low-quality radio modules, creating premium positioning for certified hardware vendors.
- Automotive fleet digitization:Embedded cellular modules are scaling across commercial vehicle platforms as logistics operators demand continuous cargo visibility and predictive maintenance capabilities.
Market Restraints
- Semiconductor supply concentration:Secure-element chip fabrication concentrates among a handful of foundries, exposing module vendors to allocation constraints during demand spikes.
- Cellular subscription cost structure:Recurring carrier fees for wide-area connectivity erode margins for low-value sensor deployments in agricultural monitoring applications.
- Legacy protocol persistence:Industrial brownfield sites continue operating proprietary fieldbus systems that resist seamless integration with IP-native M2M gateways.
Strategic Opportunities
- Edge computing localization:Manufacturers are demanding on-premise data processing to reduce cloud egress costs and satisfy data sovereignty requirements under GDPR.
- India's smart metering mandate:State electricity boards are procuring LPWAN-connected meters at scale, opening volume deployment opportunities for module vendors with BIS certification.
- 5G RedCap convergence:Reduced capability 5G chipsets are bridging the gap between high-bandwidth cellular and power-constrained LPWAN for industrial video monitoring.
Industry Challenges
- Cybersecurity certification timelines:EU Cyber Resilience Act compliance testing extends hardware development cycles by 8-14 months, compressing product refresh windows.
- Multi-protocol integration complexity:Gateway vendors must simultaneously support cellular, LPWAN, and short-range protocols while maintaining deterministic latency for control applications.
- Embedded systems talent scarcity:Firmware engineering for ultra-low-power radio stacks remains concentrated among specialists with scarce expertise in both RF design and security architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | M2M Connections Market |
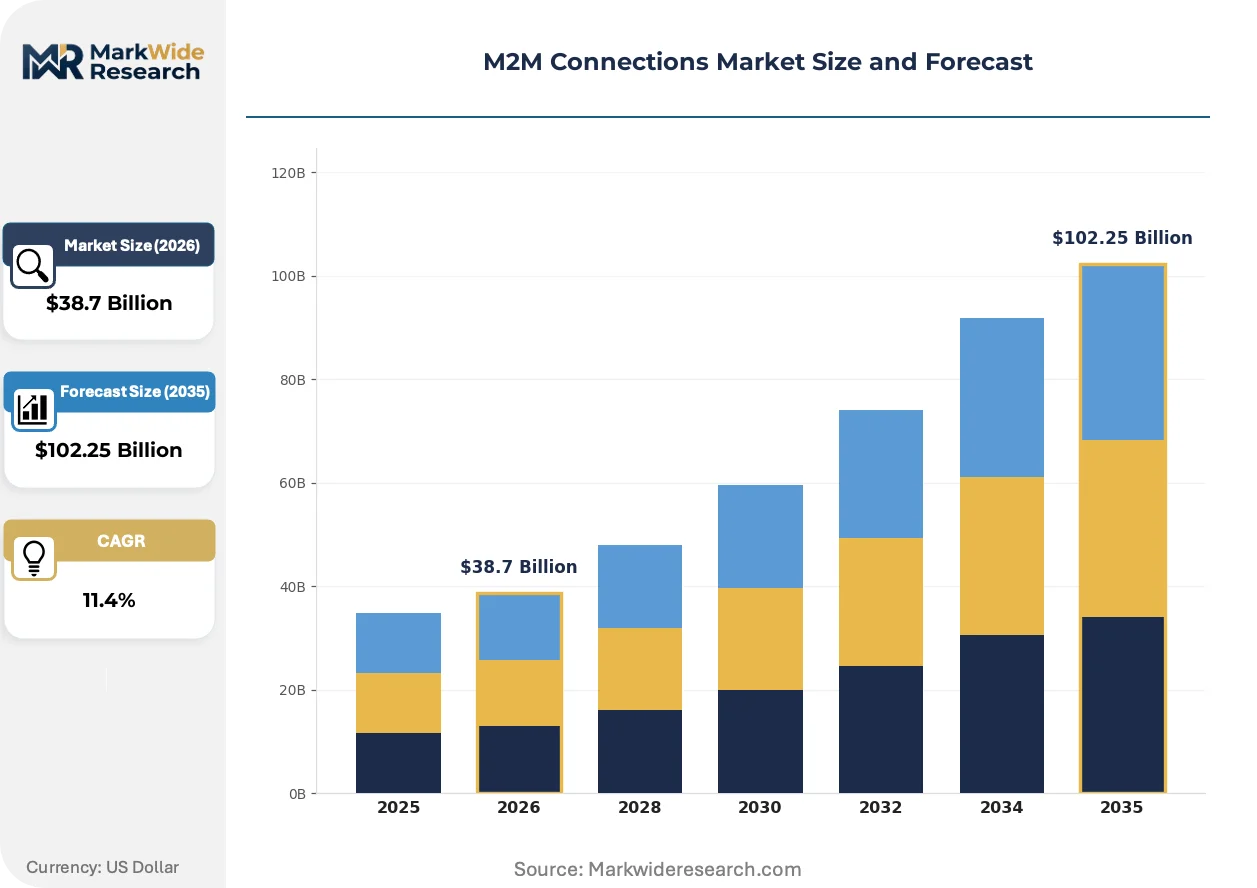
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Manufacturing, Utilities, Automotive, Healthcare Technology: LPWAN, Cellular, Wi-Fi, Bluetooth Application: Smart Metering, Asset Tracking, Telemedicine, Industrial Automation Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | AT&T, Cisco Systems, Huawei Technologies, Intel Corporation, Vodafone Group, Texas Instruments, Deutsche Telekom, NXP Semiconductors, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
M2M Connections Market Strategic Shifts
Module architecture is fragmenting along application-specific lines as edge intelligence requirements diverge between latency-critical industrial control and bandwidth-heavy video analytics.
5G RedCap is collapsing the traditional segmentation between cellular and LPWAN connectivity tiers. The technology delivers 150 Mbps peak rates with 20 MHz bandwidth and power profiles approaching LTE-M levels. German automotive suppliers are piloting RedCap modules for in-vehicle infotainment backhaul and telematics fusion. This convergence is collapsing separate procurement streams for high-bandwidth and low-power connectivity into unified hardware platforms.
ETSI EN 303 645 cybersecurity standards are mandating systematic threat modeling for consumer and industrial IoT devices sold across European member states. The framework requires manufacturers to document attack surface analysis and implement secure boot chains with hardware root of trust. Industrial M2M gateway vendors serving German automation OEMs are restructuring firmware development workflows to satisfy third-party audit requirements.
Subscription-based connectivity procurement is displacing perpetual hardware ownership models among fleet operators managing dispersed vehicle assets. Logistics providers in the US are negotiating enterprise-wide data plans with tier-one carriers rather than procuring modules and SIMs separately. This bundling concentrates purchasing power with carriers and compresses module vendors into white-label supplier roles.
M2M Connections Market Segmentation
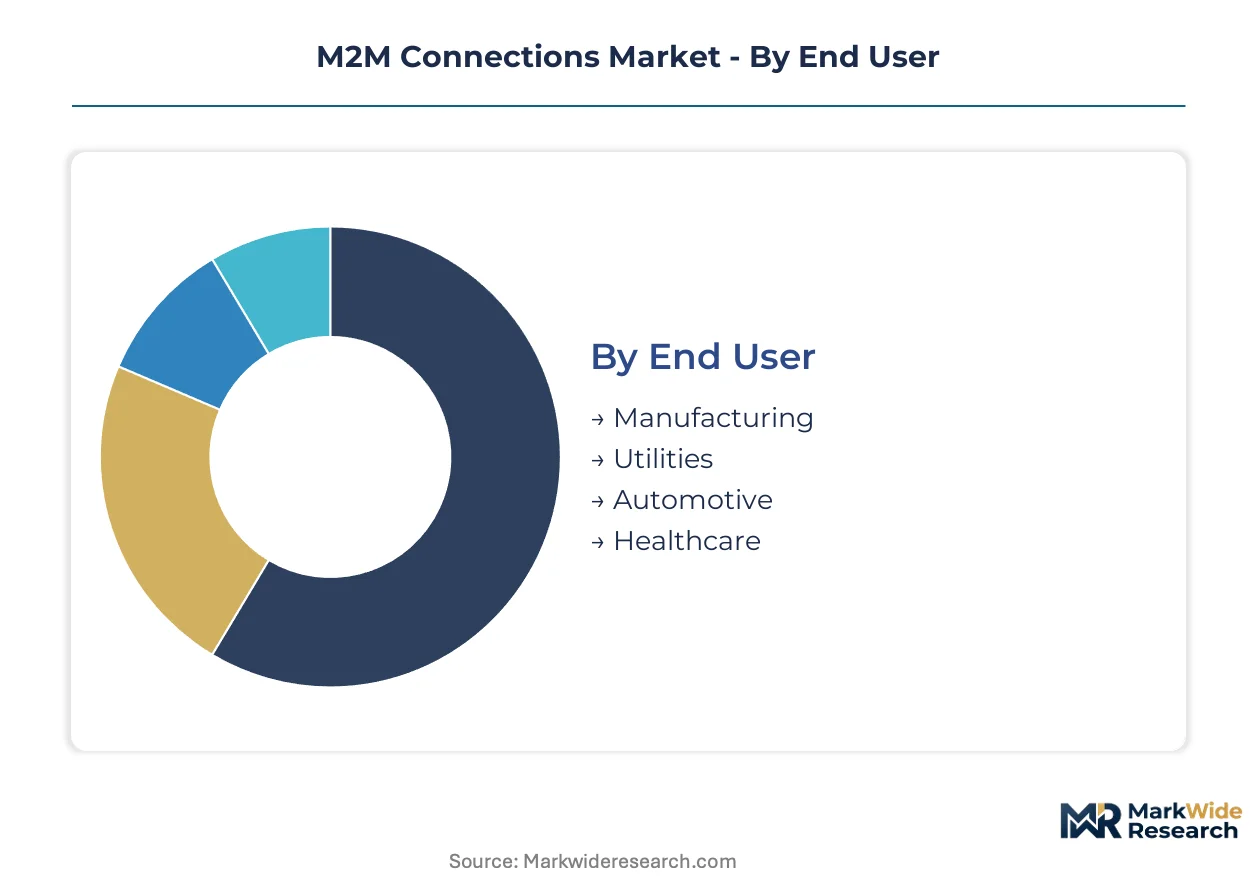
M2M connections fragment sharply across end-use requirements, with refresh cycles spanning from five-year utility meter deployments to eighteen-month automotive platform turnovers. Understanding these cadence differences shapes procurement timing and technology roadmaps for module vendors serving heterogeneous demand pools.
End User:
Automotive platforms turn over every 12-18 months, while utility infrastructure persists for 7-10 years, creating divergent R&D amortization pressures across customer segments.
- Manufacturing:Factory floor connectivity demands deterministic latency below 50 milliseconds for CNC synchronization and robotic control loops. German automotive suppliers anchor demand here, retrofitting legacy lines with LPWAN-enabled condition monitoring to avoid full capital replacement.
- Automotive:Embedded cellular modules integrate directly into vehicle telematics units, powertrain controllers, and infotainment backhaul systems. Fleet operators in commercial logistics are scaling these deployments for continuous cargo visibility and predictive maintenance across dispersed vehicle assets.
- Utilities:Smart grid infrastructure requires decade-long operational lifespans with minimal field maintenance. State electricity boards in India are procuring LPWAN-connected meters at volume, opening deployment opportunities for vendors with BIS certification.
- Healthcare:Remote patient monitoring and connected medical devices demand HIPAA-compliant data pathways with encrypted transmission. Telemedicine applications concentrate in hospital-at-home programs requiring reliable connectivity for critical vital sign streaming.
Manufacturing dominates installed base. Automotive is where expansion concentrates.
Technology:
Cost tiers separate subscription-heavy cellular stacks from capital-light unlicensed protocols, with margin structures diverging by two to three multiples across the spectrum.
- Cellular:Licensed spectrum modules command premium positioning through carrier-integrated subscription models and reliable wide-area coverage. FCC equipment authorization rules filter out low-quality radio variants, consolidating procurement around certified hardware vendors with secure-element integration.
- LPWAN:LoRa and NB-IoT protocols enable sub-dollar module economics for agricultural sensors and smart metering at the cost of bandwidth constraints. Volume expansion is climbing the fastest in this tier, driven by low-power requirements in distributed sensor networks.
- Wi-Fi:High-throughput short-range connectivity serves industrial video analytics and localized device clustering with minimal infrastructure overhead. Manufacturing OEMs deploy these for non-critical monitoring where deterministic latency is not required.
- Bluetooth:Ultra-low-power personal area networking supports wearable health monitors and proximity-based asset location within confined facilities. Healthcare deployments leverage Bluetooth Low Energy for patient-worn devices requiring multi-year battery life.
Cellular captures the largest revenue pool. LPWAN is gaining share fastest.
Application:
Customer maturity separates legacy industrial automation from emerging telemedicine deployments, with procurement sophistication varying by institutional digital readiness.
- Industrial Automation:Brownfield integration challenges dominate as proprietary fieldbus systems resist seamless migration to IP-native gateways. German manufacturing corridors are retrofitting legacy equipment with edge-enabled sensors to capture real-time equipment health data.
- Smart Metering:Regulated utility procurement cycles drive volume predictability but compress margins through competitive tendering. India's state electricity boards are mandating nationwide LPWAN meter deployment, creating certified-vendor bottlenecks.
- Asset Tracking:Fleet and cargo visibility applications demand continuous wide-area connectivity with geofencing and tamper detection capabilities. Logistics operators are negotiating enterprise-wide data plans with tier-one carriers rather than procuring modules separately.
- Telemedicine:Remote diagnostics and patient monitoring require HIPAA-compliant pathways with guaranteed uptime for critical vital streaming. Hospital-at-home programs are expanding these deployments post-acute care discharge.
Industrial Automation anchors current revenue. Asset Tracking is where expansion concentrates.
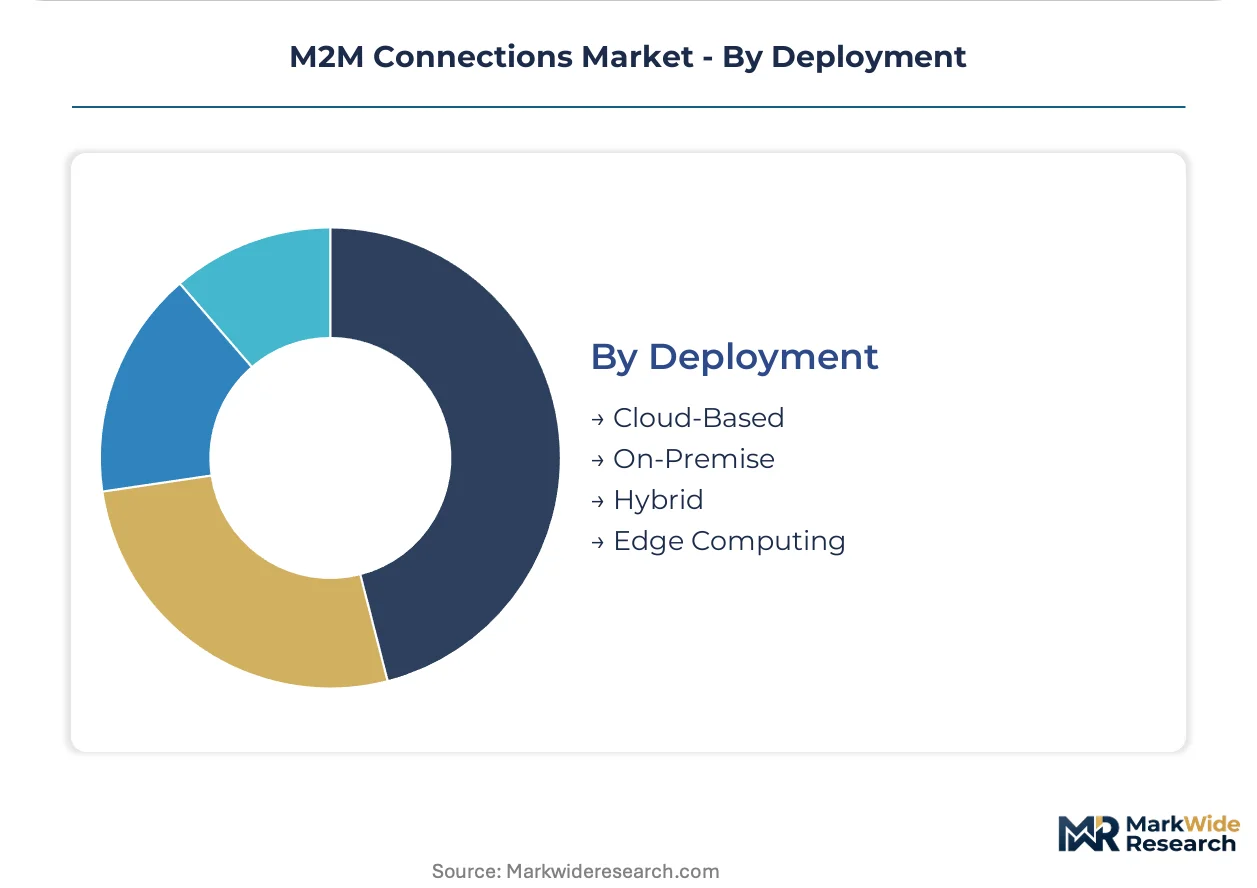
Deployment:
Volume scale favors centralized cloud architectures, while sovereignty requirements and egress cost pressures are fragmenting demand toward distributed models.
- Cloud-Based:Centralized data aggregation and analytics platforms minimize upfront infrastructure investment for smaller operators. FCC spectrum compliance and carrier integration simplify deployment for US-based fleet management applications.
- Edge Computing:On-premise processing reduces cloud egress costs and satisfies GDPR data sovereignty requirements for European manufacturing. German automation OEMs are demanding localized inference for quality control and predictive maintenance workflows.
- On-Premise:Fully isolated infrastructure serves defense, critical infrastructure, and highly regulated healthcare environments with zero external connectivity. Air-gapped deployments persist in nuclear and pharmaceutical manufacturing despite higher total cost of ownership.
- Hybrid:Tiered architectures route sensitive control traffic locally while pushing non-critical analytics to centralized cloud reservoirs. This model is expanding most quickly among mid-size manufacturers balancing sovereignty needs with capital constraints.
Cloud-Based dominates current volume. Edge Computing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module fabrication concentrates in East Asian electronics corridors, while demand clusters in German industrial zones and US logistics networks. Regulatory divergence across these geographies is fragmenting certification requirements and procurement patterns.
United States
Commercial fleet operators are scaling embedded cellular modules for cargo visibility and predictive maintenance across dispersed vehicle assets. FCC equipment authorization rules filter out low-quality radio variants, consolidating procurement around certified hardware vendors. Silicon Valley and Austin anchor module design activity, with Texas Instruments and Intel Corporation maintaining significant semiconductor presence.
Germany
Manufacturing OEMs retrofit legacy production lines with LPWAN-enabled sensors to capture real-time equipment health data without full capital replacement. EU Cyber Resilience Act mandates impose hardware-level security certification on cellular modules entering European industrial corridors. Stuttgart and Munich anchor automotive supplier demand for secure-element integration in M2M gateways.
China
Domestic 5G M2M deployments accelerate through integrated chipset-to-cloud stacks serving industrial automation and smart grid applications. MIIT mandates domestic encryption protocols and network access licenses that favor local module vendors in government procurement. Shenzhen, Shanghai, and Chengdu fragment production to reduce concentration risk in coastal electronics corridors.
India
State electricity boards procure LPWAN-connected smart meters at scale under nationwide grid modernization mandates. BIS certification requirements create vendor bottlenecks for foreign module suppliers seeking utility contracts. Bangalore and Delhi-NCR concentrate system integration activity for industrial IoT deployments.
Japan
Automotive electronics suppliers demand ultra-reliable M2M connectivity for telematics and autonomous vehicle data backhaul. METI industrial policy prioritizes domestic semiconductor supply chain resilience for critical connectivity components. Nagoya and Tokyo anchor precision manufacturing demand for deterministic low-latency machine-to-machine links.
M2M Connections Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in secure-element and radio frequency design. The vendor base stratifies between carrier-anchored connectivity providers, semiconductor fabricators with captive module lines, and pure-play hardware specialists. Three archetypes dominate: integrated chipset-to-cloud stacks, secure-element specialists, and carrier-tethered module vendors. Consolidation pressures concentrate through enterprise-wide data plan bundling and carrier direct procurement, while backward integration into secure-element fabrication represents the primary defensive maneuver.
Within the integrated platform tier, Huawei Technologies exemplifies the full-stack archetype spanning silicon through cloud orchestration. Deutsche Telekom and Vodafone Group occupy positions as carrier-anchored connectivity providers with pan-regional network coverage securing industrial IoT contracts. Among semiconductor specialists, NXP Semiconductors and Texas Instruments represent the secure-element and radio component archetypes respectively, differentiating against commoditized cellular modules through hardware-level security integration.
| Leading Market Players |
|---|
| AT&T |
| Cisco Systems |
| Huawei Technologies |
| Intel Corporation |
| Vodafone Group |
| Texas Instruments |
| Deutsche Telekom |
| NXP Semiconductors |
| Murata Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Secure-element chip fabrication concentrates in Taiwanese and South Korean foundries, anchoring margin capture downstream with module vendors who integrate hardware-level security for EU Cyber Resilience Act compliance. This upstream concentration transfers pricing power to semiconductor specialists while squeezing pure-play cellular module assemblers into white-label supplier roles.
Pricing Analysis
FCC equipment authorization rules dictate the pricing tier structure across the US market, separating certified hardware vendors from uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and secure-element integration depth. Cost compression in the economy tier intensifies because agricultural sensor deployments resist recurring carrier subscription fees. Fleet operators in commercial logistics exhibit the least price sensitivity due to enterprise-wide data plan bundling with tier-one carriers.
Supply Chain Analysis
Extended payment terms from German automotive suppliers are forcing module vendors to utilize supply-chain finance facilities for working capital management. Component sourcing draws from Taiwan, South Korea, and China for secure-element chips, RF transceivers, and baseband processors. Single-source vulnerability concentrates in secure-element fabrication, where a handful of foundries control allocation. Distribution runs through carrier-direct procurement channels and industrial automation system integrators serving German manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connectivity-as-a-service revenue layers are expanding faster than hardware unit sales as fleet operators abandon perpetual module ownership for bundled subscription models. This service-attach dynamic reorients vendor strategy toward recurring revenue capture and away from transactional hardware margins.
For Market Incumbents: Insulate margin pools by deepening backward integration into secure-element chip design and captive foundry relationships. Carrier direct procurement threatens to compress module vendors into white-label roles; defend through certification investment in EU Cyber Resilience Act compliance testing facilities. Control channel positioning by acquiring regional system integrators serving German industrial automation corridors. For New Entrants and Emerging Players: Mid-market manufacturing facilities in Eastern Europe represent the most penetrable entry point for LPWAN-enabled retrofit sensors, as German OEMs exhaust preferred vendor lists. India's state electricity boards offer volume deployment opportunities for BIS-certified LPWAN meter modules with lower competitive density than European utility procurement. Pursue partnership-based go-to-market models with established industrial automation distributors rather than carrier-direct channels. For Investors and Strategic Acquirers: Capital is best deployed toward secure-element specialists with automotive-grade certification and captive foundry access, positioned for sustained margin capture across the analysis window. Long-term viability hinges on regulatory compliance capabilities rather than commoditized module assembly. Watch for inflection in EU Cyber Resilience Act enforcement timelines, which would accelerate consolidation around certified hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Element Integration | EU Cyber Resilience Act mandates hardware-level security certification for European market access. |
| Carrier Partnership Expansion | Enterprise-wide data plan bundling concentrates procurement power with Deutsche Telekom and Vodafone Group. |
| Edge Computing Localization | German manufacturing OEMs demand on-premise processing to satisfy GDPR data sovereignty requirements. |
| 5G RedCap Module Development | Reduced capability chipsets bridge cellular and LPWAN tiers for industrial video monitoring applications. |
| India BIS Certification Investment | State electricity board procurement mandates create certified-vendor bottlenecks for foreign module suppliers. |
Study Parameters
The analysis maps cellular module, LPWAN sensor, and edge gateway sub-sectors, each validated through primary interviews with connectivity procurement officers at fleet operators, firmware engineering directors at module vendors, and industrial automation system integrators serving German manufacturing corridors. Secondary validation draws from FCC equipment authorization databases, ETSI EN 303 645 cybersecurity filings, MIIT network access license records, and carrier capex disclosures. Bottom-up unit shipment estimates triangulate against top-down connectivity service revenue reported by tier-one carriers.
Assumptions around spectrum allocation stability, regulatory certification timelines, and semiconductor foundry capacity utilization were held fixed across the modeling period, while 5G RedCap adoption curves and LPWAN protocol market share were varied through sensitivity scenarios. Segmentation dimensions include technology tier, end-use vertical, deployment architecture, and regional regulatory cluster. CAGRs derive from logistic diffusion modeling of connectivity penetration rates against equipment replacement cycles. Forecast inputs incorporate EU Cyber Resilience Act compliance testing duration estimates and India's smart metering procurement cadence.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, carrier pricing power, or foundry allocation constraints would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
5G New Radio Market