
 Global Data Quality Tool Market | 2026-2036
Global Data Quality Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Quality Tool Market Foresight
Subscription-based delivery is pivoting how data quality capabilities reach enterprise buyers. IBM Corporation leverages its hybrid cloud architecture to embed governance tools within existing data pipelines. Informatica Inc. anchors its competitive stance through extensive metadata connectivity across multi-cloud environments. SAP SE sustains dominance among installed ERP bases seeking native data quality integration.
Data quality tools encompass software platforms that profile, cleanse, match, and enrich structured and unstructured datasets through algorithmic validation rules, machine learning-based anomaly detection, and real-time monitoring dashboards. These systems serve industrial and commercial purposes by ensuring downstream analytics, regulatory reporting, and operational decision-making draw from accurate, consistent, and complete information. Cloud-based deployment is capturing the fastest growth as organizations abandon capital-intensive on-premises infrastructure for elastic consumption models. Data profiling and metadata management solution offerings command premium pricing due to their foundational role in enterprise data governance architectures. Customer data management applications attract disproportionate investment from BFSI and telecommunications end user industries confronting stringent identity verification requirements.
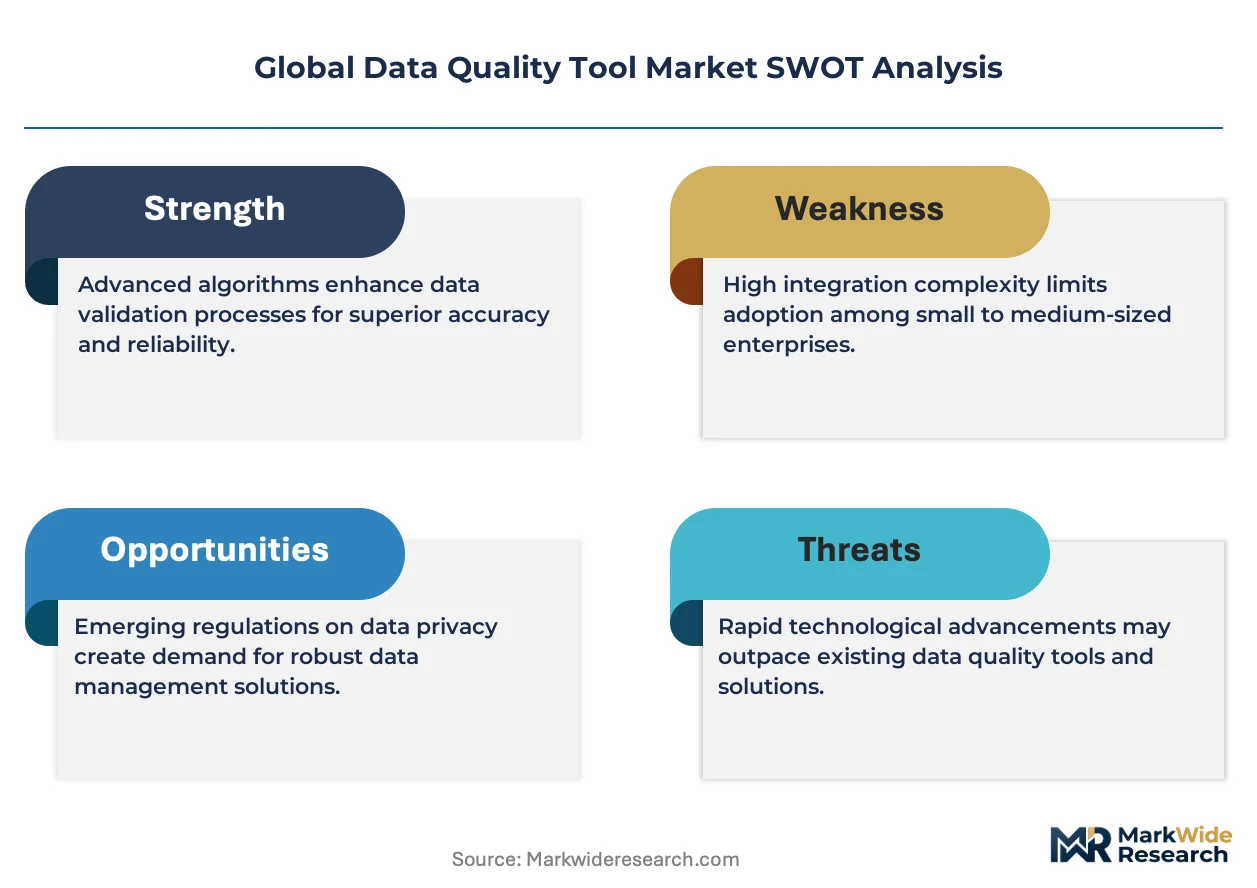
The EU AI Act and GDPR in Europe, alongside HIPAA and SEC data lineage rules in the United States, are elevating data quality from IT hygiene to board-level compliance mandate. ISO 8000 data quality standards and IEC 27001 information security frameworks further shape product certification requirements and procurement criteria across regulated sectors. Stakeholders must monitor how generative AI adoption intensifies demands for real-time data validation at unprecedented scale and velocity.
Market Dynamics
Real-time data validation requirements from generative AI deployments are compressing decision windows and forcing infrastructure rebuilds across enterprise data architectures. Organizations must now validate streaming datasets at machine-speed rather than batch intervals.
Growth Catalysts
- EU AI Act compliance mandates:Automated data governance investments accelerate as European enterprises face binding algorithmic transparency requirements.
- Financial services risk analytics:Real-time fraud detection and capital adequacy reporting demand sub-second data quality verification.
- Cloud migration velocity:Elastic consumption models displace capital-intensive on-premises deployments.
Market Restraints
- Specialized engineering talent scarcity:Machine learning operations and data engineering skill gaps constrain implementation timelines.
- Legacy system integration friction:Decades-old ERP architectures resist API-native quality tool embedding.
- Data sovereignty fragmentation:Divergent national cloud localization rules complicate multi-territory deployments.
Strategic Opportunities
- India digital infrastructure expansion:Unified Payments Interface scale and PLI scheme incentives create greenfield data quality demand.
- Healthcare interoperability mandates:HIPAA information blocking rules and TEFCA framework drive clinical data standardization tooling.
- Edge computing convergence:Distributed IoT architectures require localized validation before cloud transmission.
Industry Challenges
- ISO 8000 certification complexity:Master data quality standard implementation demands multi-year organizational transformation.
- Cross-functional alignment gaps:Data stewardship responsibilities fragment between IT, compliance, and business units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Quality Tool Market |
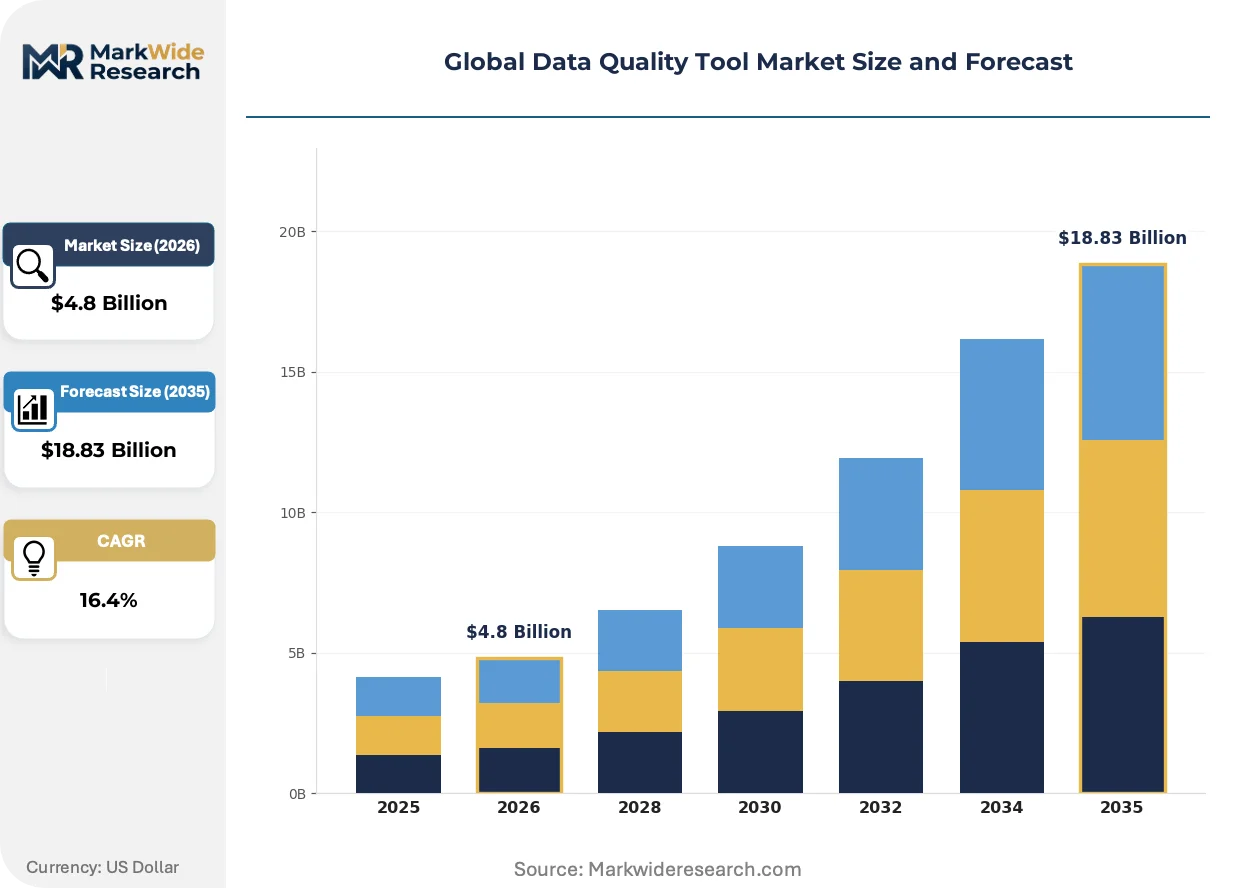
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Appliance Solution Offering: Data Profiling, Data Cleansing, Data Matching, Data Enrichment, Metadata Management Application: Customer Data Management, Risk Management, Compliance Management, Sales Analytics, Marketing Operations End User Industry: BFSI, Telecommunications, Government Agencies, Manufacturing, Education |
| Companies Covered | IBM Corporation, Informatica Inc., SAP SE, Oracle Corporation, Talend Inc., SAS Institute Inc., Precisely, Ataccama, Alteryx Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Quality Tool Market Shifts & Advancements
Algorithmic validation methods are displacing rule-based approaches as primary quality enforcement mechanisms. The shift reflects computational cost reductions and pattern recognition capabilities that static logic cannot match.
Machine learning-based anomaly detection is rewriting how enterprises identify data corruption. Pharmaceutical manufacturers deploying predictive quality models reduce batch rejection rates before production completion. This capability compresses remediation cycles from weeks to hours.
The EU AI Act risk classification framework imposes documentation burdens on high-stakes algorithmic systems. Healthcare and financial services enterprises must maintain complete data lineage for audit defense. German automotive suppliers and French insurance groups are restructuring governance committees to satisfy conformity assessment requirements.
Consumption-based pricing models displace perpetual licenses in enterprise procurement. Subscription elasticity aligns vendor revenue with customer value realization. United States federal contractors and United Kingdom public sector bodies now mandate usage-based terms in RFP evaluations.
Global Data Quality Tool Market Segmentation
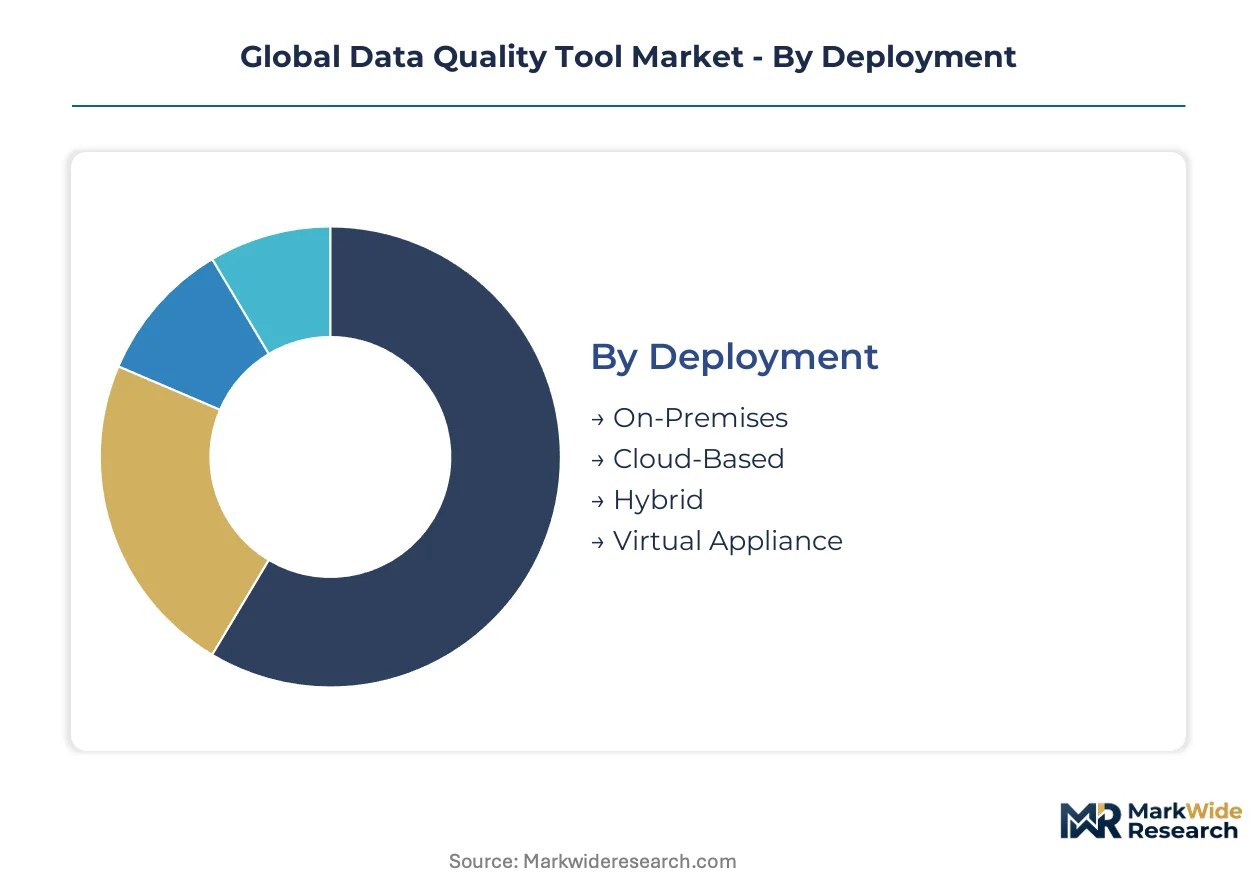
Data quality tool procurement decisions map directly to infrastructure maturity, regulatory exposure, and data velocity requirements. Buyers segment investments by deployment constraints, solution criticality, and industry-specific compliance thresholds.
Deployment:
ISO 27001 certification burdens fall heaviest on cloud and hybrid configurations requiring multi-tenant security attestations. On-premises deployments face lighter documentation loads but heavier capital approval cycles.
- On-Premises:Hardware-resident installations within enterprise data centers demand dedicated infrastructure teams. German automotive manufacturers and Japanese industrial conglomerates retain these configurations for IP-sensitive engineering datasets subject to strict data residency rules.
- Cloud-Based:Elastic consumption through SaaS platforms eliminates capital expenditure. United States healthcare systems migrating electronic health records to cloud environments drive disproportionate demand as HIPAA security rule interpretations evolve.
- Hybrid:Split architectures place sensitive master data on-premises while streaming analytics workloads to public cloud. Financial services firms in Singapore and Switzerland deploy hybrid models to satisfy both SEC disclosure timelines and local banking secrecy frameworks.
- Virtual Appliance:Pre-configured software images deploy within private cloud environments without hardware procurement. Mid-market enterprises in Australia and Canada favor this route for rapid GDPR compliance without full cloud migration.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Solution Offering:
Pricing tiers correlate with technical depth—metadata management and data profiling command premium positioning against commoditized cleansing utilities.
- Data Profiling:Automated statistical analysis of dataset structures, formats, and content distributions. Pharmaceutical manufacturers in Ireland and Switzerland deploy profiling tools to satisfy EMA pharmacovigilance data quality standards before regulatory submission.
- Data Cleansing:Algorithmic correction of inconsistencies, duplicates, and null values through pattern matching and reference data validation. Retail banking operations in Brazil and Mexico concentrate cleansing investments on customer address standardization for credit risk models.
- Data Matching:Probabilistic and deterministic record linkage across disparate sources. National identity programs in India and South Korea drive matching tool procurement for deduplicated citizen registries.
- Data Enrichment:Third-party attribute appending to augment sparse internal records. Telemarketing operations in the United Kingdom and Australia purchase enrichment services to comply with opt-in consent verification requirements.
- Metadata Management:Business glossary maintenance, lineage tracking, and impact analysis for enterprise data catalogs. EU AI Act documentation mandates are accelerating metadata investments at French insurance groups and German automotive suppliers.
Widest margin capture: Metadata Management. Steepest expansion trajectory: Data Profiling.
Application:
Functional use cases determine integration complexity and stakeholder involvement breadth.
- Customer Data Management:Unified profile construction across touchpoints for identity resolution and preference management. Telecommunications operators in Spain and Italy prioritize CDM tooling to satisfy GDPR data portability requests.
- Risk Management:Real-time validation of counterparty exposures and fraud indicators. Capital markets participants in New York and London demand sub-second data quality verification for Basel III liquidity reporting.
- Compliance Management:Audit trail maintenance, retention policy enforcement, and regulatory report generation. Healthcare providers in California and Texas invest here to defend against HIPAA information blocking investigations.
- Sales Analytics:Pipeline hygiene and forecast accuracy through opportunity data standardization. B2B software vendors in Israel and Estonia deploy these tools to correct CRM entropy degrading quarterly projections.
- Marketing Operations:Campaign audience hygiene and attribution data integrity. Consumer packaged goods companies in the Netherlands and Sweden concentrate spending on consent management integration for email marketing compliance.
Highest average contract value: Risk Management. Gaining share fastest: Compliance Management.
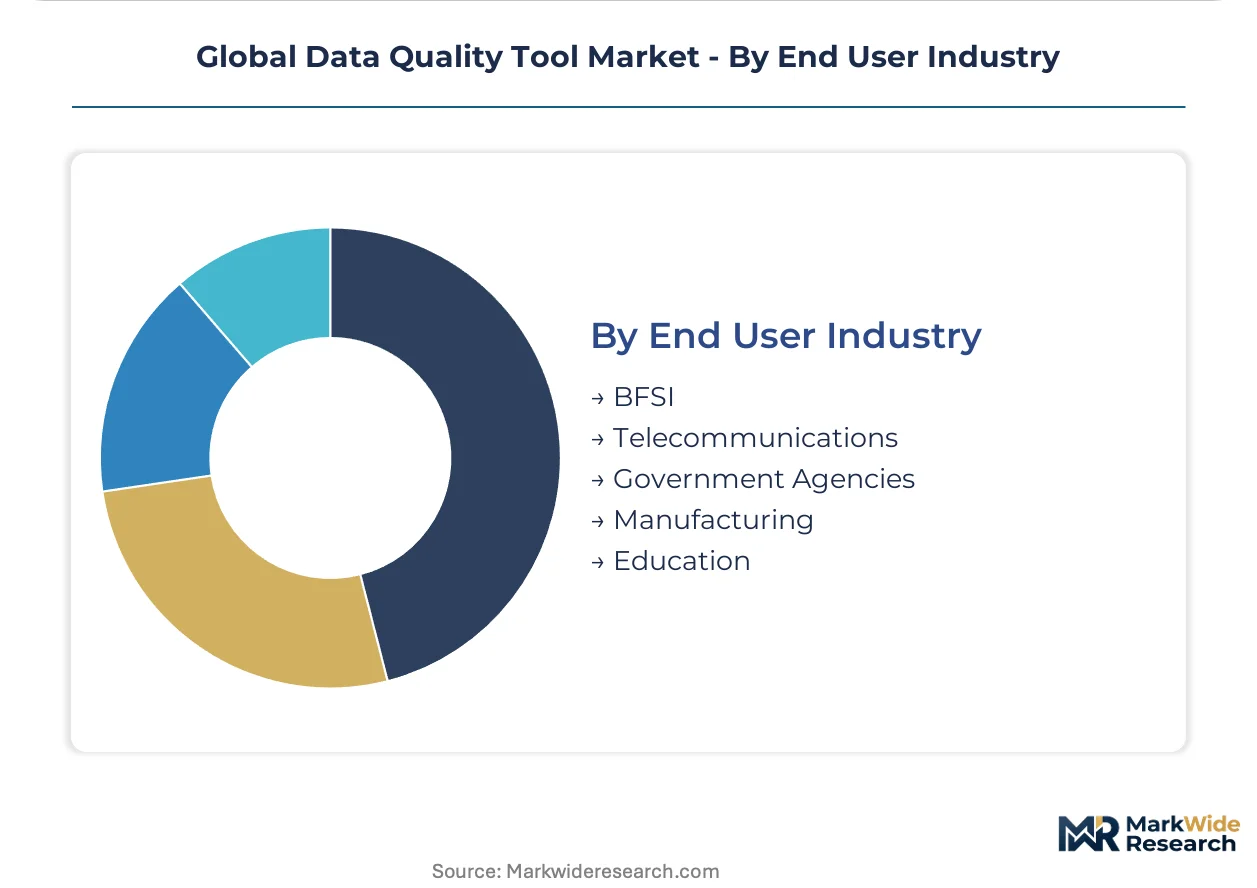
End User Industry:
Vertical-specific data velocity and regulatory density shape solution packaging requirements.
- BFSI:Trading book reconciliation, anti-money laundering screening, and stress testing data preparation. Investment banks in Singapore and asset managers in Luxembourg drive real-time validation requirements.
- Telecommunications:Subscriber identity verification, network performance telemetry, and billing accuracy. Mobile operators in Nigeria and Kenya prioritize data quality for mobile money interoperability.
- Government Agencies:Tax registry integrity, benefits eligibility verification, and open data publication standards. National statistical offices in Canada and Australia lead procurement for census and labor survey modernization.
- Manufacturing:Supplier master data harmonization, IoT sensor calibration, and product lifecycle traceability. Aerospace suppliers in France and medical device manufacturers in Massachusetts invest for FDA and EMA audit readiness.
- Education:Student information system consolidation, research data management, and alumni record maintenance. University systems in California and England deploy quality tools for federal reporting and fundraising optimization.
Deepest installed base: BFSI. Expanding most quickly: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors enterprise data quality investment as cloud migration and AI readiness initiatives concentrate spending among San Francisco Bay Area technology buyers. Financial services firms in New York and London accelerate platform adoption for real-time risk analytics. Regulatory fragmentation across jurisdictions reshapes deployment architectures.
United States
Healthcare systems migrating electronic health records to cloud environments drive disproportionate demand as HIPAA security rule interpretations evolve. SEC data lineage rules elevate data quality from IT hygiene to board-level compliance mandate. Capital markets participants in New York demand sub-second data quality verification for Basel III liquidity reporting.
Germany
Automotive manufacturers retain on-premises configurations for IP-sensitive engineering datasets subject to strict data residency rules. EU AI Act documentation mandates accelerate metadata investments at automotive suppliers restructuring governance committees. Stuttgart and Munich industrial clusters lead procurement for supplier master data harmonization and product lifecycle traceability.
United Kingdom
Telemarketing operations purchase enrichment services to comply with opt-in consent verification requirements. Public sector bodies mandate usage-based terms in RFP evaluations for procurement flexibility. London financial services firms deploy hybrid models to satisfy both SEC disclosure timelines and local banking secrecy frameworks.
India
Unified Payments Interface scale and PLI scheme incentives create greenfield data quality demand across digital infrastructure expansion. National identity programs drive matching tool procurement for deduplicated citizen registries. Bangalore and Hyderabad technology corridors concentrate cloud-based deployment adoption among mid-market enterprises.
Singapore
Financial services firms deploy hybrid models to satisfy both SEC disclosure timelines and local banking secrecy frameworks. Real-time fraud detection investments demand sub-second data quality verification for trading book reconciliation. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria across ASEAN banking networks.
Global Data Quality Tool Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as infrastructure ownership separates legacy platform vendors from cloud-native entrants. The vendor base organizes around three tiers: established enterprise software conglomerates with installed ERP bases, pure-play data management specialists with multi-cloud connectivity, and emerging AI-native challengers with algorithmic validation capabilities. Dominant competitive moves include strategic partnerships for hybrid cloud embedding and portfolio diversification into metadata management solutions.
Within the enterprise conglomerate tier, IBM Corporation and SAP SE exemplify archetypes leveraging hybrid cloud architecture and native ERP integration respectively. Informatica Inc. occupies a position among pure-play specialists anchoring competitive stance through extensive metadata connectivity. These three entities represent distinct strategic postures: infrastructure embedding, application-native delivery, and cloud-agnostic connectivity.
| Leading Market Players |
|---|
| IBM Corporation |
| Informatica Inc. |
| SAP SE |
| Oracle Corporation |
| Talend Inc. |
| SAS Institute Inc. |
| Precisely |
| Ataccama |
| Alteryx Inc. |
| Others |
Supply & Pricing Matrix
Horizontal integration into cloud infrastructure partnerships anchors supply positioning and pricing power for data quality platform vendors. SAP SE and Oracle Corporation leverage captive ERP installed bases to bundle governance tools at premium attach rates, while pure-play specialists compete through elastic consumption models that trade margin for market penetration.
Pricing Analysis
Margin tightening in cloud-based tiers reflects hyperscaler compute cost pass-through and subscription renewal compression. Three-tier pricing structure across premium, standard, and economy levels separates metadata management solutions from commoditized cleansing utilities. ISO 27001 certification premiums command price differentiation against uncertified alternatives. Buyer price sensitivity concentrates among mid-market enterprises in India and Southeast Asia, while financial services firms in the United States and Singapore exhibit lowest elasticity due to regulatory compliance mandates.
Supply Chain Analysis
Compute infrastructure supply rests on United States hyperscaler dominance, Indian engineering talent pools, and German precision manufacturing for on-premises hardware components. Cloud-native data quality platforms draw from AWS, Azure, and GCP compute instances as primary inputs, alongside open-source machine learning frameworks and proprietary algorithm libraries. Single-source vulnerability in GPU acceleration chips for AI-powered anomaly detection creates supply risk. Distribution runs through direct enterprise sales organizations, hyperscaler marketplaces, and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data quality tool market functions as a vertical-integration race where platform vendors pursue downstream control over customer data pipelines and upstream capture of specialized ML engineering talent.
For Market Incumbents: Cement hybrid cloud embedding through strategic partnerships with hyperscaler marketplaces to defend against AI-native challengers with algorithmic validation capabilities. Deepen metadata management portfolio breadth to capture EU AI Act documentation spending at German automotive suppliers and French insurance groups. Prioritize ISO 8000 certification investment to maintain procurement eligibility across regulated BFSI and healthcare verticals. For New Entrants and Emerging Players: Edge computing convergence for IoT data validation presents a technology-first wedge into manufacturing and telecommunications verticals where legacy vendors lack distributed architecture capabilities. Target greenfield demand from Indian digital infrastructure expansion and Unified Payments Interface scale where established vendor relationships remain unformed. Pursue consumption-based pricing transparency as the primary go-to-market angle against incumbent perpetual license incumbency. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by enterprise software conglomerates seeking data governance capabilities to complete cloud transformation portfolios. Long-term viability hinges on sustained R&D investment in real-time streaming validation architectures as generative AI deployments compress decision windows. Watch for inflection signals in healthcare interoperability mandate enforcement velocity across United States HIPAA information blocking investigations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Hybrid cloud embedding through hyperscaler marketplaces captures elastic consumption demand from United States healthcare systems. |
| Acquisition of Specialist Firm | Metadata management capability purchases satisfy EU AI Act documentation mandates at German automotive suppliers. |
| Geographic Expansion | India digital infrastructure presence leverages PLI scheme incentives and Unified Payments Interface scale for greenfield customer acquisition. |
| Strategic Partnership | Systems integrator alliances accelerate enterprise deployment timelines constrained by ML engineering talent scarcity. |
| Product Launch | Edge computing validation tools address distributed IoT architectures requiring localized quality verification before cloud transmission. |
Research Methodology
Independent corroboration across CTO interviews, IT procurement officer surveys, and platform engineer discussions underwrites the qualitative findings in this study. Primary fieldwork engaged data governance leads at financial services firms, compliance officers at healthcare systems, and integration specialists at systems integrators across the United States, Germany, United Kingdom, India, and Singapore. Secondary validation drew from SEC filings of publicly traded enterprise software vendors, hyperscaler capex disclosures, and EU regulatory documentation. Bottom-up segment sizing and top-down market triangulation reconciled demand estimates across deployment models and solution offerings.
The forecast window anchors to historical adoption patterns in cloud migration and AI readiness initiatives, extending through the projection horizon. Segmentation modeling incorporated deployment architecture, organization size, vertical industry, integration complexity, and regional regulatory density. CAGRs derive from trend extrapolation adjusted for technology substitution effects and compliance mandate acceleration. Industry-specific inputs include real-time validation latency requirements from generative AI deployments and ISO 8000 certification penetration rates across regulated sectors.
Several conditions sit outside the modeled scope, including unforeseen regulatory reinterpretations, macroeconomic disruptions to enterprise software spending, and breakthrough advances in autonomous data quality systems. Forecasts reflect documented assumptions about technology adoption curves and vendor competitive dynamics. A small set of named triggers warrants ongoing watch, specifically EU AI Act enforcement severity and healthcare interoperability mandate implementation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Digital Signage Market
Digital Solutions
Molecular Information Systems Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
AI In Packaging Design Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Thin Client Market
Digital Solutions
UAE ICT Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
System Integrator Market
Digital Solutions
Morocco ICT Market