
 Global Cloud High-Performance Computing Market | 2026-2036
Global Cloud High-Performance Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud High-Performance Computing Market Foresight
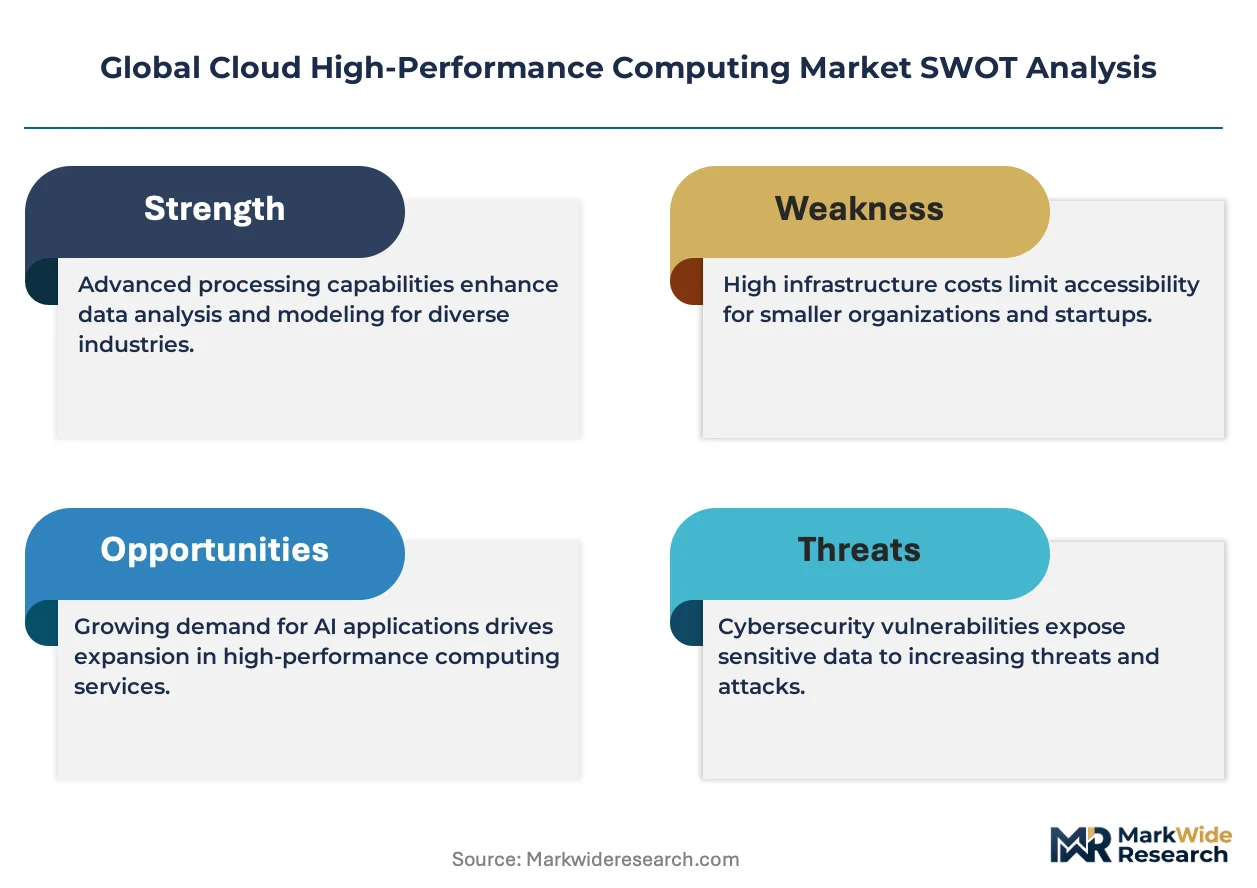
Containerized orchestration of GPU clusters is reconfiguring how cloud HPC resources are provisioned and scaled across distributed environments. NVIDIA Corporation dominates specialized AI training infrastructure through its DGX Cloud platform and CUDA software ecosystem. Microsoft Azure leverages its partnership with OpenAI to anchor enterprise demand for large-model training workloads. Amazon Web Services sustains market presence through Elastic Fabric Adapter networking and Graviton-based cost optimization for traditional HPC simulation jobs.
Cloud high-performance computing delivers scalable access to parallel processing architectures, interconnect fabrics with sub-microsecond latency, and accelerators such as GPUs and TPUs for computationally intensive workloads. The primary purpose spans climate modeling, genomic sequencing, financial risk simulation, and generative AI training where on-premise capital expenditure proves prohibitive. Hybrid Cloud deployments capture the fastest expansion as enterprises retain sensitive data on private infrastructure while bursting peak workloads to public capacity. Infrastructure-as-a-Service holds the deepest margin pool due to bare-metal server provisioning and high-bandwidth networking attach rates. Artificial Intelligence application demand is displacing traditional simulation as the primary workload driver across major provider platforms.
The EU AI Act and GDPR impose data residency and algorithmic transparency requirements that shape European cloud HPC procurement decisions. The US NIST Cybersecurity Framework and FedRAMP authorization gate federal agency adoption of cloud-based supercomputing resources. China's GB standards and MIIT cloud service regulations restrict cross-border data flows for domestic research institutions. Stakeholders must monitor divergence between sovereign AI infrastructure mandates and the technical economies of centralized hyperscale platforms.
Market Dynamics
Containerized orchestration of GPU clusters is compressing provisioning cycles from weeks to hours, forcing traditional on-premise supercomputing centers to restructure capital deployment models or risk workload migration to elastic cloud infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for high-risk AI systems are pushing pharmaceutical and automotive R&D departments toward cloud HPC providers with pre-certified GDPR-compliant infrastructure in Frankfurt and Amsterdam.
- Generative AI training workloads:Large language model development by enterprise AI labs is consuming petaflop-scale compute resources that on-premise facilities cannot provision cost-effectively.
- Molecular simulation demand:Drug discovery pipelines in Basel, Boston, and Singapore are offloading protein folding calculations to GPU-accelerated cloud instances.
Market Restraints
- Data residency restrictions:China's MIIT cloud service regulations and GB standards block cross-border data flows for domestic research institutions, fragmenting global workload portability.
- Specialized talent scarcity:Expertise in InfiniBand networking and CUDA optimization concentrates in Silicon Valley and Taipei, creating recruitment bottlenecks for European cloud operators.
- Energy cost volatility:Electricity pricing spikes in Ireland and Norway are eroding the cost advantage of Nordic data centers for sustained HPC workloads.
Strategic Opportunities
- Sovereign cloud infrastructure:France's ANSM and Germany's KBA are mandating domestic data processing for sensitive automotive simulation data, creating demand for national cloud HPC deployments.
- Quantum-classical hybrid workloads:Integration of quantum processing units with conventional GPU clusters is opening new application spaces in cryptography and materials science.
- India's PLI scheme incentives:Domestic semiconductor design firms in Bengaluru and Hyderabad are eligible for production-linked subsidies when utilizing local cloud HPC resources.
Industry Challenges
- FedRAMP authorization timelines:US federal agencies require 12-18 month certification cycles for cloud-based supercomputing resources, delaying contract awards.
- Legacy MPI code migration:Decades-old Fortran simulation codes require manual refactoring for containerized cloud environments, consuming specialized engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud High-Performance Computing Market |
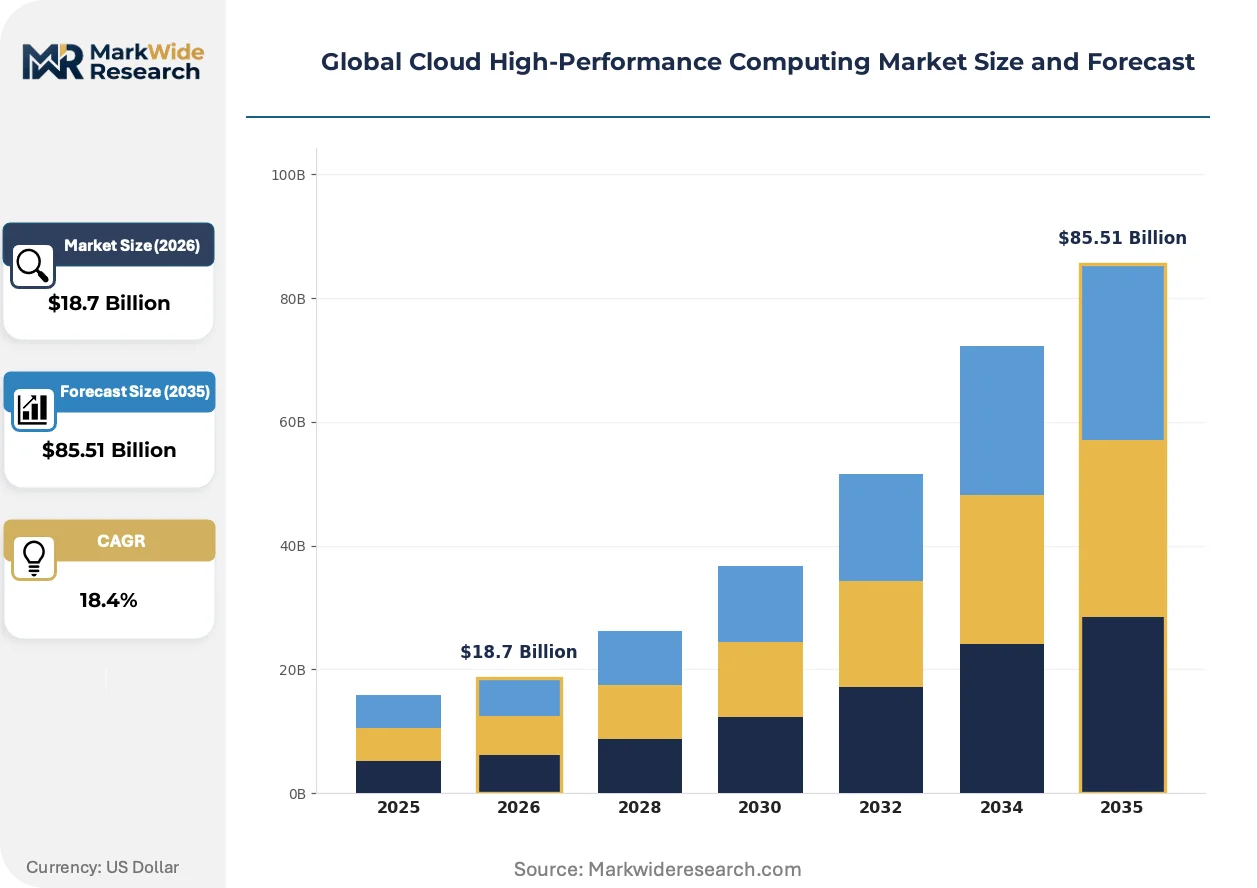
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, Managed Services End User: Academic Institutions, Research Organizations, Enterprises, Government Bodies Application: Data Analytics, Simulation, Rendering, Artificial Intelligence |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Corporation, Hewlett Packard Enterprise, Dell Technologies, NVIDIA Corporation, Intel Corporation, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud High-Performance Computing Market Shifts & Advancements
Software-defined interconnect fabrics are decoupling network topology from physical hardware, enabling dynamic reconfiguration of HPC clusters in response to workload characteristics without rack-level intervention.
Serverless GPU scheduling is digitizing how research teams access compute resources. University laboratories and mid-sized biotech firms in Cambridge and San Diego are adopting on-demand kernel execution models. This architecture is digitizing cost structures by eliminating idle capacity charges and compressing budget approval cycles from annual to project-based.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for high-performance computing outputs used in automated decision systems. German automotive OEMs and Dutch financial institutions must now document training data provenance and model explainability. Cloud providers operating Frankfurt and Amsterdam data centers are responding with integrated compliance tooling and audit-ready logging pipelines.
Consumption-based pricing models are displacing reserved instance contracts in enterprise procurement. Research consortia in Switzerland and Japan are negotiating spot-market access for non-critical simulation batches. This shift is most visible in climate modeling and genomic sequencing verticals where workload predictability remains low.
Global Cloud High-Performance Computing Market Segmentation
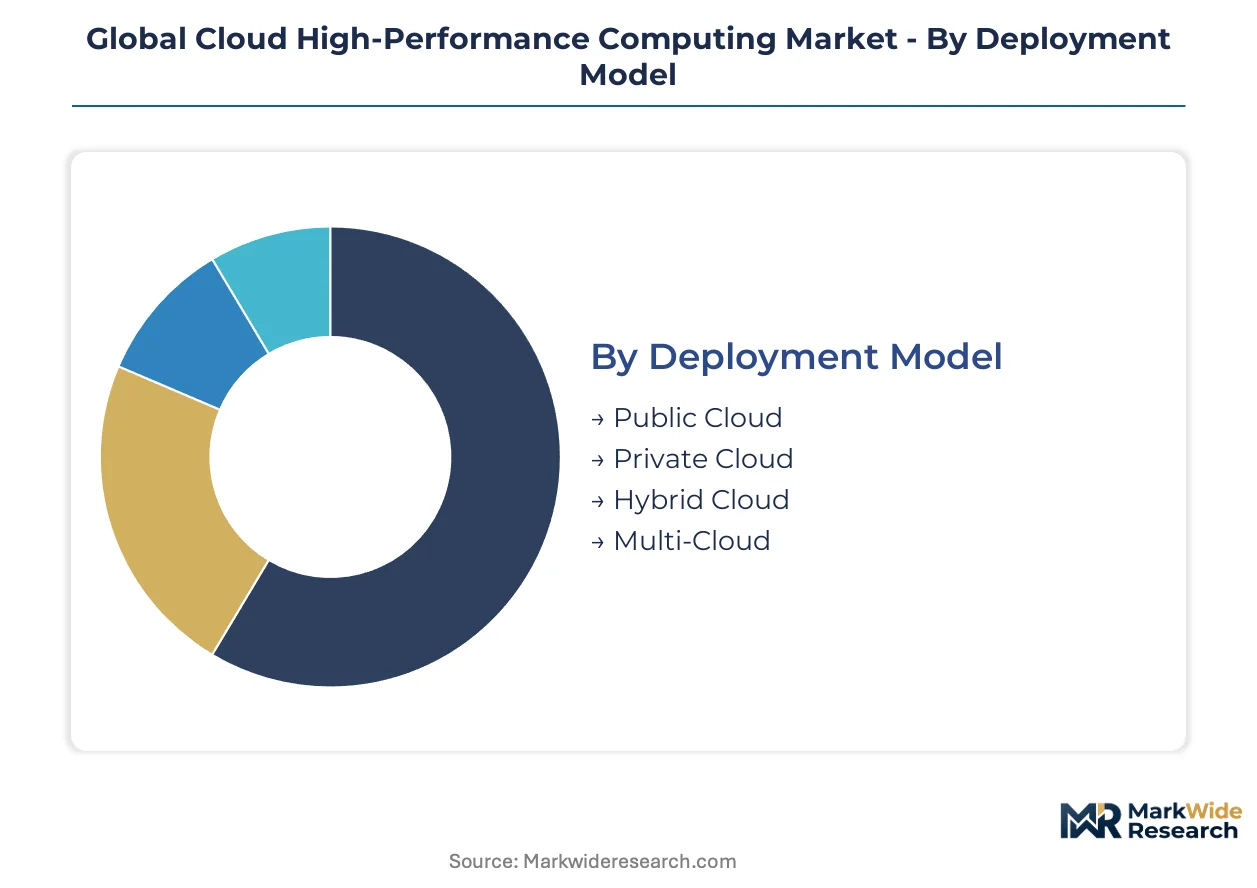
Cloud HPC segmentation reveals how workload characteristics, compliance requirements, and procurement flexibility shape infrastructure choices across molecular simulation, generative AI training, and sovereign data processing mandates. Deployment models and service tiers determine whether organizations retain control over specialized interconnect fabrics or delegate operational complexity to hyperscale operators.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premise retention from operational expenditure models that trade control for elasticity and geographic reach.
- Public Cloud:Shared infrastructure pools deliver petaflop-scale GPU clusters through metered access, eliminating rack-level capital deployment. Pharmaceutical firms in Basel and Boston burst protein folding workloads to Frankfurt and Amsterdam zones for EU AI Act compliance without facility construction.
- Hybrid Cloud:Sensitive genomic data remains on private infrastructure while peak simulation loads spill to public capacity during clinical trial deadlines. German automotive OEMs use this architecture to satisfy KBA domestic processing mandates for crash simulation data.
- Private Cloud:Dedicated bare-metal deployments serve classified government workloads and proprietary AI model training with physical isolation guarantees.
- Multi-Cloud:Workload portability across AWS, Azure, and Google Cloud mitigates vendor lock-in for research consortia negotiating spot pricing arbitrage.
Public Cloud holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Service Type:
Application abstraction level determines whether customers manage kernel-level optimization or consume pre-configured simulation environments.
- IaaS:Bare-metal server provisioning with InfiniBand or Elastic Fabric Adapter networking places interconnect tuning burden on customer engineering teams. Deep margin pools accrue to providers attaching high-bandwidth networking to GPU instances.
- PaaS:Containerized orchestration layers automate MPI cluster configuration, reducing weeks of manual setup to hours for university laboratories without specialized HPC administrators.
- SaaS:Pre-built molecular dynamics or computational fluid dynamics interfaces abstract infrastructure entirely, targeting biotech firms in Cambridge and San Diego.
- Managed Services:Provider-operated workload optimization and compliance documentation addresses EU AI Act algorithmic transparency requirements for Dutch financial institutions.
IaaS dominates revenue contribution. PaaS is climbing the fastest as containerization standardizes.
End User:
Customer type segmentation maps procurement authority, budget cycles, and regulatory exposure to distinct service packaging requirements.
- Enterprises:Automotive and pharmaceutical R&D departments command annual cloud budgets exceeding institutional allocations, driving consumption-based contract negotiation and dedicated support tiers.
- Academic Institutions:Grant-funded research cycles and publication pressures favor spot-market pricing and preemptible instances for non-critical climate modeling batches.
- Government Bodies:FedRAMP authorization gates US federal adoption, while China's MIIT regulations restrict domestic research institutions to sovereign infrastructure.
- Research Organizations:Cross-border consortia in Switzerland and Japan require data residency guarantees and audit-ready logging pipelines for multi-institutional collaboration.
Enterprises anchor current spending. Academic Institutions are gaining share fastest through serverless GPU scheduling adoption.
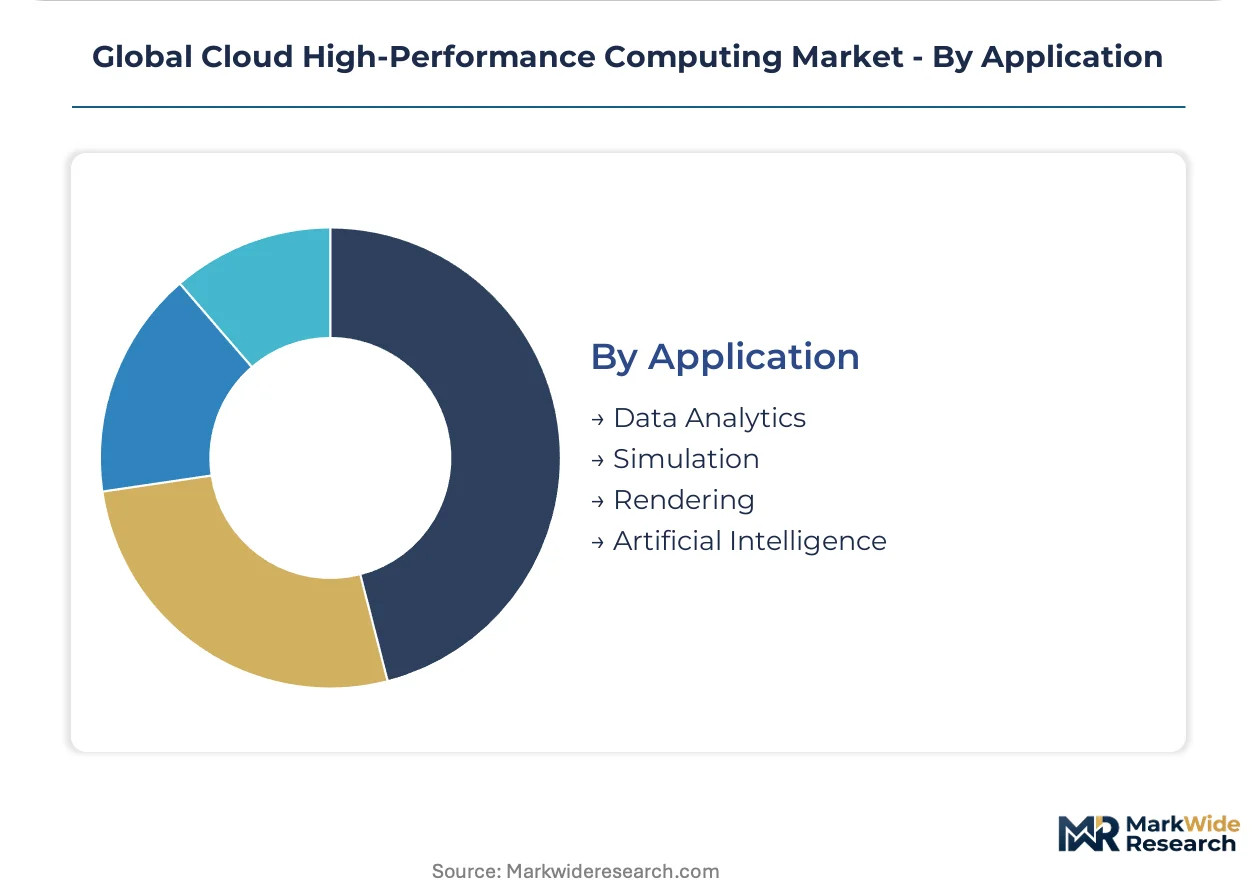
Application:
Volume concentration and computational intensity separate batch-oriented simulation from always-on inference and real-time analytics pipelines.
- Artificial Intelligence:Large language model training consumes petaflop-scale resources across distributed GPU clusters, displacing traditional simulation as the primary workload driver. NVIDIA DGX Cloud and Microsoft Azure OpenAI partnerships anchor enterprise demand.
- Simulation:Computational fluid dynamics and finite element analysis retain dominance in automotive crash testing and aerospace certification where legacy Fortran MPI codes require bare-metal execution.
- Data Analytics:Genomic sequencing pipelines in Singapore and financial risk calculations in London exploit elastic scaling for irregular batch volumes.
- Rendering:Media production studios in Los Angeles and Vancouver burst VFX workloads to cloud render farms during post-production peaks.
Simulation holds legacy installed base. Artificial Intelligence commands the steepest expansion trajectory as foundation model competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscale providers export cloud HPC capacity to pharmaceutical clusters in Basel, automotive R&D centers in Stuttgart, and financial institutions in London. Cross-border data flows concentrate in Frankfurt, Amsterdam, and Singapore as compliance-ready landing zones for regulated workloads.
United States
Federal agencies and enterprise AI labs drive consumption of petaflop-scale GPU clusters for foundation model training. FedRAMP authorization gates cloud supercomputing procurement, creating 12-18 month certification cycles that delay contract awards. Seattle and Northern Virginia data centers anchor hyperscale infrastructure serving domestic pharmaceutical and defense simulation workloads.
Germany
Automotive OEMs and industrial machinery manufacturers migrate crash simulation and computational fluid dynamics to elastic cloud infrastructure. KBA mandates domestic data processing for sensitive vehicle safety data, pushing BMW and Volkswagen toward sovereign cloud deployments. Munich and Stuttgart engineering clusters represent Europe's densest concentration of HPC-intensive manufacturing R&D.
China
Domestic semiconductor design and AI research institutions operate under MIIT cloud service regulations that restrict cross-border data flows. GB standards enforce data localization for research institutions, fragmenting workload portability with global cloud networks. Beijing and Shanghai supercomputing centers serve as captive infrastructure for national AI development programs.
India
Bengaluru and Hyderabad semiconductor design firms access production-linked incentives under the PLI scheme when utilizing domestic cloud HPC resources. CDSCO regulatory pathways for clinical trial data create demand for compliant infrastructure within national borders. Domestic cloud operators capture subsidy-eligible workloads from fabless chip designers and biotech startups.
United Kingdom
London financial institutions and Cambridge biotech firms burst risk simulation and genomic sequencing workloads to cloud infrastructure. Post-Brexit data adequacy arrangements with the EU shape procurement decisions for cross-border research consortia. Oxford and Cambridge university laboratories adopt serverless GPU scheduling for grant-funded molecular dynamics projects.
Global Cloud High-Performance Computing Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic layers: hyperscale cloud operators, specialized AI infrastructure platforms, and legacy enterprise hardware vendors pivoting to as-a-service models. Hyperscalers leverage global fiber networks and pre-certified compliance frameworks to capture regulated workloads. Specialized GPU cloud providers compete on CUDA optimization and interconnect latency. Legacy hardware vendors defend installed bases through hybrid cloud orchestration tools. Dominant competitive moves include vertical integration into silicon design and strategic partnerships with foundation model developers.
Among hyperscale cloud operators, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by networking differentiation and AI workload anchoring. AWS exemplifies the infrastructure-optimized archetype through Elastic Fabric Adapter and Graviton-based cost positioning. Microsoft Azure represents the AI-partnership vector through OpenAI integration and enterprise sales channel density. Google Cloud sits within the workload-portability tier with Kubernetes-native orchestration and multi-cloud tooling. Each anchors distinct procurement preferences: AWS for traditional simulation cost optimization, Azure for large-model training, Google for container-native research environments.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Corporation |
| Hewlett Packard Enterprise |
| Dell Technologies |
| NVIDIA Corporation |
| Intel Corporation |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Northern Virginia's hyperscale data center cluster concentrates GPU server deployment capacity, translating rack-level scarcity into pricing leverage for providers serving pharmaceutical and automotive R&D buyers. Frankfurt and Amsterdam zones command compliance premiums under EU AI Act mandates, while Nordic facilities face margin compression from electricity cost volatility.
Pricing Analysis
Next-generation NVIDIA H100 and Blackwell clusters command 3-4x premiums over prior-generation A100 instances, while older CPU-only simulation nodes face price erosion from Graviton-based alternatives. Three-tier pricing structure across premium GPU clusters, standard CPU instances, and economy spot-market access separates enterprise AI training budgets from academic grant-funded workloads. Pricing pressure stems from hyperscaler capex cycles and foundry allocation constraints for advanced accelerators. Academic institutions exhibit highest price sensitivity, leveraging preemptible instances and spot-market arbitrage across AWS, Azure, and Google Cloud.
Supply Chain Analysis
Upstream feedstock for cloud HPC infrastructure draws from Taiwan for advanced GPU foundry output, South Korea for HBM memory stacks, and the United States for networking silicon and optical interconnect components. NVIDIA's CUDA ecosystem and InfiniBand switch supply anchor provider differentiation, while specialized cooling equipment and high-density power distribution units create secondary bottlenecks. Single-source vulnerability concentrates in TSMC's CoWoS advanced packaging capacity for AI accelerators. Distribution runs through direct hyperscaler procurement teams and specialized HPC integrators serving sovereign cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI training demand is reshaping cloud HPC infrastructure economics, with foundation model development consuming capacity that legacy simulation workflows cannot justify. The EU AI Act's algorithmic transparency mandates create compliance moats for providers with pre-certified European infrastructure.
For Market Incumbents: Pre-empt workload migration to specialized GPU cloud providers by accelerating sovereign cloud certifications in Frankfurt, Amsterdam, and Singapore zones. Defend position through in-house production of custom AI accelerators and exclusive foundation model partnerships that lock in enterprise R&D budgets. Capacity addition in Germany's KBA-compliant zones addresses automotive OEM domestic processing mandates. For New Entrants and Emerging Players: Build out sovereign cloud HPC infrastructure in India under PLI scheme incentives, capturing subsidy-eligible semiconductor design workloads from Bengaluru and Hyderabad. Target academic institutions with serverless GPU scheduling platforms that eliminate idle capacity charges and compress procurement cycles. Go-to-market through research consortium partnerships in Switzerland and Japan offering multi-cloud workload portability tooling. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed services providers with EU AI Act compliance documentation capabilities and long-term pharmaceutical contracts. Long-term viability centers on providers with captive supply of advanced accelerators and pre-certified sovereign infrastructure across three or more regulatory jurisdictions. Monitor hyperscaler capex allocation signals for early inflection in next-generation GPU cluster deployment timing. Cross-checking against CDU and liquid cooling equipment order backlogs is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act and KBA mandates in Germany create compliance-driven procurement preferences for domestic data processing. |
| GPU Cloud Platform Integration | NVIDIA DGX Cloud and CUDA ecosystem lock-in anchors enterprise AI training workloads against hyperscaler alternatives. |
| Backward Integration into Silicon | Custom accelerator design reduces dependency on TSMC foundry allocation and NVIDIA supply constraints. |
| Strategic Partnership with Foundation Model Developers | OpenAI integration at Microsoft Azure demonstrates how exclusive AI lab relationships capture enterprise R&D budgets. |
| Geographic Expansion to India | PLI scheme incentives for domestic cloud HPC utilization attract fabless semiconductor design firms in Bengaluru. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud infrastructure executives, HPC workload engineering leads, pharmaceutical R&D procurement officers, and automotive simulation managers; and secondary validation against hyperscaler capex disclosures, SEC filings, EU regulatory filings on AI Act implementation, and CDSCO clinical trial infrastructure reports. Bottom-up triangulation against top-down market sizing ensured consistency across deployment model, service type, and application segmentation dimensions.
Forecast inputs considered GPU cluster utilization rates, InfiniBand networking attach rates, and sovereign cloud procurement timelines across the projection horizon. Segmentation modeling incorporated deployment model elasticity, service tier abstraction levels, end-user procurement authority, and application computational intensity. CAGRs derived from installed capacity expansion curves and workload migration patterns from on-premise supercomputing centers. Industry-specific inputs included EU AI Act compliance certification timelines and India's PLI scheme subsidy eligibility criteria.
Practitioners should monitor hyperscaler foundry allocation announcements, EU AI Act delegated act publications, and sovereign cloud tender awards for early signals of forecast revision. Cross-checking against NVIDIA quarterly data center revenue disclosures and TSMC CoWoS capacity expansion statements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Government Cloud Computing Market
Cloud Computing
Cloud Database Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Europe Cloud Computing Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Private Cloud Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
VM Service Market
Cloud Computing
Commerce Cloud Market
Cloud Computing
UK Cloud Backup Market