
 Asia Pacific Enterprise Collaboration Market | 2026-2036
Asia Pacific Enterprise Collaboration Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Enterprise Collaboration Market Outlook
Enterprise-grade security certification is reorganizing competitive hierarchy across the Asia Pacific Enterprise Collaboration Market. Microsoft Corporation leverages its Azure sovereign cloud architecture to anchor public sector contracts in Australia and Singapore. Huawei Technologies competes through localized data center infrastructure that satisfies China's MIIT cross-border data rules.
Asia Pacific enterprise collaboration encompasses integrated software platforms enabling real-time communication, document co-authoring, and workflow orchestration across distributed organizational networks, typically deployed through multi-tenant cloud architectures with sub-100 millisecond latency requirements for video synchronization. The primary commercial purpose centers on eliminating geographic friction in knowledge work and accelerating decision velocity across time-zone separated teams. Cloud-based deployment structures now capture the dominant margin pool as hybrid configurations recede to legacy migration scenarios, while workflow automation applications outpace document sharing in net-new contract value across large enterprise accounts.
India's TRAI data localization advisories, China's Cybersecurity Law administered by the CAC, and Australia's Privacy Act amendments collectively reshape product architecture requirements, forcing vendors to engineer region-specific tenant isolation and encryption key sovereignty. Japan's METI digital transformation subsidies further steer procurement toward platforms demonstrating JIS-aligned interoperability standards. Stakeholders must evaluate whether their infrastructure investments align with emerging multi-jurisdiction compliance matrices before committing to platform consolidation roadmaps.
Market Dynamics
Data sovereignty mandates across the Asia Pacific region are forcing vendors to fragment their cloud architectures into jurisdiction-specific instances, raising operational complexity while creating compliance-based competitive moats for incumbents with localized infrastructure.
Growth Catalysts
- India's PLI scheme for IT hardware:Domestic server manufacturing incentives accelerate data residency-compliant infrastructure deployment, reducing cross-border latency for enterprise tenants.
- Financial services digitization:Southeast Asian banks and insurers are consolidating point solutions into unified collaboration suites to support hybrid workforces across dispersed branch networks.
- Japan's METI digital transformation subsidies:Procurement incentives steer public and private sector buyers toward platforms demonstrating JIS-aligned interoperability standards.
Market Restraints
- Submarine cable concentration:Over 70% of intra-Asia Pacific data traffic traverses Singapore-Japan routes, creating single-point-of-failure risk for real-time collaboration latency.
- Encryption export control friction:China's MIIT cross-border data rules and Australia's TGA-adjacent security frameworks impose conflicting cryptographic key management requirements.
- Legacy on-premise sunk costs:Large Australian enterprises maintain substantial investments in private branch exchange and document management systems that resist cloud migration.
Strategic Opportunities
- Vietnam and Philippines enterprise greenfield:Mid-market firms in these markets lack entrenched legacy infrastructure, enabling native cloud-first deployment without migration overhead.
- Workflow automation convergence:Integration of low-code process orchestration with core collaboration platforms opens new contract value in professional services and logistics verticals.
- Australia's Privacy Act amendments:Mandatory breach notification and enhanced consent frameworks create demand for sovereign-tenant architectures with audit-ready data lineage.
Industry Challenges
- Multi-jurisdiction compliance engineering:Vendors must maintain parallel codebases for TRAI data localization advisories, CAC Cybersecurity Law implementations, and Australia's Privacy Act requirements simultaneously.
- Sub-100 millisecond latency engineering:Video synchronization standards demand edge computing investments that strain capex budgets outside established Singapore, Sydney, and Tokyo data center clusters.
- Interoperability certification backlog:JIS standards alignment and regional security clearances create 12-18 month product launch delays for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Enterprise Collaboration Market |
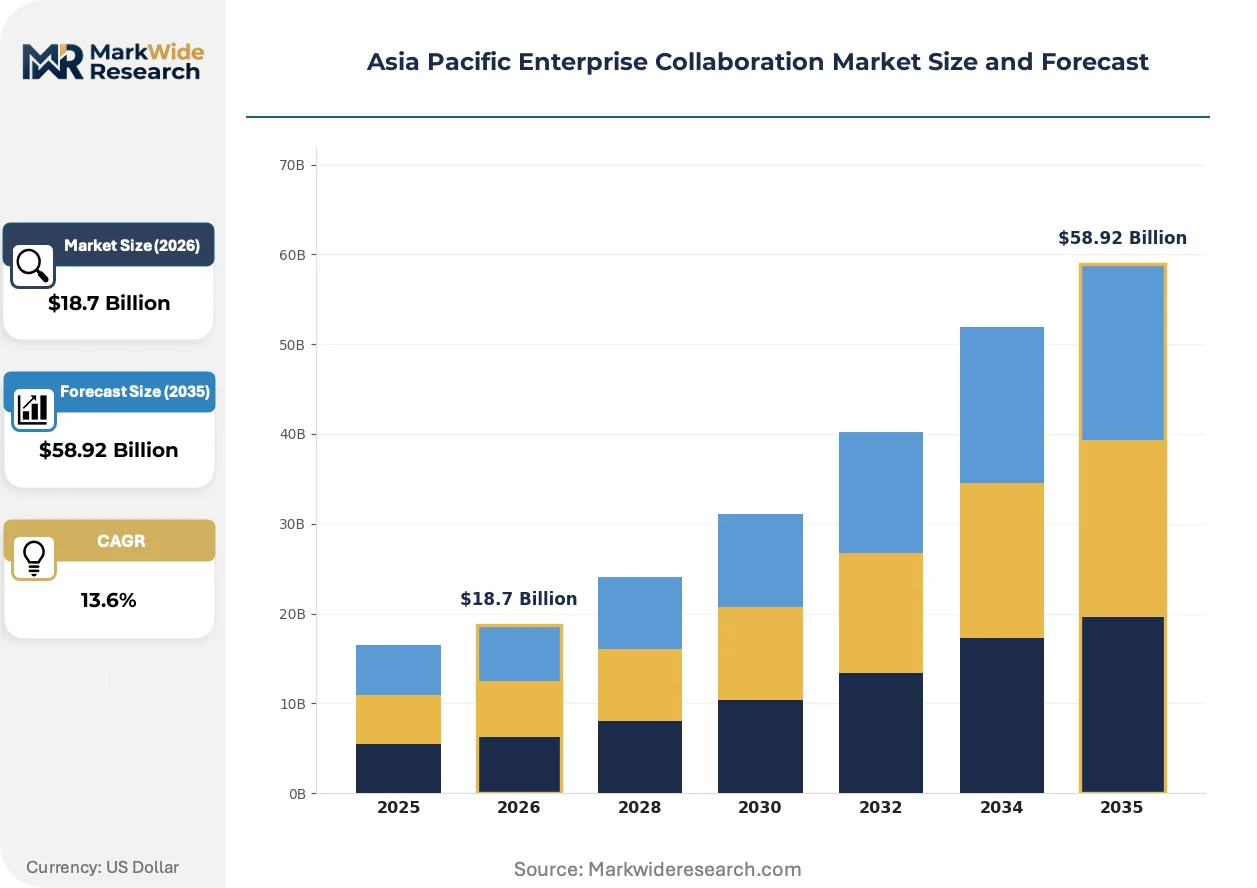
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Project Management, Document Sharing, Communication Tools, Workflow Automation Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Tenant End User: Small Enterprises, Large Enterprises, Government Sector, Non-Profit Organizations Solution: Unified Communication, Video Conferencing, Instant Messaging, Collaboration Software |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Atlassian Corporation, Slack Technologies, Salesforce, Google, Cisco Systems, Zoho Corporation, Huawei Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Enterprise Collaboration Market Strategic Shifts
Artificial intelligence agents embedded within collaboration platforms are compressing decision cycles by automating meeting transcription, action item extraction, and cross-functional workflow handoffs without human intermediation.
Generative AI summarization and task generation is supplanting traditional meeting recording and manual note-taking workflows in large enterprise accounts. Australian financial services firms and Singaporean government agencies are deploying these capabilities at scale within six-month procurement cycles. The technology is compressing vendor differentiation around basic communication features while elevating workflow automation and vertical-specific AI training as the primary competitive battlegrounds.
China's MIIT cross-border data transfer security assessment rules and India's TRAI data localization advisories are forcing architectural fragmentation. Vendors must now engineer region-isolated tenant environments with sovereign encryption key custody rather than global multi-tenant instances. Australian public sector procurement channels and Singaporean financial services regulators are demanding proof of jurisdictional data containment before contract award.
Subscription fatigue among mid-market buyers is fragmenting procurement into modular, best-of-breed selections rather than suite consolidation. Southeast Asian professional services firms and Indian IT services companies are unbundling video, document, and project management functions across specialized vendors. This pattern is most visible in Bangalore, Ho Chi Minh City, and Manila where buyers prioritize functional depth over vendor consolidation.
Asia Pacific Enterprise Collaboration Market Segmentation
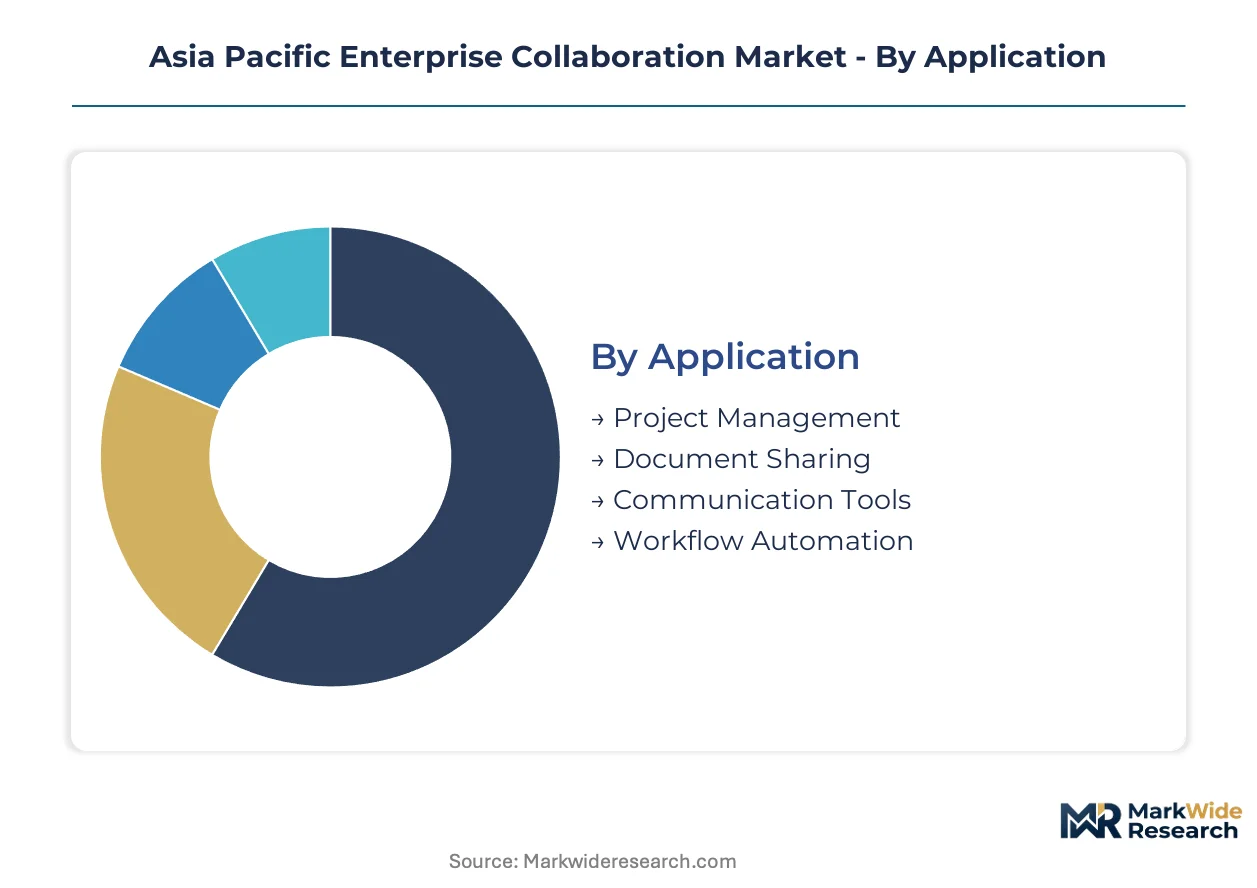
Asia Pacific enterprise collaboration procurement patterns diverge sharply across application types and deployment architectures, with regulatory compliance requirements fragmenting vendor offerings into jurisdiction-specific configurations. Understanding segment-level demand concentration enables platform providers to align infrastructure investments with localized data sovereignty mandates.
Application:
Regulatory differentiation across TRAI advisories, CAC Cybersecurity Law, and Australia's Privacy Act amendments reshapes functional prioritization within enterprise collaboration suites.
- Project Management:Gantt-based task orchestration with resource allocation dashboards dominates Australian professional services and Singaporean logistics verticals. Melbourne consulting firms and Jakarta supply chain operators prioritize native integration with ERP systems to satisfy audit-ready workflow documentation requirements.
- Workflow Automation:Low-code process orchestration with conditional logic and API connectors commands premium pricing in Japanese manufacturing and Indian IT services. METI digital transformation subsidies accelerate procurement of JIS-aligned platforms with embedded robotic process automation capabilities.
- Document Sharing:Co-authoring platforms with version control and granular permission matrices serve distributed legal and financial services teams.
- Communication Tools:Persistent chat channels with threaded conversations and searchable archives support real-time coordination across time-zone separated operations.
Established volume favors Document Sharing; emerging adoption favors Workflow Automation.
Deployment:
Cost tier stratification separates capex-intensive private infrastructure from operational expenditure models favored by mid-market buyers.
- Cloud-Based:Multi-tenant SaaS architectures with elastic compute scaling capture dominant contract value across Southeast Asian financial services. Bangkok banks and Ho Chi Minh City insurers consolidate point solutions into unified suites to support hybrid branch networks without on-premise maintenance overhead.
- Multi-Tenant:Isolated tenant environments with sovereign encryption key custody address China's MIIT cross-border data rules and India's data localization requirements. Beijing state-owned enterprises and Mumbai system integrators demand jurisdictional data containment with sub-100 millisecond latency guarantees.
- Hybrid:Split architectures maintaining sensitive workloads on-premise while routing collaboration traffic through cloud gateways.
- On-Premises:Private data center deployments serving defense and critical infrastructure operators with air-gapped security requirements.
Deployment concentration tilts toward Cloud-Based configurations; compliance complexity elevates Multi-Tenant specification rates.
End User:
Customer type determines feature depth requirements and procurement cycle duration across the Asia Pacific region.
- Large Enterprises:Global 2000 subsidiaries with 10,000+ seat deployments require custom integration layers and dedicated customer success management. Sydney headquarters operations and Singaporean regional hubs mandate enterprise-grade security certification with 99.999% uptime SLAs.
- Government Sector:Sovereign cloud mandates with classified data handling protocols dominate Australian public sector and Chinese state procurement channels. Canberra agencies and provincial Chinese administrations require localized data center presence with domestic staff access restrictions.
- Small Enterprises:Modular, best-of-breed procurement patterns without suite consolidation.
- Non-Profit Organizations:Grant-funded implementations with donated or discounted licensing tiers.
Revenue concentration centers on Large Enterprises; steepest expansion trajectory appears in Government Sector digitization programs.
Solution:
Technology maturity separates commoditized communication functions from vertically integrated platform strategies.
- Unified Communication:Integrated voice, video, and messaging with presence awareness and calendar synchronization anchors enterprise-wide collaboration strategies. Tokyo financial institutions and Seoul conglomerates consolidate legacy PBX infrastructure into cloud-native platforms with mobile-first endpoint support.
- Collaboration Software:Workspace-centric platforms combining project tracking, knowledge bases, and external guest access serve distributed professional services networks. Bangalore IT services companies and Manila business process outsourcing operators prioritize API extensibility for client-specific customization.
- Video Conferencing:High-definition meeting rooms with AI-powered transcription and translation capabilities.
- Instant Messaging:Lightweight peer-to-peer and group messaging with end-to-end encryption for field workforce coordination.
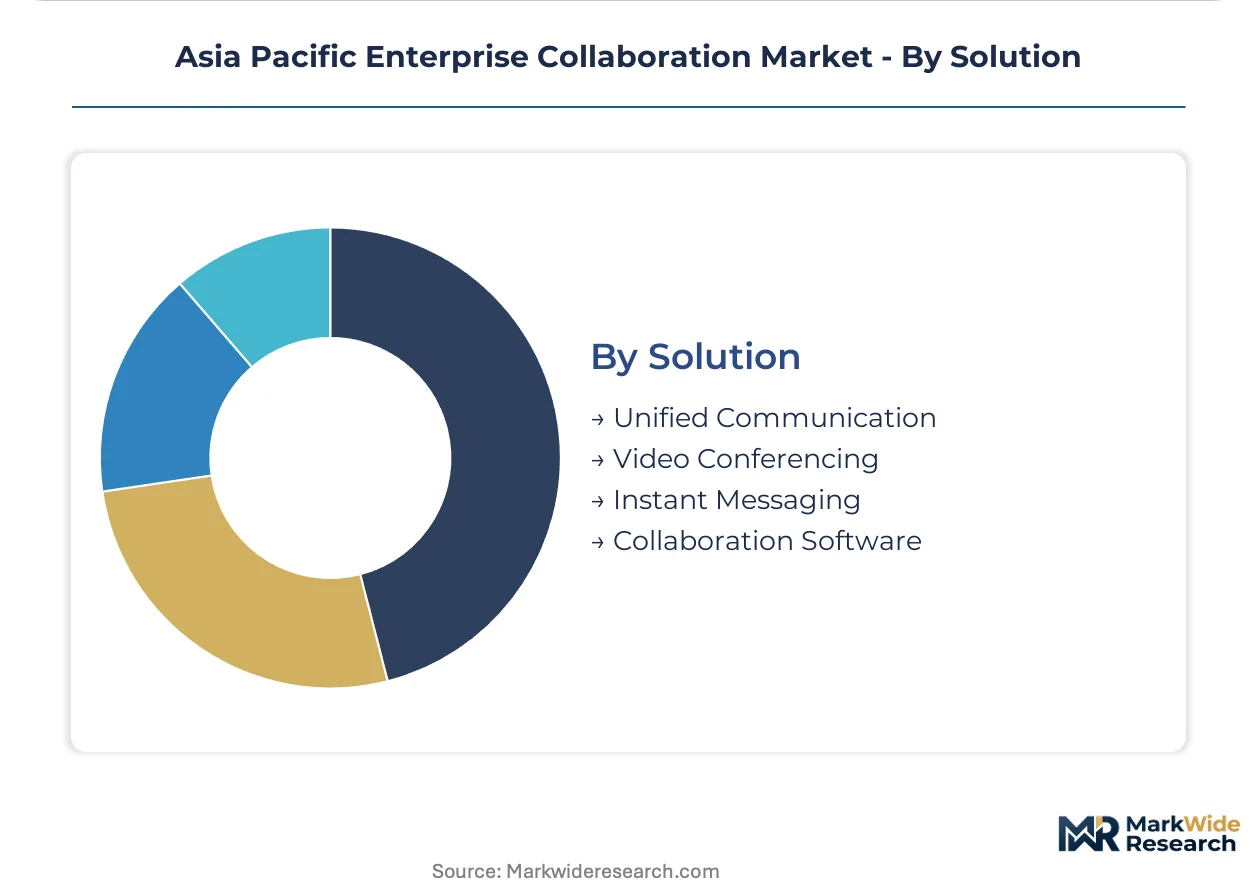
Platform consolidation favors Unified Communication; functional unbundling elevates Collaboration Software selection rates among specialized verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific enterprise collaboration markets exhibit pronounced trade asymmetry in software services, with India and China running substantial surpluses in IT-enabled collaboration exports while Australia and Japan remain net importers of cloud infrastructure technology. Cross-border data flow restrictions are redrawing traditional service delivery corridors.
China
State-owned enterprises in Beijing and Shanghai drive demand for sovereign-tenant architectures with domestic encryption key custody. MIIT cross-border data transfer security assessments mandate localized data center presence for foreign vendors. Shenzhen technology parks host indigenous platform development competing against imported suites.
India
Bangalore IT services companies and Mumbai system integrators procure collaboration platforms for delivery center coordination across multiple client time zones. TRAI data localization advisories push vendors toward domestic server deployment under PLI scheme incentives. Hyderabad cloud infrastructure clusters expand capacity to serve ASEAN enterprise tenants.
Japan
Tokyo financial institutions and Osaka manufacturing conglomerates prioritize JIS-aligned interoperability standards in procurement decisions. METI digital transformation subsidies accelerate replacement of legacy on-premise systems with cloud-native platforms. Nagoya automotive supply chain operators demand sub-100 millisecond latency guarantees for real-time coordination.
Australia
Sydney headquarters operations and Melbourne professional services firms mandate sovereign cloud certification for public sector contracts. Privacy Act amendments requiring mandatory breach notification steer selection toward audit-ready data lineage architectures. Canberra government agencies enforce domestic staff access restrictions on classified collaboration environments.
Singapore
Maritime logistics operators and regional banking headquarters consolidate ASEAN-wide branch coordination through unified collaboration suites. Monetary Authority of Singapore cybersecurity guidelines impose encryption standards exceeding baseline commercial offerings. One-north technology district hosts vendor innovation labs serving Southeast Asian mid-market expansion.
Asia Pacific Enterprise Collaboration Market Competitive Environment
Concentration sits with hyperscale cloud providers possessing sovereign infrastructure footprints across multiple Asia Pacific jurisdictions. Tier-two specialists compete through vertical-specific workflow automation and JIS-aligned certification maintenance. Dominant competitive moves include strategic partnerships with domestic system integrators and accelerated edge computing deployment to satisfy latency requirements outside established data center clusters.
Among United States-based technology conglomerates, Microsoft Corporation and Amazon Web Services anchor the infrastructure layer through Azure sovereign cloud and AWS regional instance offerings. Atlassian Corporation exemplifies the application-tier specialist archetype with project management and developer collaboration tools. Zoho Corporation represents India-origin SaaS providers competing on modular pricing and SME-focused distribution.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Atlassian Corporation |
| Slack Technologies |
| Salesforce |
| Cisco Systems |
| Zoho Corporation |
| Huawei Technologies |
| Others |
Value Chain & Pricing Dynamics
Cloud-native software stacks displacing legacy on-premise hardware simultaneously redistribute supply geography toward hyperscaler data center clusters and compress pricing economics through subscription normalization. This substitution dynamic concentrates vendor margin pools in recurring service layers while fragmenting infrastructure procurement across jurisdiction-specific compliance zones.
Pricing Analysis
Large enterprise buyers anchor Asia Pacific enterprise collaboration pricing through volume-commitment contracts with sovereign-tenant premiums. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification grade and data residency compliance tier as primary differentiation drivers. Cost compression in mid-market SaaS tiers intensifies because subscription fatigue drives modular unbundling. Small enterprises exhibit highest price sensitivity, while government sector buyers prioritize audit-ready data lineage over unit cost.
Supply Chain Analysis
Singapore, Sydney, and Tokyo anchor hyperscale data center infrastructure serving ASEAN, Australasia, and Northeast Asian enterprise tenants respectively. Compute capacity expansion draws from domestic server manufacturing under India's PLI scheme, submarine cable bandwidth, and sovereign encryption key custody services. Single-point-of-failure risk concentrates in Singapore-Japan cable routes. Distribution runs through domestic system integrators with METI subsidy administration capability in Japan and sovereign cloud certification authority in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific enterprise collaboration functions as a service-attach opportunity where workflow automation and AI-powered orchestration layers expand contract value faster than core communication subscriptions. Managed security services and compliance consulting represent the fastest-growing recurring revenue attachments.
For Market Incumbents: Fortify sovereign infrastructure footprints across multiple jurisdictions to defend against emerging regional specialists with localized MIIT and TRAI compliance capabilities. Prioritize edge computing deployment outside established Singapore, Sydney, and Tokyo clusters to satisfy sub-100 millisecond latency requirements. Deepen backward integration into domestic server manufacturing through PLI scheme partnerships. For New Entrants and Emerging Players: JIS certification fast-tracks open procurement access to METI-subsidized manufacturing and financial services digitization programs in Japan. Vietnam and Philippines enterprise greenfield segments lack entrenched legacy infrastructure and present lowest competitive density. Target mid-market professional services firms in Ho Chi Minh City and Manila with modular, API-extensible collaboration software. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed workflow automation specialists possessing JIS-aligned interoperability certification and established Japanese manufacturing customer bases. Five-to-ten year viability hinges on multi-jurisdiction compliance engineering capability rather than feature parity. Monitor submarine cable route diversification announcements as infrastructure inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Deployment | Azure and AWS regional instances satisfy Australia's Privacy Act amendments and Singapore MAS cybersecurity guidelines. |
| Workflow Automation Integration | Low-code orchestration with RPA capabilities commands premium pricing in METI-subsidized Japanese manufacturing procurement. |
| Edge Computing Expansion | Jakarta and Manila data center presence reduces latency for ASEAN financial services branch networks. |
| AI Agent Embedding | Generative summarization and task automation compress decision cycles in Australian financial services and Singapore government agencies. |
| Domestic System Integrator Partnership | Canberra and Beijing procurement channels require localized staff access restrictions and sovereign encryption key custody. |
Study Parameters
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and channel partners across Sydney, Singapore, Tokyo, Bangalore, and Shanghai, and refined through secondary validation against hyperscaler capex disclosures, SEC filings, TRAI regulatory advisories, and METI subsidy program documentation. Bottom-up tenant deployment estimates triangulated with top-down market sizing from cloud infrastructure spend analysis.
Variance-decomposition across deployment model, organization size, vertical, integration complexity, and regional adoption pattern shaped the analytical framework throughout the projection horizon. CAGRs derived from elasticity-adjusted penetration curves incorporating JIS certification timelines, PLI scheme infrastructure buildout schedules, and data sovereignty mandate implementation phases.
Decision-makers should treat outputs as directional under sustained regulatory fragmentation and hyperscaler concentration assumptions; material deviation in submarine cable route economics or encryption export control frameworks would warrant model refresh. Recalibration cycles align with material shifts in MIIT cross-border data rules and Australia's Privacy Act enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
United States Managed Services Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Europe Managed Infrastructure Services Market
Enterprise Services
Shared Services Center Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Qatar Managed Services Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Enterprise Social Networks Market