
 Jordan ICT Market | 2026-2036
Jordan ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Jordan ICT Market Insights
Banking and financial services adoption is restructuring the Jordan ICT Market as digital payment rails and core banking modernization absorb the largest share of enterprise technology budgets. Zain Jordan leverages its nationwide fiber footprint to dominate carrier-grade connectivity for financial institutions. Orange Jordan Telecommunications Company anchors wholesale and enterprise segments through submarine cable landing rights and data center presence in Amman. Microsoft Corporation sustains cloud platform adoption across regulated industries navigating data residency requirements.
Information and communications technology in Jordan encompasses telecommunications infrastructure, cloud platforms, enterprise software, cybersecurity systems, and managed services operating across fixed and mobile networks with latency specifications typically below 50ms for financial trading applications. The primary purpose centers on enabling digital service delivery, government modernization, and private sector competitiveness through reliable data transmission and compute access. Cloud Computing leads technology investment as enterprises migrate legacy workloads to local and regional hyperscaler regions, while Cybersecurity commands premium pricing amid escalating threat volumes targeting Gulf-facing financial gateways. Managed Services within the Service Type dimension captures expanding margin pools as skills scarcity pushes mid-market enterprises toward outsourced operations.
Jordan's Ministry of Digital Economy and Entrepreneurship, the Telecommunications Regulatory Commission, and Central Bank of Jordan shape market access through cloud sovereignty guidelines, spectrum allocation frameworks, and payment systems cybersecurity mandates respectively. The Central Bank's operational resilience requirements force financial institutions toward audited managed security providers, tightening vendor qualification standards. Stakeholders must monitor regulatory divergence between Jordan's national cloud policies and GCC alignment pressures as data localization commitments reshape cross-border service architectures.
Market Dynamics
Cloud sovereignty mandates from the Ministry of Digital Economy and Entrepreneurship are compressing procurement timelines and forcing hyperscaler localization investments across Jordan's public sector and regulated industries.
Growth Catalysts
- Cloud-First Policy Mandates:The Ministry of Digital Economy and Entrepreneurship's directive accelerates public sector workload migration to sovereign infrastructure, creating guaranteed demand for compliant hosting providers.
- Banking Modernization:Core banking replacement cycles across Amman-based financial institutions absorb substantial technology budgets as legacy systems reach end-of-life.
- Cybersecurity Incidents:Ransomware exposure targeting Gulf-facing payment gateways compels enterprises toward audited managed security services and zero-trust architectures.
Market Restraints
- Skills Scarcity:Domestic cloud architecture and cybersecurity expertise shortages force enterprises toward premium-priced outsourced operations, inflating total cost of ownership.
- Spectrum Allocation Delays:The Telecommunications Regulatory Commission's prolonged 5G mid-band licensing timeline constrains mobile edge computing deployment for financial trading applications.
- Data Localization Costs:Sovereign cloud requirements fragment hyperscaler economics, preventing Jordanian enterprises from accessing regional economies of scale available in UAE or Saudi Arabia.
Strategic Opportunities
- Zarqa Industrial Corridor:Manufacturing clusters outside Amman remain underpenetrated for industrial IoT and predictive maintenance solutions, presenting greenfield deployment potential.
- Converged Security-Network Bundles:SASE architecture adoption creates openings for providers integrating SD-WAN with cloud-delivered security for mid-market enterprises.
- Central Bank Cybersecurity Mandates:Operational resilience requirements for payment systems force vendor qualification standardization, favoring certified managed service providers with local presence.
Industry Challenges
- Certification Bottlenecks:Central Bank of Jordan security audit timelines for cloud service providers extend 12-18 months, delaying revenue recognition for new market entrants.
- Legacy Integration Complexity:Core banking systems from 1990s architectures resist API-native connectivity, requiring costly middleware layers for cloud migration projects.
- Talent Retention Pressures:Gulf-based competitors recruit Jordanian cybersecurity specialists at 3-4x local compensation, eroding domestic service provider capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jordan ICT Market |
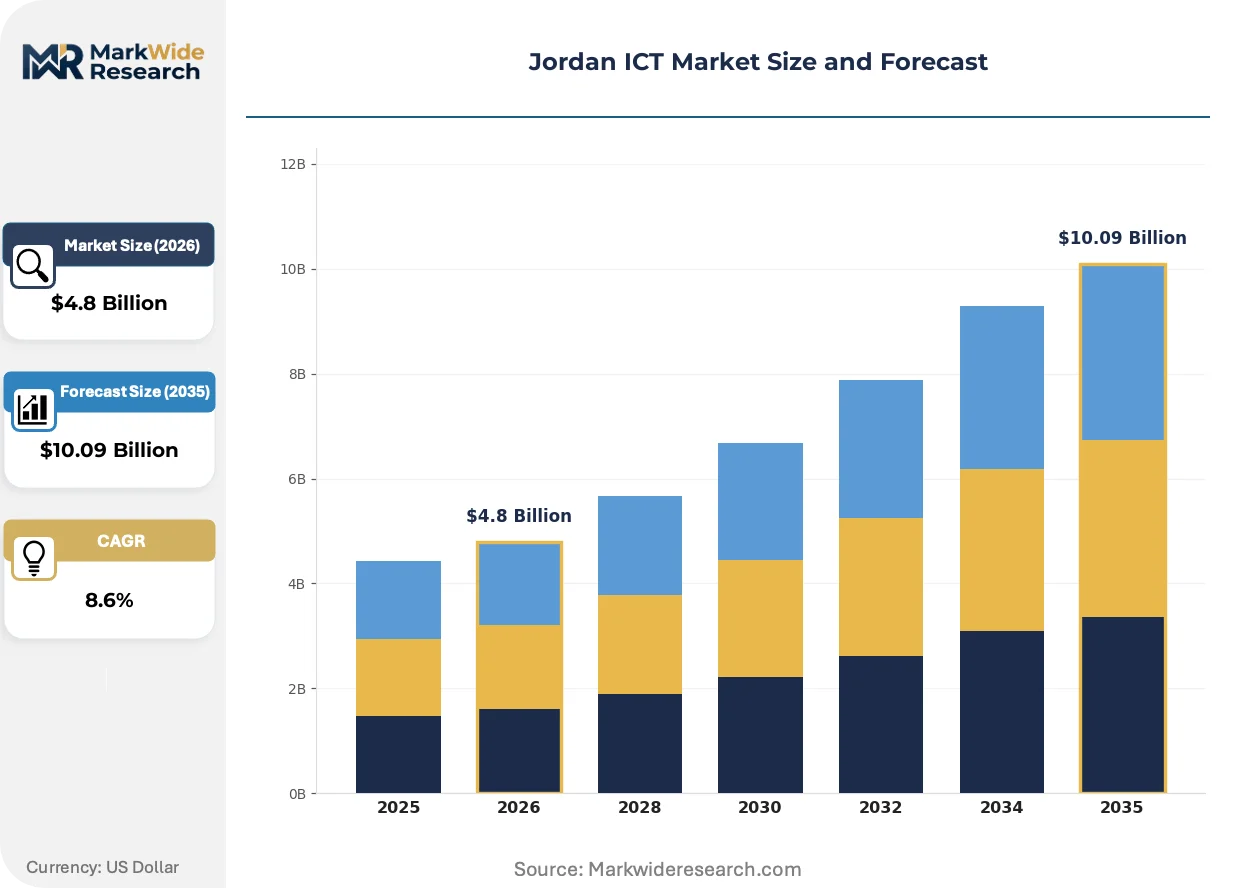
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, IoT, Big Data, Cybersecurity Application: Telecommunications, E-Government, E-Commerce, Healthcare Solutions Service Type: Managed Services, Professional Services, Software Development, IT Support End User: Public Sector, Private Sector, SMEs, Educational Institutions |
| Companies Covered | Zain Jordan, Orange Jordan Telecommunications Company, Umniah Mobile Company PSC, Microsoft Corporation, Cisco Systems Inc., Optimiza, Integrated Technology Group (ITG), ProgressSoft Corporation, Specialized Technical Services Company (STS), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jordan ICT Market Trends and Innovations
Artificial intelligence deployment patterns are reshaping infrastructure requirements as Jordanian enterprises move from experimentation to production workloads, demanding specialized compute and data governance frameworks.
Edge computing infrastructure is expanding into financial services as Amman-based trading floors and payment processors demand sub-10 millisecond latency for real-time risk calculations. Zain Jordan's fiber-to-the-building investments in the capital's central business district support this migration. The technology is compressing traditional data center centralization models by distributing inference workloads closer to transaction origination points.
The Central Bank of Jordan's operational resilience directive for payment systems mandates multi-region disaster recovery and annual penetration testing for all critical technology suppliers. This forces cloud providers to establish secondary sites within national borders and submit to continuous security audits. Financial institutions are responding by consolidating vendor relationships around providers with demonstrated compliance histories.
Enterprise buyers are consolidating security spending around integrated platforms rather than point solutions, displacing fragmented best-of-breed procurement patterns prevalent through 2023. Mid-market banks and insurers in Zarqa and Irbid are driving this consolidation as skills gaps make multi-vendor management unsustainable. This concentration is most visible among regulated entities navigating Central Bank vendor qualification requirements.
Jordan ICT Market Segmentation
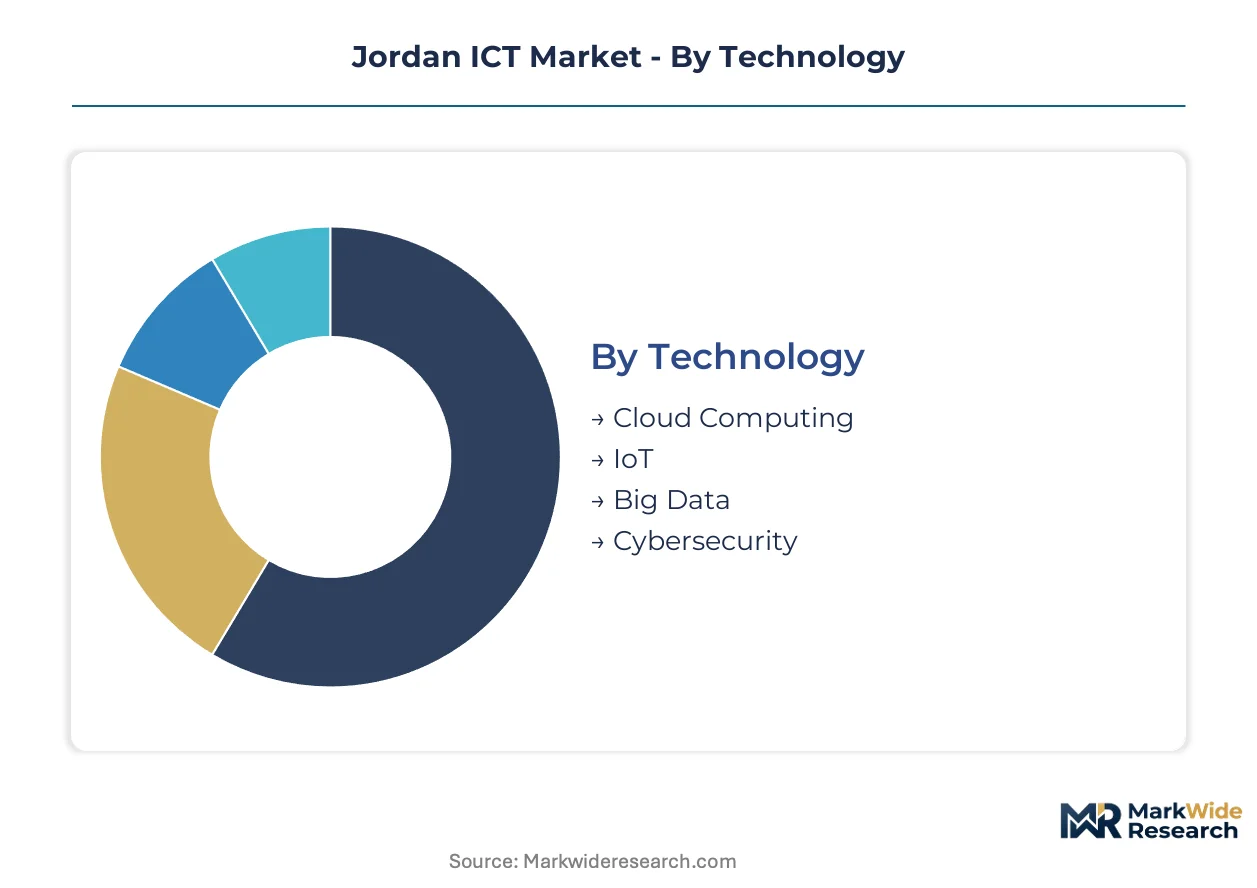
Segmentation reveals how procurement patterns split across sovereign infrastructure mandates and commercial modernization cycles in Jordan. Technology investment concentrates where regulatory compliance intersects with operational resilience requirements.
Technology:
Cloud Computing and Cybersecurity operate as standalone procurement categories with dedicated budgets, while IoT and Big Data embed within broader enterprise systems.
- Cloud Computing:Sovereign infrastructure deployments dominate public sector procurement under Ministry of Digital Economy and Entrepreneurship directives. Financial institutions in Amman absorb capacity in local hyperscaler regions to satisfy data residency requirements.
- Cybersecurity:Audited managed security services command premium pricing as ransomware campaigns target Gulf-facing payment gateways. Central Bank of Jordan operational resilience mandates force vendor consolidation around certified providers with local presence.
- IoT:Industrial deployments concentrate in Zarqa manufacturing corridors for predictive maintenance applications.
- Big Data:Analytics workloads support credit scoring modernization and fraud detection across Amman-based banking networks.
Volume placements concentrate in Cloud Computing; the faster expansion belongs to Cybersecurity.
Application:
Telecommunications and E-Government anchor high-volume procurement with established funding mechanisms, while E-Commerce and Healthcare Solutions attract emerging investment tiers.
- Telecommunications:Fiber-to-the-building infrastructure and 5G readiness programs absorb carrier capital expenditure. Zain Jordan's nationwide footprint and Orange Jordan's submarine cable landing rights structure competitive positioning for financial connectivity.
- E-Government:Ministry-mandated cloud migration timelines compress procurement cycles for compliant hosting providers. Citizen service portals and tax digitization drive workload consolidation onto sovereign infrastructure.
- E-Commerce:Payment gateway modernization and logistics platform integration attract mid-market technology spending.
- Healthcare Solutions:Electronic medical record deployments accelerate in Amman and Irbid hospital networks.
Telecommunications captures the largest procurement volumes; E-Government climbs the fastest on policy mandate timelines.
Service Type:
Managed Services and IT Support function as ongoing operational expenditures, while Professional Services and Software Development represent project-based capital deployment.
- Managed Services:Skills scarcity across cloud architecture and cybersecurity disciplines pushes mid-market enterprises toward outsourced operations. Annual recurring revenue models displace one-time licensing as preferred commercial structures.
- Professional Services:System integration and legacy modernization projects concentrate in banking and public sector verticals. Core banking replacement cycles from 1990s architectures require specialized middleware expertise.
- Software Development:Custom application builds support regulatory reporting and payment system compliance.
- IT Support:Help desk and infrastructure maintenance contracts sustain provider margins in cost-competitive segments.
Managed Services dominates revenue stability; Professional Services gains share fastest on modernization urgency.
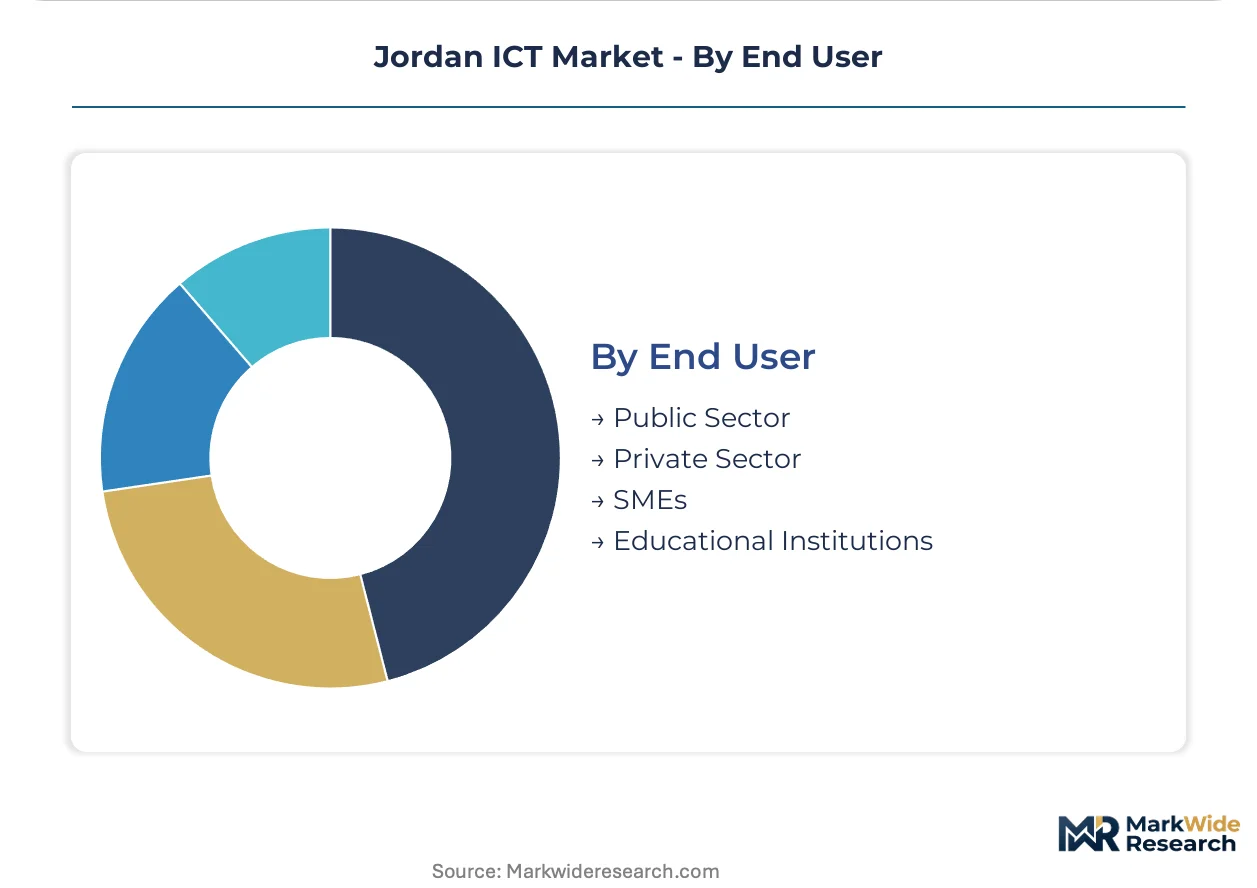
End User:
Public Sector and Private Sector operate through distinct procurement frameworks, while SMEs and Educational Institutions access technology through aggregated purchasing channels.
- Public Sector:Ministry of Digital Economy and Entrepreneurship cloud-first policies guarantee sovereign infrastructure demand. Budget cycles align with fiscal year appropriations rather than commercial return-on-investment metrics.
- Private Sector:Banking and financial services anchor enterprise technology spending with operational resilience requirements. Manufacturing clusters in Zarqa present greenfield deployment opportunities outside Amman concentration.
- SMEs:Bundled service packages and managed security offerings address capability gaps without dedicated internal teams.
- Educational Institutions:University digital transformation programs and vocational training platforms absorb specialized funding streams.
Public Sector secures the steadiest volume commitments; Private Sector expands most quickly on competitive modernization pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Aqaba Special Economic Zone Authority drives technology concentration through tax incentives and duty exemptions on ICT equipment imports. This regulatory enclave attracts data center investments and submarine cable landing infrastructure that anchor Jordan's digital connectivity to regional markets.
Amman Governorate
Financial services modernization and sovereign cloud migration absorb the majority of enterprise technology spending. The Ministry of Digital Economy and Entrepreneurship's cloud-first mandates compress procurement timelines for compliant hosting providers. The Abdali and Shmeisani districts concentrate banking technology headquarters and hyperscaler edge nodes serving real-time payment systems.
Zarqa Governorate
Industrial IoT deployments for predictive maintenance are penetrating manufacturing clusters previously underserved by digital infrastructure. The Zarqa Chamber of Industry coordinates SME technology adoption programs with subsidized connectivity packages. Al-Russayfah and Al-Hashimiyah industrial zones host pilot smart factory implementations integrating sensor networks with cloud analytics.
Irbid Governorate
Educational technology procurement from Yarmouk University and Jordan University of Science and Technology sustains specialized software development demand. The Higher Council for Science and Technology funds research computing infrastructure that anchors local data center capacity. Northern corridor fiber extensions from Zain Jordan and Orange Jordan reduce latency to Amman financial hubs.
Aqaba Governorate
Port logistics digitization and customs modernization drive specialized maritime technology spending. The Aqaba Special Economic Zone Authority's regulatory autonomy permits streamlined data center licensing outside national telecom frameworks. The Aqaba Development Corporation anchors submarine cable investments linking Jordan to Saudi Arabia and Egypt markets.
Balqa Governorate
Salt's emerging status as a government services backup site creates disaster recovery and business continuity demand. The National Information Technology Center's secondary facilities in the governorate distribute public sector workloads from Amman concentration. Public-private partnership frameworks for e-government service delivery attract managed services providers with sovereign compliance capabilities.
Jordan ICT Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with telecommunications carriers commanding infrastructure layers while systems integrators capture enterprise transformation budgets. The market structures around three tiers: nationwide fiber and mobile operators with submarine cable assets; certified managed security providers meeting Central Bank qualification standards; and boutique software developers serving vertical-specific compliance requirements. M&A activity concentrates in cybersecurity capabilities as qualified personnel scarcity drives consolidation, while strategic partnerships between global hyperscalers and local hosting providers proliferate to satisfy data residency mandates.
Among carrier-grade infrastructure providers, Zain Jordan and Orange Jordan Telecommunications Company exemplify the connectivity-anchored archetype through nationwide fiber footprints and submarine cable landing rights. Microsoft Corporation occupies a position as the hyperscaler reference point for regulated industry cloud adoption, navigating data residency requirements through local region availability. These three entities represent the dominant competitive anchors shaping procurement patterns across Jordan's banking, public sector, and industrial verticals.
| Leading Market Players |
|---|
| Zain Jordan |
| Orange Jordan Telecommunications Company |
| Umniah Mobile Company PSC |
| Microsoft Corporation |
| Cisco Systems Inc. |
| Optimiza |
| Integrated Technology Group (ITG) |
| ProgressSoft Corporation |
| Specialized Technical Services Company (STS) |
| Others |
Pricing and Supply Chain Analysis
Cloud architecture talent concentration in Amman and Zarqa corridors drives labor-cost differentials that widen pricing-tier spreads between premium managed services and commodity IT support. Central Bank of Jordan cybersecurity certification requirements compress margins for uncertified providers while inflating premiums for audited specialists.
Pricing Analysis
Short lead-time premiums dominate managed security services as Central Bank operational resilience mandates compress procurement windows for compliant providers. Three-tier pricing structure across certified premium, standard managed, and economy support levels reflects audit investment recovery. Pricing pressure stems from Gulf-based competitors recruiting Jordanian specialists at elevated compensation. Mid-market manufacturing clusters in Zarqa exhibit highest price sensitivity; Amman-based financial institutions demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced semiconductor components feeding data center infrastructure. Hardware procurement draws from China for networking equipment, USA for enterprise software licensing, and regional UAE hubs for cloud compute capacity. Tariff exposure on ICT equipment imports through Aqaba Special Economic Zone threatens margin stability. Distribution runs through carrier-direct channels for fiber connectivity, systems integrators for enterprise transformation, and hyperscaler marketplaces for cloud services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Jordan ICT Market functions as a cost-of-compliance story where Central Bank of Jordan cybersecurity mandates erect barrier-to-entry moats favoring certified incumbents with established audit histories.
For Market Incumbents: Deepen vertical integration into sovereign cloud infrastructure to defend against hyperscaler localization partnerships. Expand Zarqa industrial corridor presence before manufacturing IoT demand matures. Certification investment in Central Bank operational resilience standards anchors pricing power against uncertified competitors. For New Entrants and Emerging Players: AI-powered predictive maintenance platforms offer technology-first wedge into underpenetrated Zarqa manufacturing clusters. Target mid-market enterprises in Irbid governorate with bundled SASE architecture solutions. Partner with Zain Jordan or Orange Jordan for carrier-grade connectivity anchoring. For Investors and Strategic Acquirers: The window for entry favors certified managed security providers with demonstrated Central Bank compliance histories. Long-term viability centers on recurring revenue models displacing project-based professional services. Watch Zarqa Chamber of Industry SME technology adoption program expansion as inflection signal for industrial IoT demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Hyperscaler alliances with local hosting providers satisfy Ministry of Digital Economy data residency mandates. |
| Acquisition of Specialist Firm | Certified cybersecurity talent pools command premium valuations amid Gulf recruitment competition. |
| Geographic Expansion | Zarqa industrial corridor penetration captures manufacturing IoT demand before competitor saturation. |
| Platform Integration | Converged security-network bundles address mid-market skills gaps driving vendor consolidation. |
| Product Launch | Sovereign cloud regions unlock public sector procurement under Ministry cloud-first directives. |
Research Methodology
Document review covered Telecommunications Regulatory Commission spectrum allocation frameworks, Central Bank of Jordan operational resilience directives, and Ministry of Digital Economy cloud sovereignty guidelines, complemented by interviews with chief technology officers at Amman-based financial institutions, procurement leads at Zarqa manufacturing clusters, cybersecurity practice heads at managed service providers, and network planning directors at carrier operations. Secondary validation drew from hyperscaler capex disclosures, submarine cable landing infrastructure records, and industrial zone technology adoption program documentation. Bottom-up demand modeling triangulated against top-down regulatory mandate timelines.
Market size and growth trajectory outputs reflect segmentation across technology type, application vertical, service delivery model, and end-user scale dimensions. Deployment architecture complexity and compliance certification tier served as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical procurement patterns against policy mandate acceleration curves.
Several conditions sit outside the modeled scope, including potential Telecommunications Regulatory Commission 5G mid-band licensing timeline acceleration, Gulf Cooperation Council regulatory alignment pressures affecting data localization requirements, and unforeseen cybersecurity incident severity affecting enterprise spending prioritization. Forecasts reflect documented assumptions about sovereign infrastructure demand continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Oman ICT Market