
 Global Electric Vehicle Parts and Components Market | 2026-2036
Global Electric Vehicle Parts and Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Vehicle Parts and Components Market Analysis
Cell-to-pack battery architecture is reconfiguring thermal management and structural integration requirements across the supplier base. Contemporary Amperex Technology Co. Ltd leverages its position in cell chemistry innovation to anchor high-volume contracts with European and Asian OEMs. Robert Bosch GmbH competes through its integrated power electronics and motor control systems, while Denso Corporation specializes in thermal management components that address the heat-density challenges of next-generation battery formats.
Electric vehicle parts and components encompass electrochemical energy storage systems, electromagnetic propulsion units, power conversion electronics, and conductive charging interfaces, with lithium-ion cells typically operating at nominal voltages of 300-800V depending on vehicle class and performance tier. The primary industrial purpose centers on replacing hydrocarbon combustion with grid-delivered electricity for road transport propulsion. Battery systems command the dominant share of component value, with lithium and copper materials facing supply constraints as OEMs and Tier-1 Suppliers scale production commitments. Permanent magnet motor technology leads in traction applications, though switched reluctance designs are gaining ground in commercial vehicle segments where rare-earth price volatility drives sourcing diversification.
The EPA tailpipe emissions standards in the United States, the EU Green Deal's 2035 ICE phase-out mandate, and China's MIIT new energy vehicle production quotas collectively determine market access timelines and product certification requirements for component suppliers. REACH and RoHS compliance in Europe, alongside China's GB standards for battery safety, add layer complexity to cross-border component flows. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of platform standardization versus regional customization strategies.
Market Dynamics
Cell-to-pack battery architecture is collapsing traditional module boundaries and forcing Tier-1 suppliers to requalify thermal management and structural bonding processes at unprecedented speed. This single engineering shift is redistributing value from module assemblers toward cell manufacturers and integrators with in-house simulation capabilities.
Growth Catalysts
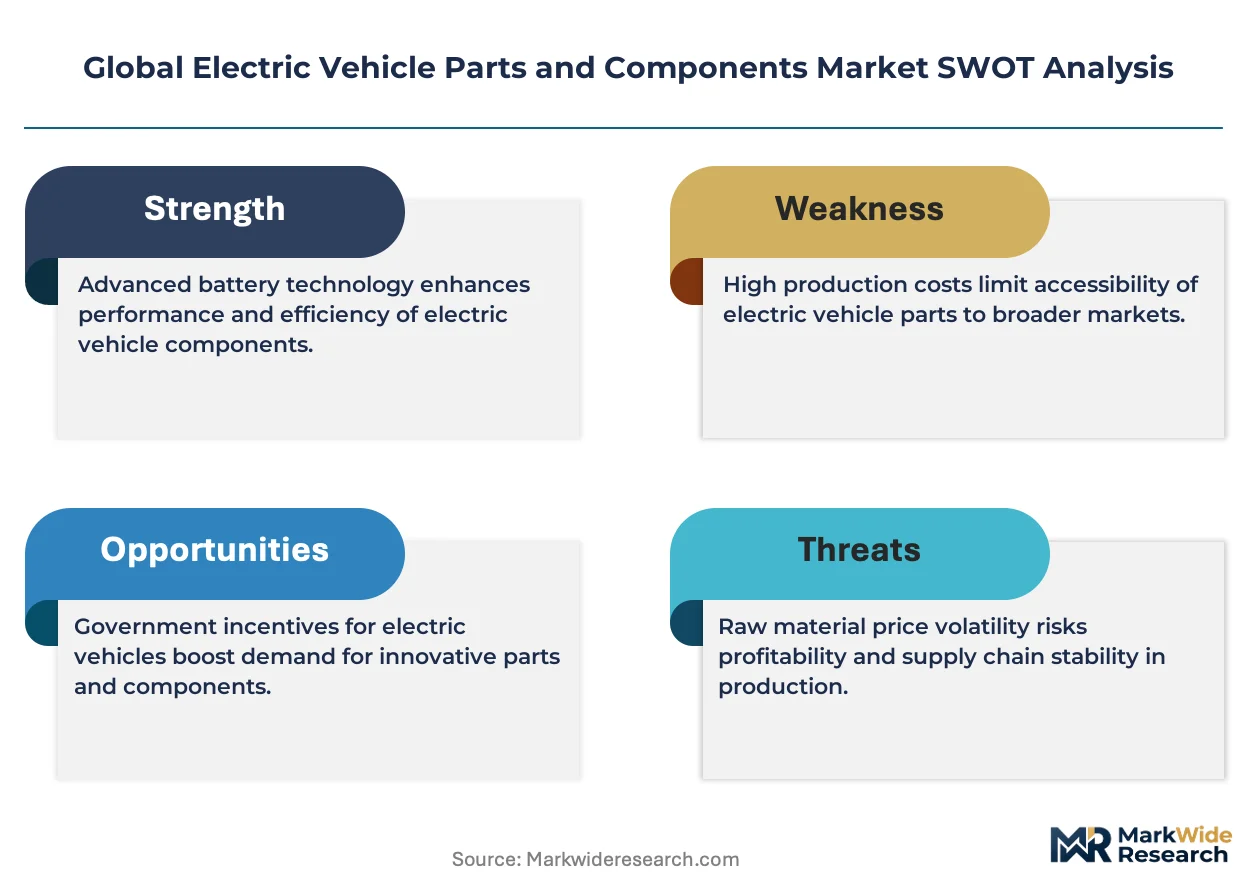
- EU Green Deal ICE Phase-Out:The 2035 mandate for zero-emission new vehicle sales is compressing platform development cycles and forcing component suppliers to accelerate electrification roadmaps for powertrain and thermal systems.
- Lithium Refining Concentration in Chile and Australia:Downstream offtake agreements with integrated mining-conversion operations are securing cathode material supply chains for high-nickel chemistries targeting premium passenger segments.
- 800V Architecture Migration:Premium OEMs are specifying higher-voltage platforms to enable faster DC charging, driving demand for silicon carbide power electronics and reinforced insulation systems across the supplier base.
Market Restraints
- Rare Earth Magnet Supply Concentration:Permanent magnet motor production depends on neodymium-dysprosium supply chains concentrated in Chinese refining operations, exposing traction motor suppliers to price volatility and export control risks.
- Copper Cathode Cost Structure:Winding materials for high-efficiency motors and busbar interconnects face sustained input cost pressure from electrification demand competing with grid infrastructure and renewable energy buildouts.
- REACH Chemical Compliance Friction:European substance restrictions on flame retardants and electrolyte additives are forcing reformulation of thermal interface materials and battery pack sealants with extended qualification timelines.
Strategic Opportunities
- India PLI Scheme for ACC Manufacturing:Production-linked incentives for advanced cell chemistry plants are attracting component suppliers to establish localized electrode coating and separator production serving domestic two-wheeler and commercial vehicle electrification.
- Vehicle-to-Grid Integration:Bidirectional charging hardware and grid communication protocols represent an emerging component category as fleet operators seek revenue streams from energy arbitrage and frequency regulation services.
- Solid-State Electrolyte Convergence:Sulfide and oxide ceramic separator technologies are opening qualification pathways for next-generation cell architectures with enhanced energy density and reduced thermal runaway risk.
Industry Challenges
- Functional Safety Certification Burden:ISO 26262 ASIL-D compliance for battery management systems and motor controllers requires dedicated hardware architectures and documentation rigor that extends development cycles by 12-18 months.
- Electrification Talent Scarcity:Power electronics design, cell electrochemistry, and thermal simulation expertise command premium compensation as automotive suppliers compete with energy storage and renewable energy sectors for equivalent skill profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Vehicle Parts and Components Market |
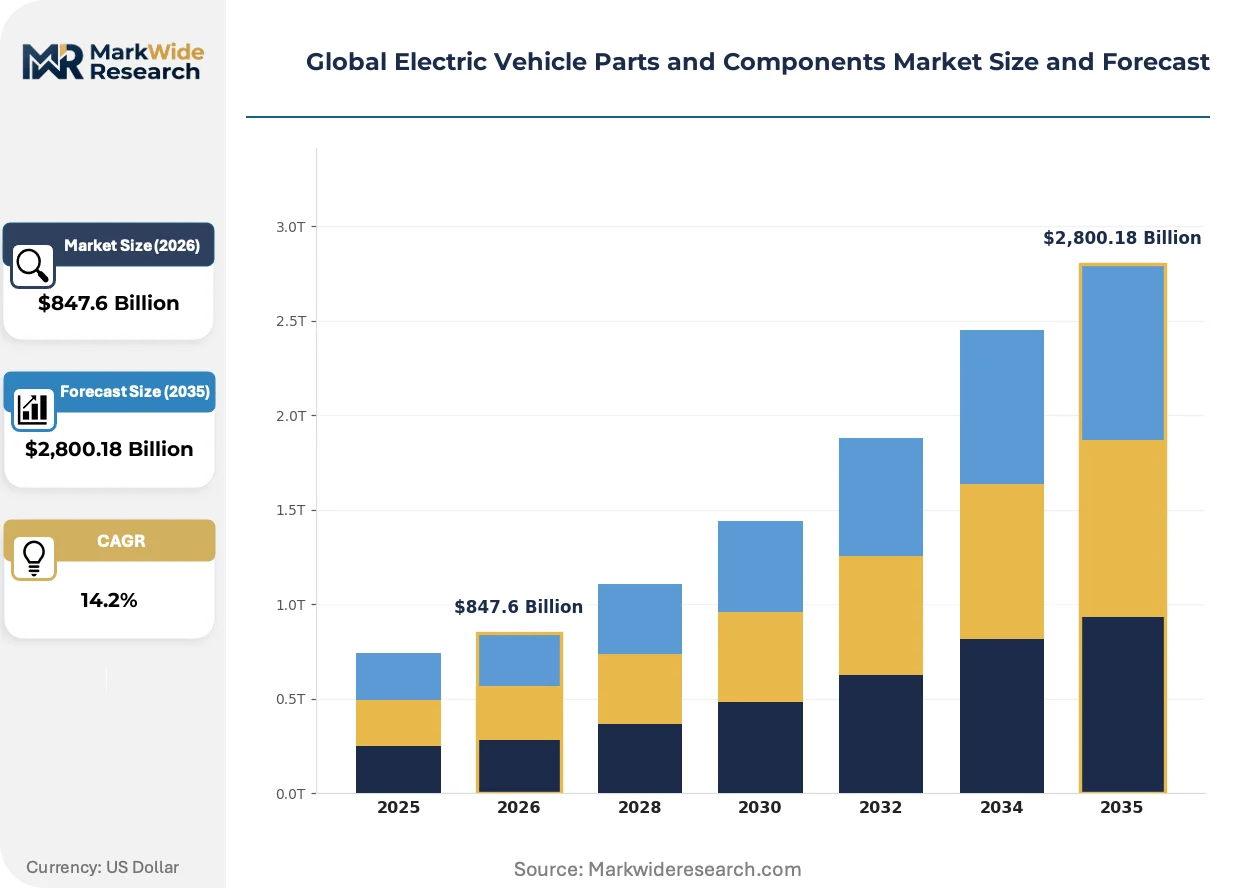
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,800.18 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Battery, Electric Motor, Inverter, Charger Material: Lithium, Copper, Aluminum, Steel Technology: Switched Reluctance, Permanent Magnet, Induction, Li-ion End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Contemporary Amperex Technology Co. Ltd, LG Energy Solution Ltd, Robert Bosch GmbH, BYD Co. Ltd, Panasonic Holdings Corp, Denso Corporation, Continental AG, Hyundai Mobis Co. Ltd, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Vehicle Parts and Components Market Emerging Trajectories
Electrification is forcing convergence between automotive-grade reliability requirements and consumer electronics speed-to-market expectations. Suppliers must now validate components across wider temperature and vibration envelopes while compressing qualification schedules.
Silicon carbide MOSFETs are replacing insulated-gate bipolar transistors in traction inverters to cut switching losses and enable higher power densities. Commercial vehicle manufacturers are specifying SiC-based systems for heavy-duty applications where thermal efficiency translates directly to range and payload capacity. This transition is hybridizing the supplier base as semiconductor foundries and automotive Tier-1s form joint development agreements for custom power module packaging.
China's MIIT battery safety GB standards are mandating nail penetration, overcharge, and thermal propagation tests that exceed UN ECE R100 requirements. Cell manufacturers serving the Chinese market must redesign venting mechanisms and separator materials to comply. European suppliers exporting to China are establishing parallel qualification tracks rather than attempting unified global designs.
Fleet operators are consolidating supplier relationships around integrated subsystem providers capable of warranting complete electric powertrain performance. Single-source contracting for motor-inverter-reducer combinations is displacing discrete component procurement in commercial vehicle segments. This concentration is most visible in Germany's logistics hub regions where large fleet managers negotiate direct with powertrain integrators bypassing traditional distribution channels.
Global Electric Vehicle Parts and Components Market Segmentation
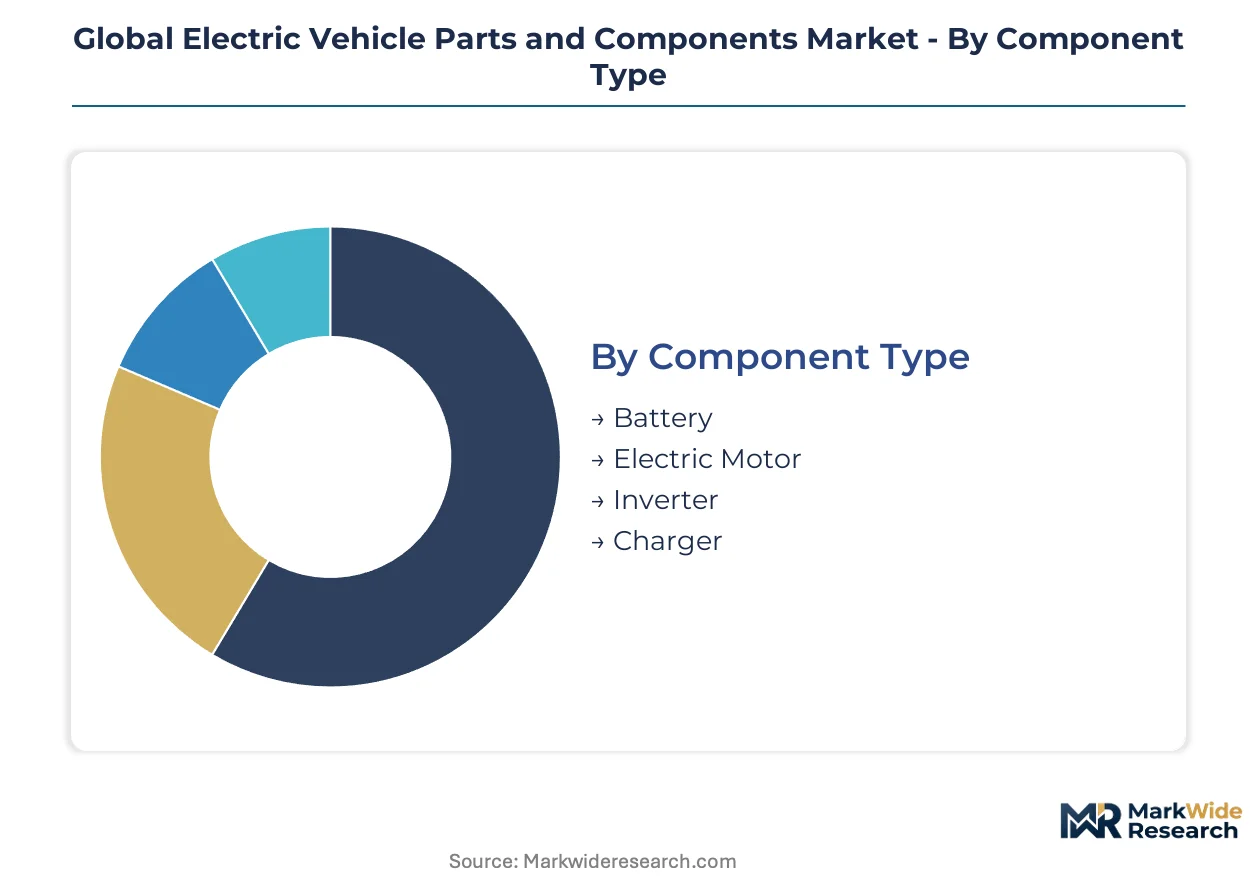
Component segmentation in the electric vehicle supply chain determines procurement hierarchies, margin structures, and qualification timelines. Suppliers position across multiple segment boundaries simultaneously, creating overlapping competitive sets that defy simple categorization.
Component Type:
Mature battery systems anchor value concentration while emerging charger architectures reshape infrastructure deployment economics.
- Battery:Electrochemical energy storage systems utilizing lithium-ion cells with nickel-cobalt-manganese or lithium-iron-phosphate cathode chemistries. Pack assembly in China's Yangtze River Delta and Germany's supplier corridor concentrates procurement for European and Asian OEM platforms, with cell-to-pack architectures collapsing traditional module boundaries.
- Electric Motor:Electromagnetic propulsion units converting electrical to mechanical energy through permanent magnet or reluctance topologies. Demand clusters around Stuttgart's automotive engineering ecosystem for premium passenger applications, where torque density specifications and rare-earth magnet supply security drive sourcing decisions.
- Inverter:Power electronics modules managing DC-AC conversion for traction motor control.
- Charger:Onboard and offboard conductive charging interfaces spanning 7kW AC to 350kW DC capabilities.
Battery handles the majority of throughput; charger is the fastest mover on share.
Material:
Cost tier differentiation separates commodity metals from engineered materials with supply concentration risks.
- Lithium:Light alkali metal extracted from brine pools and hard-rock spodumene deposits, refined into carbonate and hydroxide salts for cathode precursor production. Chilean and Australian refining operations dominate cathode material supply chains for high-nickel chemistries targeting premium segments.
- Copper:High-conductivity metal for motor windings, busbar interconnects, and charging infrastructure conductors. Electrification demand competes with grid infrastructure and renewable energy buildouts for finite cathode supply.
- Aluminum:Lightweight structural material for battery enclosures and motor housings.
- Steel:High-strength alloys for chassis integration and crash protection structures.
Lithium commands the steepest price volatility exposure; aluminum is climbing fastest on substitution demand.
Technology:
Application requirements dictate motor topology selection across passenger and commercial vehicle segments.
- Permanent Magnet:Synchronous motors utilizing neodymium-iron-boron or ferrite magnets delivering peak efficiency and power density. Neodymium-dysprosium supply chains concentrated in Chinese refining operations expose traction motor suppliers to export control risks and price volatility.
- Switched Reluctance:Magnet-free motors operating through rotor saliency and controlled reluctance torque production. Commercial vehicle manufacturers in North America specify these designs specifically to eliminate rare-earth dependencies in heavy-duty powertrains.
- Induction:Asynchronous motors with copper or aluminum rotor cages for cost-sensitive applications.
- Li-ion:Rechargeable electrochemical cells with organic liquid electrolytes and intercalation electrodes.
Permanent magnet retains volume leadership; switched reluctance is expanding most quickly in commercial segments.
End User:
Customer type determines contract structures, warranty obligations, and technical specification authority.
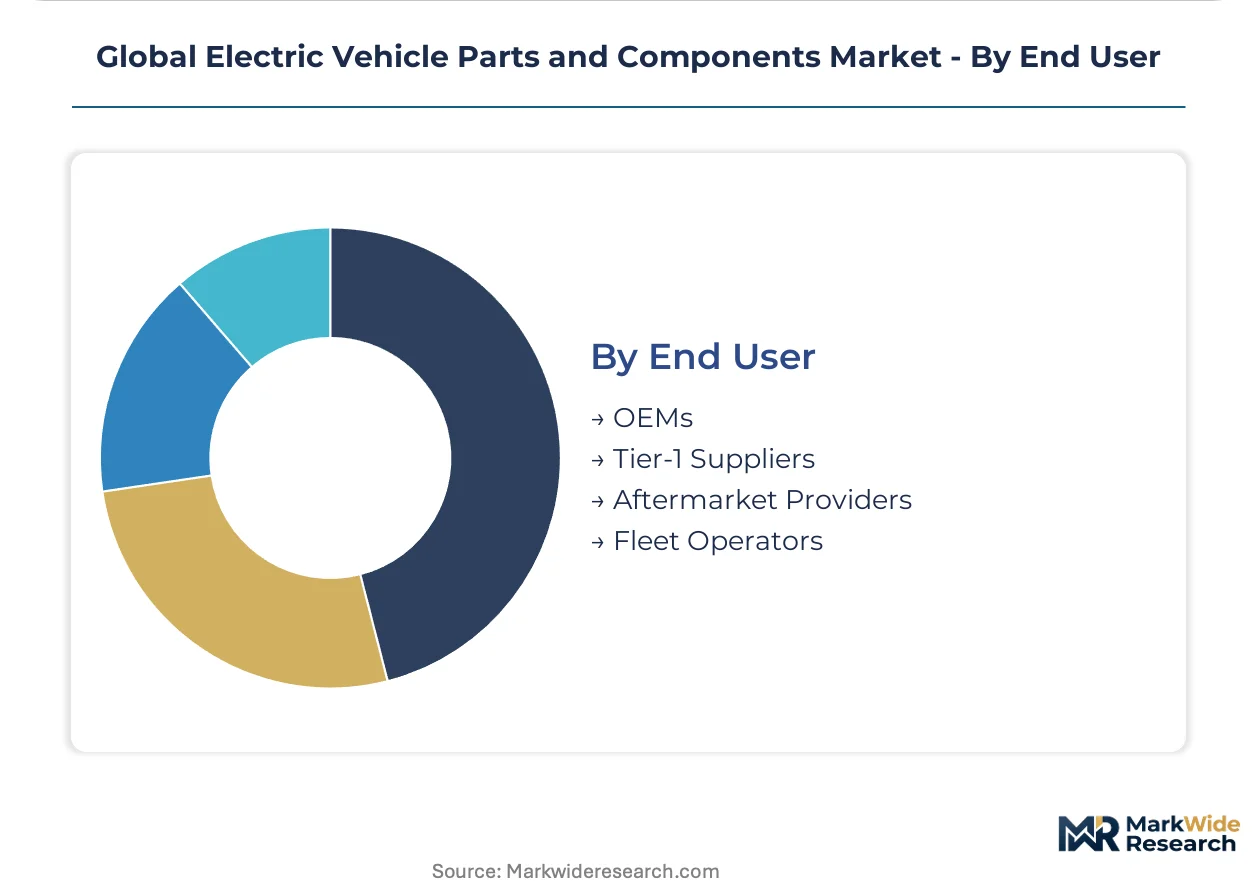
- OEMs:Vehicle manufacturers holding final assembly responsibility and brand accountability. Volkswagen Group and BYD negotiate direct with cell manufacturers and powertrain integrators, compressing traditional Tier-1 margins through platform consolidation strategies.
- Tier-1 Suppliers:Integrated subsystem providers warranting complete electric powertrain performance. Robert Bosch GmbH and Denso Corporation compete through motor-inverter-reducer combinations that displace discrete component procurement in Germany's logistics hub regions.
- Aftermarket Providers:Independent distributors and service networks supporting vehicle lifecycle maintenance.
- Fleet Operators:Commercial vehicle aggregators consolidating supplier relationships around total cost of ownership metrics.
OEMs direct the majority of specification authority; fleet operators are gaining share fastest on procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers export powertrain systems to Asian OEMs through established trade corridors, while Chinese cell manufacturers redirect capital toward European production bases to circumvent tariff exposure.
China
NEV production quotas from MIIT compress ICE phase-out timelines and redirect supplier investment toward advanced cell chemistry plants. Dual carbon goals mandate domestic OEMs source from localized electrode coating operations. The Yangtze River Delta concentrates pack assembly capacity serving both domestic platforms and export contracts.
Germany
Volkswagen Group and BMW negotiate direct with powertrain integrators, compressing traditional Tier-1 margins through platform consolidation. EU Green Deal ICE phase-out mandates force component suppliers to accelerate electrification roadmaps for thermal systems. Stuttgart's supplier corridor anchors traction motor development for premium passenger segments.
United States
EPA tailpipe emissions standards determine market access timelines for battery and motor suppliers targeting domestic OEM platforms. The Inflation Reduction Act domestic content provisions reshape cathode material sourcing decisions. Michigan and Ohio industrial clusters host motor winding and inverter assembly operations serving Detroit-based manufacturers.
South Korea
Hyundai Motor Group and Kia consolidate supplier relationships around integrated electric powertrain subsystems. MFDS-equivalent automotive safety regulators enforce battery management system certification requirements. The Seoul Capital Area concentrates power electronics design centers competing for silicon carbide inverter contracts.
India
PLI scheme incentives for advanced cell chemistry plants attract electrode coating and separator production investments. Domestic two-wheeler and commercial vehicle electrification drives demand for localized motor controller manufacturing. Gujarat and Tamil Nadu host emerging pack assembly operations serving Mahindra and Tata Motors platforms.
Global Electric Vehicle Parts and Components Market Vendor Landscape
On the supply side, the industry is consolidating around integrated subsystem providers capable of warranting complete electric powertrain performance. Cell manufacturers and semiconductor foundries form joint development agreements that hybridize traditional Tier-1 boundaries. Three archetypes dominate: chemistry-led cell specialists, power electronics integrators, and thermal management subsystem providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure cathode material offtake and silicon carbide wafer supply.
Among Asia-based energy storage specialists, Contemporary Amperex Technology Co. Ltd and LG Energy Solution Ltd occupy positions anchoring high-volume cell supply contracts. Robert Bosch GmbH exemplifies the integrated power electronics archetype within the European supplier base. These three entities represent distinct strategic postures: chemistry innovation leadership, scale-driven manufacturing, and systems integration capability.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Ltd |
| LG Energy Solution Ltd |
| Robert Bosch GmbH |
| BYD Co. Ltd |
| Panasonic Holdings Corp |
| Denso Corporation |
| Continental AG |
| Hyundai Mobis Co. Ltd |
| BorgWarner Inc. |
| Others |
Supply Flow & Price Mechanics
Rare-earth magnet supply concentration in Chinese refining operations determines both pricing tier spreads across permanent magnet motor categories and supply chain shape through forced dual-sourcing strategies. Cell manufacturers and Tier-1 suppliers face compressed margins as neodymium-dysprosium price volatility feeds back into motor controller procurement decisions and thermal management subsystem bundling economics.
Pricing Analysis
800V architecture migration widens pricing spreads between silicon carbide traction inverters and legacy IGBT systems, with premium passenger OEMs absorbing technology premiums while commercial fleet operators negotiate volume-scaled standard-tier contracts. Price differentiation hinges on ASIL-D functional safety certification tier and cathode material chemistry grade, with high-nickel NCM cells commanding structural premiums over LFP alternatives. Cost compression in entry-level two-wheeler segments intensifies as Indian and Southeast Asian OEMs consolidate supplier relationships around localized motor controller manufacturing. Fleet operators exhibit highest price sensitivity through total cost of ownership modeling, whereas premium passenger OEMs prioritize energy density specifications over unit economics.
Supply Chain Analysis
Extended payment terms from Volkswagen Group and BYD strain working capital across German and Chinese Tier-1 suppliers, accelerating supply-chain finance facility adoption among electrode coating and separator producers. Manufacturing concentration centers on China's Yangtze River Delta, Germany's Stuttgart corridor, and South Korea's Seoul Capital Area, with lithium hydroxide and copper cathode inputs drawing from Chilean-Australian refining operations and Zambian-DRC mining complexes. Single-source vulnerability in silicon carbide wafer supply exposes power electronics integrators to foundry allocation constraints. Distribution runs through direct OEM contracting for battery pack assemblies, bypassing traditional automotive distribution channels in commercial vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal ICE phase-out mandates and China's MIIT NEV production quotas compress electrification timelines, creating a high-growth disruption window as chemistry innovation and power electronics convergence reshape component procurement hierarchies.
For Market Incumbents: Entrench market position through backward integration into cathode material precursor production and captive silicon carbide wafer supply arrangements. Robert Bosch GmbH and Denso Corporation demonstrate defensive consolidation through motor-inverter-reducer subsystem bundling that displaces discrete component suppliers. Capacity expansion in India's Gujarat and Tamil Nadu industrial corridors counters emerging local competitors attracted by PLI scheme incentives. For New Entrants and Emerging Players: Mid-market commercial vehicle powertrain retrofits in India's logistics corridors represent the most penetrable entry point, with second-life battery repurposing for stationary storage offering parallel white-space capture. Solid-state electrolyte component qualification for sulfide and oxide ceramic separators opens technical differentiation pathways against established liquid electrolyte incumbents. Go-to-market execution should anchor on fleet operator direct contracting relationships that bypass entrenched Tier-1 distribution channels. For Investors and Strategic Acquirers: Thermal management subsystem specialists with in-house simulation capabilities and GB standards compliance expertise present attractive acquisition profiles as cell-to-pack architectures redistribute value from module assemblers. Long-term viability assessment should frame five-to-ten year holding periods around chemistry convergence timelines and regional production localization imperatives. Monitor EPA tailpipe emissions standard stringency adjustments and IRA domestic content provision enforcement as primary inflection indicators for North American supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell-to-pack architectures force direct cathode material offtake negotiations with Chilean and Australian refiners. |
| Silicon Carbide Foundry Partnership | Joint development agreements between semiconductor foundries and Tier-1s hybridize traditional supplier boundaries. |
| Platform Standardization | OEM consolidation around 800V architectures reduces power electronics variant complexity and qualification overhead. |
| Geographic Manufacturing Footprint | European production bases for Chinese cell manufacturers circumvent tariff exposure under EU Green Deal implementation. |
| Charging Infrastructure Partnership | Bidirectional charging hardware integration opens fleet operator revenue streams from grid services arbitrage. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, and aftermarket distributors, combined with secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs trade records. Bottom-up component demand modeling triangulated against top-down OEM electrification roadmap analysis ensured cross-verification of volume assumptions across the projection horizon.
Forecast inputs incorporated vehicle class segmentation, propulsion architecture differentiation, and content-per-vehicle trajectories across passenger and commercial categories. CAGRs were derived through regression analysis of historical production volumes against regulatory mandate timelines and OEM platform commitment disclosures. Silicon carbide adoption curves and solid-state electrolyte qualification pathways provided technology-specific forecast modifiers.
Practitioners should monitor EPA standard adjustments, EU Green Deal implementation pacing, and MIIT quota modifications for early signals of forecast deviation. Macroeconomic commodity price shocks in lithium and copper markets, regulatory divergence between REACH and GB standards, or technological breakthroughs in sodium-ion chemistry would prompt revision of underlying assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Steering Gear Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Towing Ropes Market