
 North America Cargo Inspection Market | 2026-2036
North America Cargo Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cargo Inspection Market Analytics
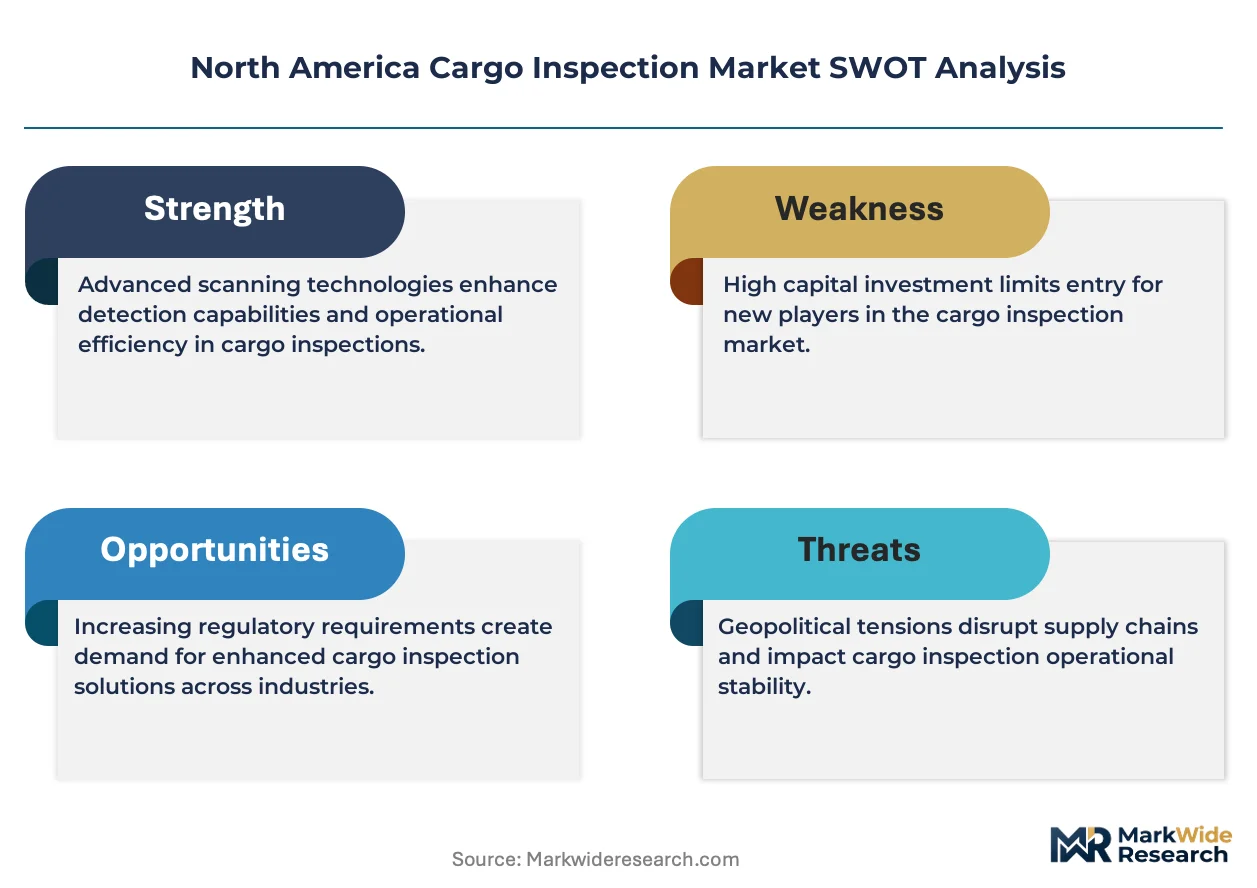
Project finance for port infrastructure and third-party leasing of scanning equipment is fragmenting the competitive landscape in North America cargo inspection. Bureau Veritas leverages its laboratory network across US and Canadian port cities to sustain chemical testing contracts with petrochemical shippers. SGS Group anchors its position through geographic dominance in Mexican customs facilitation and cross-border agricultural inspection. Cotecna competes by specializing in mobile scanner deployment for mid-sized breakbulk terminals along the Mississippi River system.
North America cargo inspection encompasses the systematic verification of freight integrity, safety, and regulatory compliance through physical, chemical, and radiological assessment protocols, typically employing gamma-ray spectroscopy, gas chromatography, and non-intrusive imaging to detect contraband, hazardous materials, or tariff misclassification. X-ray scanning commands the largest equipment-installed base among inspection methods, though chemical testing generates superior margins due to specialized laboratory infrastructure and certified personnel requirements. Containerized cargo drives the highest absolute inspection volume, while bulk cargo inspection is expanding fastest as US grain and mineral export terminals modernize detection capabilities to satisfy FMSA and APHIS protocols.
US CBP, Transport Canada, and Mexico's SAT collectively shape demand through harmonized cargo security standards under the USMCA framework, with each agency mandating distinct documentation and physical inspection thresholds for cross-border freight. FDA and USDA APHIS regulations further dictate inspection intensity for agricultural and pharmaceutical shipments entering US ports. Stakeholders must monitor how evolving AI-enabled detection standards and shifting trade corridor volumes between Pacific and Gulf Coast gateways reshape capital allocation priorities for inspection infrastructure.
Market Dynamics
US CBP security mandates are compressing inspection timelines while expanding the scope of required detection protocols, forcing logistics operators to accelerate capital deployment into automated screening infrastructure across Gulf Coast and Pacific gateway ports.
Growth Catalysts
- USMCA Harmonization:The trilateral trade framework mandates standardized cargo security documentation across US, Canadian, and Mexican borders, reducing inspection redundancy and accelerating cross-border freight velocity.
- Petrochemical Corridor Expansion:Bulk liquid terminals along the Texas-Louisiana chemical processing belt require intensive chemical testing and radiation scanning to satisfy FMSA hazardous materials protocols.
- Machine Vision Integration:AI-enabled detection algorithms are replacing manual image interpretation in container screening, compressing inspection cycles from hours to minutes at high-volume terminals.
Market Restraints
- Certified Personnel Scarcity:Chemical testing protocols require ISO-certified laboratory technicians, creating bottlenecks in US Gulf Coast and Great Lakes port cities where training pipelines lag demand.
- Equipment Import Concentration:Gamma-ray spectroscopy and non-intrusive imaging hardware rely on concentrated Asian manufacturing supply chains, exposing procurement timelines to geopolitical friction.
- Legacy System Interoperability:Existing X-ray scanning infrastructure at mid-sized Mississippi River breakbulk terminals cannot interface with newer AI detection platforms without complete hardware replacement.
Strategic Opportunities
- Canadian Arctic Gateway Development:Climate-driven shipping season extension through the Northwest Passage creates first-mover advantage for mobile inspection deployment at emerging Nunavut and Yukon port facilities.
- Pharmaceutical Cold Chain Mandates:FDA temperature integrity requirements for biologic imports are expanding inspection scope beyond security screening into environmental monitoring at US border crossings.
- Drone-Deployed Radiation Detection:Unmanned aerial systems carrying spectroscopic sensors are enabling perimeter screening of agricultural bulk terminals without disrupting ground operations.
Industry Challenges
- Cyber-Physical System Vulnerabilities:Networked scanning equipment at US and Mexican customs facilities faces escalating ransomware exposure as CBP mandates real-time data transmission to centralized threat databases.
- APHIS Certification Backlogs:Agricultural inspection clearances for grain and mineral exports are accumulating multi-week delays at Pacific Northwest terminals due to inspector capacity constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cargo Inspection Market |
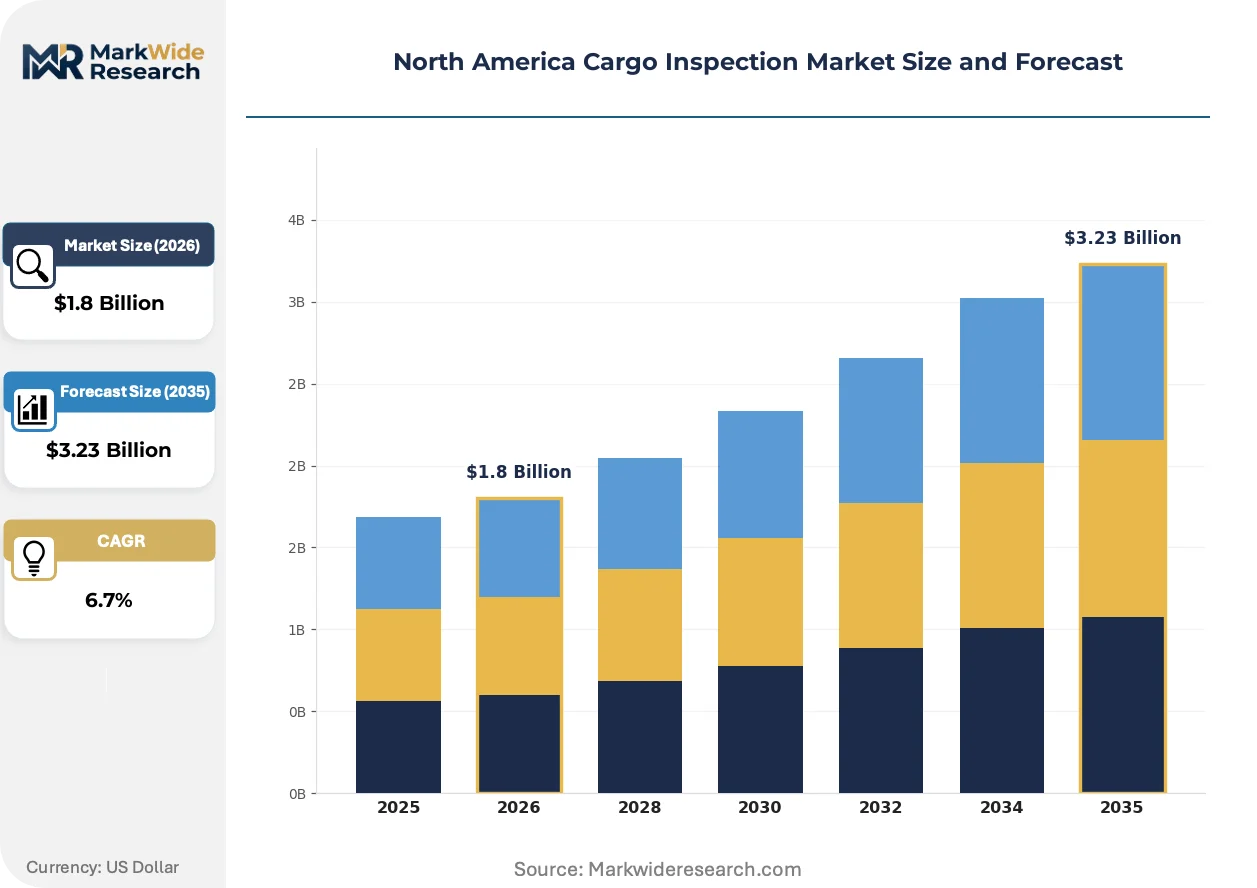
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Inspection Method: Visual Inspection, X-Ray Scanning, Ultrasound, Chemical Testing Cargo Type: Containerized Cargo, Bulk Cargo, Breakbulk Cargo, Liquid Cargo End User Sector: Government Agencies, Logistics Companies, Shipping Lines, Importers Technology: Automated Systems, Manual Inspection, RFID Technology, Mobile Scanners |
| Companies Covered | SGS Group, Bureau Veritas, Intertek Group, Cotecna, ALS Limited, Camin Cargo Control, Alex Stewart International, Swiss Approval International, AHK Group Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cargo Inspection Market Evolving Landscape
Detection technology convergence with artificial intelligence is compressing inspection cycles while expanding the categories of contraband and hazard that automated systems can identify without human intervention.
Dual-energy X-ray absorptiometry systems equipped with material discrimination algorithms are penetrating dense cargo loads to differentiate organic from inorganic substances. US Gulf Coast petrochemical terminals are deploying these platforms at twice the rate of Pacific container gateways. Conventional single-energy radiography is rendering obsolete for high-value chemical shipments where misclassification carries tariff and safety penalties.
APHIS and FDA are mandating blockchain-anchored documentation trails for agricultural and pharmaceutical imports, creating immutable inspection records accessible to customs agencies across USMCA borders. This regulatory architecture forces terminal operators to integrate distributed ledger verification into existing cargo release workflows. Mexican agricultural exporters face the steepest compliance curve as SAT digitizes phytosanitary certificates ahead of US and Canadian implementation timelines.
Third-party inspection service contracts are fragmenting from annual retainers toward per-container pricing indexed to cargo value and risk tier. Mid-sized breakbulk operators along the Mississippi River system are abandoning fixed-cost laboratory relationships in favor of mobile scanner leasing with usage-based billing. Canadian Prairie grain terminals exhibit the most pronounced shift toward variable inspection economics as export volumes fluctuate with commodity price cycles.
North America Cargo Inspection Market Segmentation
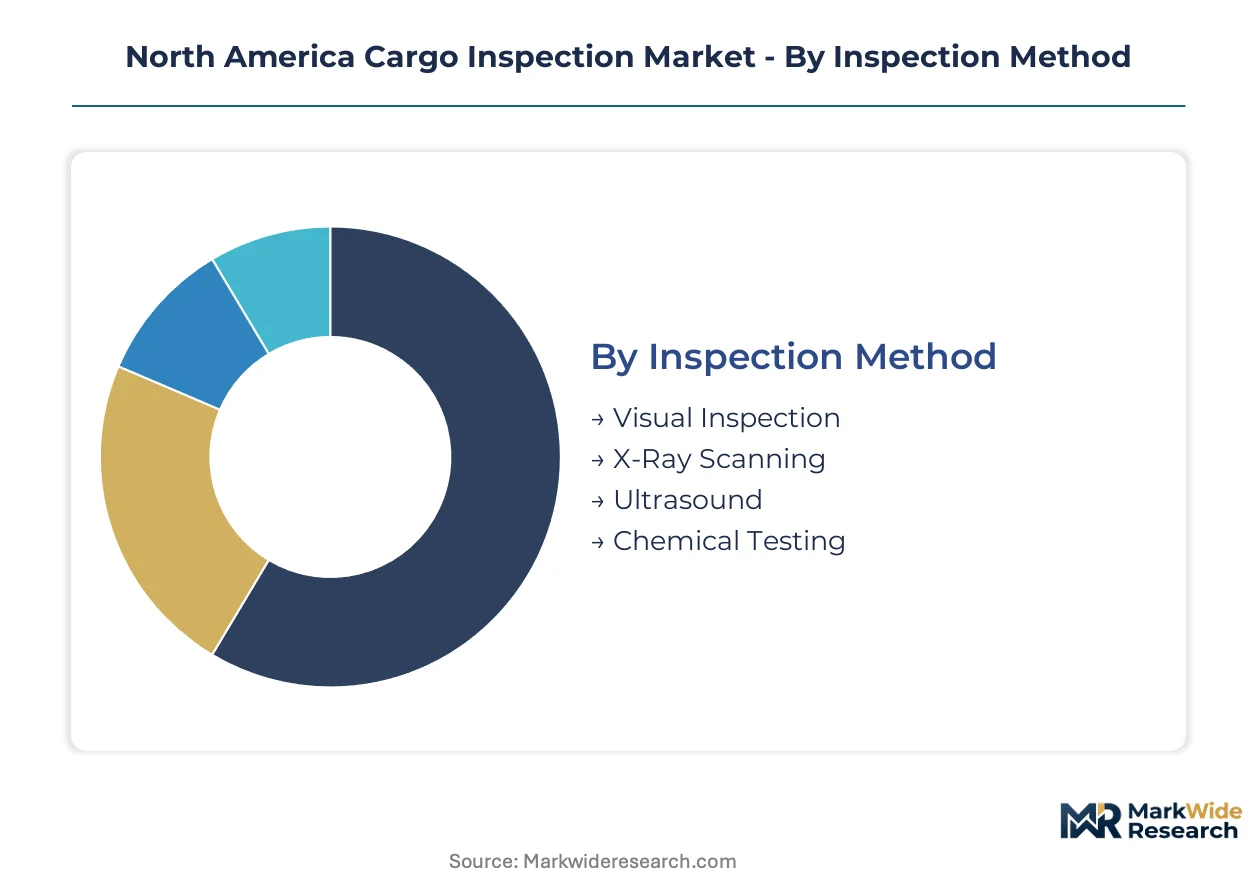
Cargo inspection segmentation in North America reflects divergent capital intensity and regulatory exposure across methods, cargo forms, and technology platforms. Inspection cycle times vary dramatically—from minutes for automated container screening to days for laboratory chemical analysis—shaping procurement patterns and vendor contract structures.
Inspection Method:
X-ray scanning turns over fastest with near-real-time throughput, while chemical testing cycles stretch across multi-day laboratory protocols. Visual inspection occupies the middle ground with inspector-dependent variability.
- X-Ray Scanning:Gamma-ray and dual-energy radiography systems penetrate dense cargo loads to differentiate organic from inorganic materials. US Gulf Coast petrochemical terminals deploy these platforms at twice the rate of Pacific container gateways to satisfy CBP non-intrusive inspection mandates.
- Chemical Testing:Gas chromatography and spectroscopic analysis identify hazardous material composition, tariff misclassification, and FMSA compliance violations. ISO-certified laboratory infrastructure concentrates in Houston, Corpus Christi, and Lake Charles where bulk liquid terminals require intensive hazardous materials verification.
- Visual Inspection:Physical examination by certified customs personnel remains mandatory for agricultural shipments under USDA APHIS protocols.
- Ultrasound:Acoustic imaging detects internal structural defects in sealed containers and tank walls without cargo disruption.
X-ray scanning dominates installed base. Chemical testing is where expansion concentrates.
Cargo Type:
Capital deployment intensity separates high-volume container flows from specialized bulk and liquid handling infrastructure requiring dedicated detection equipment.
- Containerized Cargo:Standardized twenty-foot and forty-foot units drive absolute inspection volume across Pacific and Atlantic gateway ports. CBP Automated Targeting System directs risk-based screening toward high-value electronics and pharmaceutical shipments entering Los Angeles-Long Beach and Savannah.
- Bulk Cargo:Grain, mineral, and agricultural commodities move through dedicated export terminals in Vancouver, Prince Rupert, and Pacific Northwest ports. APHIS certification requirements for phytosanitary clearance create inspection bottlenecks during peak harvest export windows.
- Liquid Cargo:Chemical tankers and refined petroleum products require specialized radiation scanning and density verification at Texas-Louisiana processing belt terminals.
- Breakbulk Cargo:Project cargo and non-containerized manufactured goods move through Mississippi River system ports with mobile scanner deployment.
Containerized cargo commands the largest equipment footprint. Bulk cargo is climbing the fastest as Canadian Prairie and US Midwest grain terminals modernize detection capabilities.
End User Sector:
Procurement authority splits between sovereign customs agencies mandating inspection protocols and private logistics operators financing compliance infrastructure.
- Government Agencies:US CBP, Transport Canada, and Mexico SAT establish mandatory screening thresholds and detection technology standards under USMCA harmonization frameworks.
- Logistics Companies:Third-party providers and freight forwarders lease mobile scanning equipment to satisfy customer-specific compliance requirements without fixed capital commitment.
- Shipping Lines:Ocean carriers pre-clear cargo through certified inspection facilities to minimize port dwell time and demurrage exposure.
- Importers:Large retailers and manufacturers maintain captive inspection relationships with Bureau Veritas and SGS Group to accelerate customs release.
Government agencies set regulatory baselines. Logistics companies represent the steepest expansion trajectory as third-party inspection contracts fragment toward per-container pricing.
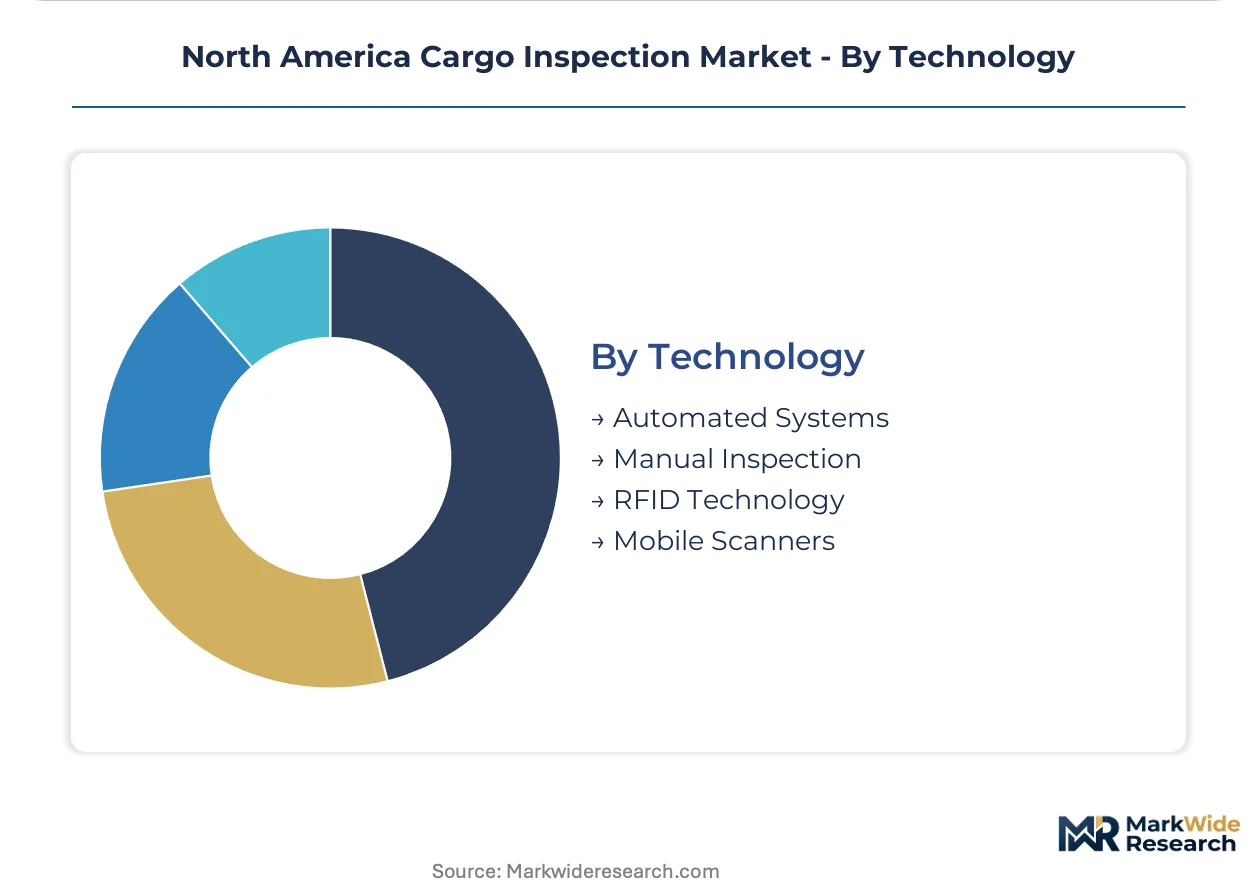
Technology:
Automation penetration separates high-throughput gateway terminals from legacy facilities dependent on manual inspection labor.
- Automated Systems:AI-enabled detection algorithms replace manual image interpretation, compressing container screening cycles from hours to minutes at Los Angeles-Long Beach and New York-New Jersey.
- Mobile Scanners:Truck-mounted gamma-ray units serve mid-sized breakbulk terminals along the Mississippi River system without permanent infrastructure investment.
- RFID Technology:Radio-frequency identification tracks inspection status and documentation compliance across multi-modal supply chains.
- Manual Inspection:Human examiner review persists for agricultural quarantine enforcement and contested tariff classification appeals.
Automated systems anchor new capital deployment. Mobile scanners are gaining share fastest among mid-sized operators avoiding fixed infrastructure commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import intensity varies sharply across North American corridors, with chemical and agricultural flows driving inspection infrastructure investment unevenly between US Gulf terminals, Canadian Prairie grain hubs, and Mexican manufacturing gateways.
United States
US Gulf Coast petrochemical terminals handle the densest concentration of hazardous liquid cargo requiring radiation scanning and chemical verification. CBP Automated Targeting System directs non-intrusive inspection toward high-value electronics and pharmaceutical shipments entering Los Angeles-Long Beach and Savannah. Houston, Corpus Christi, and Lake Charles anchor ISO-certified laboratory capacity where bulk liquid terminals satisfy FMSA protocols through intensive gas chromatography analysis.
Canada
Canadian Prairie grain terminals in Vancouver and Prince Rupert are modernizing detection capabilities to satisfy APHIS phytosanitary certification for export windows. Transport Canada harmonizes cargo security standards with USMCA frameworks while maintaining distinct documentation thresholds for cross-border agricultural freight. Climate-driven shipping season extension through the Northwest Passage creates emerging demand for mobile inspection deployment at Nunavut and Yukon port facilities.
Mexico
Mexican SAT digitizes phytosanitary certificates ahead of US and Canadian implementation timelines, accelerating compliance curves for agricultural exporters. Cross-border manufacturing corridors concentrate customs facilitation demand at Laredo and Tijuana gateways where containerized electronics and automotive components require rapid clearance. SGS Group maintains geographic dominance in SAT-mandated inspection protocols for northbound agricultural and manufactured goods.
North America Cargo Inspection Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in laboratory and mobile equipment niches. The North America cargo inspection market exhibits tiered consolidation among multinational testing giants and regional specialists. Three archetypes dominate: multinational laboratory networks, mobile scanner leasing operators, and customs-facilitation specialists. Competitive positioning hardens through strategic partnerships between terminal operators and inspection vendors, alongside portfolio diversification into AI-enabled detection platforms.
Within the multinational tier, SGS Group, Bureau Veritas, and Cotecna occupy positions shaped by geographic specialization rather than undifferentiated scale. SGS Group exemplifies customs-facilitation dominance through Mexican SAT relationships. Bureau Veritas represents laboratory-network concentration across US and Canadian port cities. Cotecna anchors the mobile deployment archetype for mid-sized breakbulk terminals. Each entity reflects distinct capital allocation: fixed infrastructure versus variable-cost equipment leasing versus government-contract anchoring.
| Leading Market Players |
|---|
| SGS Group |
| Bureau Veritas |
| Intertek Group |
| Cotecna |
| ALS Limited |
| Camin Cargo Control |
| Alex Stewart International |
| Swiss Approval International |
| AHK Group Ltd |
| Others |
Value Network & Pricing Analysis
Overcapacity in Asian gamma-ray spectroscopy manufacturing is compressing equipment procurement timelines and eroding supplier pricing power across US Gulf Coast terminal operators while simultaneously accelerating adoption of usage-based inspection contracts.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by ISO certification grade and after-sales service bundling. Price differentiation hinges on laboratory accreditation tier and geographic proximity to petrochemical corridors. Cost compression in the mid-tier is intensifying because mobile scanner leasing platforms are displacing fixed-cost laboratory relationships. Small breakbulk operators along the Mississippi River system exhibit the highest price sensitivity, while multinational petrochemical shippers prioritize certification tier over unit cost.
Supply Chain Analysis
Export controls on dual-use radiation detection technology limit flows of gamma-ray spectroscopy and non-intrusive imaging hardware from concentrated Asian manufacturing bases. Component sourcing draws from China, South Korea, and Japan for scintillation crystals, detector arrays, and AI-enabled image processing units. Single-source vulnerability concentrates in specialized scintillation material supply chains. Distribution runs through OEM-direct procurement for large terminal operators and third-party leasing platforms for mid-sized breakbulk facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine vision integration represents a high-growth disruption as AI-enabled detection algorithms compress inspection cycles from hours to minutes, forcing capital reallocation across North American port infrastructure.
For Market Incumbents: Harden laboratory network defensibility by deepening ISO-certified technician pipelines in Houston and Corpus Christi to offset certified personnel scarcity. Fortify mobile scanner deployment capabilities along the Mississippi River system against Cotecna's specialization. Vertical integration into AI detection platform development protects margin position as manual image interpretation becomes obsolete.
For New Entrants and Emerging Players: Establish a beachhead in Canadian Arctic gateway development at emerging Nunavut and Yukon port facilities where climate-driven shipping season extension creates first-mover advantage. Penetrate pharmaceutical cold chain inspection services at US border crossings where FDA temperature integrity mandates expand scope beyond security screening. Pursue drone-deployed radiation detection partnerships with agricultural bulk terminal operators seeking perimeter screening without ground operation disruption.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mobile scanner leasing operators serving mid-sized breakbulk terminals with usage-based billing indexed to cargo value and risk tier. Long-term viability favors inspection service providers with diversified technology portfolios spanning automated systems, mobile deployment, and laboratory infrastructure. Monitor AI-enabled detection standard adoption rates at US CBP as the primary inflection indicator for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Detection Platform Integration | Compresses inspection cycles at Los Angeles-Long Beach and New York-New Jersey terminals under CBP mandates. |
| Mobile Scanner Fleet Expansion | Captures variable-cost demand from Mississippi River breakbulk operators abandoning fixed laboratory contracts. |
| Laboratory Network Consolidation | Builds ISO-certified capacity concentration in Houston-Corpus Christi-Lake Charles chemical processing belt. |
| Drone-Deployed Radiation Partnerships | Enables perimeter screening at agricultural bulk terminals without disrupting ground operations under APHIS protocols. |
| Blockchain Documentation Integration | Satisfies FDA and APHIS mandates for immutable inspection records across USMCA borders. |
Research Methodology
A standing panel of CBP compliance officers, terminal operations managers, third-party inspection service executives, and petrochemical logistics directors provided ongoing calibration. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation from US CBP enforcement statistics, Transport Canada trade facilitation reports, SAT digitization disclosures, and customs equipment procurement databases. Bottom-up terminal-level capacity assessments and top-down trade flow analysis were triangulated to establish market sizing.
Scenario-bracketing framed analytical development across the projection horizon. Segmentation dimensions modeled encompass inspection method, cargo type, end user sector, and technology platform. CAGRs were derived from equipment deployment trajectories and contract value expansion patterns. Forecast inputs incorporated USMCA harmonization implementation timelines and AI detection standard adoption curves at major gateway ports.
Stress conditions across trade corridor volume shifts, CBP mandate acceleration, and certified technician supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization pace and technology substitution thresholds. Material shifts in US CBP AI detection procurement timelines or USMCA documentation digitization schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Cargo Transportation Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Thailand E-Commerce Logistics Market