
 Cylindrical Roller Bearings Market | 2026-2036
Cylindrical Roller Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Cylindrical Roller Bearings Market Outlook
Asset-light manufacturing partnerships and third-party bearing service leasing are rewriting competitive entry barriers for mid-tier suppliers. SKF leverages captive steel-forging operations and remanufacturing networks to sustain margin control across Europe and Asia. Schaeffler anchors its position through integrated sensor-bearing units that dominate railway and wind-turbine OEM specifications. Timken competes on tapered-to-cylindrical crossover engineering, occupying niche high-load industrial segments where standard designs fail.
Cylindrical roller bearings are precision-engineered antifriction components with line contact between rollers and raceways, typically manufactured from through-hardened chromium steel with cage-guided or full-complement roller arrangements. They primarily transmit heavy radial loads with minimal deflection in rotating machinery shafts, operating at higher speed tolerances than spherical or needle equivalents. Single-row and double-row configurations lead industrial machinery and automotive applications, while full-complement designs capture the fastest growth in wind-turbine main shaft and gearbox installations where maximum load density outweighs speed limitations. Cage-type bearings retain mature, high-volume positions in standardized OEM supply chains, whereas extra-large segments concentrate margin pools in custom-specified railway and aerospace programs.
FCC and NHTSA emissions and safety mandates in the United States compress automotive bearing tolerances, while EU Green Deal industrial decarbonization targets and REACH material restrictions in Europe reshape alloy composition and lubricant compatibility requirements. Japan's METI energy-efficiency standards and China's GB/T rolling bearing precision classifications further segment product certification tiers across export markets. Stakeholders must monitor electrified drivetrain torque specifications and regional carbon-border adjustment mechanisms to align capacity investments with evolving compliance thresholds.
Market Dynamics
Electrified drivetrain torque specifications are compressing traditional bearing geometries while simultaneously opening premium niches for ceramic-hybrid and sensor-integrated designs that legacy steel architectures cannot satisfy.
Growth Catalysts
- Railway rolling stock expansion:High-speed and freight programs in India and Europe are accelerating procurement of large-diameter bearings for axle and gearbox applications.
- EU Green Deal decarbonization:Industrial machinery OEMs face binding carbon-intensity targets that favor extended-fatigue-life bearings reducing replacement cycles and material waste.
- Ceramic hybrid cage diffusion:Silicon nitride roller elements are penetrating wind-turbine main shafts where maximum load density outweighs speed constraints.
Market Restraints
- Alloy steel price volatility:Chromium and molybdenum input costs swing with ferroalloy supply disruptions, squeezing margin on through-hardened bearing grades.
- REACH material restrictions:ECHA substance-of-very-high-concern listings are forcing reformulation of traditional lubricant additives and surface coatings.
- Spherical bearing substitution:Self-aligning designs capture misalignment-tolerant applications where cylindrical precision becomes over-engineered.
Strategic Opportunities
- Remanufacturing service networks:Asset-light operators in Germany and Japan are leasing bearing lifecycle management to railway operators, capturing recurring revenue streams.
- India PLI scheme alignment:Domestic precision manufacturing clusters can anchor OEM supply contracts for electrified commercial vehicle drivetrains.
- Sensor-bearing convergence:Integrated condition-monitoring units combine vibration sensing with load telemetry for predictive maintenance in wind turbines.
Industry Challenges
- Metallurgical talent scarcity:Vacuum degassing and controlled-atmosphere heat treatment expertise concentrates among aging workforces in Japan and Germany.
- GB/T precision certification timelines:Chinese export-bound products face extended testing protocols for high-speed railway classifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cylindrical Roller Bearings Market |
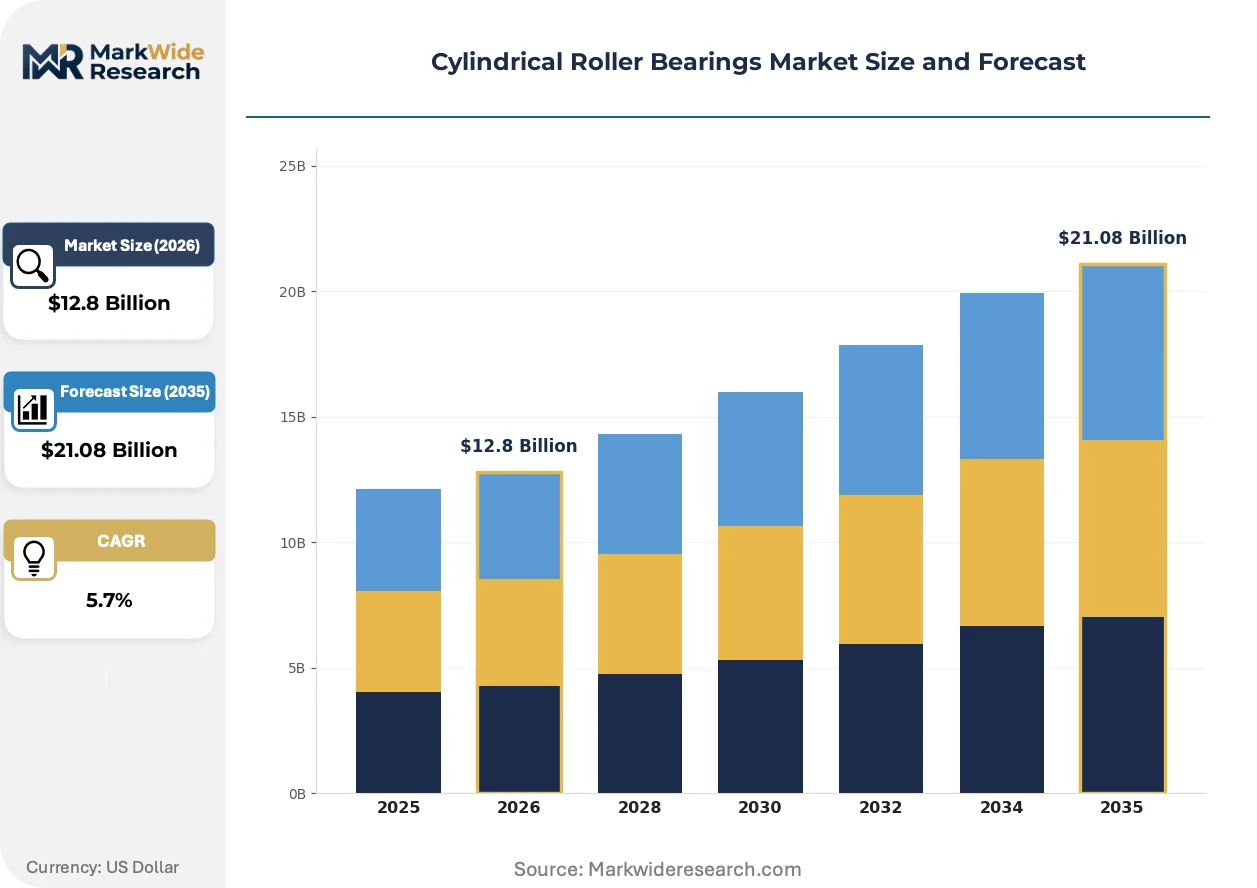
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cage Type, Full Complement, Single Row, Double Row Application: Automotive, Aerospace, Industrial Machinery, Robotics End User: Manufacturers, OEMs, Distributors, Maintenance Providers Size: Small, Medium, Large, Extra Large |
| Companies Covered | SKF, NSK, NTN Corporation, Schaeffler, Timken, JTEKT, National Engineering Industries, KOYO, NACHI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cylindrical Roller Bearings Market Strategic Shifts
Material science advances and embedded intelligence are fragmenting the traditional bearing into a system-level component, with ceramic hybrids and sensor integration redefining value capture away from commodity steel volumes.
Ceramic hybrid cylindrical roller bearings combine silicon nitride rolling elements with steel raceways to extend fatigue life under electrified drivetrain shock loads. Wind-turbine OEMs and high-speed railway operators are adopting these configurations fastest, accepting premium positioning for maintenance-interval extension. The technology is hybridizing product architectures, forcing suppliers to integrate material science capabilities that pure metallurgical players lack.
EU REACH substance restrictions and F-Gas Regulation phase-downs are eliminating perfluoropolyether lubricants and certain anti-corrosion coatings from bearing supply chains. Industrial machinery manufacturers must qualify alternative ion-implanted surfaces and synthetic hydrocarbon greases. German and Japanese precision clusters are absorbing the compliance burden fastest, while emerging suppliers face certification backlogs.
Aftermarket service unbundling is separating bearing supply from installation, monitoring, and remanufacturing contracts. Railway operators in Europe and wind-farm asset managers are procuring lifecycle performance guarantees rather than unit purchases. This reconfiguration concentrates margin with vertically integrated service providers and compresses spot-market spot sales for standardized catalog bearings.
Cylindrical Roller Bearings Market Segmentation
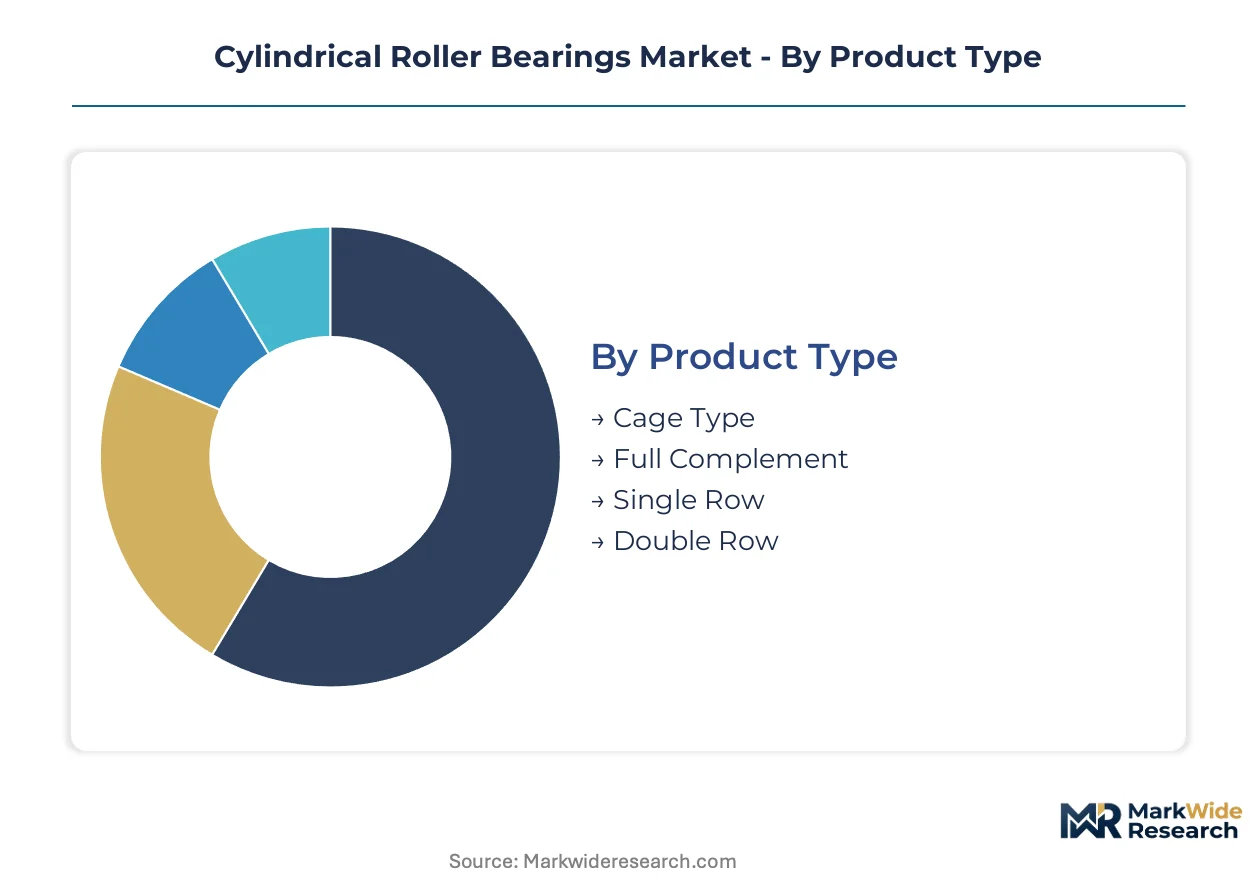
Cylindrical roller bearings fragment into distinct performance tiers that map directly to replacement cycle economics. High-speed cage-type units turn over predictably in automotive lines, while full-complement giants in wind turbines stretch service intervals across decades. Procurement patterns diverge sharply between these extremes, reshaping how suppliers allocate forging capacity and service infrastructure.
Product Type:
Cage-type bearings cycle fastest through replacement schedules, while full-complement designs lock in decades-long service intervals that reshape revenue recognition models.
- Single Row:Through-hardened chromium steel raceways with cage-guided roller arrangements dominate high-volume automotive transmission and electric motor shaft applications. German and Japanese precision clusters anchor OEM supply contracts for electrified drivetrain specifications where METI energy-efficiency standards compress tolerance bands.
- Full Complement:Maximum roller density configurations eliminate cage mass to carry shock loads in wind-turbine main shafts and heavy freight railway axles where speed limits yield to load density. Demand concentrates in extra-large diameter programs across India and Europe where rolling stock expansion accelerates procurement.
- Cage Type:Standardized cage-guided designs retain mature positions in industrial machinery supply chains with predictable replacement cadences.
- Double Row:Paired raceway configurations handle combined radial and axial loads in gearbox and pump applications requiring higher stiffness than single-row equivalents.
Single-row bearings dominate installed base. Full-complement designs are where expansion concentrates.
Application:
Cost tier stratification separates precision-aerospace specifications from price-sensitive automotive volumes, with industrial machinery occupying the contested middle ground.
- Industrial Machinery:Machine tool spindles, rolling mills, and printing presses consume standardized double-row and single-row configurations in the highest absolute volumes. EU Green Deal decarbonization targets bind machinery OEMs to extended-fatigue-life specifications that reduce replacement cycles and material waste.
- Automotive:Electrified drivetrain torque specifications compress traditional geometries while opening premium niches for ceramic-hybrid designs. FCC and NHTSA emissions mandates in the United States tighten tolerance requirements for transmission and axle applications.
- Aerospace:Super-precision specifications with vacuum-degassed steel and ion-implanted surfaces command extreme margins in engine and landing gear applications.
- Robotics:Compact single-row and small-diameter double-row units serve articulated arm joints and precision positioning stages in automated manufacturing lines.
Industrial machinery absorbs the highest unit volumes. Automotive electrification is climbing the fastest.
End User:
Customer type determines contract structure, with OEMs demanding lifecycle performance guarantees and distributors fighting on spot-market availability.
- OEMs:Original equipment manufacturers specify integrated sensor-bearing units and ceramic-hybrid configurations under multi-year supply agreements with embedded remanufacturing clauses. Railway rolling stock OEMs in Europe and wind-turbine builders in Germany anchor the most demanding qualification programs.
- Maintenance Providers:Aftermarket service unbundling separates bearing supply from installation, monitoring, and remanufacturing contracts. Asset-light operators in Germany and Japan lease lifecycle management to railway operators, capturing recurring revenue streams.
- Manufacturers:In-house bearing production for captive consumption persists among integrated machinery builders with metallurgical capabilities.
- Distributors:Catalog-bearing spot sales face margin compression as service-integrated providers consolidate procurement relationships.
OEMs dominate specification authority. Maintenance providers are gaining share fastest.
Size:
Supply concentration escalates with diameter, as only Japanese and German forges maintain vacuum degassing capacity for extra-large railway and wind-turbine grades.
- Extra Large:Diameters exceeding 400 millimeters serve wind-turbine main shafts and high-speed railway axles where custom forging and controlled-atmosphere heat treatment concentrate among aging workforces in Japan and Germany. REACH material restrictions and F-Gas Regulation phase-downs force reformulation of lubricants and coatings in these long-service applications.
- Large:Heavy industrial gearboxes and freight railway applications consume standardized large-diameter units with moderate customization requirements.
- Medium:Automotive transmissions and general industrial machinery represent the highest-volume production tier with the most intense price competition.
- Small:Electric motors, robotics joints, and precision instruments demand miniaturized single-row configurations with tight geometric tolerances.
Medium bearings dominate unit shipments. Extra-large segments command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in cylindrical roller bearings tilt toward surplus nations with vacuum-degassing capacity, while import-dependent markets accelerate domestic forging investments. Germany, Japan, and China anchor precision-grade exports. India and the United States absorb the highest import volumes for railway and industrial machinery applications.
Germany
High-speed railway axle specifications and wind-turbine main shaft programs drive demand for extra-large diameter bearings. EU Green Deal decarbonization targets bind industrial machinery OEMs to extended-fatigue-life specifications. Schweinfurt and Thuringia precision clusters concentrate vacuum-degassed steel forging for railway and aerospace grades.
China
Electrified commercial vehicle drivetrains and high-speed rail expansion consume medium and large-diameter bearings in record volumes. GB/T rolling bearing precision classifications segment export-bound products into tiered certification tracks. Luoyang and Wafangdian forging centers scale controlled-atmosphere heat treatment for domestic railway OEM supply contracts.
Japan
Automotive electrification and robotics precision positioning stages demand miniaturized single-row configurations with tight geometric tolerances. METI energy-efficiency standards compress tolerance bands for transmission and motor shaft applications. Kansai and Nagoya industrial corridors retain metallurgical talent for ceramic-hybrid cage development.
India
Freight railway rolling stock expansion and wind-turbine installations accelerate procurement of large-diameter bearings. PLI scheme incentives anchor domestic precision manufacturing clusters for electrified commercial vehicle drivetrains. Gujarat and Maharashtra bearing forges scale capacity to reduce import dependence on German and Japanese extra-large grades.
United States
Industrial machinery rebuild cycles and automotive transmission programs sustain demand for standardized cage-type bearings. FCC and NHTSA emissions and safety mandates compress automotive bearing tolerances. Ohio and Indiana manufacturing belts concentrate tapered-to-cylindrical crossover engineering for high-load industrial segments.
Cylindrical Roller Bearings Market Competitive Environment
On the supply side, the industry is consolidating around metallurgical capabilities that younger competitors cannot replicate. Vacuum-degassed steel forging and controlled-atmosphere heat treatment expertise concentrates among established precision clusters. Three archetypes dominate: integrated steel-forging operators with remanufacturing networks, sensor-bearing specialists capturing railway and wind-turbine OEM specifications, and tapered-to-cylindrical crossover engineers occupying niche high-load segments. Competitive moves center on asset-light service leasing partnerships and ceramic-hybrid material science integration.
Among European integrated operators, SKF and Schaeffler exemplify the steel-forging and sensor-integration archetypes respectively. SKF anchors margin control through captive forging operations and remanufacturing networks across Europe and Asia. Schaeffler occupies a position in integrated sensor-bearing units that dominate railway and wind-turbine OEM specifications. Timken represents the crossover engineering specialist, sitting within the tapered-to-cylindrical niche where standard cylindrical designs fail under extreme load conditions.
| Leading Market Players |
|---|
| SKF |
| NSK |
| NTN Corporation |
| Schaeffler |
| Timken |
| JTEKT |
| National Engineering Industries |
| KOYO |
| NACHI |
| Others |
Value Chain & Pricing Dynamics
Vacuum-degassed steel forging capacity in Japan and Germany anchors margin capture for extra-large bearing grades, concentrating pricing power with suppliers who control captive metallurgical operations while compressing spot-market returns for standardized catalog products.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across premium, standard, and economy tiers. Price differentiation separates vacuum-degassed railway grades from through-hardened industrial catalog bearings, with certification level under GB/T and METI standards driving tier placement. Cost compression in medium-diameter automotive segments is intensifying because electrified drivetrain procurement consolidates volume among fewer platform suppliers. Aftermarket maintenance providers exhibit lowest price sensitivity due to lifecycle performance guarantees, while distributor spot sales face the steepest margin erosion.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for bearing distributors serving industrial machinery rebuild programs. Forging concentration centers on Germany, Japan, and China, with chromium and molybdenum ferroalloy inputs drawing from South African and Kazakh mining operations. Single-source vulnerability persists in silicon nitride ceramic roller supply, where Japanese material science specialists control powder metallurgy pathways. Distribution runs through OEM direct contracts for premium grades and authorized distributor networks for replacement volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cylindrical roller bearings constitute a defensive-moat market where regulatory entrenchment through railway certification programs and METI precision standards creates structural switching costs that protect incumbent positions.
For Market Incumbents: Entrench metallurgical capabilities through captive vacuum-degassing investments in Thuringia and Kansai corridors, countering the threat of ceramic-hybrid substitution by integrating silicon nitride roller production in-house rather than sourcing from external powder specialists. For New Entrants and Emerging Players: Mid-scale wind-turbine maintenance providers in India represent the most penetrable entry point, where PLI-scheme forging incentives and unbundled service contracts create procurement openings outside German-Japanese OEM supply agreements. A sensor-integrated remanufacturing partnership model bypasses capital-intensive forging requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European bearing service networks that lease lifecycle management to railway operators. Long-term viability hinges on electrified drivetrain torque specification capture across the analysis window. Watch ceramic-hybrid adoption rates in wind-turbine main shaft programs as the inflection signal for material science capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum-Degassed Steel Forging | Captive supply of railway-grade material secures margin control against ferroalloy price volatility. |
| Ceramic-Hybrid Cage Development Partnership | Silicon nitride roller integration extends fatigue life for electrified drivetrain shock load applications. |
| Sensor-Bearing Convergence Investment | Integrated vibration sensing meets wind-turbine OEM predictive maintenance specifications. |
| Remanufacturing Service Network Expansion | Asset-light leasing contracts capture recurring revenue from European railway operators. |
| GB/T Precision Certification Fast-Track | Accelerated testing protocols unlock Chinese high-speed railway export qualification tiers. |
Study Parameters
Desk research of customs trade databases, railway procurement registries, and SEC 10-K filings preceded structured interviews with bearing procurement managers at wind-turbine OEMs, maintenance directors at European railway operators, vacuum-degassing plant engineers in Germany and Japan, and aftermarket service heads at industrial distributors. Bottom-up volume modeling triangulated against top-down OEM supply contract aggregation.
Assumptions held electrified drivetrain penetration and EU Green Deal decarbonization targets fixed across the projection horizon, while alloy input costs and REACH regulatory timelines varied under sensitivity scenarios. Segmentation dimensions spanned product architecture, application load density, end-user contract structure, and diameter tier. CAGRs derived from replacement cycle economics and capacity expansion announcements. Forecast inputs incorporated railway rolling stock procurement schedules and wind-turbine installation pipelines.
Macroeconomic conditions sit as an overlay; deviation in ferroalloy supply disruptions or carbon-border adjustment implementation pace would shift the trajectory. Forecasts reflect documented assumptions regarding ceramic-hybrid adoption curves and certification timeline compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Car Modification Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Electric Vehicle High Voltage Connector System Market
Vehicle Components
Rear Axle Market
Vehicle Components
Throttle Cable Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market