
 Trailer Surge Brake Market | 2026-2036
Trailer Surge Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Surge Brake Market Analysis
Recreational trailer buyer fragmentation is expanding across independent RV owners and small rental operators. Dexter Axle Company leverages its manufacturing scale to supply OEM channels across North America. CURT Manufacturing LLC anchors its position through aftermarket distribution networks. Demco specializes in hydraulic surge brake systems for boat and utility trailers.
Trailer surge brakes are hydraulic or mechanical deceleration devices that activate through inertial force transfer from the towing vehicle, typically rated for gross trailer weights between 2,000 and 12,000 pounds and requiring master cylinder pressures of 1,000 to 1,500 PSI for effective stopping. Their primary purpose is to provide autonomous braking in towed units without electrical connection dependency, serving recreational boating, cargo hauling, and equipment transport applications. Hydraulic brake type dominates factory-installed configurations due to superior thermal performance in marine environments. Aftermarket installation methods are gaining traction among recreational users seeking retrofit compliance with DOT Specification standards. CE Marking compliance creates margin differentiation for suppliers targeting European import channels.
NHTSA enforces FMVSS stopping-distance thresholds that directly shape surge brake actuator design specifications. DOT Specification and SAE Standards testing protocols determine market access for domestic and import manufacturers. Stakeholders must monitor regulatory divergence between NHTSA requirements and emerging ISO Certifications for unified product platform strategies.
Market Dynamics
NHTSA's tightening FMVSS stopping-distance mandates are compressing actuator design cycles and forcing suppliers to recalibrate hydraulic pressure specifications across marine and utility trailer segments.
Growth Catalysts
- FMVSS Compliance Deadlines:NHTSA enforcement of reduced stopping-distance thresholds compels fleet operators to retrofit medium-duty trailers with higher-performance surge brake actuators.
- Marine Trailer Corrosion Resistance:Saltwater exposure requirements in coastal boating corridors accelerate factory-specified hydraulic surge brake adoption over mechanical alternatives.
- Indiana-Texas Manufacturing Cluster:Proximity of trailer OEM assembly plants to component suppliers compresses logistics costs and enables just-in-time actuator delivery schedules.
Market Restraints
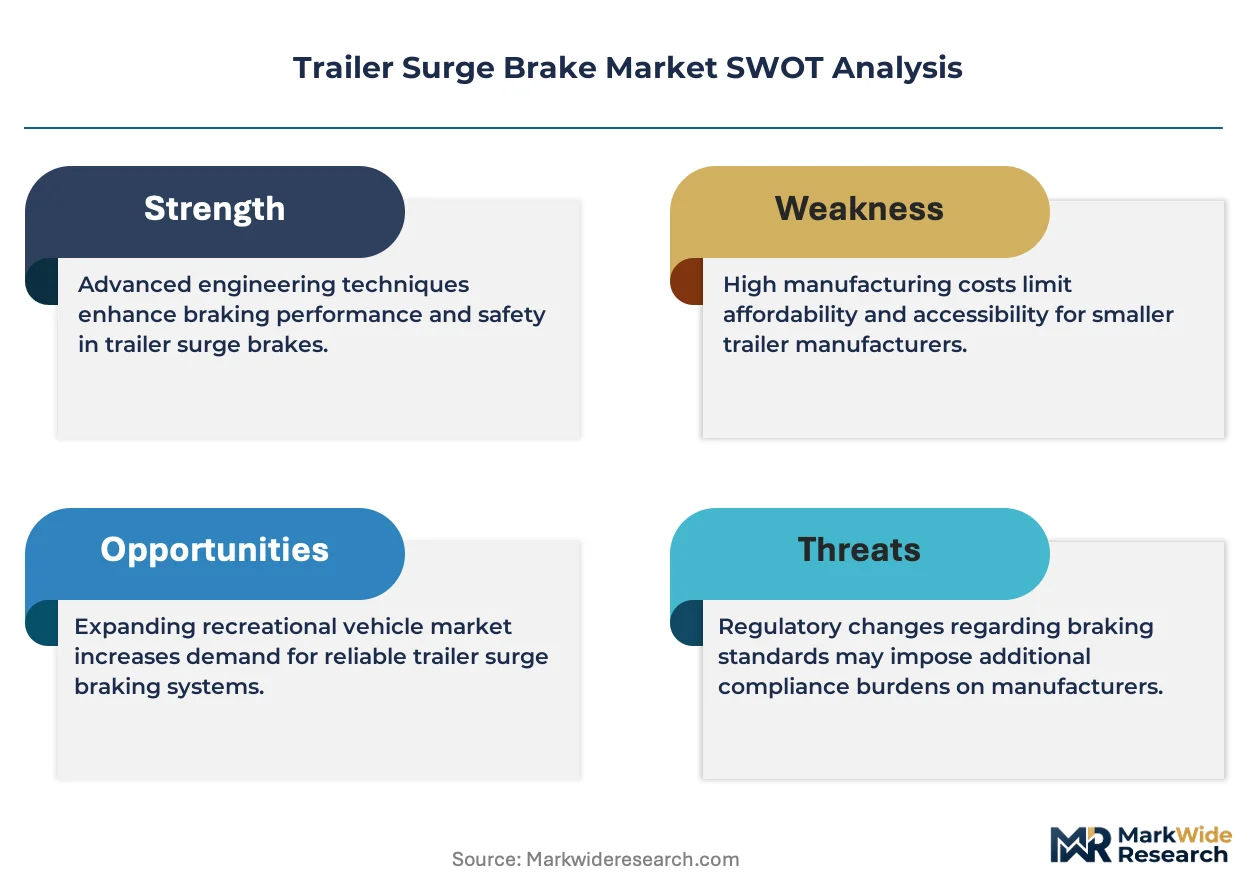
- Aluminum Alloy Price Volatility:Master cylinder housing costs fluctuate with commodity spot markets, squeezing margin structures for mid-tier actuator manufacturers.
- Single-Source Forging Capacity:Precision brake component casting concentrates among domestic foundry operators, creating supply vulnerability during peak trailer production seasons.
- Electrical Brake Substitution:Electric-over-hydraulic systems gain traction in premium RV segments, threatening displacement of pure hydraulic surge mechanisms.
Strategic Opportunities
- CE Marking Export Channels:European import compliance creates pricing premium capture for suppliers achieving unified brake actuator certification across NHTSA and EU regulatory frameworks.
- Boat Trailer Rental Fleets:Short-term recreational watercraft operators represent an underserved retrofit market with concentrated seasonal demand spikes.
- Sensor-Actuator Integration:Convergence of load-sensing telemetry with hydraulic pressure modulation enables predictive maintenance service offerings.
Industry Challenges
- DOT Specification Testing Bottlenecks:SAE Standards validation queues extend product qualification timelines, delaying market entry for redesigned actuator platforms.
- ISO Certification Harmonization:Divergence between NHTSA protocols and emerging international standards fragments R&D investment across incompatible test regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Surge Brake Market |
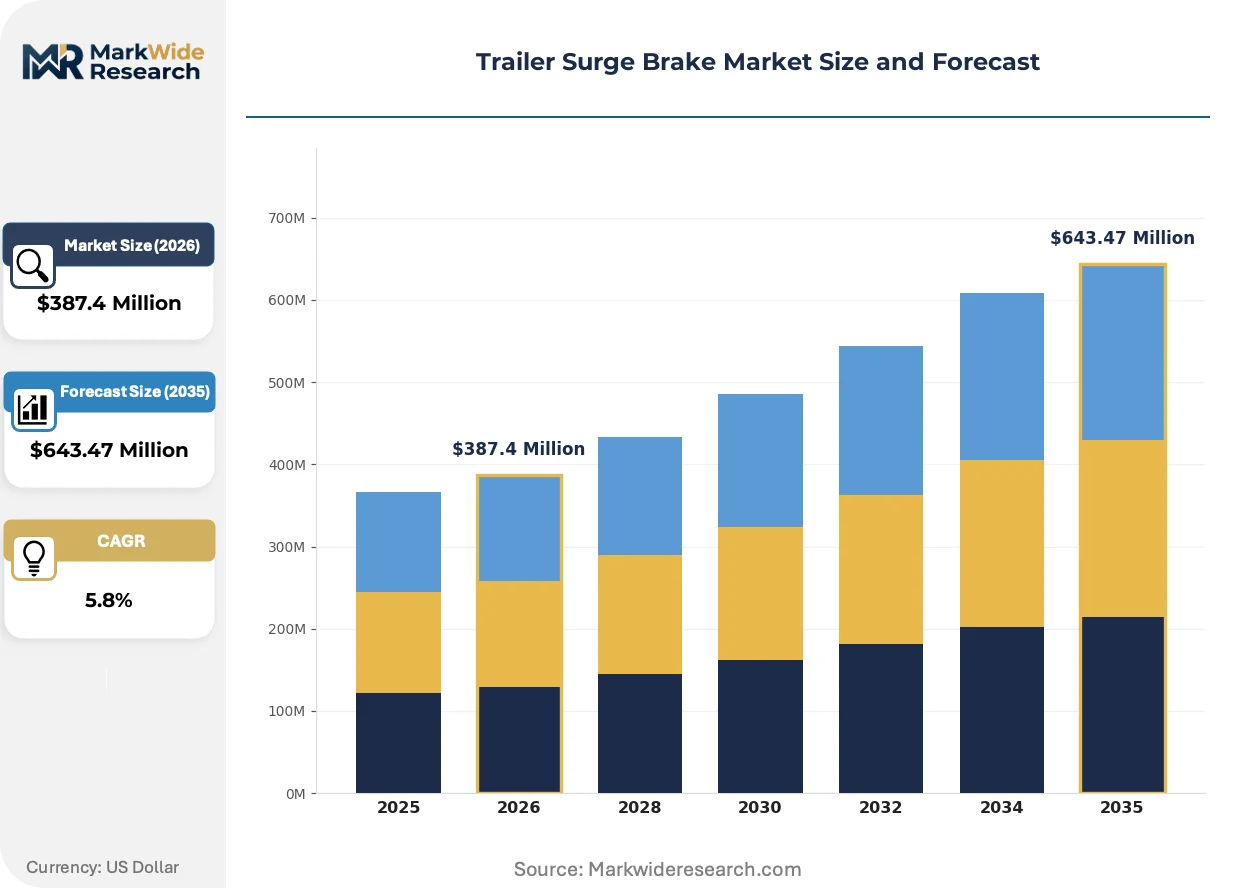
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $643.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Brake Type: Hydraulic, Electric, Mechanical, Pneumatic End User: Commercial Fleets, Recreational Users, Government Agencies, Logistics Providers Installation Method: Factory-installed, Aftermarket, DIY Kit, Professional Installation Compliance Standard: DOT Specification, SAE Standards, ISO Certifications, CE Marking |
| Companies Covered | Dexter Axle Company, CURT Manufacturing LLC, Demco, Tie Down Engineering, Lippert Components Inc., Heritage Custom Trailers, PJ Trailers, Atwood, Titan Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Surge Brake Market Emerging Trajectories
Actuator intelligence and materials science are redefining performance benchmarks in trailer braking, with regulatory pressure and buyer sophistication accelerating specification upgrades.
Corrosion-resistant composite master cylinder housings are replacing traditional cast aluminum in marine surge brake assemblies. Coastal boat trailer manufacturers specify these polymer-composite units for saltwater immersion durability. This materials shift is converging with extended warranty requirements from rental fleet operators seeking reduced service intervals.
NHTSA's updated FMVSS 121 stopping-distance thresholds are compressing actuator response time specifications. Brake system engineers must recalibrate hydraulic pressure curves to achieve shorter deceleration windows. Medium-duty cargo trailer segments face the steepest redesign burden as legacy actuator architectures approach compliance limits.
Independent RV owners now source surge brake components through direct-to-consumer channels rather than traditional dealership networks. Online specification tools enable self-selection of actuator pressure ratings matched to trailer gross weights. This channel migration is most pronounced in the southeastern United States, where year-round towing activity sustains aftermarket demand velocity.
Trailer Surge Brake Market Segmentation
Surge brake procurement patterns diverge sharply across brake architecture, end-use intensity, installation channel, and regulatory jurisdiction. Each segmentation axis reveals distinct margin structures and capital deployment requirements that shape supplier positioning.
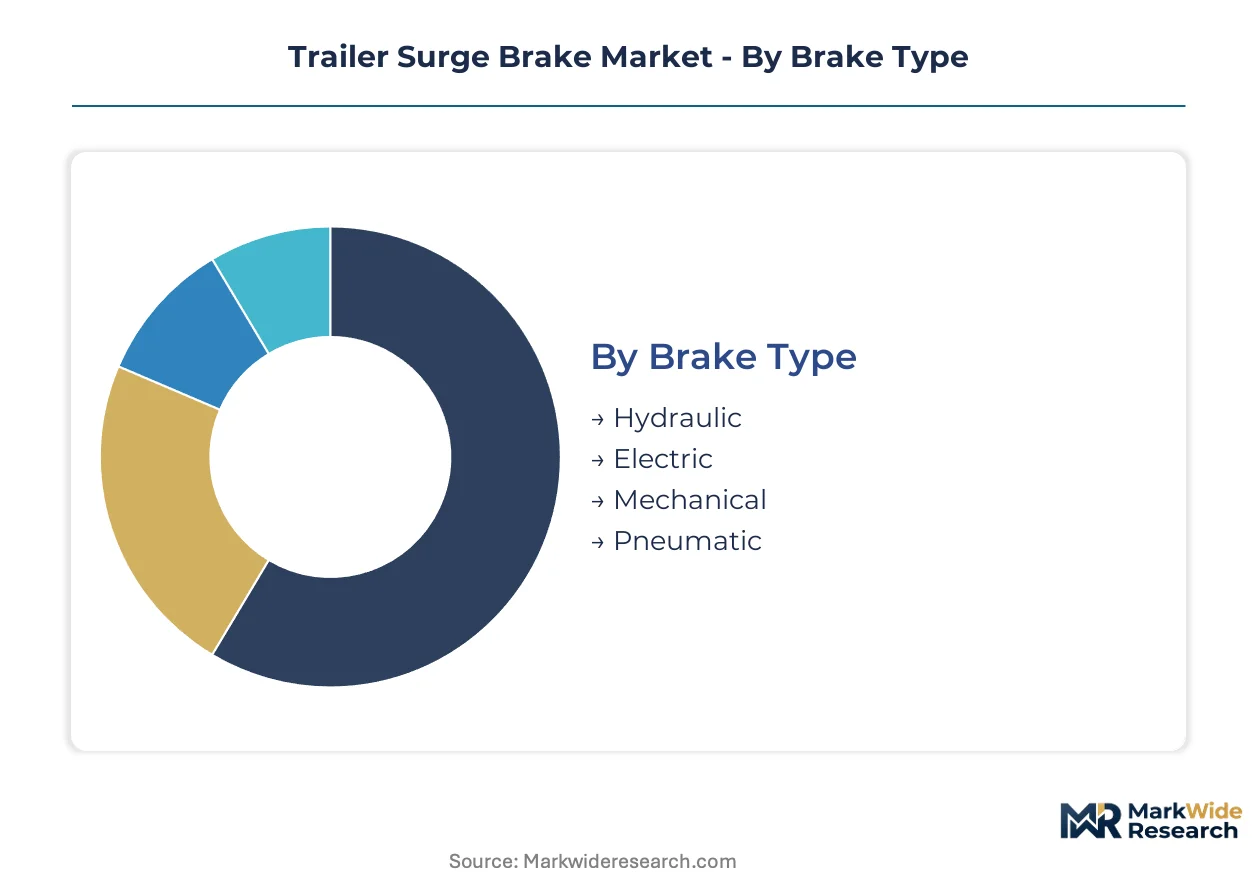
Brake Type:
Hydraulic systems command the highest upfront tooling investment due to precision-machined master cylinder requirements and pressure-testing infrastructure.
- Hydraulic:Pressurized fluid systems utilizing master cylinders rated at 1,000 to 1,500 PSI dominate marine trailer factory specifications. Saltwater corrosion resistance requirements in Florida and Gulf Coast boating corridors sustain premium pricing for stainless-steel piston configurations.
- Electric:Electromagnetic actuation enables integration with tow vehicle brake controllers, gaining share in premium RV segments where synchronized deceleration is prioritized over autonomous operation. NHTSA electrical safety standards elevate certification costs for entry-level suppliers.
- Mechanical:Cable-actuated designs serve lightweight utility trailers below 3,500 pounds gross weight with minimal component count.
- Pneumatic:Air-pressure systems anchor heavy-duty commercial fleet applications where tractor air supply compatibility is mandatory.
Most installed capacity flows through Hydraulic. Expansion is steepest in Electric.
End User:
Customer scale determines service model economics, with large fleet operators extracting volume pricing that compresses per-unit margins.
- Commercial Fleets:Medium-duty cargo haulers and equipment transport operators mandate FMVSS-compliant stopping distances across multi-trailer inventories. Indiana-based trailer OEMs coordinate just-in-time actuator delivery to fleet specification centers.
- Recreational Users:Independent boat owners and RV enthusiasts prioritize corrosion resistance and warranty coverage over initial acquisition cost. Southeast United States seasonal demand spikes strain aftermarket distribution networks.
- Government Agencies:Municipal equipment pools and military transport units specify hardened actuators with extended service intervals.
- Logistics Providers:Third-party freight operators balance DOT inspection compliance against rapid trailer turnover requirements.
Recreational Users absorb the highest per-unit pricing. Commercial Fleets drive volume throughput.
Installation Method:
Channel selection determines warranty liability exposure and technical support intensity.
- Factory-installed:OEM line-fit integration at Indiana and Texas assembly plants ensures hydraulic system pressure validation before customer delivery. Master cylinder-to-actuator mating precision reduces field failure rates.
- Aftermarket:Distributor-channel retrofit serves compliance-driven fleet upgrades and recreational replacement cycles. CURT Manufacturing anchors this channel through regional warehouse distribution.
- DIY Kit:Consumer-direct packaging with installation documentation targets independent RV owners in southeastern states.
- Professional Installation:Certified technician networks handle complex hydraulic bleeding procedures and DOT inspection documentation.
Factory-installed captures margin premiums. Aftermarket channels are expanding most quickly.
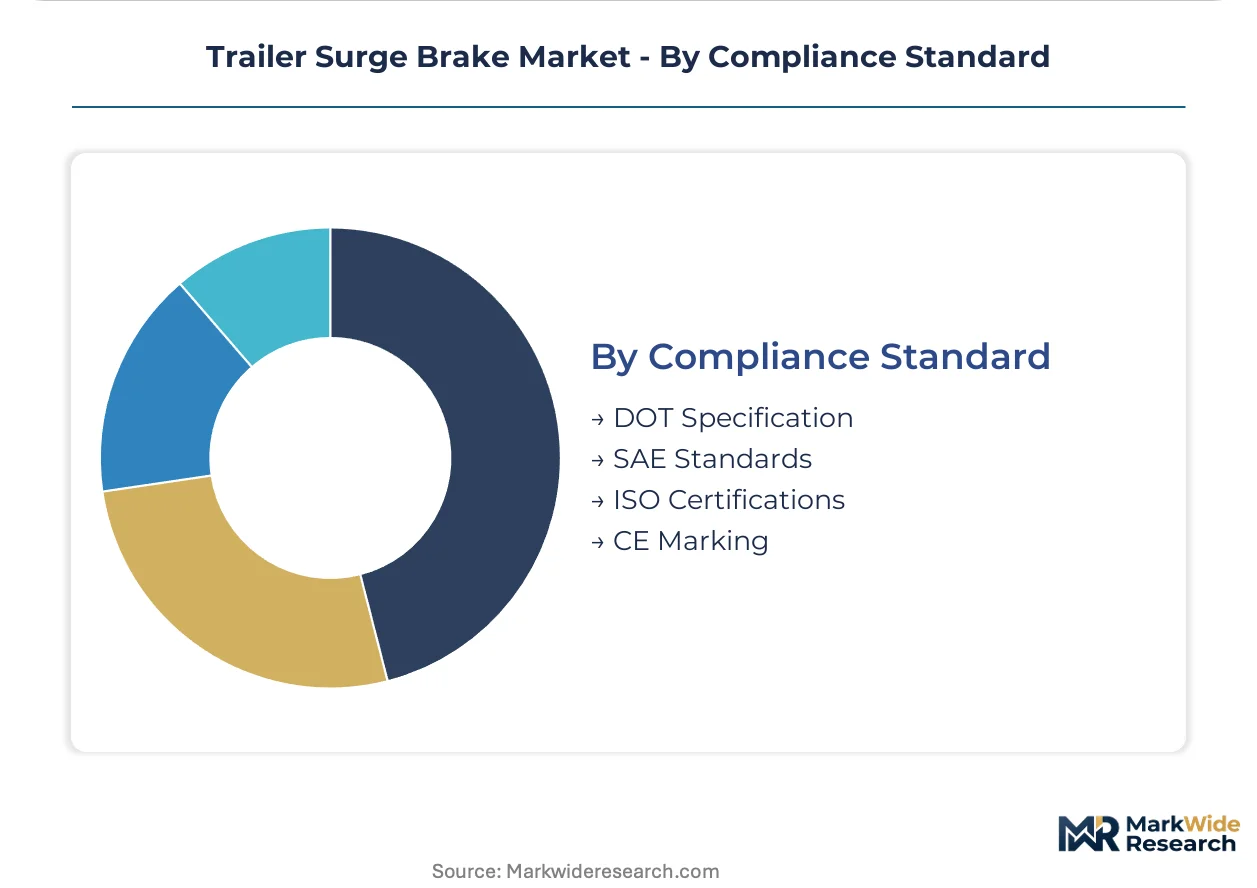
Compliance Standard:
Certification breadth determines addressable market geography and pricing tier eligibility.
- DOT Specification:FMVSS 121 stopping-distance mandates govern all United States interstate commerce applications. Test protocol documentation requirements extend product qualification timelines.
- SAE Standards:Society of Automotive Engineers testing protocols provide industry-recognized performance benchmarks beyond federal minimums.
- ISO Certifications:International Organization for Standardization quality management systems enable supplier qualification for export-oriented trailer manufacturers.
- CE Marking:European Union conformity assessment unlocks premium pricing in EU import channels but fragments R&D investment across incompatible test regimes.
DOT Specification anchors domestic volume. CE Marking delivers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's marine trailer corridor generates distinct corrosion-resistance specifications compared to Australia's saltwater boating infrastructure, while both markets operate under separate federal brake performance frameworks.
United States
NHTSA's FMVSS 121 mandates compress actuator design cycles across Indiana and Texas manufacturing clusters. Indiana-based OEM assembly plants coordinate just-in-time hydraulic component delivery with regional foundry operators. Texas Gulf Coast boat trailer fabricators specify stainless-steel piston configurations for saltwater immersion durability.
Canada
Transport Canada CMVSS brake standards govern trailer stopping-distance requirements across Ontario and Quebec recreational boating corridors. Provincial inspection protocols in British Columbia accelerate aftermarket retrofit cycles for utility trailer compliance. Manitoba-based fleet operators source hydraulic actuators through cross-border distribution channels serving prairie agricultural equipment haulers.
Germany
KBA type-approval requirements for trailer braking systems create certification complexity for hydraulic surge brake exporters. CE Marking conformity assessment unlocks premium pricing tiers across Bavaria and Baden-Württemberg industrial trailer segments. Stuttgart-area automotive suppliers integrate surge brake actuators into specialized equipment transport configurations.
Australia
ADR 38 brake performance standards govern trailer deceleration requirements across New South Wales and Queensland coastal boating markets. Saltwater corrosion specifications in Sydney and Melbourne marine corridors mirror Florida Gulf Coast material requirements. Perth-based mining equipment operators specify heavy-duty hydraulic actuators for remote site access trailers.
Mexico
NOM-034-SCT brake system standards align with US FMVSS thresholds for cross-border commercial fleet interoperability. Nuevo León manufacturing clusters supply actuator components to Texas OEM assembly plants through integrated supply chain networks. Baja California marine trailer fabricators serve California recreational boating demand through Tijuana-area export channels.
Trailer Surge Brake Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across factory-installed and aftermarket channels. The vendor base organizes around three strategic archetypes: integrated trailer OEMs with captive brake production, dedicated component manufacturers serving multiple OEM accounts, and aftermarket distributors with private-label sourcing capabilities. Consolidation pressure intensifies as NHTSA compliance costs rise and aluminum alloy price volatility squeezes mid-tier actuator margins. Dominant competitive moves include backward integration into precision forging capacity and geographic expansion into CE Marking-qualified European export channels.
Among North American component specialists, Dexter Axle Company and CURT Manufacturing LLC exemplify scale-driven positioning across divergent channel strategies. Demco occupies a specialist position within hydraulic surge brake configurations for marine applications. These three entities represent distinct archetype anchors: integrated manufacturing scale, aftermarket distribution density, and application-specific engineering focus respectively.
| Leading Market Players |
|---|
| Dexter Axle Company |
| CURT Manufacturing LLC |
| Demco |
| Tie Down Engineering |
| Lippert Components Inc. |
| Heritage Custom Trailers |
| PJ Trailers |
| Atwood |
| Titan Tire Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up component specialists anchor the supplier base, compressing procurement cycles and enforcing volume-discipline pricing across Indiana and Texas manufacturing clusters. Their consolidated balance sheets enable just-in-time inventory financing that locks in aluminum alloy hedges and transfers commodity risk downstream to mid-tier actuator assemblers.
Pricing Analysis
Capacity additions in Texas foundry corridors are reshaping price floors for precision-machined master cylinder housings. Three-tier pricing structure across premium stainless-steel, standard aluminum, and economy cast-iron configurations stratifies by corrosion resistance grade and DOT certification tier. Pricing pressure stems from electric-over-hydraulic substitution in premium RV segments. Recreational boat trailer buyers exhibit lowest price sensitivity; fleet procurement managers at commercial haulers negotiate hardest on per-unit basis.
Supply Chain Analysis
Workforce availability constraints in Indiana precision-machining hubs and Texas Gulf Coast fabrication centers compress production scheduling flexibility during peak trailer assembly seasons. Supply concentrates in the United States, Mexico, and Canada through integrated NAFTA-era supplier networks. Raw material flows draw from domestic aluminum smelters, Chinese stainless-steel billet imports, and regional polymer-composite resin producers. Single-source forging vulnerability for master cylinder castings creates supply interruption exposure. Distribution runs through OEM direct line-fit, regional aftermarket warehouses, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA's FMVSS 121 stopping-distance tightening generates forced replacement demand across installed trailer bases.
For Market Incumbents: Deploy backward integration into captive forging capacity to secure master cylinder housing supply against foundry bottlenecks. Lock in multi-year aluminum alloy offtake agreements before spot market volatility accelerates. Electric-over-hydraulic substitution in premium RV segments threatens pure hydraulic actuator displacement; counter with extended warranty bundling and corrosion-resistant composite material differentiation. For New Entrants and Emerging Players: The mid-tier price gap between Dexter Axle's OEM scale and CURT Manufacturing's aftermarket density opens white-space for specialized marine actuator suppliers. Target boat trailer rental fleets in Florida and Gulf Coast corridors with seasonal surge capacity and rapid retrofit turnaround. Enter through CE Marking-qualified export channels where European import compliance creates pricing premium capture unavailable in saturated domestic aftermarket. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier hydraulic specialists lacking OEM line-fit relationships but holding DOT certification and regional foundry partnerships. Five-to-ten year viability hinges on NHTSA compliance cost absorption capacity and aluminum price hedge sophistication. Monitor electric-over-hydraulic patent filing velocity as inflection signal for technology substitution timeline.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive master cylinder housing supply secures production continuity against domestic foundry bottlenecks during peak trailer assembly seasons. |
| CE Marking Certification Investment | EU conformity assessment unlocks premium pricing tiers in German and Benelux industrial trailer import channels. |
| Sensor-Actuator Integration Development | Load-sensing telemetry convergence enables predictive maintenance service offerings for commercial fleet operators. |
| Multi-Year Aluminum Alloy Hedging | Long-term commodity contracts insulate margin structures from spot market volatility squeezing mid-tier manufacturers. |
| Boat Trailer Rental Fleet Partnerships | Concentrated seasonal demand from short-term watercraft operators represents underserved retrofit market with rapid inventory turnover. |
Methodological Framework
Bottom-up trailer end-use modeling reconciled against top-down actuator production tracking forms the analytical core. Primary fieldwork encompassed interviews with hydraulic system engineers at Indiana OEM assembly plants, procurement directors at Texas marine trailer fabricators, aftermarket distribution managers at CURT Manufacturing regional warehouses, and fleet maintenance supervisors at commercial equipment haulers. Secondary validation drew from NHTSA FMVSS 121 enforcement documentation, DOT brake performance test protocols, SAE Standards technical bulletins, and aluminum alloy commodity exchange data.
Input-output matrices mapped hydraulic actuator specifications against trailer gross weight categories, brake type architectures, and compliance standard tiers across the projection horizon. Segmentation dimensions encompassed brake mechanism type, end-user scale, installation channel, and regulatory jurisdiction cluster. CAGRs were derived from installed base replacement cycles, fleet expansion trajectories, and regulatory compliance deadline impacts. Forecast inputs included NHTSA stopping-distance threshold implementation schedules and marine trailer corrosion specification adoption curves.
Caveats apply where NHTSA rulemaking delays, aluminum price spike magnitude, or electric-over-hydraulic technology cost curves could materially shift the outlook. Forecasts embed assumptions regarding regulatory enforcement consistency and commodity market stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Global Bearings Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Child Seats Market
Vehicle Components
Steering Column Module Market