
 Fuel Sensor Market | 2026-2036
Fuel Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Sensor Market Insights
Asian sensor foundries is restructuring output priorities to meet automotive-grade fuel sensor demand. Robert Bosch GmbH leverages its MEMS fabrication depth to supply capacitive level modules for European OEM tank systems. Continental AG anchors its position through integrated fuel-system electronics that merge level sensing with engine control unit communication. TE Connectivity Ltd. competes on harsh-environment reliability, extending its aerospace-grade sealing methods into agricultural and off-road fuel applications.
A fuel sensor is an electromechanical or electronic transducer that measures liquid fuel volume, level, or quality within a storage or delivery system, typically operating across temperature ranges from minus forty to one hundred twenty degrees Celsius and withstanding hydrocarbon chemical exposure. Its primary industrial purpose is to enable precise inventory management, prevent engine damage from contaminated fuel, and support emissions compliance through accurate consumption tracking. Capacitive sensors dominate OEM installations due to their immunity to fuel formulation changes, while ultrasonic variants capture expanding share in leak detection applications where non-contact measurement prevents contamination risk. IoT-enabled technology segments are drawing disproportionate R&D investment as fleet operators demand real-time cloud telemetry, though analog architectures persist in cost-sensitive agricultural equipment.
The EPA enforces evaporative emissions standards under Title 40 CFR that mandate sealed fuel systems with accurate level reporting, while NHTSA crashworthiness rules shape sensor mounting and wiring protection specifications. CARB operates parallel heavy-duty vehicle requirements that exceed federal stringency, creating a dual-compliance burden for suppliers serving California-registered fleets. ISO 15170 and SAE J1810 define electrical and mechanical interchange standards that determine market access for replacement sensor designs. Stakeholders must monitor the divergence between EPA Phase Three greenhouse gas rules and emerging state-level zero-emission mandates, as these frameworks will determine whether fuel sensor demand shifts toward hybrid-optimized architectures or contracts under full electrification timelines.
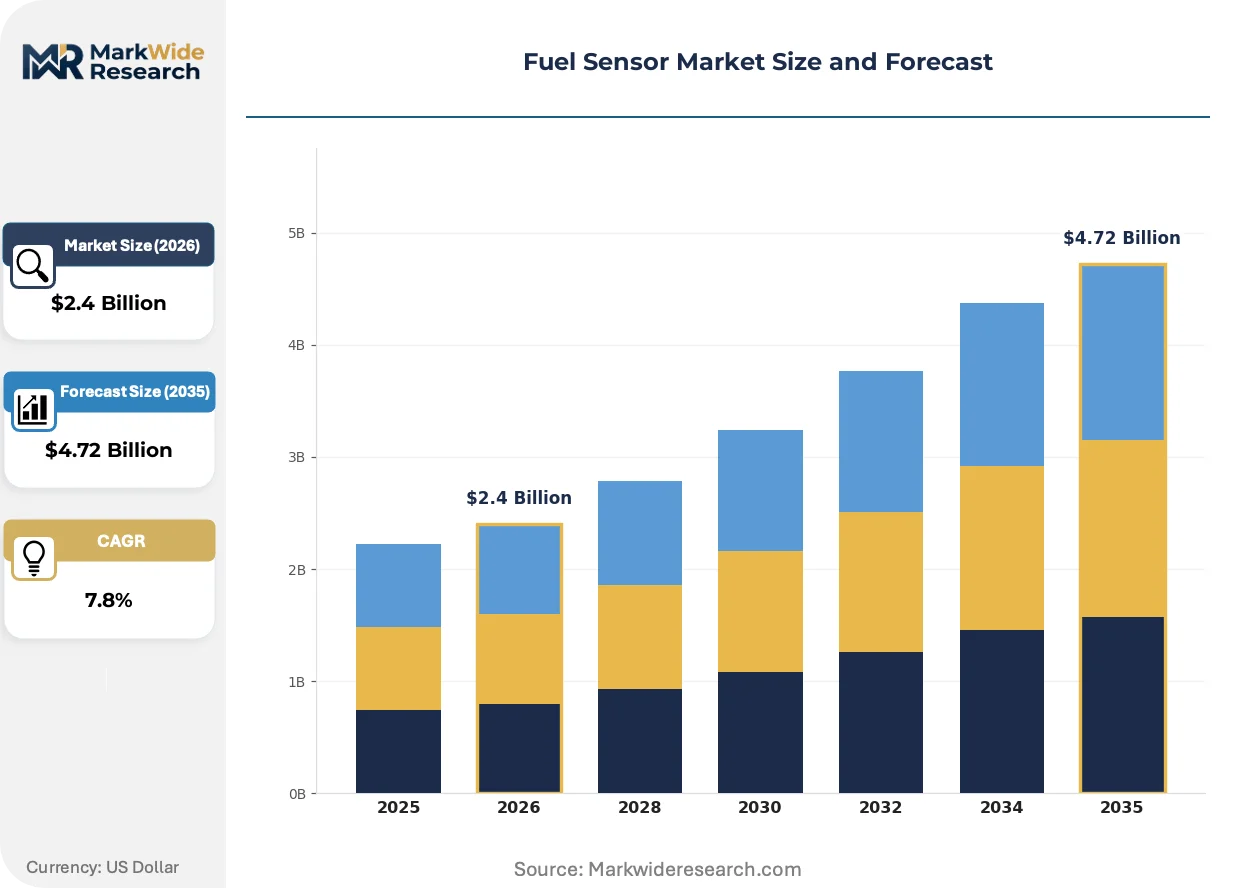
Market Dynamics
Fleet telematics integration is compressing replacement cycles for fuel sensors across commercial vehicle segments, as operators demand real-time consumption visibility to optimize diesel logistics and prevent theft losses.
Growth Catalysts
- CARB Heavy-Duty Vehicle Rules:California's emissions enforcement mandates sealed fuel systems with accurate level reporting, forcing sensor upgrades across registered fleets operating within the state.
- Capacitive Level Modules:OEM tank system specifications increasingly favor capacitive architectures for their immunity to fuel formulation changes, displacing resistive alternatives in new vehicle platforms.
- Fleet Theft Prevention:Commercial operators in the United States are deploying ultrasonic and capacitive sensors with tamper-detection logic to reduce unauthorized fuel siphoning incidents.
Market Restraints
- Automotive-Grade MEMS Supply:Asian foundry capacity constraints limit output of precision capacitive elements, creating allocation pressure for European and North American module assemblers.
- Electrification Substitution:Zero-emission mandates in select jurisdictions threaten long-term fuel sensor demand as battery-electric and hydrogen platforms eliminate conventional tank architectures entirely.
- ISO 15170 Certification Burden:Electrical interchange standards require extensive validation cycles, extending time-to-market for replacement sensor designs and favoring incumbent suppliers with established test histories.
Strategic Opportunities
- Leak Detection Ultrasonics:Non-contact ultrasonic measurement is capturing share in environmental monitoring applications where contamination prevention outweighs cost sensitivity.
- Agricultural IoT Telemetry:Cost-constrained farm equipment represents underpenetrated terrain for cloud-connected fuel monitoring, with operators beginning to unbundle after-sales service from hardware procurement.
- EPA Phase Three Alignment:Anticipated greenhouse gas rules for medium and heavy-duty vehicles will tighten consumption tracking requirements, creating regulatory tailwind for precision sensor architectures.
Industry Challenges
- SAE J1810 Mechanical Interoperability:Wiring protection and mounting specifications vary across OEM platforms, forcing suppliers to maintain multiple tooling configurations and complicating scale economies.
- Telematics Integration Complexity:Fleet management software ecosystems demand proprietary data protocols, requiring sensor firmware customization that fragments engineering resources.
- Harsh-Environment Sealing Expertise:Aerospace-grade methods for hydrocarbon exposure and temperature cycling remain concentrated among specialized suppliers, limiting rapid capability replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Sensor Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Capacitive Sensors, Optical Sensors, Resistive Sensors End User: Automotive OEMs, Fleet Management, Agricultural Equipment, Industrial Machinery Technology: IoT-Enabled, Wireless, Analog, Digital Application: Fuel Monitoring, Tank Level Measurement, Leak Detection, Fuel Quality Assessment |
| Companies Covered | Continental AG, Robert Bosch GmbH, Bourns Inc., Pricol Ltd., Delphi Technologies Plc, TE Connectivity Ltd., Valeo SA, Melexis, elobau GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Sensor Market Trends and Innovations
Sensor architectures are bifurcating between analog persistence in cost-driven agricultural segments and digital telemetry acceleration in regulated commercial fleets, with interface standardization emerging as the critical battleground for supplier positioning.
Capacitive fuel level sensing is converging with engine control unit communication protocols, enabling closed-loop consumption optimization that was previously impossible with standalone measurement. Tier-1 suppliers are embedding bidirectional data links directly into tank modules, allowing powertrain controllers to adjust injection timing based on real-time fuel temperature and composition. This integration is compressing the addressable market for discrete sensor vendors while expanding total system value for integrated fuel-system electronics providers.
REACH chemical restrictions in Europe are reshaping material specifications for sensor housings and seals, with ECHA scrutiny of persistent organic pollutants forcing reformulation of traditional hydrocarbon-resistant polymers. Suppliers serving EU-registered commercial fleets must now validate alternative elastomer compounds against extended temperature cycling requirements. German agricultural equipment manufacturers are responding fastest, leveraging existing compliance infrastructure from adjacent emissions control component lines.
Fleet procurement patterns are consolidating around outcome-based fuel management contracts that bundle sensor hardware, installation, and data analytics into single vendor relationships. This disintermediates traditional parts distributors and favors direct OEM or tier-1 supplier engagement with large commercial operators. The United States exhibits the most pronounced shift, where telematics platform providers are acquiring sensor calibration capabilities to capture recurring software subscription revenue streams.
Fuel Sensor Market Segmentation
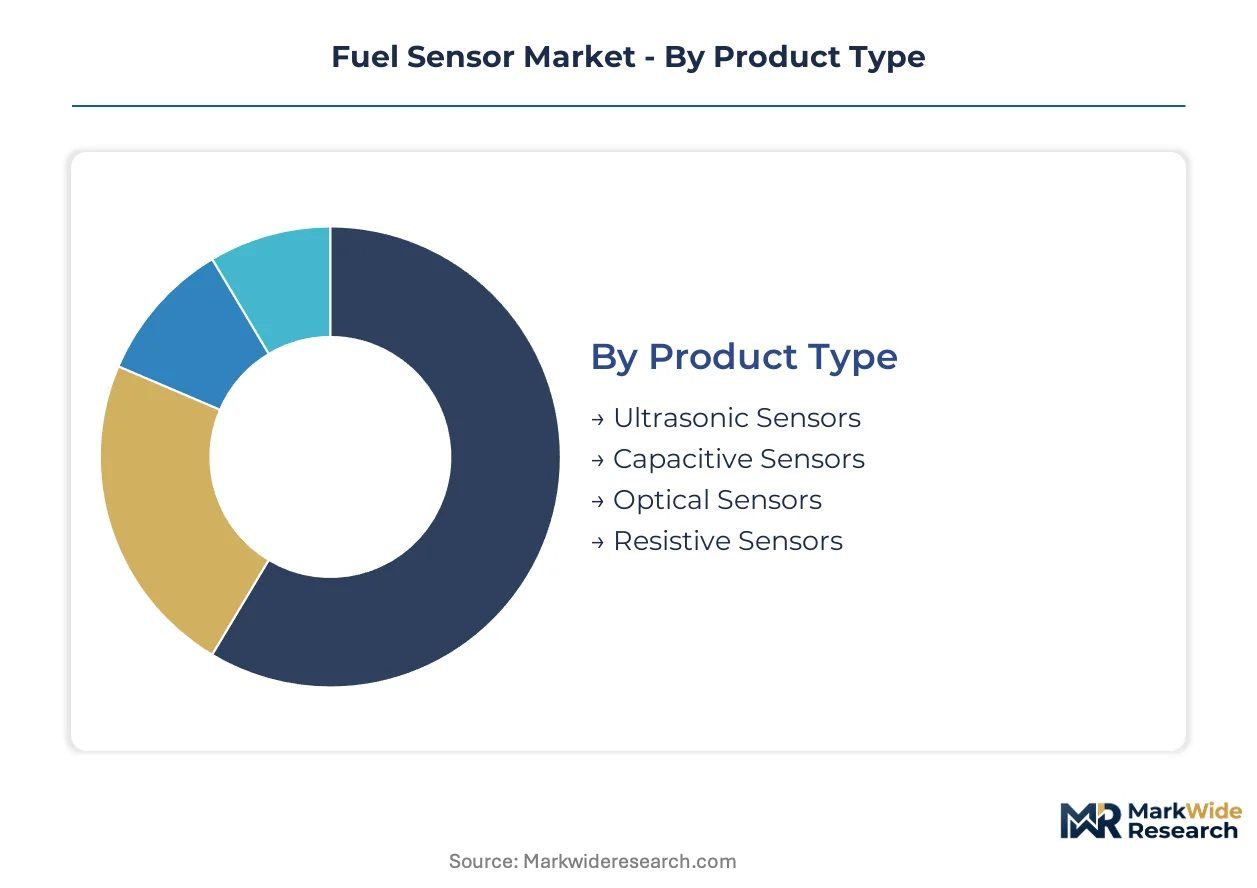
Fuel sensor segmentation reveals how upgrade cycles concentrate around regulatory deadlines and telematics integration timelines. Replacement demand fragments across product architectures, with capacitive modules and IoT-enabled systems capturing disproportionate investment from fleet operators facing CARB compliance pressure.
Product Type:
Upgrade cycles for fuel sensors accelerate when OEM platforms mandate sealed-system architectures that resist fuel formulation changes.
- Capacitive Sensors:These modules measure fuel level through dielectric constant variation, eliminating mechanical wear points found in resistive alternatives. Demand concentrates in United States heavy-duty fleets where CARB rules mandate accurate level reporting for evaporative emissions compliance.
- Ultrasonic Sensors:Non-contact measurement via piezoelectric transducers prevents fuel contamination while enabling leak detection sensitivity down to millimeter-scale level changes. Fleet operators in California deploy these for theft prevention alongside environmental monitoring.
- Optical Sensors:Infrared absorption spectroscopy identifies fuel contamination and adulteration in real-time.
- Resistive Sensors:Float-arm potentiometer designs persist in cost-sensitive agricultural equipment where analog simplicity outweighs precision requirements.
Capacitive sensors sit at the top of the volume ranking, with ultrasonic variants climbing the fastest.
End User:
Customer procurement patterns diverge sharply between regulated commercial fleets and equipment operators prioritizing total cost of ownership.
- Fleet Management:Telematics-integrated fuel monitoring contracts bundle hardware, installation, and cloud analytics into recurring subscription relationships. United States commercial operators lead this shift, unbundling after-sales service from traditional parts distribution channels.
- Automotive OEMs:Tank system specifications increasingly demand bidirectional communication between level modules and engine control units, enabling closed-loop injection timing optimization based on real-time fuel temperature data.
- Agricultural Equipment:Cost-constrained farm machinery represents underpenetrated terrain for IoT telemetry, with operators beginning to separate hardware procurement from service contracts.
- Industrial Machinery:Harsh-environment sealing requirements from aerospace-grade suppliers extend into off-road construction and mining applications.
Fleet management commands the largest addressable base, while agricultural equipment is gaining share fastest as cloud connectivity penetrates legacy machinery.
Technology:
Interface standardization battles determine supplier positioning as analog architectures persist alongside digital acceleration.
- IoT-Enabled:Cloud-connected sensors transmit real-time consumption data through cellular or satellite links, enabling predictive maintenance and theft alerts. United States telematics platform providers are acquiring sensor calibration capabilities to capture recurring software revenue.
- Digital:CAN bus and LIN protocol integration allows direct engine control unit communication without intermediate signal conditioning.
- Wireless:Bluetooth Low Energy and LoRaWAN eliminate wiring harness complexity in retrofit applications.
- Analog:Voltage-output resistive designs maintain dominance where electromagnetic compatibility certification costs exceed telemetry value.
Analog technology retains the highest installed base, though IoT-enabled architectures are expanding most quickly among regulated commercial segments.
Application:
Functional specialization is reshaping how sensor value gets captured across the fuel system lifecycle.
- Fuel Monitoring:Continuous volume tracking supports inventory management and consumption optimization across diesel logistics operations. EPA Phase Three greenhouse gas rules for medium and heavy-duty vehicles will tighten tracking precision requirements.
- Leak Detection:Ultrasonic and pressure-differential methods detect evaporative emissions violations before regulatory penalties accrue.
- Tank Level Measurement:Capacitive and resistive architectures compete on cost-precision tradeoffs for basic inventory visibility.
- Fuel Quality Assessment:Optical spectroscopy identifies water contamination, particulate intrusion, and fuel adulteration that threatens engine durability.
Fuel monitoring generates the highest unit volume, with leak detection showing the steepest expansion trajectory as environmental enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as sensor fabricators migrate toward jurisdictions with lower cost-of-compliance for automotive-grade MEMS output. Assembly operations concentrate where EPA, CARB, and ECHA enforcement create premium-tier demand for certified modules.
United States
Fleet telematics contracts and CARB heavy-duty vehicle rules drive capacitive sensor upgrades across California-registered commercial vehicles. EPA Phase Three greenhouse gas rules for medium and heavy-duty vehicles tighten consumption tracking precision requirements nationwide. Detroit-Warren-Dearborn automotive cluster anchors module assembly for domestic OEM tank systems.
Germany
REACH chemical restrictions force reformulation of hydrocarbon-resistant polymers for sensor housings and seals. ECHA scrutiny of persistent organic pollutants extends validation cycles for replacement sensor designs. Stuttgart industrial corridor hosts integrated fuel-system electronics development merging level sensing with engine control unit communication.
China
Domestic OEM platform expansion and fleet modernization programs accelerate demand for sealed-system fuel architectures. MIIT automotive standards and GB certification requirements shape module specifications for local vehicle production. Yangtze River Delta sensor foundries restructure output priorities to meet automotive-grade capacitive element demand.
Japan
Precision manufacturing heritage supports harsh-environment sealing expertise for aerospace-grade methods extending into agricultural and off-road fuel applications. METI industrial standards govern automotive component interchange specifications. Nagoya-Chubu automotive cluster concentrates bidirectional data link development for tank module integration.
South Korea
Hyundai-Kia platform specifications and domestic commercial fleet telematics adoption compress replacement cycles for IoT-enabled fuel monitoring. MFDS automotive component standards align with ISO 15170 electrical interchange requirements. Seoul Capital Area hosts module calibration facilities serving Asia-Pacific OEM customers.
Fuel Sensor Market Competitive Landscape
German producers anchor one tier; Asian foundry specialists hold supply-side leverage over precision capacitive element output. The vendor base concentrates around integrated fuel-system electronics providers and discrete sensor module assemblers, with tier-1 automotive suppliers capturing disproportionate value through closed-loop engine control integration. Three archetypes dominate: MEMS fabrication depth players, harsh-environment sealing specialists, and telematics platform integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure automotive-grade foundry allocation.
Among Germany-based integrated systems providers, Continental AG and Robert Bosch GmbH exemplify the tier-1 archetype that merges sensor hardware with powertrain control electronics. TE Connectivity Ltd. represents the harsh-environment reliability segment, extending aerospace-grade methods into agricultural and off-road applications. These three anchors illustrate how competitive positioning stratifies between system integrators capturing closed-loop value and specialists defending niche sealing expertise.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Bourns Inc. |
| Pricol Ltd. |
| Delphi Technologies Plc |
| TE Connectivity Ltd. |
| Valeo SA |
| Melexis |
| elobau GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap sensor assemblers across Germany and Japan anchor premium-tier pricing discipline through captive certification infrastructure, while private-equity-rolled-up distributors in North America compress channel margins to capture fleet telematics bundling contracts. This ownership bifurcation creates divergent supply responses: European specialists defend margin through ISO 15170 validation depth, whereas consolidated US channels sacrifice hardware markup for recurring software revenue share.
Pricing Analysis
Distributor margin capture runs through three distinct layers: direct-to-OEM contracts command 15-25 point discounts against list, national fleet aggregators extract volume rebates tied to telematics platform commitments, and independent aftermarket channels defend residual markup on legacy resistive replacements. Pricing stratifies across premium, standard, and economy tiers keyed to CARB compliance certification and SAE J1810 validation history. Cost compression in economy-grade analog sensors is intensifying because agricultural OEMs unbundle hardware from service contracts. Fleet management operators show least price sensitivity due to theft-loss recovery value, while cost-constrained farm machinery buyers drive commoditization pressure.
Supply Chain Analysis
ISO 15170 and SAE J1810 qualification gating restricts qualified supplier pools to incumbents with established test histories, fragmenting tier-2 module assembly across Germany, China, and South Korea. Automotive-grade MEMS fabrication draws from Yangtze River Delta foundries, precision elastomer compounds feed from Stuttgart-area chemical specialists, and rare-earth magnet supply for ultrasonic transducers rests on Chinese separation capacity. Single-source vulnerability concentrates in capacitive element wafer supply. Distribution runs through tier-1 automotive system integrators capturing closed-loop ECU integration value, with direct fleet contracting disintermediating traditional parts wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage positioning favors suppliers locating final assembly in Mexico or Southeast Asia to exploit cost differentials against CARB-mandated US fleet demand, while maintaining German or Japanese certification headquarters to preserve premium-tier pricing access.
For Market Incumbents: Extend aerospace-grade sealing expertise into agricultural IoT retrofit markets before TE Connectivity Ltd. consolidates harsh-environment positioning. Defend against telematics platform disintermediation by embedding bidirectional data links directly into tank modules, capturing closed-loop ECU integration value that standalone sensor vendors cannot replicate. Prioritize backward integration into automotive-grade MEMS capacity to secure allocation against Asian foundry constraints. For New Entrants and Emerging Players: Enter via ultrasonic leak detection specialization targeting California environmental compliance deadlines, where non-contact measurement premium outweighs incumbent scale advantages. Agricultural equipment in the US Midwest represents the most penetrable white-space, with legacy machinery retrofit demand outpacing OEM-installed base growth. Pursue direct contracting with regional farm cooperatives unbundling hardware procurement from dealer service agreements. For Investors and Strategic Acquirers: Valuations sit cheapest among analog resistive sensor specialists serving cost-driven agricultural segments, as electrification substitution threat compresses long-term multiple expectations despite near-term replacement cycle stability. Acquisition targets should display ISO 15170 certification infrastructure transferable to capacitive module platforms. Watch EPA Phase Three final rule timing as inflection signal: accelerated medium-duty vehicle compliance deadlines would re-rate precision sensor architectures against commodity alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade MEMS Capacity Expansion | Secures wafer allocation from Yangtze River Delta foundries against supply constraint. |
| Telematics Platform Partnership | Captures recurring software revenue through direct fleet operator subscription relationships. |
| REACH-Compliant Material Reformulation | Validates alternative elastomer compounds under ECHA persistent organic pollutant scrutiny. |
| ISO 15170 Certification Investment | Accelerates time-to-market for replacement sensor designs against incumbent test history. |
| Agricultural IoT Telemetry Launch | Penetrates underpenetrated farm equipment segment with cloud-connected fuel monitoring. |
Research Methodology
Direct dialogue with tier-1 supplier procurement officers, fleet telematics platform engineers, automotive OEM fuel system architects, and agricultural equipment aftermarket distributors grounded qualitative assessment. Secondary validation drew from EPA regulatory filings, CARB enforcement databases, SAE standards documentation, and vehicle production registration data. Bottom-up sensor unit demand estimates triangulated against top-down fuel system electronics market sizing.
Segment-level projections across capacitive, ultrasonic, resistive, and optical architectures were generated over the projection horizon, with technology adoption curves calibrated to CARB compliance deadlines and EPA Phase Three rulemaking trajectory. Modeled dimensions included product type, end-user procurement pattern, interface technology, and application function. CAGRs were derived from replacement cycle compression rates and telematics penetration assumptions, with cross-validation against foundry capacity expansion announcements and OEM platform specification disclosures.
Inputs from EPA and CARB regulatory dockets were available through the study window; gaps in final Phase Three rule specificity introduce uncertainty bands around medium-duty vehicle compliance timing. Forecasts reflect assumptions regarding electrification substitution pace and foundry allocation continuity. A model refresh is warranted upon material change in EPA Phase Three adoption timeline or MIIT automotive standard revisions affecting Chinese OEM platform specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steering Gear Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Front Forks Market
Vehicle Components
Idler Arm Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Air Ride Suspension Systems Market