
 Bicycle Chain Market | 2026-2036
Bicycle Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Chain Market Analysis
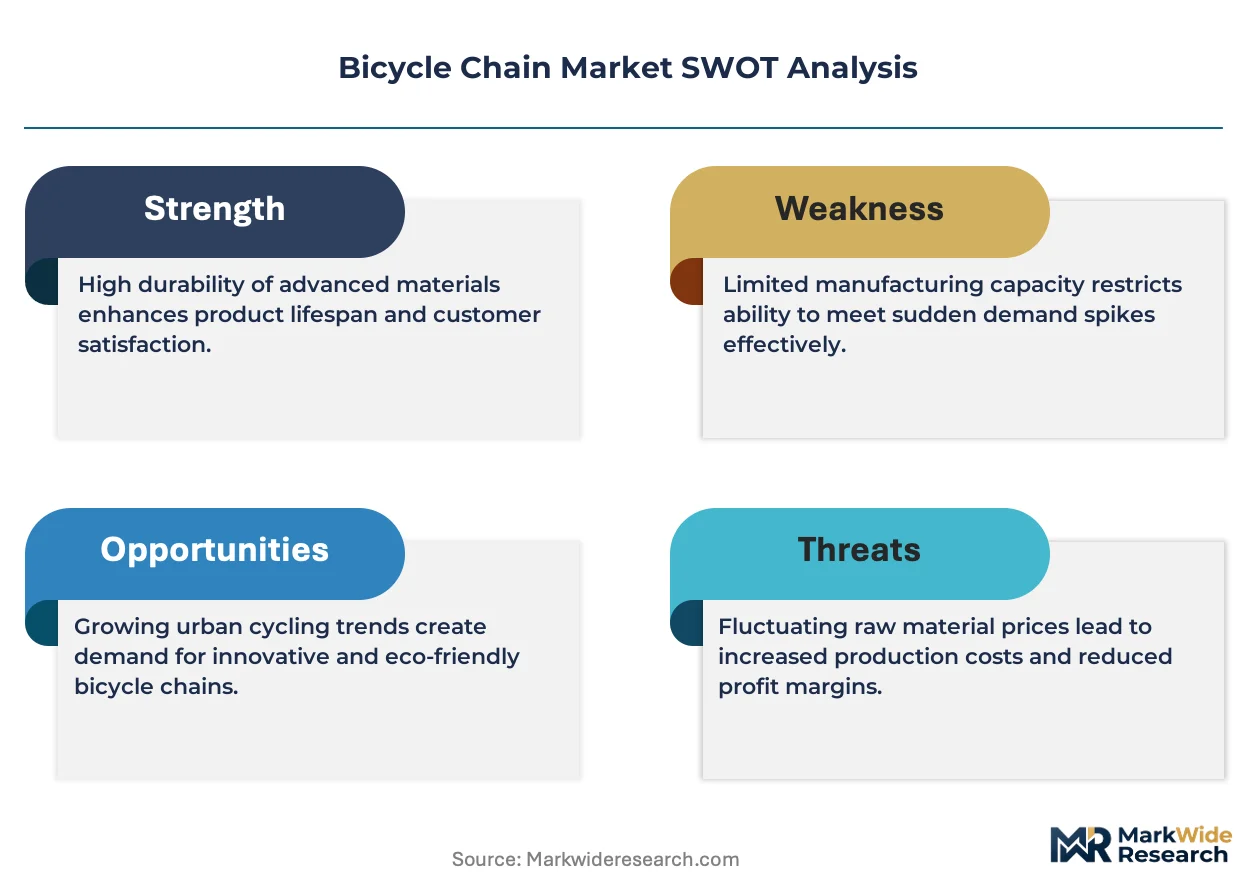
Buyer concentration among e-bike OEMs and direct-to-consumer brands is rebalancing procurement leverage away from traditional independent bike dealers. Shimano Inc. leverages its captive forging and plating infrastructure to control cost positions across premium and mid-tier chain lines. SRAM LLC competes through close integration with its wireless electronic shifting ecosystems, locking in replacement demand. KMC Chain Industrial Co., Ltd. anchors aftermarket volume with broad compatibility across competing drivetrain standards.
A bicycle chain is a roller chain transmitting mechanical power from crankset to rear wheel, typically constructed from hardened steel plates and pins with nickel or chrome surface treatments for wear resistance. The component serves as the critical wear item in bicycle drivetrains, requiring periodic replacement to maintain efficiency and prevent cassette damage. Multi Speed chains command the largest revenue pool due to complexity and precision tolerances, while single speed variants occupy the value-oriented commuter segment. Carbon fiber and alloy material experiments remain niche but attract development dollars from racing-focused suppliers seeking gram reductions.
REACH restrictions in Europe limit hexavalent chromium in electroplating, pushing suppliers toward trivalent alternatives or physical vapor deposition. Japan's METI enforces JIS standards for fatigue testing that shape export qualification protocols for Asian manufacturers. OEMs and aftermarket distributors must monitor how California's Proposition 65 warning requirements affect labeling and channel access for plated steel components entering the US market.
Market Dynamics
E-bike fleet operators are compressing replacement cycles while REACH compliance forces plating chemistry shifts across European supply chains. These dual pressures are restructuring procurement leverage toward OEMs with captive forging capacity and away from fragmented aftermarket distributors.
Growth Catalysts
- REACH electroplating mandates:Tightened hexavalent chromium discharge limits in Europe are accelerating trivalent chromium and physical vapor deposition adoption, creating upgrade demand across mid-tier supplier tooling.
- E-bike commercial fleet expansion:Last-mile delivery and shared mobility operators in Germany and the Netherlands are standardizing preventive maintenance schedules that treat chains as consumables rather than durable components.
- Southeast Asian manufacturing concentration:Thai and Vietnamese forging clusters now capture the majority of multi-speed drivetrain assembly contracts, lowering landed costs for global OEM procurement teams.
Market Restraints
- Specialized steel alloy volatility:Hardened steel plate and pin feedstock costs fluctuate with scrap metal and energy pricing, squeezing margin on economy-grade single-speed chain lines.
- Plating technology lock-in:Electroplating infrastructure in legacy European facilities requires capital-intensive retooling to meet ECHA discharge thresholds, disadvantaging smaller regional suppliers.
- Wireless electronic shifting ecosystems:Proprietary drivetrain architectures from integrated component manufacturers create switching costs that limit aftermarket chain compatibility and price competition.
Strategic Opportunities
- Carbon fiber composite experimentation:Racing-focused suppliers are allocating development budgets to alloy and carbon fiber pin alternatives, targeting gram reduction in professional cycling segments.
- Direct-to-consumer channel buildout:E-bike OEMs are bypassing independent bike dealer networks through subscription and lease models that bundle chain replacement into service contracts.
- California Proposition 65 compliance services:Warning label and material disclosure requirements for plated steel components entering the US market create advisory and logistics revenue streams for distributors with regulatory expertise.
Industry Challenges
- JIS fatigue testing certification timelines:Japan's METI export qualification protocols require extended validation cycles that delay Asian manufacturer market entry and tie up engineering resources.
- Multi-standard compatibility engineering:Chain suppliers must maintain simultaneous compatibility with competing drivetrain geometries, multiplying SKU complexity and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Chain Market |
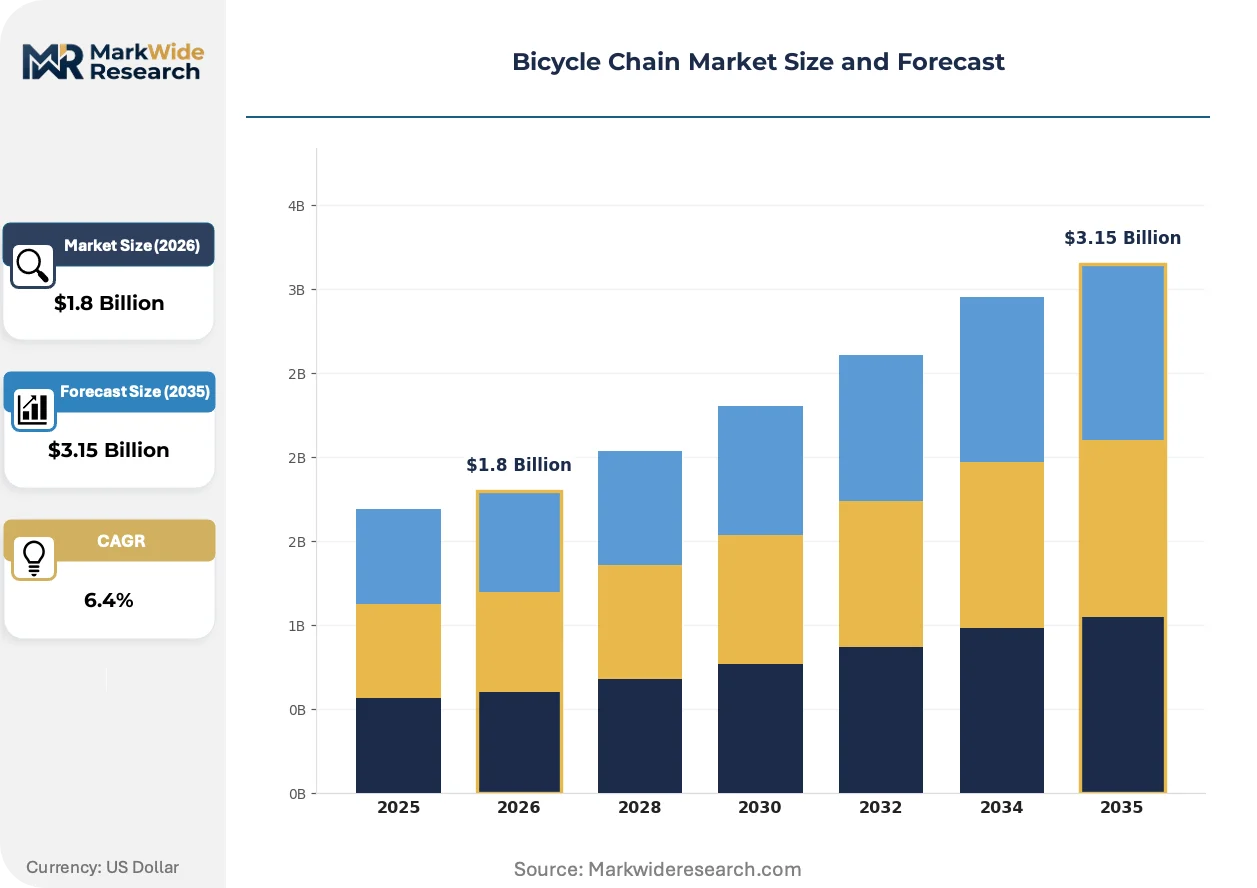
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Speed, Multi Speed, Track, BMX Material: Steel, Aluminum, Carbon Fiber, Alloy Application: Mountain Biking, Road Cycling, Commuting, Racing End User: Recreational Riders, Professional Cyclists, Trade Shops, OEMs |
| Companies Covered | Shimano Inc., SRAM LLC, KMC Chain Industrial Co., Ltd., TAYA Chain Co., Ltd., Izumi Chain Mfg Co., Ltd., Wippermann GmbH, Campagnolo S.r.l., Connex, SunRace Sturmey-Archer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Chain Market Emerging Trajectories
Surface treatment chemistry and procurement consolidation are the dominant forces reshaping competitive positioning. Suppliers are racing to qualify alternative plating processes while buyer concentration shifts volume toward vertically integrated OEMs.
Trivalent chromium electroplating is expanding into mid-tier and premium chain lines as manufacturers phase out hexavalent processes ahead of regulatory deadlines. E-bike OEMs in Northern Europe are specifying these finishes for fleet durability warranties. This transition is compressing the supplier base by disqualifying plating operations lacking capital for chemistry conversion.
Europe's ECHA is enforcing progressively stricter nickel and chromium discharge limits through REACH annex amendments. Forging and plating facilities in Germany and Poland face compliance-driven consolidation or partnership with Southeast Asian toll processors. Multi-speed chain suppliers serving the European aftermarket are most exposed, with many redirecting volume through Thai contract manufacturers.
Fleet operators are unbundling chain replacement from full drivetrain service, creating standalone consumables procurement categories. Direct-to-consumer e-bike brands are capturing this volume through subscription models that pre-schedule component swaps. This pattern is most visible in Dutch and German urban mobility markets where operational uptime metrics override initial component cost.
Bicycle Chain Market Segmentation
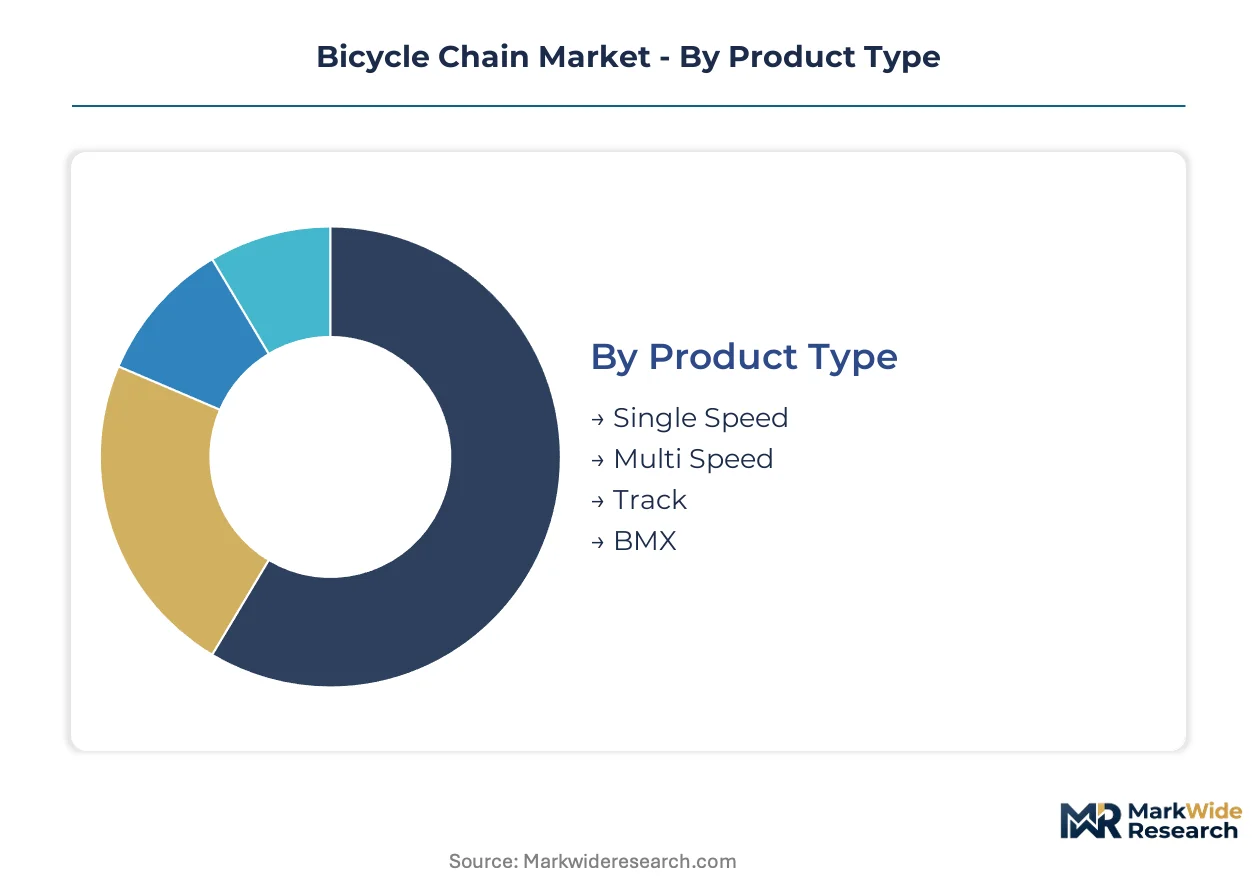
Segmentation in bicycle chains reflects divergent certification burdens across product tiers. REACH plating mandates, JIS fatigue protocols, and OEM qualification requirements create tiered compliance costs that reshape supplier economics and channel access.
Product Type:
REACH electroplating compliance and JIS fatigue testing requirements apply unevenly across product tiers, with multi-speed and track chains facing the heaviest certification loads.
- Multi Speed:Precision roller chains with narrow plate profiles and optimized pin diameters for indexed shifting across 8-13 speed cassettes. Demand concentrates in German and Dutch e-bike fleet procurement where preventive maintenance contracts treat these as consumables, driven by REACH-mandated trivalent chromium finishes for warranty compliance.
- Single Speed:Wider, heavier chains with standardized 1/8 inch pitch for fixed-gear and internally-geared hub applications. Urban commuter markets in Copenhagen and Amsterdam absorb volume, constrained by margin pressure from steel alloy feedstock volatility on economy-grade lines.
- Track:Ultra-narrow, high-tensile chains optimized for velodrome sprint and pursuit disciplines with minimal lateral flexibility. Professional cycling teams in Belgium and Italy specify these for national federation certification protocols.
- BMX:Reinforced plates and oversized pins engineered for high-impact landings and grind durability. Aftermarket demand flows through specialty distributors serving North American and Australian freestyle scenes.
Multi Speed sits at the top of the volume ranking, with Single Speed climbing the fastest as European urban mobility subsidies expand.
Material:
Material selection stratifies across cost tiers and performance requirements, with carbon fiber commanding development budgets while steel maintains procurement dominance.
- Steel:Hardened alloy plates with nickel or chrome surface treatments remain the industrial standard for durability and repairability. Thai and Vietnamese forging clusters now supply the majority of OEM procurement for multi-speed drivetrain assemblies.
- Aluminum:Lightweight alternatives for mid-tier recreational segments where gram reduction justifies wear rate trade-offs. Southeast Asian toll processors handle volume plating for European aftermarket distributors.
- Carbon Fiber:Experimental composite pins and plate reinforcements targeting professional racing weight thresholds. Development concentrates with racing-focused suppliers in Italy and Switzerland seeking UCI equipment approval.
- Alloy:Hybrid material combinations blending steel strength with corrosion-resistant coatings for coastal and all-weather applications. Japanese METI export qualification protocols shape supplier qualification timelines for Asian manufacturers.
Steel dominates procurement tonnage, while Carbon Fiber gains share fastest among racing-focused development budgets.
Application:
Application segments diverge sharply in replacement cycle economics and distribution channel structure.
- Commuting:High-mileage urban use with accelerated wear profiles and subscription-based replacement models. Dutch and German fleet operators unbundle chain service from full drivetrain maintenance.
- Road Cycling:Performance-oriented demand from enthusiast and racing segments with precision tolerance requirements. Italian and Spanish clubs drive premium specification through regional distributor networks.
- Mountain Biking:Contaminated operating environments requiring enhanced corrosion resistance and quick-link serviceability. Pacific Northwest and Alpine European markets prioritize mud-shedding plate geometries.
- Racing:UCI-regulated professional competition with weight-minimized, fatigue-tested components. National federation procurement in France and Belgium mandates JIS-standard validation.
Commuting leads volume as fleet electrification expands, with Racing posting the steepest expansion trajectory in per-unit value terms.
End User:
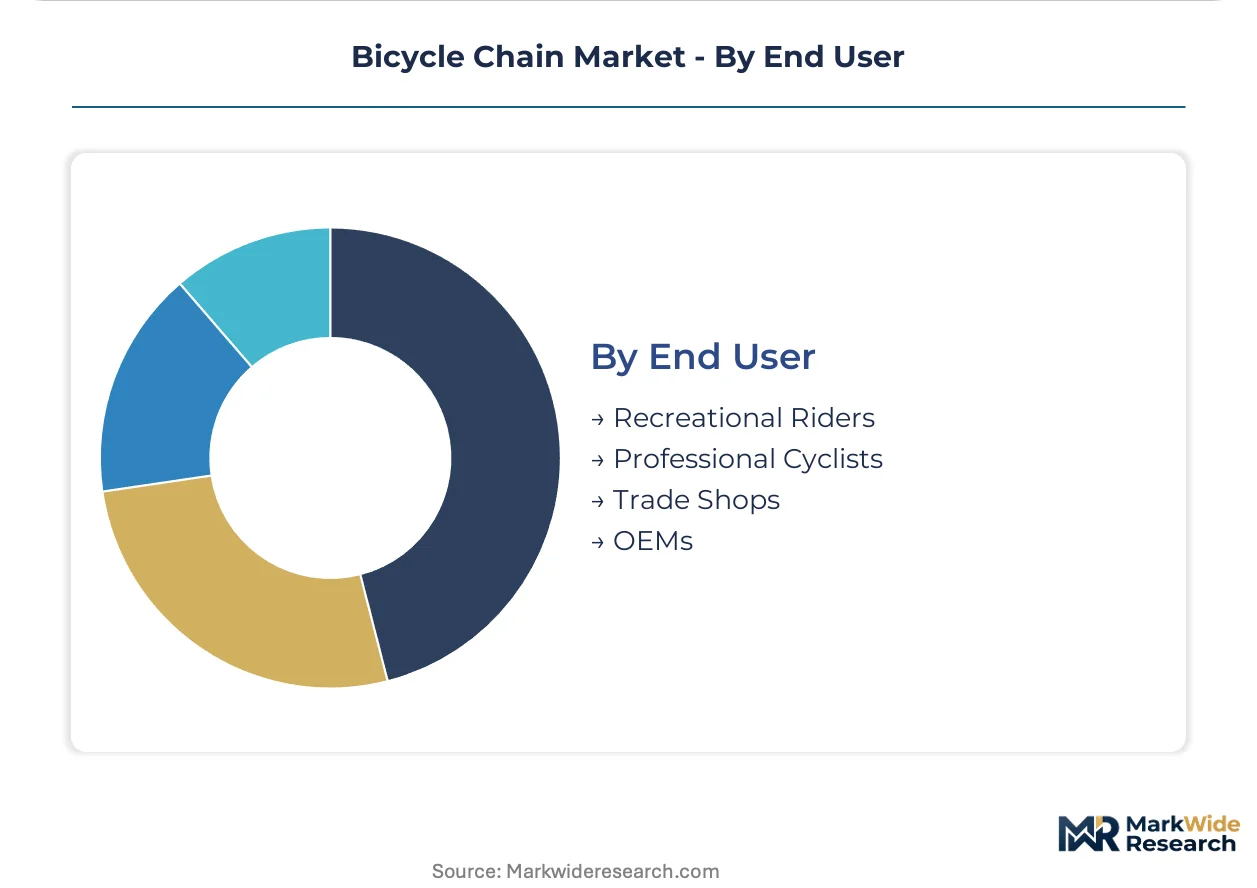
End user concentration is rebalancing procurement leverage toward OEMs and away from fragmented aftermarket channels.
- OEMs:Volume contracts with captive forging and plating infrastructure for specification control. Shimano and SRAM lock in replacement demand through proprietary drivetrain architectures.
- Trade Shops:Independent bike dealer networks facing margin compression from direct-to-consumer brand bypass. German and Benelux service chains consolidate purchasing for aftermarket multi-speed lines.
- Professional Cyclists:Team and federation procurement with equipment approval protocols and sponsorship obligations. UCI equipment regulations and national federation standards govern selection.
- Recreational Riders:Price-sensitive replacement demand through online retailers and mass merchants. California Proposition 65 warning requirements affect labeling for plated steel components entering US distribution.
OEMs command the volume ranking, with Trade Shops losing share fastest to direct-to-consumer subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the Netherlands compress replacement cycles for commercial e-bike fleets, while Southeast Asian forging clusters capture OEM procurement volume. Regulatory divergence across REACH, JIS, and state-level chemical disclosure rules fragments supplier qualification pathways.
Germany
Last-mile delivery operators in Berlin and Hamburg standardize preventive chain replacement every 2,500 kilometers. The country's Federal Motor Transport Authority enforces strict commercial vehicle safety protocols that extend to e-cargo bike fleets. Bavarian component distributors consolidate aftermarket purchasing for multi-speed lines serving independent bike dealer networks.
Netherlands
Shared mobility platforms in Amsterdam and Rotterdam unbundle chain service from full drivetrain maintenance contracts. The Dutch National Institute for Public Health and the Environment monitors nickel discharge from plating operations under EU Water Framework Directive alignment. Eindhoven-region logistics hubs coordinate Southeast Asian toll processing for European aftermarket volume.
Japan
Professional cycling teams in Tokyo and Osaka demand JIS-certified fatigue-tested chains for national federation equipment approval. METI export qualification protocols require extended validation cycles that delay Asian manufacturer market entry. Nagoya-area forging facilities maintain captive plating infrastructure for premium drivetrain component supply.
United States
Recreational rider replacement demand concentrates in California and Colorado mountain biking corridors. The state's Proposition 65 mandates warning labels for plated steel components entering distribution channels. Pacific Northwest specialty retailers prioritize quick-link serviceability for contaminated operating environments.
Thailand
Thai forging clusters now supply the majority of OEM procurement contracts for multi-speed drivetrain assemblies. The country's Industrial Estate Authority of Thailand oversees environmental compliance for electroplating operations serving export markets. Bangkok-region contract manufacturers process volume for European aftermarket distributors facing REACH retooling costs.
Bicycle Chain Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Three to five integrated component manufacturers control premium specification through captive forging and plating infrastructure. Mid-tier suppliers rely on Southeast Asian toll processing for cost positioning. Dominant competitive moves include backward integration into heat treatment operations and geographic expansion through Thai and Vietnamese contract manufacturing partnerships.
Within the integrated drivetrain tier, Shimano Inc. and SRAM LLC exemplify archetypes of specification control through proprietary architectures. KMC Chain Industrial Co., Ltd. anchors the aftermarket compatibility segment with broad standard coverage. These three occupy positions that reflect divergent strategic bets on captive infrastructure versus multi-standard flexibility.
| Leading Market Players |
|---|
| Shimano Inc. |
| SRAM LLC |
| KMC Chain Industrial Co., Ltd. |
| TAYA Chain Co., Ltd. |
| Izumi Chain Mfg Co., Ltd. |
| Wippermann GmbH |
| Campagnolo S.r.l. |
| Connex |
| SunRace Sturmey-Archer Inc. |
| Others |
Supply Flow & Price Mechanics
Trivalent chromium electroplating adoption across European supply chains simultaneously elevates capital requirements for mid-tier suppliers and compresses price competition among qualified plating operations. This chemistry transition concentrates forging and finishing capacity among Thai and Vietnamese contract manufacturers, reshaping procurement leverage toward OEMs with captive toll-processing relationships.
Pricing Analysis
Capacity additions in Thailand and Vietnam are reshaping price floors for multi-speed chain assemblies serving European and North American OEM procurement teams. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with REACH-compliant trivalent finishes commanding premiums over legacy hexavalent plating. Cost compression in economy-grade single-speed lines is intensifying because scrap metal and energy pricing volatility squeezes margin on hardened steel feedstock. Fleet operators in Germany and the Netherlands exhibit lowest price sensitivity due to subscription-based preventive maintenance models, while recreational riders through US online retailers show highest sensitivity to per-unit replacement costs.
Supply Chain Analysis
Workforce availability constraints in Thai and Vietnamese forging clusters are tightening as European aftermarket distributors redirect volume to escape REACH retooling costs. Supply concentrates in Thailand, Vietnam, and Japan, with Nagoya-area facilities maintaining captive plating infrastructure for premium drivetrain components. Raw material dependencies center on hardened steel alloy plate and pin feedstock, nickel and chromium plating chemistry, and specialized heat treatment energy inputs. Single-source vulnerability runs through Southeast Asian toll processors serving multiple OEM qualification protocols simultaneously. Distribution runs through direct-to-consumer e-bike subscription models, independent bike dealer networks in Germany and Benelux, and specialty retailers in Pacific Northwest mountain biking corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through REACH-mandated plating upgrades that disqualify fragmented competitors and consolidate volume among capitalized suppliers. Southeast Asian manufacturing scale combined with European regulatory compliance premiums creates sustainable pricing power for qualified operations.
For Market Incumbents: To counter wireless electronic shifting ecosystem lock-in from integrated drivetrain manufacturers, backward integration into heat treatment operations secures specification control while expanding Thai contract manufacturing partnerships captures European aftermarket volume fleeing legacy plating retooling costs. For New Entrants and Emerging Players: REACH in Europe opens a window for trivalent chromium plating specialists to capture mid-tier supplier tooling upgrade demand. Carbon fiber composite experimentation for professional racing segments offers white-space penetration with UCI equipment approval pathways, while California Proposition 65 compliance advisory services create logistics revenue streams for US market entry. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier suppliers lacking capital for chemistry conversion but holding established European aftermarket relationships. Long-term viability hinges on regulatory compliance durability rather than commodity scale, with Thai and Vietnamese toll-processing partnerships as the inflection indicator signaling qualified supply base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive forging infrastructure locks in specification control for premium drivetrain OEM contracts. |
| Trivalent Chromium Plating Conversion | REACH compliance qualifies suppliers for German and Dutch fleet operator warranty programs. |
| Thai Contract Manufacturing Partnership | Southeast Asian toll processing lowers landed costs for European aftermarket volume redirection. |
| Carbon Fiber Composite Development | UCI equipment approval targets gram reduction premiums in professional cycling team procurement. |
| Direct-to-Consumer Subscription Buildout | E-bike lease models bundle chain replacement into service contracts, bypassing independent dealer networks. |
Methodological Framework
Coverage spans Germany, the Netherlands, Japan, the United States, and Thailand, with primary inputs from each market combining interviews with e-bike fleet procurement managers, component distributor operations heads, plating facility technical directors, and aftermarket retailer category buyers. Secondary validation draws from ECHA REACH annex amendments, METI JIS standard documentation, California Proposition 65 regulatory filings, and Thai Industrial Estate Authority environmental compliance records. Bottom-up and top-down triangulation cross-checks supplier capacity estimates against OEM procurement disclosure patterns.
Rate-of-change decomposition separates volume growth from value expansion across product type, material grade, application segment, and end-user channel dimensions throughout the forecast period. CAGRs derive from segment-level replacement cycle modeling and fleet electrification penetration curves, with e-bike commercial fleet expansion and REACH plating mandate compliance timelines as industry-specific forecast inputs.
Revisions become necessary when ECHA tightens nickel discharge thresholds beyond current trivalent chromium capabilities, when Japanese METI extends JIS fatigue testing validation cycles, or when California expands Proposition 65 warning requirements to additional plated steel components. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
US Automotive Sensors Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Wheel Chocks Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Aluminum Alloy Wheel Market