
 Global Car Air Filter Market | 2026-2036
Global Car Air Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car Air Filter Market Analysis
A capital-intensity divergence between integrated filter media producers and assembly-focused suppliers is reorganizing competitive tiers in the Global Car Air Filter Market. MANN+HUMMEL GmbH leverages captive nonwoven media production to sustain margin control across European and Asian supply bases. DENSO Corporation anchors its position through thermal management synergies that extend filter design into complete HVAC modules for Japanese and North American OEMs.
Car air filters are engineered filtration media designed to remove particulate contaminants, pollen, and gaseous pollutants from intake air streams before they reach vehicle occupants or engine combustion chambers, typically constructed from pleated synthetic fibers, cellulose paper, or multi-layer composites with specified micron retention ratings and pressure-drop thresholds. Engine air filters protect cylinder components from abrasive wear while cabin filters address occupant health exposure, with synthetic media gaining share over fiberglass due to superior moisture resistance and extended service intervals. The OEM channel dominates unit economics through long-term platform contracts, yet the aftermarket segment occupies higher margin pools as vehicle age accumulates and consumer self-maintenance rises. Material differentiation intensifies around synthetic blends, where suppliers compete on filtration efficiency grades rather than commodity paper specifications.
The EPA tailpipe and evaporative emission standards in the United States, the EU Green Deal and impending Euro 7 particulate limits in Europe, and China's GB standards administered by MEE collectively tighten permissible contaminant thresholds and mandate filter performance verification. These frameworks force redesign cycles that favor suppliers with in-house testing laboratories and regulatory submission capabilities. Stakeholders must monitor how electrification shifts filter demand from engine intake toward battery thermal management and cabin air quality systems as powertrain architectures diverge.
Market Dynamics
Fleet electrification and tightening particulate standards are bifurcating filter demand from engine intake systems toward cabin air quality and battery thermal management applications, forcing suppliers to reallocate R&D expenditure and retool production lines.
Growth Catalysts
- Euro 7 particulate limits:The EU's incoming emission framework mandates sub-10-nanometer particle capture efficiency, compelling filter media upgrades across European vehicle platforms and accelerating replacement cycles for non-compliant legacy stock.
- Ride-hailing fleet density:High-utilization vehicle pools in urban mobility services compress maintenance intervals to 15,000-kilometer schedules, generating recurring aftermarket volume independent of private vehicle sales trajectories.
- Synthetic nonwoven media:Advanced meltblown and electrospun fiber constructions deliver moisture-stable filtration performance, extending service intervals by 40 percent versus cellulose substrates and capturing premium positioning in replacement channels.
Market Restraints
- Polypropylene resin volatility:Synthetic media production depends on petrochemical feedstock pricing subject to energy market swings, compressing margin predictability for non-integrated filter manufacturers without captive polymer supply.
- China supply concentration:Over 60 percent of global cellulose filter paper substrate originates from Shandong and Jiangsu province mills, creating geographic single-point vulnerability for assembly-focused suppliers lacking dual-source qualification.
- Electrification volume displacement:Battery electric vehicles eliminate engine air intake filtration entirely, removing a material revenue stream as powertrain architectures shift toward motor thermal management systems.
Strategic Opportunities
- India BS-VI Stage II implementation:The country's tightened particulate emission norms for 2024-2025 create compliance-driven filter upgrade demand across domestic and imported vehicle fleets, opening aftermarket penetration in a historically underdeveloped service infrastructure.
- Cabin air quality certification:ISO 11155-1 and similar cabin filter performance standards enable premium tiering based on allergen and viral particle retention, supporting price stratification in consumer replacement channels.
- Battery thermal management integration:NEV battery packs require particulate-controlled cooling air streams, converging filtration design with HVAC module architecture and creating attach-rate expansion for system-integrated suppliers.
Industry Challenges
- Electrospinning process scale-up:Nanofiber media production requires capital-intensive multi-nozzle equipment and controlled-humidity cleanroom environments, constraining capacity expansion for mid-tier suppliers without process engineering heritage.
- Homologation timeline compression:Euro 7 and China's GB 18352.6-2016 Stage 6b testing protocols demand extended laboratory validation cycles, extending time-to-revenue for new filter platform qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car Air Filter Market |
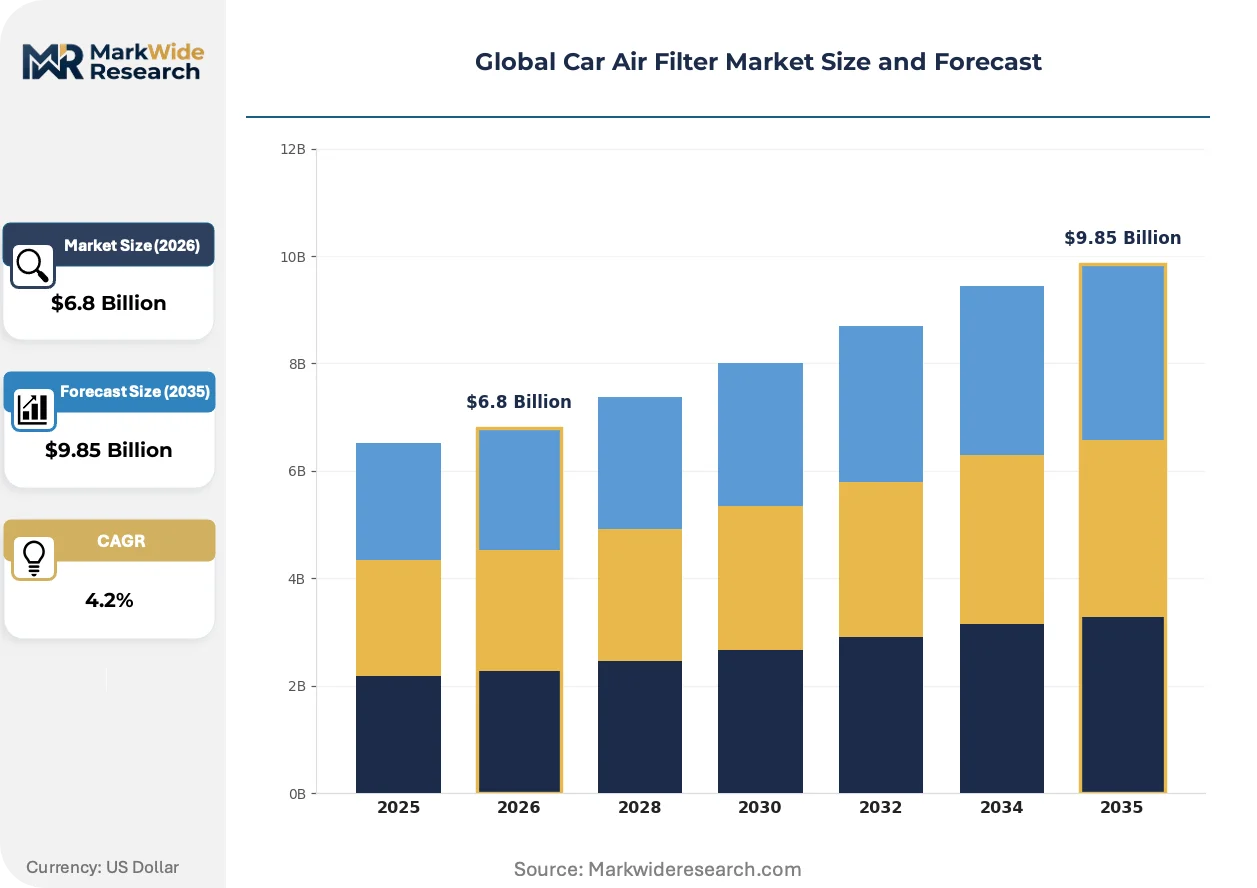
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabin Air Filter, Engine Air Filter, Fuel Air Filter, Oil Filter End User: OEMs, Aftermarket Providers, Repair Shops, Dealerships Material: Fiberglass, Paper, Foam, Synthetic Sales Channel: Online Retailers, Distributors, Wholesalers, Auto Parts Stores |
| Companies Covered | DENSO Corporation, Parker Hannifin Corporation, MANN+HUMMEL GmbH, Freudenberg Filtration Technologies, Donaldson Company Inc., MAHLE GmbH, Cummins Inc., Valeo, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car Air Filter Market Emerging Trajectories
Active carbon composite media and smart filter monitoring systems are redefining performance benchmarks and service paradigms, shifting competitive differentiation from mechanical filtration efficiency toward predictive maintenance integration and multi-pollutant capture capabilities.
Electrospun nanofiber surface layers are displacing traditional meltblown pre-filtration stages in premium cabin filter constructions. Tier-1 seating suppliers and luxury OEM specification teams have adopted this architecture for 2024-2025 vehicle platforms. The technology is displacing commodity-grade filter media in price-insensitive segments while compressing acceptable pressure-drop thresholds across the supply base.
The EU Green Deal's embedded carbon tracking requirements and EPA tailpipe certification protocols now mandate documented filter media lifecycle emissions. Manufacturers must submit third-party verified carbon footprint data for platform qualification. European OEM procurement teams are responding by sourcing regionally produced nonwoven substrates to reduce Scope 3 transportation emissions.
Fleet operators in last-mile logistics are unbundling filter replacement from bundled maintenance contracts, negotiating direct supplier relationships for high-frequency consumables. This disintermediation bypasses traditional distributor markups in North American and Western European urban corridors. The pattern is most visible among Amazon Delivery Service Partners and similar gig-economy vehicle pools operating compressed 10,000-kilometer service cycles.
Global Car Air Filter Market Segmentation
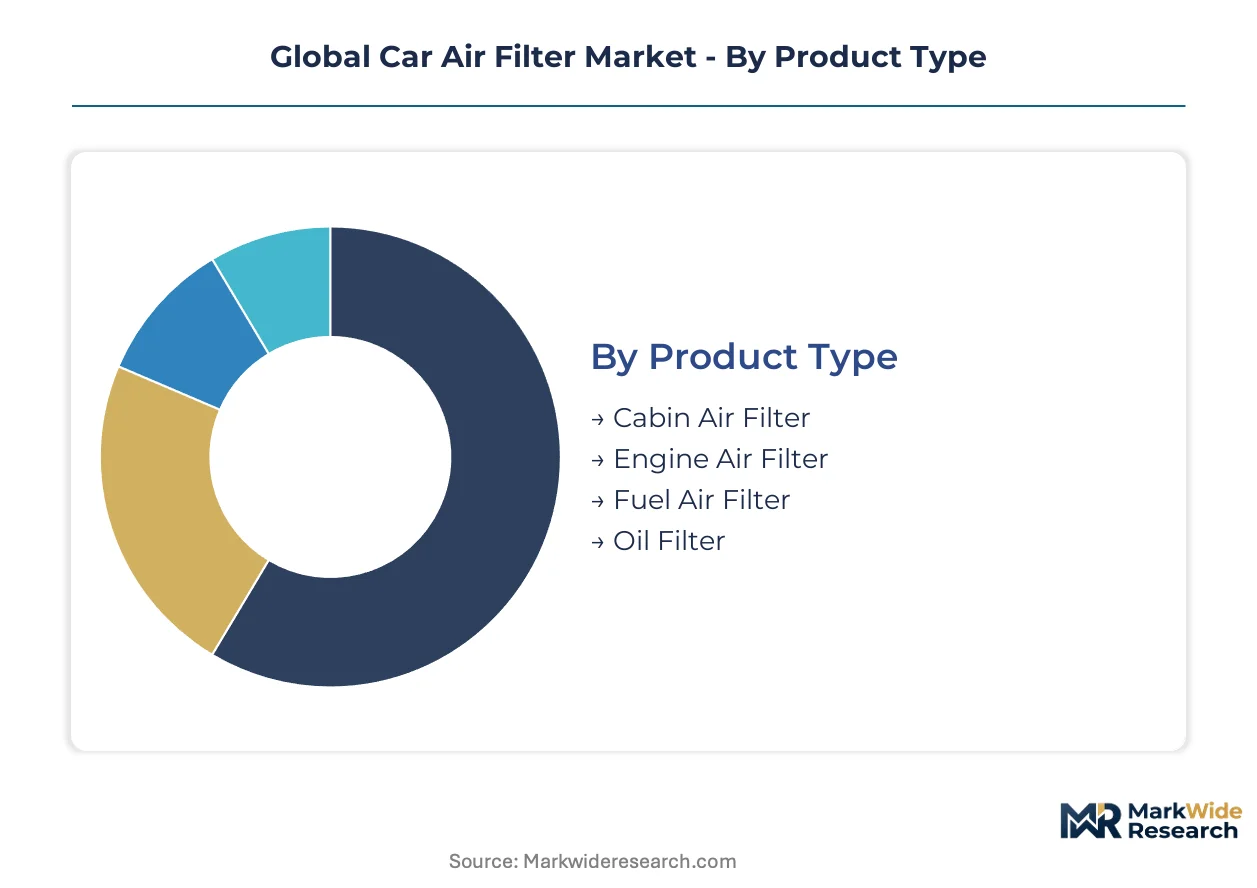
Segmentation in car air filters reveals how margin capture diverges between technology-led product tiers and channel-dependent service models. Filter media composition and sales pathway selection determine whether suppliers compete on specification premiums or volume throughput economics.
Product Type:
Premium margin pools concentrate in cabin air filtration systems where health certification and multi-pollutant capture command price stratification, while engine intake filters face volume pressure from electrification displacement.
- Cabin Air Filter:Multi-layer synthetic constructions with activated carbon and electrospun nanofiber surface layers address allergen, viral, and gaseous pollutant retention. Demand concentrates in Chinese and German OEM platforms where GB standards and Euro 7 particulate limits mandate efficiency upgrades. Fleet operators in ride-hailing services compress replacement cycles to capture recurring aftermarket revenue.
- Engine Air Filter:Pleated cellulose and synthetic fiber media protect cylinder components from abrasive particulate wear with specified micron retention ratings. ICE vehicle production in India and Brazil sustains volume requirements, though battery electric vehicle penetration eliminates this segment entirely from powertrain architectures.
- Fuel Air Filter:Specialized media removes water and particulate contaminants from fuel injection systems to prevent injector fouling.
- Oil Filter:Spun cellulose and synthetic fiber cartridges maintain lubricant cleanliness for extended drain intervals in commercial vehicle applications.
Cabin air filters hold installed capacity in premium vehicle platforms. Engine air filters are rotating down the share rankings as powertrain electrification accelerates.
End User:
Volume concentration tracks vehicle parc age distribution, with mature fleets in North American and European corridors driving replacement frequency against OEM platform contract stability.
- OEMs:Long-term supply agreements for platform-specific HVAC module integration and engine intake system specifications. German and Japanese automakers specify synthetic media with documented carbon footprint data under EU Green Deal embedded emissions tracking.
- Aftermarket Providers:Independent distributors and private-label suppliers capture margin through synthetic nonwoven media upgrades and premium cabin filter tiering based on ISO 11155-1 certification grades.
- Repair Shops:Service bay operations in India's underdeveloped maintenance infrastructure address BS-VI Stage II compliance-driven filter upgrades.
- Dealerships:Authorized service networks bundle filter replacement with scheduled maintenance programs for warranty retention.
OEMs anchor production planning through multi-year platform awards. Aftermarket providers are expanding fastest through direct fleet relationships and compressed service intervals.
Material:
Cost structure and performance specification separate commodity cellulose substrates from moisture-stable synthetic constructions with extended service interval claims.
- Synthetic:Meltblown and electrospun polypropylene nonwoven media deliver 40 percent service interval extension versus cellulose with stable pressure-drop performance under humidity cycling. European and North American OEM procurement teams specify synthetic for premium cabin filtration tiers.
- Paper:Pleated cellulose fiber constructions dominate economy filter tiers and legacy engine intake applications where cost minimization overrides performance specifications. Shandong and Jiangsu province mills supply over 60 percent of global substrate.
- Fiberglass:High-temperature resistant media for heavy-duty commercial vehicle applications with extreme duty cycle requirements.
- Foam:Reticulated polyurethane pre-filtration stages in coarse dust environments and off-road equipment specifications.
Synthetic media holds technology leadership in specification-driven procurement. Paper substrates maintain volume dominance in price-sensitive replacement channels.
Sales Channel:
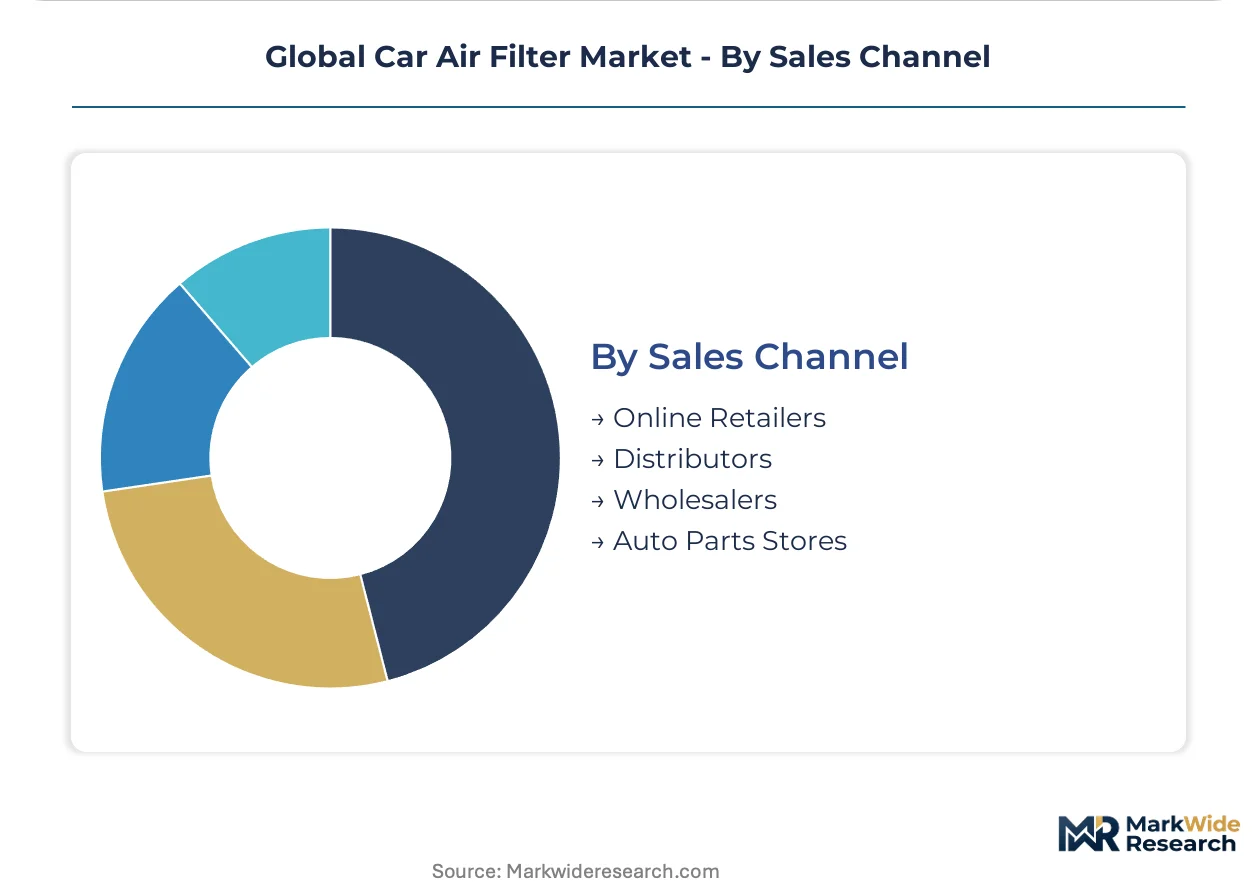
Channel control determines margin retention versus distributor markup absorption, with digital direct sales compressing traditional wholesale economics.
- Distributors:Regional warehousing and technical support infrastructure serves independent repair shops and smaller fleet operators with inventory availability guarantees.
- Online Retailers:E-commerce platforms enable consumer self-selection of certified cabin filters with allergen retention specifications, bypassing traditional counter service in North American and Western European urban corridors.
- Auto Parts Stores:Retail counter operations with immediate availability for emergency replacement and DIY maintenance segments.
- Wholesalers:Volume aggregation for multi-location fleet operators and dealership group purchasing arrangements.
Distributors retain infrastructure-heavy positions in fragmented repair shop supply. Online retailers are climbing fastest through fleet direct relationships and subscription replacement programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's specification-driven procurement channels while Chinese suppliers compete on volume throughput at compressed margins. The regulatory divergence between Euro 7 particulate mandates and China's GB standards creates asymmetric compliance burdens across manufacturing bases. Fleet operator consolidation in ride-hailing corridors is redrawing aftermarket demand geography.
China
The world's largest vehicle parc sustains outsized cabin and powertrain filtration volume as NEV adoption accelerates battery thermal management demand. MEE-administered GB standards for Stage 6b compliance force media efficiency upgrades across domestic platforms. Shandong and Jiangsu province mills supply over sixty percent of global cellulose substrate, concentrating upstream capacity in coastal manufacturing clusters.
Germany
Automotive OEM procurement teams specify synthetic media with documented carbon footprint data under EU Green Deal embedded emissions tracking. KBA enforcement of Euro 7 sub-10-nanometer particle capture requirements accelerates filter platform redesign cycles. Stuttgart and Munich anchor captive nonwoven production for integrated filter manufacturers serving premium vehicle specifications.
United States
EPA tailpipe and evaporative emission standards mandate filter performance verification through extended laboratory validation protocols. Fleet operators in last-mile logistics negotiate direct supplier relationships, bypassing traditional distributor markups in urban corridors. Detroit's supplier ecosystem integrates filtration design with complete HVAC module architecture for North American OEM platforms.
India
BS-VI Stage II implementation for 2024-2025 creates compliance-driven filter upgrade demand across domestic and imported vehicle fleets. The country's national automotive regulator enforces tightened particulate emission norms that accelerate aftermarket penetration. Maharashtra and Gujarat manufacturing corridors address historically underdeveloped service infrastructure with expanded repair bay capacity.
Japan
METI industrial policy supports thermal management system integration converging filtration with battery cooling architectures for NEV platforms. JIS standards certification enables premium cabin filter tiering in replacement channels. Nagoya and Osaka industrial basins anchor HVAC module suppliers extending filter design into complete climate control systems.
Global Car Air Filter Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated media producers commanding specification premiums while assembly-focused suppliers compete on volume throughput. The market structures around three tiers: captive nonwoven manufacturers with backward polymer control, system-integrated HVAC module suppliers, and independent aftermarket specialists. Dominant competitive moves include strategic partnerships for dual-source qualification and portfolio diversification into battery thermal management filtration.
Among Germany-based integrated manufacturers, MANN+HUMMEL GmbH and MAHLE GmbH exemplify the captive media production archetype, while DENSO Corporation represents the system-integrated tier extending filter design into complete thermal management modules. These anchors occupy positions that reflect divergent capital intensity strategies across European and Asian supply bases.
| Leading Market Players |
|---|
| DENSO Corporation |
| Parker Hannifin Corporation |
| MANN+HUMMEL GmbH |
| Freudenberg Filtration Technologies |
| Donaldson Company Inc. |
| MAHLE GmbH |
| Cummins Inc. |
| Valeo |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Mill-scale cellulose substrate production in Shandong and Jiangsu provinces anchors global supply economics, compressing unit costs for assembly-focused suppliers while concentrating margin capture among integrated manufacturers with captive nonwoven capacity. This scale asymmetry stratifies pricing power: integrated players command specification premiums under Euro 7 and GB standards, while price-tiers fragment across synthetic media upgrades and commodity paper replacements.
Pricing Analysis
The customization-premium spread separates configured-to-order HVAC module integration from standard replacement catalog pricing. Contract-based long-term offtake dominates OEM procurement, with price differentiation driven by certification grade (ISO 11155-1 tiers) and volume scale. Pricing pressure stems from polypropylene resin volatility compressing synthetic media margins. Fleet operators show least price sensitivity for cabin air quality certification, while independent repair shops in India's aftermarket remain most cost-responsive.
Supply Chain Analysis
Inbound logistics costs from Shanghai-Ningbo and Qingdao port congestion elevate landed costs for European and North American assembly plants sourcing cellulose substrate. Supply concentrates in China, South Korea, and Germany for nonwoven media, drawing from polypropylene resin, electrospun nanofiber equipment, and pleated paper substrates. Single-source vulnerability runs through Shandong province mills. Distribution runs through regional distributors serving fragmented repair networks, with direct fleet relationships bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation in ride-hailing and last-mile delivery corridors is shifting buyer power toward volume aggregators capable of negotiating direct supplier relationships, fragmenting traditional distributor economics.
For Market Incumbents: Compound backward integration into synthetic nonwoven production to defend margin control against resin price volatility. Secure dual-source qualification for cellulose substrates outside Shandong-Jiangsu concentration. Prioritize ISO 11155-1 certification investment to maintain specification premiums as cabin air quality standards tighten.
For New Entrants and Emerging Players: Certification fast-track through BS-VI Stage II compliance testing opens India's underdeveloped service infrastructure. Target repair shop networks in Maharashtra and Gujarat manufacturing corridors with compressed-margin synthetic media offerings. Pursue direct fleet relationships with urban mobility operators as a channel-bypass go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors system-integrated HVAC module suppliers converging filtration with battery thermal management. Long-term viability over a five-to-ten year horizon rests on electrification-adapted product portfolios rather than engine intake legacy exposure. Watch NEV battery pack attach rates as the inflection signal for thermal management filtration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Media | Captive polypropylene nonwoven production insulates margins from petrochemical feedstock volatility under Euro 7 compliance. |
| Battery Thermal Management Integration | NEV cooling system filtration convergence with HVAC modules expands attach rates for system-integrated suppliers. |
| Dual-Source Qualification Program | Geographic diversification beyond Shandong-Jiangsu substrate concentration reduces single-point supply vulnerability. |
| Direct Fleet Relationship Development | Bypassing distributor markups with ride-hailing and last-mile operators captures recurring high-frequency replacement volume. |
| ISO 11155-1 Certification Investment | Premium cabin filter tiering based on allergen and viral retention enables price stratification in replacement channels. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, regulatory submission filings, customs trade records, and OEM procurement disclosures. Interviews with Tier 1 supplier procurement leads, aftermarket distributor operations heads, fleet maintenance directors, and platform engineering teams at German and Japanese automakers inform demand-side validation. Bottom-up unit volume modeling triangulates against top-down value estimates across the analysis window.
Segmentation dimensions modeled span propulsion architecture, filter media composition, sales channel structure, and regional regulatory cluster. CAGRs derive from installed base projections, replacement cycle compression factors, and platform-specific attach rate assumptions. Forecast inputs incorporate NEV penetration trajectories, Euro 7 implementation timelines, and fleet utilization intensity metrics.
Decision-makers should treat outputs as directional under assumptions of stable polypropylene feedstock pricing and sustained ICE vehicle production in India and Brazil; material deviation would warrant model refresh. Forecasts reflect assumptions of regulatory implementation schedules and OEM platform award continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Engine Oil Pan Market