
 Air Filter for Automotive Market | 2026-2036
Air Filter for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Air Filter for Automotive Market Analysis
EPA Tier 3 tailpipe standards is consolidating the cost-of-entry calculus for automotive air filter suppliers, forcing material upgrades and testing investments that favor scaled manufacturers. MANN+HUMMEL leverages its captive nonwoven media production to absorb these compliance costs internally. Donaldson Company, Inc. sustains dominant positions in heavy-duty commercial filtration through proprietary nanofiber layering technology. MAHLE GmbH anchors European OEM supply chains with integrated cabin and powertrain filter portfolios.
An automotive air filter is a porous mechanical device, typically constructed from pleated cellulose, synthetic fibers, or activated carbon composites, designed to remove particulate matter and gaseous contaminants from intake or cabin air streams. Its primary purpose is protecting engine components from abrasive wear while ensuring occupant respiratory safety in enclosed vehicle environments. Pleated designs dominate OEM fitments due to superior surface-area-to-volume ratios and pressure-drop efficiency. HEPA-grade cabin filters represent the fastest-expanding technology segment as electric vehicle architectures eliminate engine intake demand and shift filtration priority toward occupant health. Aftermarket channels occupy mature, price-sensitive volume pools, whereas OEM contracts concentrate margin in long-term platform agreements with vehicle assemblers.
EPA regulations in the United States, REACH chemical compliance in Europe, and China's GB standards collectively shape particulate filtration thresholds and material disclosure requirements across major supply corridors. NHTSA cabin air quality guidelines and ECE R34 vehicle interior standards further define product certification pathways for multinational suppliers. Stakeholders must monitor how emerging solid-state battery thermal management architectures alter under-hood airflow patterns and filter placement geometry.
Market Dynamics
HEPA-grade cabin filtration is compressing demand for conventional engine intake filters as electric vehicle architectures eliminate under-hood air induction requirements. This technology pivot concentrates margin in occupant health applications while eroding legacy powertrain filter volumes.
Growth Catalysts
- EPA Tier 3 tailpipe standards:Commercial truck fleets across the United States are retrofitting filtration systems to meet stricter particulate thresholds, accelerating replacement cycles for heavy-duty intake media.
- Synthetic fiber nonwovens:Advanced meltblown and electrospun materials are capturing share from pleated cellulose in premium OEM fitments due to superior efficiency-to-pressure-drop ratios.
- Germany's automotive manufacturing cluster:Concentrated premium vehicle production around Stuttgart and Munich sustains dense supplier ecosystems for integrated cabin and powertrain filter portfolios.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyester fiber costs fluctuate with crude oil indices, compressing margin stability for synthetic media manufacturers.
- REACH chemical disclosure requirements:European compliance mandates add testing overhead and material certification timelines that disadvantage smaller compounders without dedicated regulatory teams.
- Activated carbon substitution:Zeolite-based adsorbents are displacing traditional carbon composites in cabin odor-control applications, threatening legacy material supply contracts.
Strategic Opportunities
- India's expanding passenger vehicle production:Domestic OEM capacity additions around Chennai and Pune create uncontracted volume for tier-one filter suppliers establishing local compounding operations.
- China's GB standards for cabin air quality:Mandatory PM2.5 filtration thresholds for new vehicle registrations are pulling HEPA-grade technology into mass-market segments previously served by standard media.
- Direct-to-fleet digital distribution:Commercial vehicle operators are bypassing traditional aftermarket wholesalers through platform-based procurement, opening margin capture for manufacturers with logistics integration.
Industry Challenges
- Electrospinning process engineering:Scaled nanofiber production requires specialized equipment and cleanroom protocols that exceed legacy pleating facility capabilities.
- ECE R34 cabin air certification timelines:European homologation testing for new filter geometries extends platform launch schedules, compressing development windows for model-year synchronized products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Filter for Automotive Market |
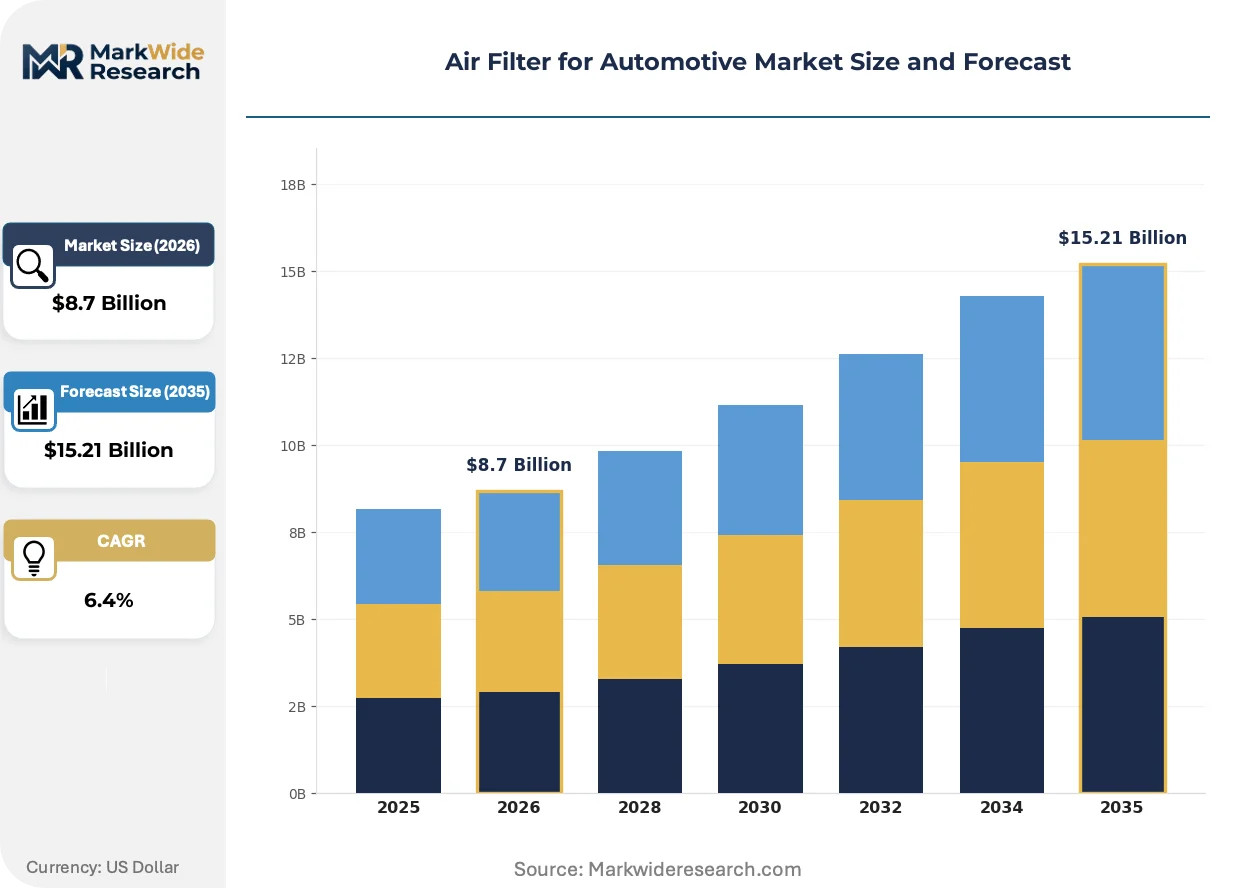
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pleated, Panel, Cartridge, Foam Application: Passenger Vehicles, Commercial Trucks, SUVs, Motorcycles Technology: Electrostatic, HEPA, Activated Carbon, Fiberglass End User: OEMs, Aftermarket, Fleet Operators, Vehicle Assemblers |
| Companies Covered | MANN+HUMMEL, Donaldson Company, Inc., MAHLE GmbH, Robert Bosch GmbH, DENSO Corporation, Ahlstrom-Munksjö, Cummins Inc., K&N Engineering, Inc., Hengst SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Filter for Automotive Market Emerging Trajectories
Filtration technology is bifurcating between precision-engineered synthetic media for electric vehicle cabins and cost-optimized solutions for remaining internal combustion powertrains. Material science advances are compressing the performance gap between premium and standard product tiers.
Electrospun nanofiber layers are expanding into electric vehicle cabin air systems as the primary barrier against ultrafine particulates and biological aerosols. OEMs serving the European premium segment are specifying multilayer composites with sub-micron filtration efficiency at standard pressure-drop levels. This capability compression is expanding into mid-price vehicle categories as battery electric architectures standardize around HEPA-equivalent occupant protection.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of adhesive binders and hydrophobic coatings used in pleated media manufacturing. Compounders serving the European aftermarket must recertify existing product lines under ECHA's updated SVHC candidate list, extending inventory transition periods. Cabin filter suppliers with captive chemical synthesis capabilities are absorbing these compliance costs more rapidly than outsourced competitors.
Fleet operators in North America are consolidating filter procurement through integrated vehicle maintenance platforms that bundle consumables with telematics-enabled service scheduling. Traditional jobber distributors are losing share to direct manufacturer relationships with national leasing companies and municipal transport authorities. This channel compression is most visible in California and Texas, where large commercial vehicle concentrations support dedicated logistics infrastructure for high-volume filter replenishment programs.
Air Filter for Automotive Market Segmentation
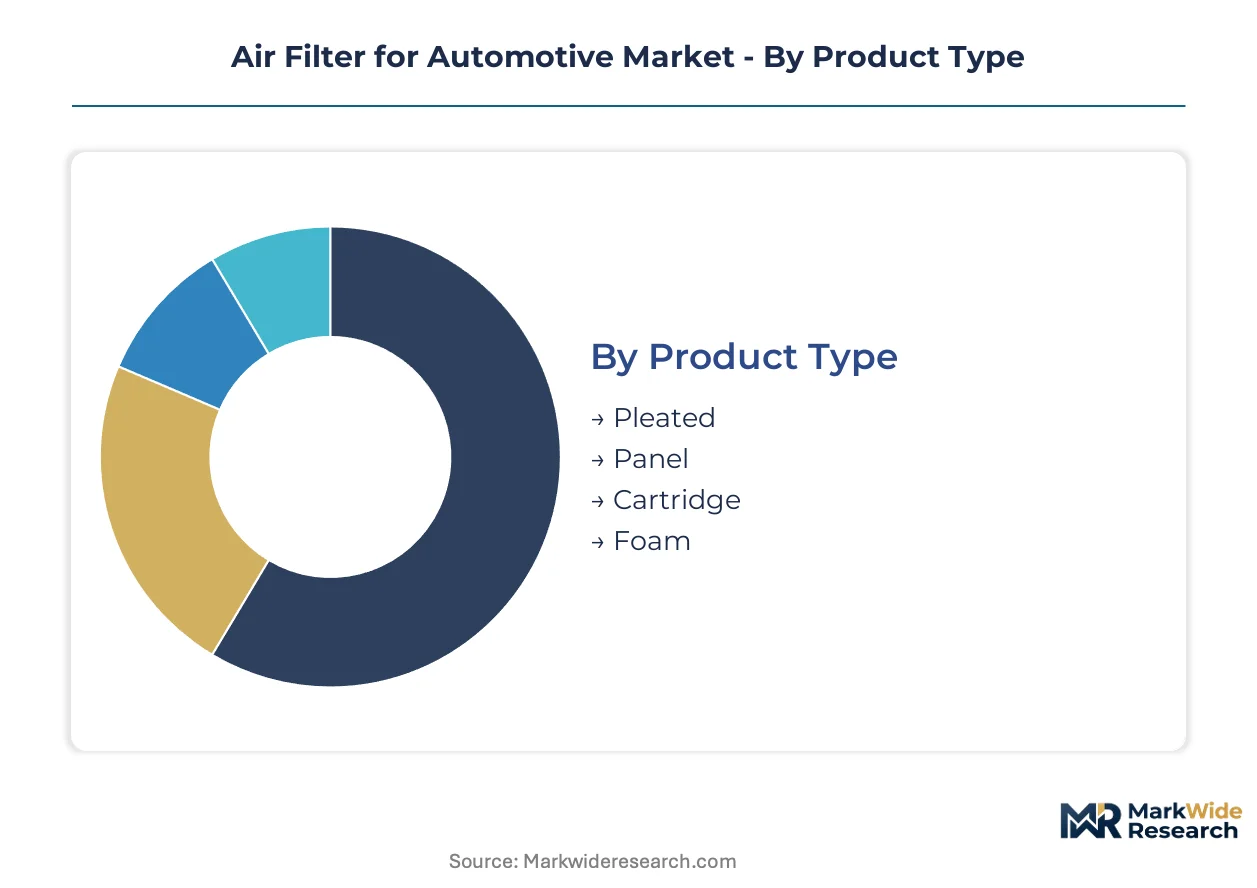
Segmentation in automotive air filtration reflects divergent engineering priorities across powertrain architectures. Electric vehicle cabin systems demand precision-grade media while internal combustion applications optimize for cost-efficiency and service intervals.
Product Type:
Standalone filter housings dominate serviceable applications, whereas embedded cartridge systems integrate into sealed powertrain modules with extended replacement cycles.
- Pleated:Multi-layer cellulose or synthetic fiber matrices folded into corrugated geometries maximize surface area within compact engine bay envelopes. Demand clusters in German passenger vehicle manufacturing where MANN+HUMMEL and MAHLE specify high-efficiency variants for turbocharged direct-injection engines requiring stringent particulate control.
- Panel:Flat-sheet configurations with perimeter sealing gaskets serve cost-optimized vehicle platforms and high-volume aftermarket replacement. Volume concentrates in North American light-duty truck production where rectangular intake geometries accommodate standardized filter dimensions across model years.
- Cartridge:Cylindrical or oval elements designed for drop-in replacement within reusable plastic housings reduce material waste per service event. Fleet operators in California specify cartridge systems for municipal bus fleets to align with state procurement sustainability mandates.
- Foam:Reticulated polyurethane or polyester open-cell structures provide coarse pre-filtration in off-road and powersport applications where dust loading exceeds standard media capacity. ATV and side-by-side manufacturers in Texas integrate foam layers as primary intake barriers for desert operating conditions.
Volume placements concentrate in Panel configurations; the faster expansion belongs to Cartridge systems as OEMs design for reduced service waste.
Application:
Cost tiers separate mass-market passenger fitments from premium commercial specifications, with SUVs commanding intermediate pricing due to dual cabin and engine filtration requirements.
- Passenger Vehicles:Compact sedans and hatchbacks specify standardized pleated media with 99% efficiency ratings at 10 microns. China's GB cabin air standards are pulling HEPA-grade technology into mass-market electric vehicle segments previously served by conventional media.
- Commercial Trucks:Heavy-duty diesel platforms require multi-stage intake filtration with safety elements protecting turbocharger compressors from catastrophic dust ingestion. EPA Tier 3 compliance is accelerating replacement cycles for Class 8 fleets operating across interstate corridors.
- SUVs:Elevated dust ingestion profiles and premium cabin air expectations drive dual-filter architectures with separate engine intake and climate control media. Three-row configurations in Stuttgart's manufacturing cluster specify activated carbon composites for odor control in recirculation-heavy operating modes.
- Motorcycles:Compact form factors and high vibration environments favor foam or hybrid foam-pleated constructions with integral sealing frames. Pune's expanding two-wheeler production base creates uncontracted volume for tier-one suppliers establishing local compounding operations.
Commercial Trucks capture the steepest expansion trajectory; Passenger Vehicles retain the largest installed base for replacement demand.
Technology:
Maturity gradients separate established mechanical filtration from emerging electromechanical approaches, with premium positioning concentrated in cabin air applications.
- HEPA:High-efficiency particulate air media rated at 99.97% capture for 0.3-micron particles serve electric vehicle cabin systems where occupant health replaces engine protection as the primary filtration objective. European premium OEMs specify multilayer composites with sub-micron efficiency at standard pressure-drop levels.
- Activated Carbon:Impregnated cellulose or synthetic substrates adsorb gaseous contaminants and volatile organic compounds in climate control recirculation modes. Zeolite-based alternatives are displacing traditional carbon composites in odor-control applications, threatening legacy material supply contracts.
- Electrostatic:Permanently charged synthetic fibers enhance particulate capture through electrostatic attraction without denser mechanical structures that increase airflow resistance. Emerging applications in Asian electric vehicle platforms leverage low-pressure-drop characteristics for extended range optimization.
- Fiberglass:Borosilicate or microglass matrices provide absolute-rated filtration for critical engine control systems and laboratory-grade cabin specifications. Niche deployment in high-performance internal combustion engines where sensor protection demands sub-micron retention.
HEPA configurations are gaining share fastest; Activated Carbon retains the broadest aftermarket penetration for odor-sensitive applications.
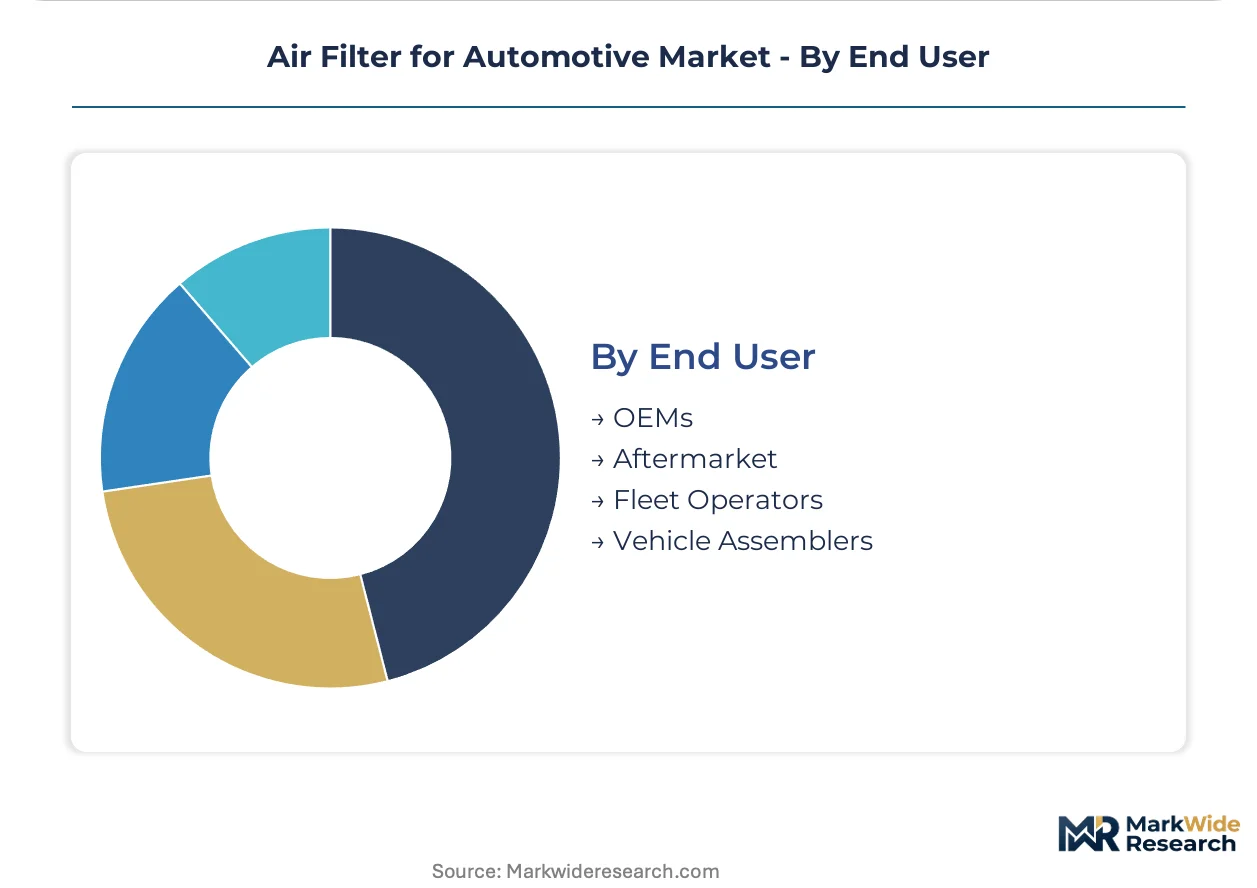
End User:
Customer type determines margin structure, with long-term OEM contracts concentrating engineering resources while aftermarket channels absorb volume volatility.
- OEMs:Original equipment manufacturers specify platform-integrated filtration systems with synchronized development timelines and multi-year supply agreements. MANN+HUMMEL leverages captive nonwoven media production to absorb compliance cost pressures from REACH substance restrictions.
- Aftermarket:Independent service channels and retail distributors serve price-sensitive replacement demand with standardized product lines across vehicle parc diversity. Traditional jobber distributors are losing share to direct manufacturer relationships with national leasing companies.
- Fleet Operators:Consolidated commercial vehicle purchasers negotiate volume-based procurement with telematics-enabled service scheduling integration. Platform-based procurement in Texas and California is opening margin capture for manufacturers with dedicated logistics infrastructure.
- Vehicle Assemblers:Contract manufacturing partners and regional assembly operations source filter modules as part of integrated HVAC or powertrain subsystem supply. Chennai's expanding domestic OEM capacity creates procurement opportunities for tier-one suppliers with local compounding capabilities.
Aftermarket channels retain volume dominance; Fleet Operators are climbing the fastest as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive air filter production concentrates near vehicle assembly corridors where just-in-time delivery requirements and emissions compliance create geographic lock-in. Germany's automotive manufacturing cluster around Stuttgart and Munich sustains dense supplier ecosystems for integrated cabin and powertrain filter portfolios.
United States
Commercial truck fleets operating interstate corridors drive heavy-duty intake filter demand as EPA Tier 3 tailpipe standards accelerate replacement cycles. NHTSA cabin air quality guidelines shape product certification pathways for suppliers serving domestic OEMs. Manufacturing activity clusters in Michigan and Ohio where tier-one suppliers co-locate with vehicle assembly plants.
Germany
Premium vehicle production around Stuttgart anchors OEM supply relationships for HEPA-grade cabin filtration systems. REACH chemical disclosure requirements from ECHA mandate material certification timelines that favor scaled manufacturers with dedicated regulatory teams. MANN+HUMMEL and MAHLE maintain integrated filter portfolios serving European premium segments.
China
GB standards for cabin air quality mandate PM2.5 filtration thresholds for new vehicle registrations, pulling HEPA technology into mass-market segments. MIIT regulations on vehicle interior materials shape filter media specifications for domestic electric vehicle platforms. Production concentrates in Yangtze River Delta manufacturing corridors serving battery electric vehicle assemblers.
India
Expanding passenger vehicle production around Chennai and Pune creates procurement opportunities for tier-one filter suppliers establishing local compounding operations. BIS certification requirements for automotive components extend product validation timelines for imported media. Two-wheeler manufacturing in Pune favors compact foam filtration solutions for high-vibration applications.
Japan
Electric vehicle cabin air systems specification from domestic OEMs drives demand for electrospun nanofiber layers with sub-micron efficiency. METI guidelines on vehicle interior air quality influence filter performance benchmarks for export-oriented production. Manufacturing clusters in Aichi Prefecture support integrated HVAC subsystem supply to regional vehicle assemblers.
Air Filter for Automotive Market Vendor Landscape
German producers anchor premium OEM supply tiers; North American specialists hold dominant positions in heavy-duty commercial applications. The vendor base separates into scaled integrated suppliers with captive media production, technology-focused specialists in nanofiber layering, and regional compounders serving aftermarket price tiers. Three archetypes define competitive positioning: full-system integrators, media technology specialists, and volume aftermarket distributors. Consolidation through strategic partnerships and backward integration into nonwoven compounding represent the dominant competitive vectors.
Within the full-system integrator tier, MANN+HUMMEL and MAHLE GmbH exemplify European-based suppliers with integrated cabin and powertrain filter portfolios. Donaldson Company, Inc. occupies a position among North American specialists with established presence in heavy-duty commercial filtration. These three entities represent distinct geographic anchoring and end-market specialization patterns visible across the competitive structure.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| Donaldson Company, Inc. |
| MAHLE GmbH |
| Robert Bosch GmbH |
| DENSO Corporation |
| Ahlstrom-Munksjö |
| Cummins Inc. |
| K&N Engineering, Inc. |
| Hengst SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
Captive nonwoven media production anchors both supply security and pricing power for scaled automotive air filter manufacturers, compressing cost structures for MANN+HUMMEL and MAHLE while forcing smaller compounders into outsourced supply dependencies that erode margin flexibility.
Pricing Analysis
Short lead-time premiums command measurable price elevation above spot inventory discounts in fleet procurement contracts, with three-tier pricing structure across premium, standard, and economy levels separating HEPA-grade cabin systems from conventional pleated media and foam pre-filtration. Price differentiation rests on certification tier—ECE R34 homologation versus uncertified aftermarket—and volume scale in multi-year OEM platform agreements. Cost compression in synthetic fiber tiers is intensifying because polypropylene feedstock volatility feeds directly into compounder margins. Aftermarket distributors exhibit highest price sensitivity; OEM specification engineers prioritize performance-to-pressure-drop ratios over unit cost.
Supply Chain Analysis
Workforce availability constraints in Michigan and Ohio manufacturing corridors limit pleating facility expansion despite proximity to Detroit Three assembly plants, while Aichi Prefecture and Yangtze River Delta clusters draw from deeper technical labor pools for electrospun nanofiber production. Geographic supply concentration centers on Germany, China, and the United States for integrated filter module assembly. Raw material dependencies encompass meltblown polypropylene, electrospun nanofiber substrates, and activated carbon impregnates. Single-source vulnerability in specialized nanofiber equipment creates bottleneck risk for HEPA-grade capacity expansion. Distribution runs through tier-one supplier direct relationships with OEM platform teams and fleet procurement platforms bypassing traditional jobber networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
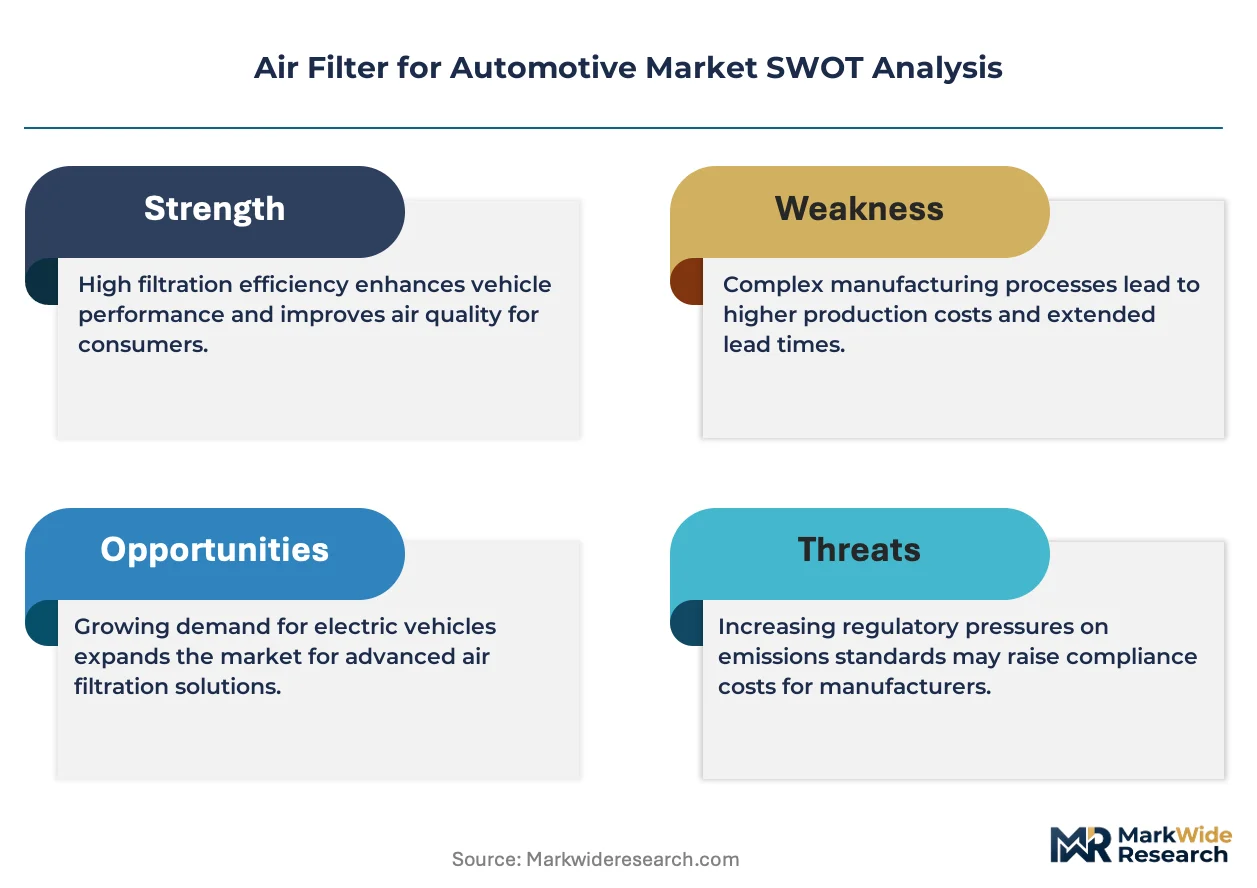
Automotive air filtration has become a vertical-integration race where captive media production and regulatory certification capabilities determine who captures margin in HEPA-grade cabin systems and EPA-compliant heavy-duty applications.
For Market Incumbents: Anticipate zeolite-based adsorbent substitution threatening activated carbon composite contracts by accelerating in-house production of synthetic fiber nonwovens and electrospun nanofiber layers. Defensive consolidation moves require REACH certification investment for adhesive reformulation and capacity addition in Chennai or Pune to intercept India's domestic OEM procurement. Channel control through direct fleet platform relationships protects against distributor disintermediation in Texas and California commercial vehicle markets. For New Entrants and Emerging Players: Direct-to-fleet digital distribution routes offer lowest barrier to revenue in North American commercial vehicle segments where telematics-enabled service scheduling creates procurement entry points. White-space targets concentrate on India's uncontracted two-wheeler foam filtration demand and China's mass-market electric vehicle cabin air upgrades driven by GB standards. The most penetrable segment remains mid-price HEPA-equivalent systems for battery electric platforms lacking engine intake requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-system integrators seeking nanofiber technology capabilities or regional manufacturing footprints. Long-term viability across the projection horizon favors compounders with captive chemical synthesis and cleanroom electrospinning infrastructure over outsourced competitors facing ECHA recertification delays. Acquisition target archetype: mid-cap specialists with ECE R34 certification and established OEM platform relationships. The signal to watch is solid-state battery thermal management architecture shifts altering under-hood airflow geometry and filter placement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nonwoven Media | Captive meltblown production absorbs REACH compliance costs and polypropylene volatility for German suppliers. |
| Electrospun Nanofiber Capacity Expansion | Cleanroom-scale manufacturing enables sub-micron HEPA efficiency for European premium electric vehicle platforms. |
| Direct Fleet Platform Partnerships | Bypassing jobber distributors captures margin in California and Texas commercial vehicle procurement consolidation. |
| India Manufacturing Footprint Establishment | Chennai and Pune compounding operations intercept domestic OEM capacity additions for uncontracted volume. |
| ECE R34 Certification Investment | Accelerated homologation timelines defend model-year synchronized product development against European competitors. |
Methodological Framework
Multi-period observation of vehicle production databases, HEPA technology penetration rates, and fleet procurement platform adoption anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and regulatory affairs specialists at compounders. Secondary validation drew from EPA Tier 3 compliance filings, ECHA SVHC candidate list updates, MIIT GB standard announcements, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulated against top-down market value estimates across the analysis window.
Input-output matrices modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster as primary segmentation dimensions. CAGRs derived from regression analysis of historical penetration curves applied to projected vehicle assembly volumes and technology substitution rates. Industry-specific forecast inputs encompassed electric vehicle cabin air system specification timelines and commercial fleet replacement cycle acceleration under EPA particulate thresholds.
The model holds under stable polypropylene feedstock pricing and sustained electric vehicle platform standardization; deviation in solid-state battery thermal management architectures or REACH substance restriction expansion would shift filter placement geometry and material certification requirements. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Europe Automotive Parts Die Casting Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Global Automotive Auxiliary Brake Market