
 Two-Wheeled Containers Market | 2026-2036
Two-Wheeled Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeled Containers Market Analytics
High-density polyethylene rotational molding is reconfiguring how two-wheeled containers achieve impact resistance and UV stability without metal reinforcement. Toter leverages in-house resin compounding to control material consistency across its domestic manufacturing footprint. SSI Schaefer anchors its position through modular container platforms that integrate with automated lifting mechanisms. Rehrig Pacific Company differentiates via RFID-embedded bin tracking systems that sustain fleet visibility for municipal customers.
Two-wheeled containers denote mobile waste receptacles mounted on paired castor wheels, typically molded from HDPE or metal with capacities spanning 60 to 360 liters, designed for manual tilting and mechanized emptying via standardized DIN lifting interfaces. The plastic material segment dominates unit volume due to corrosion immunity and weight advantages in curbside collection cycles, though metal variants retain share in industrial fire-risk environments where thermal resistance matters. Recycling bins represent the fastest-growing type category as extended producer responsibility laws expand source-separation mandates across jurisdictions, while garbage bins remain the mature revenue base tied to replacement cycles of existing municipal fleets.
EPA waste characterization protocols and OSHA ergonomic guidelines shape container design specifications in the United States, while the EU Packaging and Packaging Waste Directive harmonizes collection infrastructure standards across member states. France's national environmental agency enforces ecodesign criteria that influence wheel assembly durability testing and recyclability thresholds. Stakeholders must monitor evolving extended producer responsibility fee structures and lifting interface standardization debates to align product roadmaps with procurement specifications.
Market Dynamics
Standardized DIN lifting interfaces are consolidating procurement specifications across municipal waste fleets, forcing manufacturers to redesign wheel assemblies and rim geometries for automated compatibility rather than manual handling optimization.
Growth Catalysts
- EPR mandate expansion:France's ecodesign criteria under ANSM enforcement now require 240-liter organic waste separation bins in Paris and Lyon, creating fleet replacement pull.
- Ergonomic injury reduction:OSHA guidelines in the United States are accelerating single-wheel bin phaseouts in favor of two-wheeled configurations with tilt-assist geometry.
- HDPE rotational molding:In-house resin compounding capabilities are letting domestic manufacturers control impact resistance and UV stability specifications without metal reinforcement.
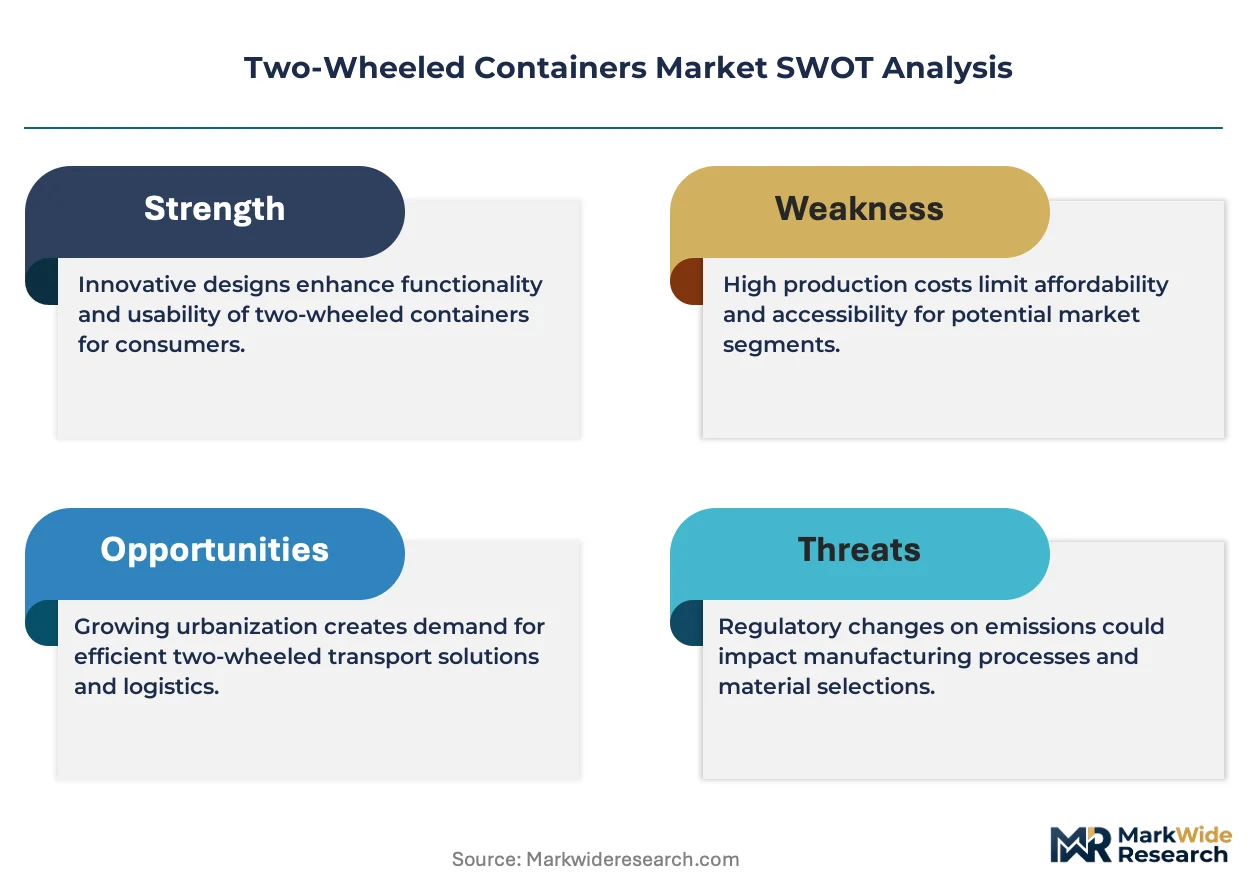
Market Restraints
- Petroleum-based resin volatility:HDPE feedstock costs fluctuate with crude oil indices, compressing margin visibility for rotational molders locked into municipal tender cycles.
- Wheel assembly supply concentration:Precision castor manufacturing clusters in Germany create single-source risk for DIN-compatible axle systems.
- Metal substitution in fire-risk environments:Industrial thermal resistance requirements prevent plastic penetration in chemical and foundry waste streams.
Strategic Opportunities
- RFID fleet tracking integration:Embedded bin identification systems enable municipal customers to optimize collection route density and container utilization rates.
- Modular platform architectures:Automated lifting mechanism compatibility is opening specification wins in German packaging regulator-mandated standardization programs.
- Recycling bin category expansion:Source-separation mandates under EU Packaging and Packaging Waste Directive are accelerating demand for color-coded 120-360 liter configurations.
Industry Challenges
- DIN interface certification timelines:Third-party testing for automated lifting compatibility extends product development cycles by 8-14 months.
- Legacy fleet integration friction:Municipal customers face compatibility gaps when mixing new two-wheeled containers with existing single-wheel tipping mechanisms.
- Resin formulation IP complexity:UV stabilizer and impact modifier licensing agreements create supply chain reconfiguration delays for manufacturers switching compound suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeled Containers Market |
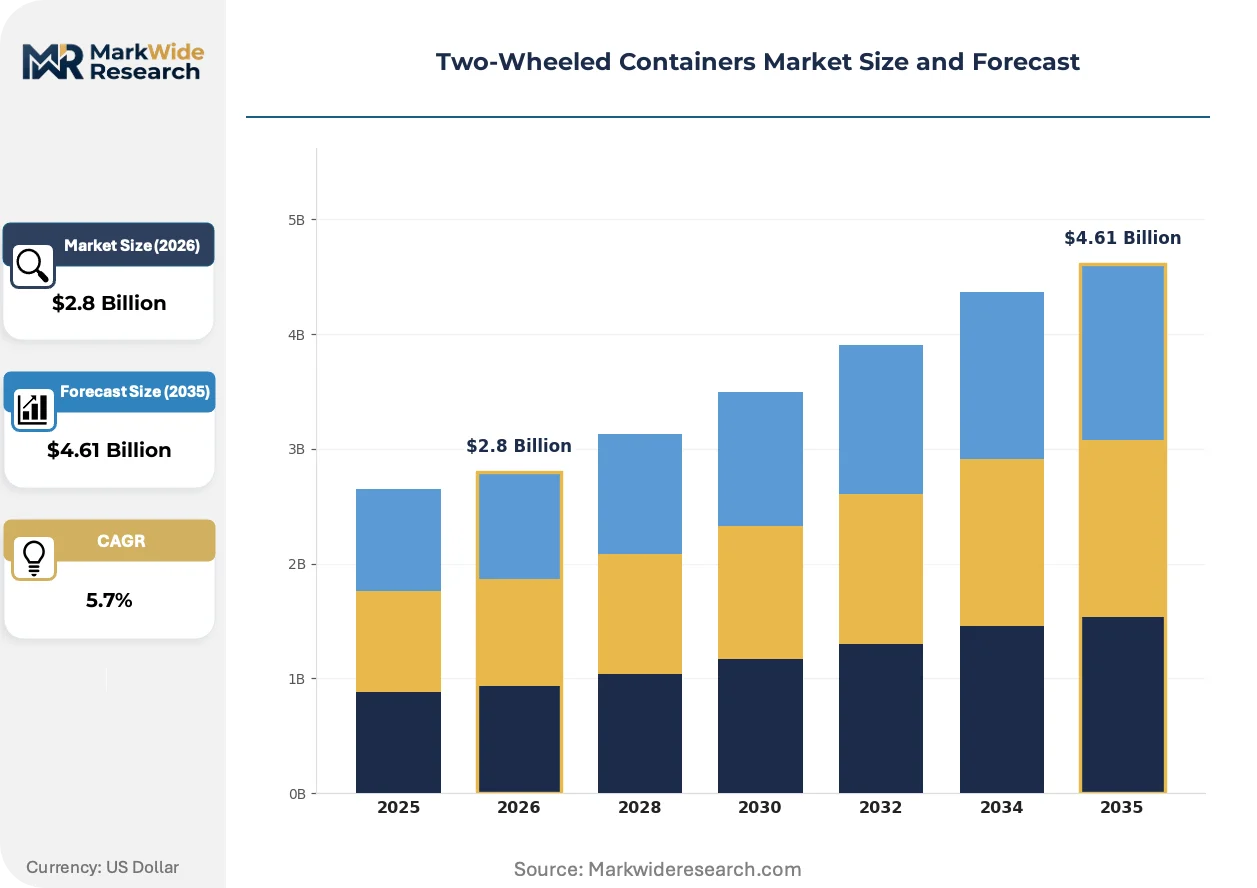
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Utility Carts, Garbage bins, Recycling Bins, Garden Trolleys Material: Plastic, Metal, Composite, Wood End User: Residential Users, Commercial Institutions, Municipalities, Industrial Facilities Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Toter, SSI Schaefer, Rehrig Pacific Company, Rubbermaid Commercial Products, Contenur, SULO International, Craemer Holding, Plastic Omnium, Schäfer Container Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeled Containers Market Evolving Landscape
Digital identification layers and automated material handling compatibility are redefining how two-wheeled containers transition from passive receptacles to integrated fleet assets.
RFID-embedded tracking systems are virtualizing container location and fill-level monitoring for municipal operators. German cities piloting smart waste logistics are mandating chip-readable bin identification to synchronize collection vehicle routing with real-time capacity data. This virtualization is compressing the traditional tender-based procurement cycle toward performance-contracting models where utilization metrics determine fleet renewal timing.
REACH compliance deadlines for persistent organic pollutants in plastic additives are forcing reformulation of HDPE stabilizer packages. The EU Packaging and Packaging Waste Directive's harmonization requirements are pushing manufacturers toward pre-certified resin compounds that satisfy multiple member state recyclability thresholds. Recycling bin categories face the steepest compliance burden due to colorant and additive restrictions in food-contact and organic waste streams.
Municipal procurement offices are consolidating vendor relationships around full-service fleet management contracts. Traditional equipment-only tenders in France and Germany are yielding to multi-year service agreements where container supply, maintenance, and RFID infrastructure are bundled. This consolidation is most visible in Paris and Lyon, where uniform 240-liter organic waste mandates have compressed supplier shortlists to three integrated platform providers.
Two-Wheeled Containers Market Segmentation
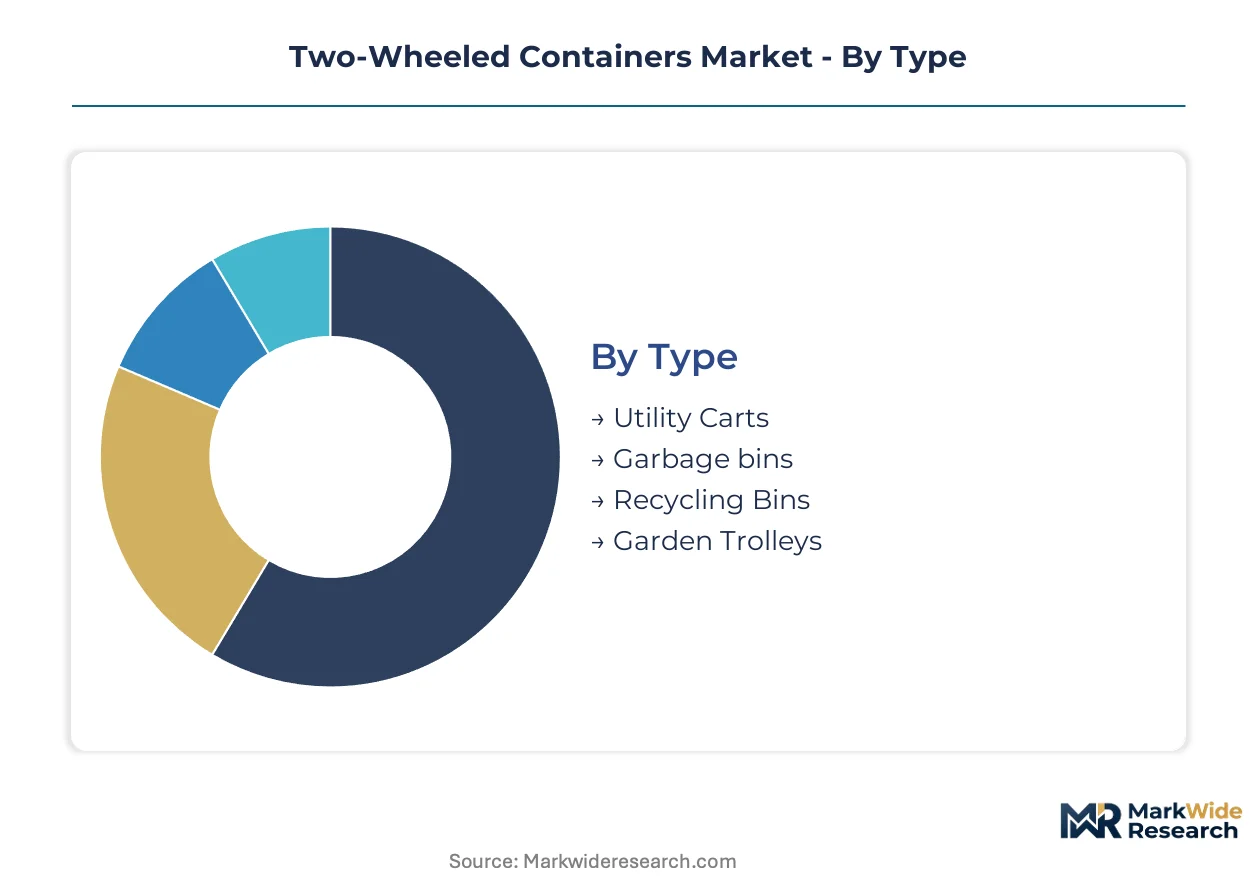
Two-wheeled container procurement cycles vary dramatically by segment, with municipal fleet replacements stretching 8-12 years while retail garden trolley turnover compresses to 2-3 seasons. Understanding these differential replacement velocities shapes inventory planning and margin capture strategies for manufacturers serving mixed demand pools.
Type:
Garbage bins turn over slowest due to municipal tender cycles, while garden trolleys refresh fastest through seasonal retail channels.
- Garbage bins:HDPE rotational-molded receptacles with DIN-standard lifting interfaces dominate curbside collection fleets. Demand concentrates in French municipalities where ANSM-mandated 240-liter organic waste separation drives standardized procurement.
- Recycling bins:Color-coded HDPE containers with UV-stabilized resins enable source-separation compliance. Expansion concentrates in German cities under packaging regulator standardization programs where automated lifting compatibility determines vendor selection.
- Utility Carts:Multi-purpose wheeled platforms serve facility maintenance and logistics applications with shorter replacement cycles than municipal waste infrastructure.
- Garden Trolleys:Consumer-grade units with pneumatic or solid castor configurations move through home improvement retail channels with seasonal demand spikes.
Garbage bins dominate installed base. Recycling bins are where expansion concentrates.
Material:
Cost tiers separate premium composite formulations from commodity HDPE and fire-resistant metal variants.
- Plastic:High-density polyethylene rotational molding delivers corrosion immunity and weight advantages for curbside collection cycles. REACH compliance deadlines for persistent organic pollutants in additives are forcing reformulation of stabilizer packages across European supply chains.
- Metal:Steel and aluminum variants retain specification wins in industrial fire-risk environments where thermal resistance prevents plastic penetration. Foundry and chemical waste streams mandate these configurations despite weight penalties.
- Composite:Fiber-reinforced polymer blends occupy niche premium positioning for specialized durability requirements.
- Wood:Traditional material persists in aesthetic-focused garden and heritage applications with minimal industrial penetration.
Plastic commands unit volume leadership. Metal defends premium positioning in regulated thermal environments.
End User:
Customer concentration runs from fragmented residential demand through consolidated municipal procurement.
- Municipalities:Fleet-scale purchasers with multi-year tender cycles and DIN interface standardization requirements. Paris and Lyon uniform 240-liter mandates exemplify specification consolidation.
- Residential Users:Individual households purchasing replacement units through retail channels with minimal standardization pressure.
- Commercial Institutions:Universities, hospitals, and office complexes with intermediate volume needs and customization requirements.
- Industrial Facilities:Fire-risk environments with thermal resistance specifications that exclude plastic variants from waste stream handling.
Municipalities anchor revenue stability. Commercial institutions are climbing the fastest as EPR mandates expand source-separation obligations.
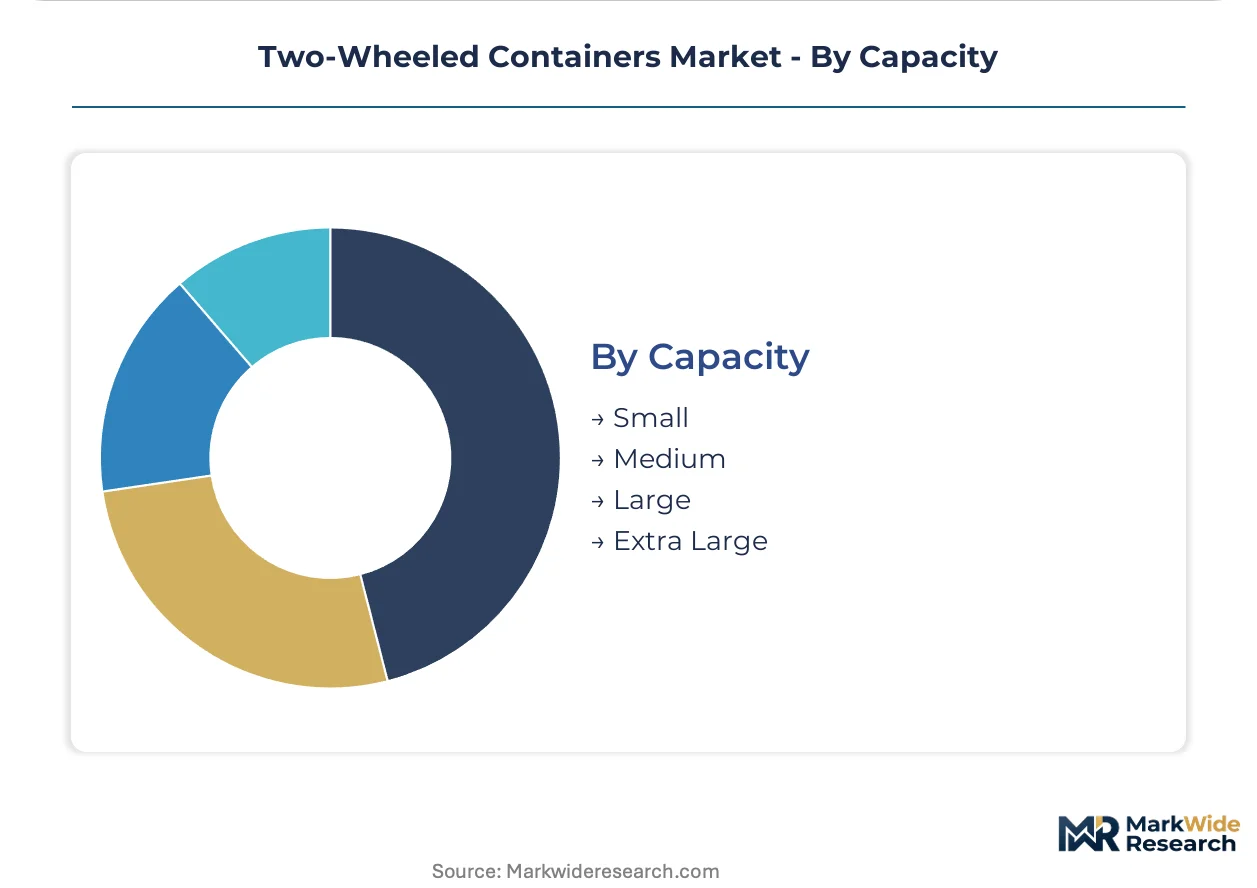
Capacity:
Volume tiers map to handling ergonomics and mechanized emptying compatibility.
- Large:240-360 liter configurations align with ANSM-mandated organic waste separation in French cities and German packaging regulator standardization. OSHA ergonomic guidelines in the United States favor these geometries for tilt-assist handling.
- Medium:120-180 liter units serve multi-unit residential and small commercial applications with manual handling predominance.
- Small:Sub-120 liter formats target space-constrained urban environments and specialized waste streams.
- Extra Large:360+ liter industrial configurations for high-volume commercial and manufacturing waste generation points.
Large capacity holds procurement specification power. Medium capacity is gaining share fastest as multi-unit residential EPR obligations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement offices concentrate demand in Western European markets where standardization mandates drive fleet replacement cycles. France and Germany anchor specification-setting authority through national packaging regulators. The United States follows with OSHA-driven ergonomic upgrades.
Germany
Standardized DIN lifting interfaces dominate municipal tender specifications across North Rhine-Westphalia and Bavaria. The national packaging regulator enforces strict recycling quotas that mandate container interface uniformity. Precision castor manufacturing clusters around Stuttgart supply axle systems for automated lifting compatibility.
France
ANSM-mandated 240-liter organic waste separation drives fleet replacement in Paris and Lyon metropolitan areas. Ecodesign criteria enforce wheel assembly durability testing and recyclability thresholds. The Île-de-France region compresses supplier shortlists to integrated platform providers under uniform procurement.
United States
OSHA ergonomic guidelines accelerate single-wheel bin phaseouts favoring tilt-assist geometries. EPA waste characterization protocols shape container design specifications for municipal fleets. Southeast municipal districts concentrate demand for HDPE rotational-molded receptacles with corrosion immunity.
United Kingdom
Extended producer responsibility frameworks expand source-separation mandates across English metropolitan councils. The Environment Agency harmonizes collection infrastructure standards with EU Packaging and Packaging Waste Directive alignment. Greater Manchester and Birmingham pilot RFID-embedded fleet tracking for route optimization.
Italy
Regional waste management consortia in Lombardy and Emilia-Romagna consolidate procurement around modular container platforms. REACH compliance deadlines for persistent organic pollutants force HDPE stabilizer reformulation. Northern industrial districts retain metal variant specifications for foundry waste streams.
Two-Wheeled Containers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented municipal procurement channels. The vendor base organizes around three strategic archetypes: integrated platform providers with RFID infrastructure bundling, rotational molding specialists with in-house resin compounding, and precision wheel assembly manufacturers with DIN certification authority. Competitive moves concentrate on multi-year service agreement consolidation and automated lifting mechanism compatibility certification.
Among North American waste container fabricators, Toter exemplifies the resin-compounding archetype with domestic manufacturing control. SSI Schaefer anchors the modular platform tier through German engineering heritage. Rehrig Pacific Company occupies the digital integration position with embedded identification system capabilities.
| Leading Market Players |
|---|
| Toter |
| SSI Schaefer |
| Rehrig Pacific Company |
| Rubbermaid Commercial Products |
| Contenur |
| SULO International |
| Craemer Holding |
| Plastic Omnium |
| Schäfer Container Systems |
| Others |
Value Network & Pricing Analysis
Petroleum-based resin volatility determines both pricing tier spreads and supply chain shape in two-wheeled container manufacturing, compressing margin visibility for rotational molders locked into municipal tender cycles while forcing geographic consolidation around feedstock-advantaged production clusters.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate municipal procurement, locking manufacturers into margin structures that fluctuate with HDPE feedstock costs. Price differentiation hinges on DIN interface certification tier and after-sales service bundling, with integrated platform providers capturing premium positioning over commodity molders. Pricing pressure stems from extended tender cycles that delay cost pass-through to fleet operators. Municipal buyers exhibit highest price sensitivity, while industrial fire-risk purchasers accept metal variant premiums for thermal compliance.
Supply Chain Analysis
Export-control scrutiny on precision castor manufacturing equipment limits technology transfer to emerging production bases, concentrating DIN-compatible axle supply around Stuttgart-area specialists. Raw material flows draw from German petrochemical complexes, Benelux resin compounders, and Chinese UV stabilizer producers. Single-source vulnerability concentrates in wheel assembly supply, where automated lifting compatibility certification creates captive supplier relationships. Distribution runs through municipal procurement offices with multi-year tender cycles, compressing channel alternatives for mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Two-wheeled containers represent an early-cycle expansion story as extended producer responsibility mandates accelerate source-separation infrastructure deployment across European municipalities.
For Market Incumbents: Build certification moats around DIN interface testing authority to defend against modular platform competitors. Deepen backward integration into in-house resin compounding to offset petroleum feedstock volatility, while securing multi-year service agreements in Paris and Lyon to lock out challenger bids. Monitor REACH compliance deadlines as a regulatory chokepoint that favors pre-certified stabilizer formulations.
For New Entrants and Emerging Players: Pursue white-space opportunities in medium-capacity recycling bins for multi-unit residential complexes, where EPR obligations proliferate faster than incumbent capacity expansion. Target commercial institutions with customization-flexible utility cart configurations, leveraging shorter procurement cycles than municipal tenders. Lead with RFID-embedded fleet tracking as a differentiated service bundle rather than equipment-only positioning.
For Investors and Strategic Acquirers: The market sits at a standardization phase that favors integrated platform providers with automated lifting compatibility certification. Long-term viability across the projection horizon rests on capturing municipal fleet management contracts that bundle container supply, maintenance, and digital infrastructure. Watch for DIN interface harmonization debates as the signal indicating consolidation timing for precision wheel assembly specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | In-house HDPE formulation control insulates margins from crude oil index volatility. |
| DIN Interface Certification Investment | Automated lifting compatibility opens specification wins in German regulator-mandated programs. |
| RFID Fleet Tracking Platform Launch | Embedded bin identification enables performance-contracting models with municipal operators. |
| Multi-Year Service Agreement Expansion | Paris and Lyon uniform procurement compresses supplier shortlists to integrated providers. |
| REACH-Compliant Stabilizer Reformulation | Pre-certified additive packages satisfy multiple member state recyclability thresholds. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement officers, rotational molding plant managers, and waste logistics fleet supervisors; and secondary validation through EU Packaging and Packaging Waste Directive filings, ANSM ecodesign criteria documentation, and OSHA ergonomic guideline records. Bottom-up triangulation across container shipment volumes and top-down reconciliation against municipal fleet replacement budgets anchored value estimates.
Forecast inputs span material type segmentation, capacity tier adoption curves, and end-user procurement cycle patterns across the analysis window. Modeled dimensions include container type, material formulation, end-user concentration, and geographic regulatory cluster. CAGRs were derived from segment-level volume trajectories weighted by replacement velocity differentials, with HDPE resin price assumptions and DIN standardization timelines as industry-specific calibration factors.
Sensitivities concentrate around petroleum feedstock volatility, REACH additive compliance deadlines, and municipal tender timing slippage. Forecasts reflect documented assumptions on EPR mandate expansion rates and automated lifting mechanism penetration. Material shifts in German packaging regulator standardization programs or ANSM organic waste separation enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
HCV Axles Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Idler Arm Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Railroad Equipment Manufacturing Market