
 Energy Supplements Market | 2026-2036
Energy Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Supplements Market Intelligence
Multi-source ingredient procurement is shifting toward vertically integrated supply chains as raw material volatility pressures margins. Glanbia PLC leverages its dairy-derived protein infrastructure to control whey isolate quality from farm to finished powder. NOW Foods sustains competitive positioning through domestic manufacturing scale and third-party certification density across its portfolio. Herbalife International of America anchors its model on direct-selling channel control, bypassing traditional retail markup structures entirely.
Energy supplements comprise formulated ingestible products containing caffeine, amino acids, vitamins, and botanical extracts designed to enhance physical performance, mental alertness, or metabolic output, typically standardized to deliver measurable active compound doses per serving unit. Protein powders occupy the mature revenue base with established manufacturing infrastructure and commodity-like pricing dynamics, while energy drinks command premium shelf positioning in convenience and grocery channels. The tablet and capsule form segment attracts formulation specialists seeking precise dosing control and extended-release delivery mechanisms for sustained cognitive enhancement applications.
The FDA exercises primary oversight through Current Good Manufacturing Practice regulations for dietary supplements, while the FTC monitors advertising claims related to energy and performance benefits. The USDA Organic certification and NSF Certified for Sport standards increasingly function as market access gatekeepers for premium positioning. Stakeholders must monitor evolving state-level caffeine disclosure mandates and adapt labeling strategies accordingly.
Market Dynamics
The FDA's DSHEA modernization initiative is forcing manufacturers toward transparent formulation disclosure, compressing margins for legacy opaque blends while rewarding vertically integrated suppliers with captive ingredient sourcing.
Growth Catalysts
- Fitness culture mainstreaming:Workout culture now permeates demographics beyond traditional athletes, expanding addressable demand for pre-workout and intra-workout formulations.
- NSF Certified for Sport standards:Third-party athletic certification is gating premium shelf access in collegiate and professional sports nutrition channels.
- Whey protein infrastructure maturity:Dairy-derived processing scale in North America and Europe enables cost-efficient amino acid precursor supply for energy formulations.
Market Restraints
- Caffeine raw material volatility:Synthetic caffeine supply concentrates in Chinese pharmaceutical intermediates, exposing formulators to input cost swings and tariff exposure.
- DSHEA labeling friction:Evolving FDA disclosure mandates require reformulation cycles that delay product launches by 8-14 months.
- Botanical extract standardization limits:Natural caffeine and adaptogen potency variance forces over-formulation to guarantee label claims, eroding gross margins.
Strategic Opportunities
- Direct-to-consumer channel expansion:Subscription models bypass retail slotting fees and capture recurring revenue with higher lifetime value metrics.
- EU novel food authorization pathway:EFSA clearance for emerging botanical actives creates first-mover positioning in European functional food crossover applications.
- Cognitive enhancement convergence:Nootropic ingredient stacks combined with physical energy actives target knowledge workers and esports competitors.
Industry Challenges
- Formulation science talent scarcity:Cross-functional expertise spanning sports nutrition, pharmaceutical delivery systems, and flavor masking commands premium compensation.
- Certification timeline compression:NSF Informed Sport and BSCG Certified Drug Free testing queues extend go-to-market schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Supplements Market |
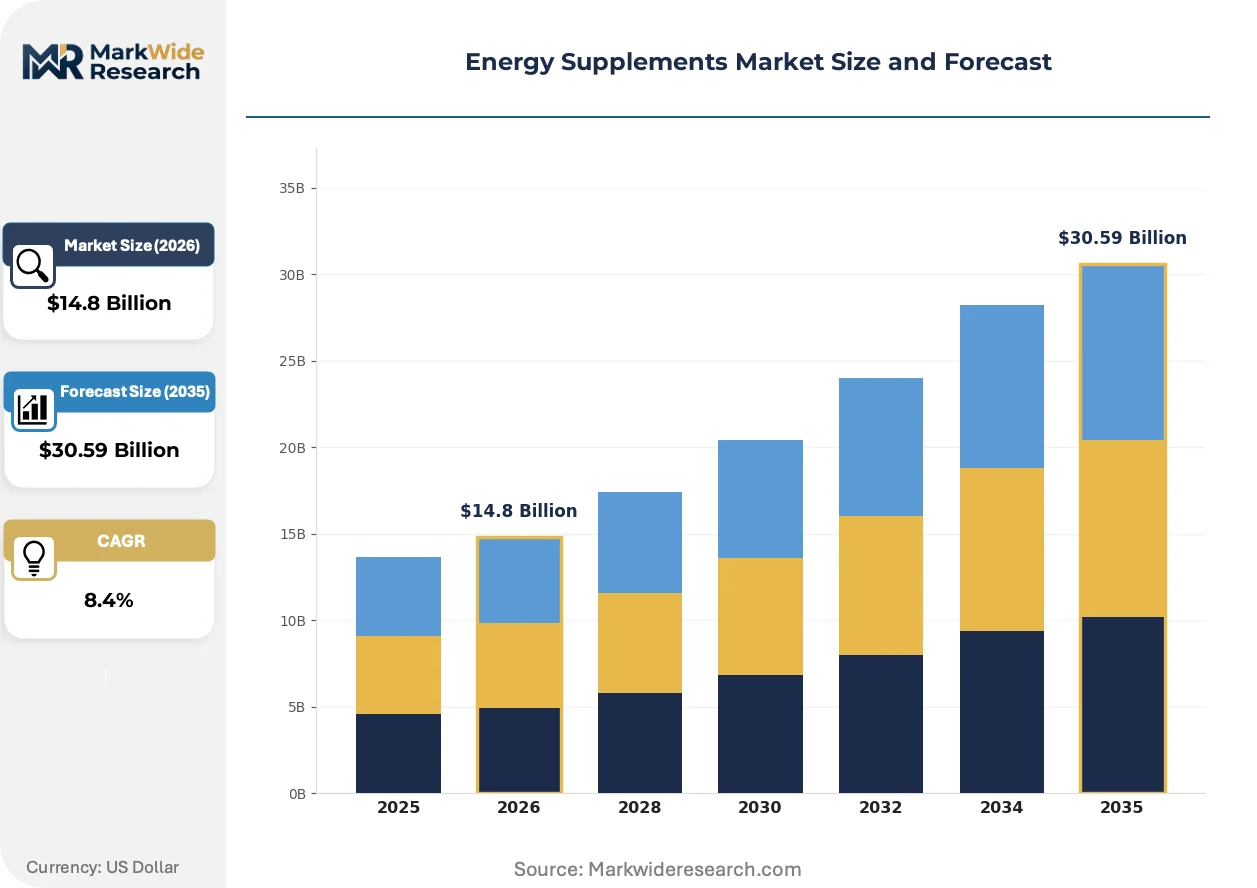
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Energy Drinks, Supplements Form: Liquid, Powder, Tablet, Capsule Target Audience: Athletes, Fitness Enthusiasts, Office Workers, Students Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Clubs |
| Companies Covered | Amway Corp., The Coca-Cola Company, Glanbia PLC, Thorne, GNC Holdings, Nestle Health Science, PepsiCo, NOW Foods, Herbalife International of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Supplements Market Strategic Shifts & Innovations
Clean-label formulation pressure is restructuring competitive advantage around supply chain transparency rather than proprietary blend opacity, rewarding manufacturers with backward-integrated raw material control.
Time-released caffeine microencapsulation is overtaking immediate-release formats in premium positioning. Fitness enthusiasts and shift workers adopt sustained-energy formulations that flatten pharmacokinetic curves. The technology is compressing demand for conventional energy drink formats in convenience channels.
EU REACH chemical registration requirements are tightening botanical extract import documentation. Manufacturers must demonstrate supply chain traceability for adaptogenic ingredients sourced from third-country suppliers. Premium positioning now requires EFSA-compliant novel food dossiers for emerging actives.
Subscription-based replenishment is displacing retail repurchase cycles among core user segments. Direct brands capture consumption data that enables personalized formulation adjustments. The United States exhibits highest penetration of auto-ship models, with urban coastal metros leading adoption velocity.
Energy Supplements Market Segmentation
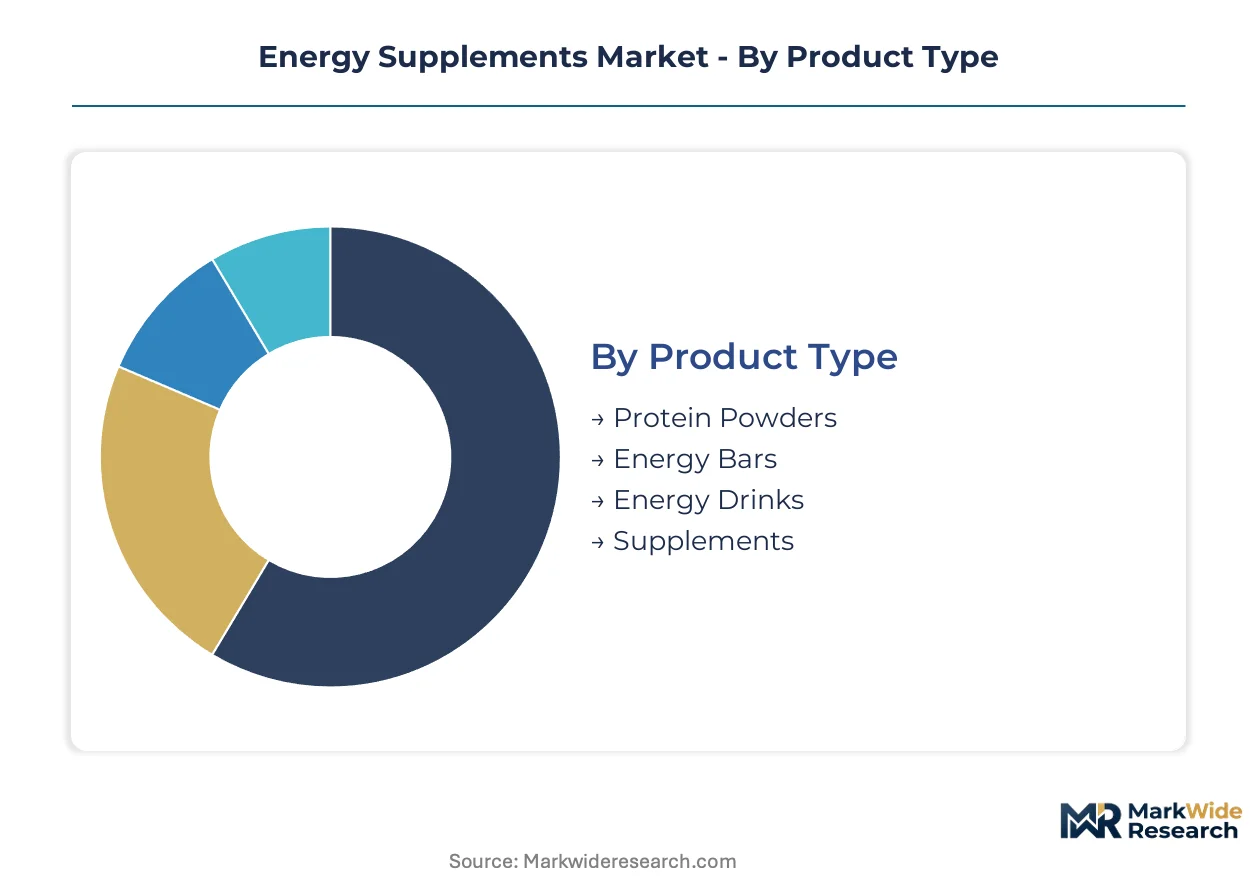
Energy supplements fragment across four distinct category axes, each revealing divergent margin structures and channel control points. Product type and form factor determine manufacturing complexity, while audience targeting and distribution access govern pricing power.
Product Type:
Customization intensity varies from commodity protein processing to proprietary stimulant matrices, with formulation opacity directly correlating to margin capture.
- Protein Powders:Whey and plant-derived isolates dominate volume through established dairy processing infrastructure. Demand concentrates in United States metropolitan fitness clusters where subscription replenishment models have displaced retail repurchase cycles.
- Energy Drinks:Ready-to-drink caffeinated formulations command premium shelf positioning in convenience channels. Caffeine raw material volatility from Chinese pharmaceutical intermediates exposes formulators to input cost swings and tariff exposure.
- Energy Bars:Macro-balanced snack formats bridge meal replacement and performance nutrition applications. Shelf-stable binding technologies differentiate texture profiles.
- Supplements:Tablet and capsule concentrates enable precise dosing of botanical actives and nootropic stacks. Standardization variance forces over-formulation to guarantee label claims.
Leading the category by volume: Protein Powders. Growing fastest: Energy Drinks.
Form:
Delivery mechanism selection trades off bioavailability speed against portability and dosing precision, with liquid formats sacrificing margin for impulse purchase accessibility.
- Liquid:Pre-mixed solutions eliminate preparation friction for immediate consumption scenarios. Convenience channel placement drives trial but compresses gross margins through packaging and logistics costs.
- Powder:Bulk concentrates offer cost-per-serving efficiency and flavor customization flexibility. United States warehouse club penetration sustains volume leadership.
- Tablet:Compressed actives enable precise unit dosing and extended shelf stability. Manufacturing scale requirements favor incumbent pharmaceutical contract manufacturers.
- Capsule:Gelatin and vegetable-shell enclosures mask bitter botanical compounds. Time-release microencapsulation technology is overtaking immediate-release formats in premium positioning.
Volume leadership rests with Powder formats. Steepest expansion trajectory: Capsule with sustained-release delivery systems.
Target Audience:
Audience segmentation maps directly to usage occasion intensity and price elasticity, with professional performance demands justifying premium formulation investment.
- Fitness Enthusiasts:Recreational exercisers seeking physique optimization and recovery acceleration. This segment is expanding most quickly as workout culture permeates mainstream demographics beyond traditional athletes.
- Athletes:Competitive performers requiring NSF Certified for Sport or BSCG Certified Drug Free verification. Collegiate and professional procurement channels gate access through third-party certification density.
- Office Workers:Cognitive enhancement seekers targeting sustained alertness without jitters. Shift workers adopt sustained-energy formulations that flatten pharmacokinetic curves.
- Students:Academic performance pressure drives demand for nootropic-caffeine combinations. Price sensitivity favors private-label and bulk powder procurement.
Dominant volume: Fitness Enthusiasts. Climbing the fastest: Office Workers seeking cognitive-physical hybrid formulations.
Distribution Channel:
Channel selection determines customer data capture depth and margin retention, with direct models bypassing retail slotting fees entirely.
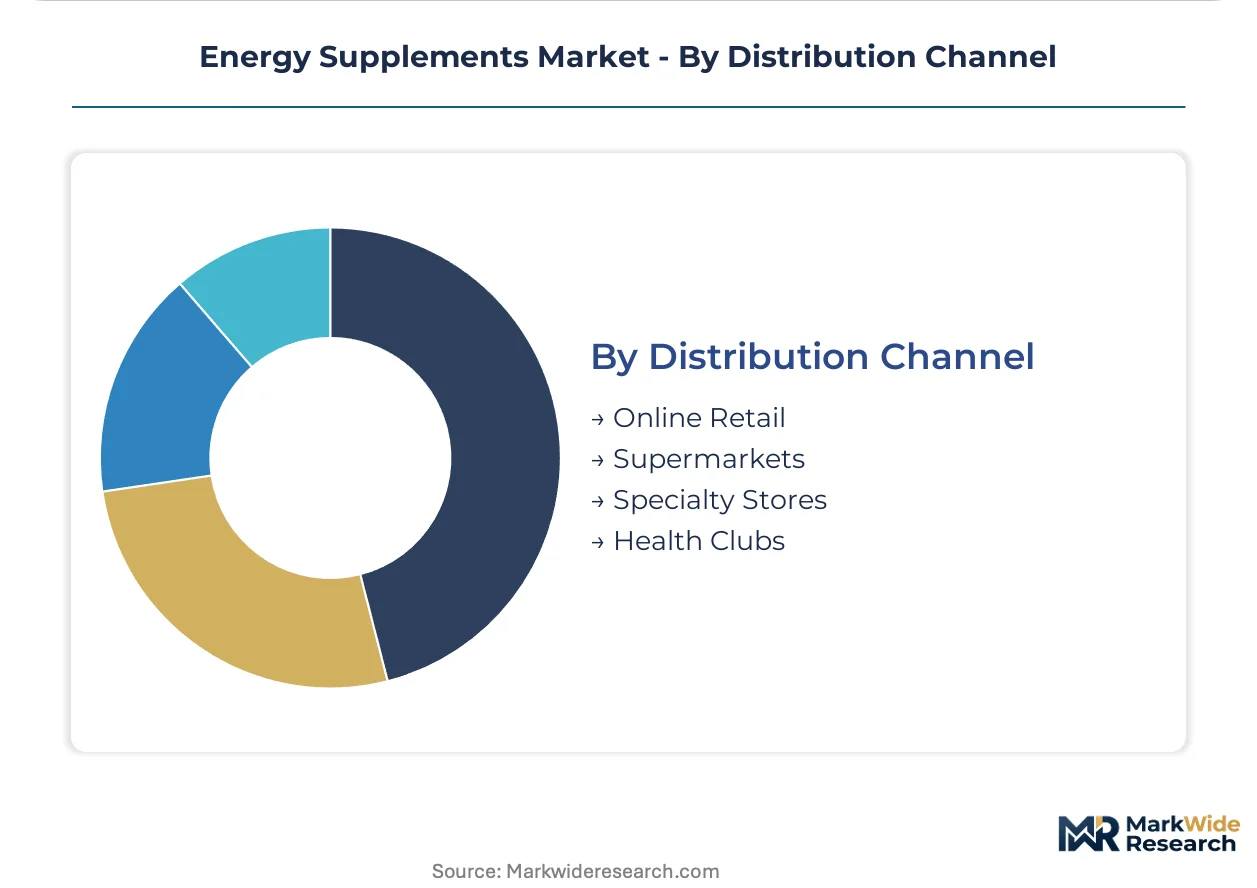
- Online Retail:Direct-to-consumer platforms enable subscription auto-ship and personalized formulation adjustments. United States urban coastal metros lead adoption velocity for replenishment automation.
- Supermarkets:Mass-market placement requires trade promotion investment and standardized packaging formats. Clean-label transparency pressures are restructuring competitive advantage around supply chain visibility.
- Specialty Stores:Curated assortments and educated staff consultation support premium positioning. NSF and USDA Organic certifications function as market access gatekeepers.
- Health Clubs:Point-of-consumption placement captures immediate post-workout replenishment demand. On-site vending and pro-shop integration limits brand comparison shopping.
Highest volume penetration: Online Retail. Gaining share fastest: Health Clubs with embedded consumption moments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
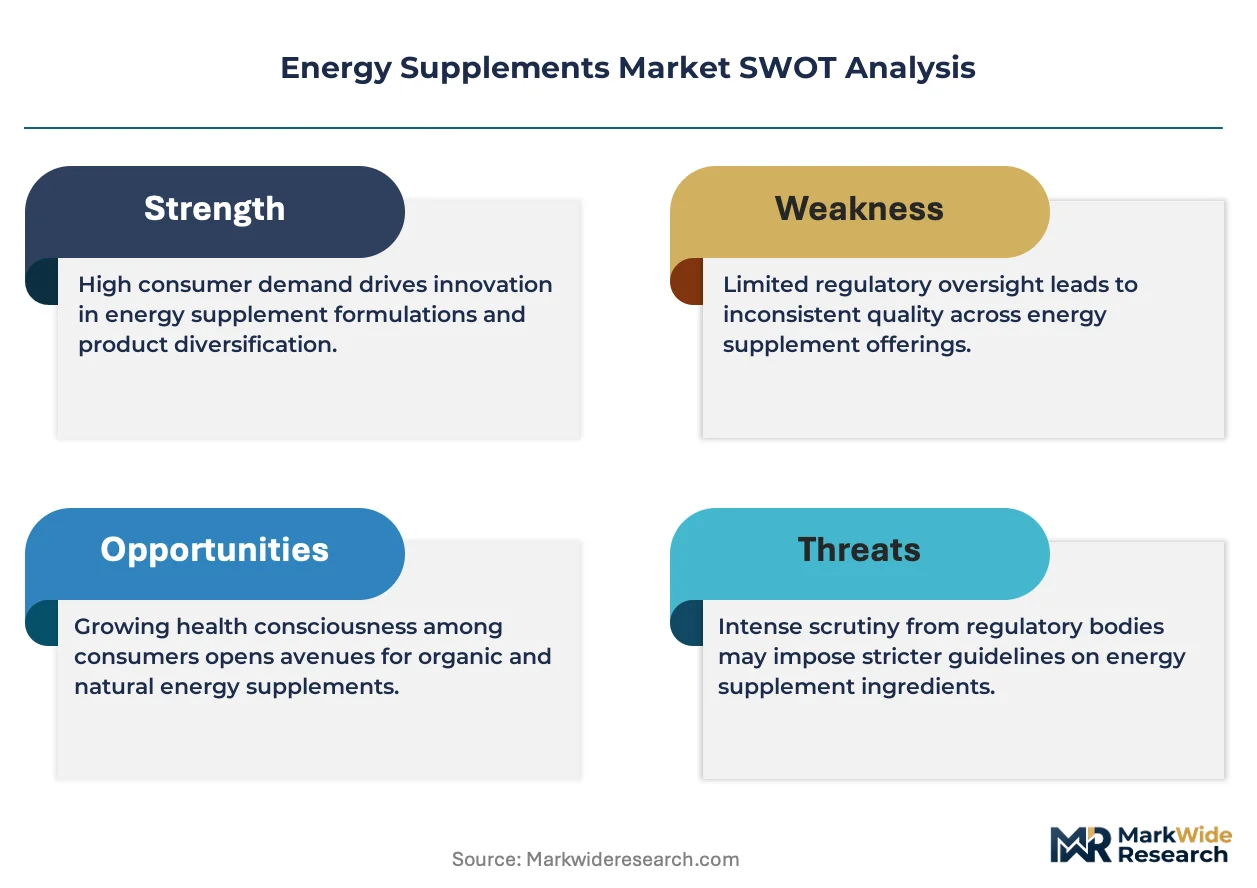
Demand concentrates in the United States where gym membership penetration and direct-to-consumer brand loyalty remain highest among developed economies. Subscription auto-ship models have displaced retail repurchase cycles in urban coastal metros. Fitness culture mainstreaming expands addressable demand across recreational exercisers beyond traditional athletes.
United States
Metropolitan fitness clusters in Los Angeles, Miami, and New York sustain the highest subscription replenishment adoption. FDA DSHEA modernization pressures manufacturers toward transparent formulation disclosure. The Pacific Northwest hosts emerging clean-label specialists targeting NSF Certified for Sport verification density.
Germany
Precision dosing preferences among fitness enthusiasts drive capsule and tablet format demand. EFSA novel food authorization pathways create first-mover positioning for emerging botanical actives. Bavaria's dairy processing infrastructure enables cost-efficient whey isolate supply for energy formulations.
United Kingdom
Shift workers in London and Birmingham adopt sustained-energy formulations that flatten pharmacokinetic curves. Trading Standards and MHRA jointly monitor caffeine disclosure compliance across supplement retail channels. The Southeast corridor concentrates direct-to-consumer brand headquarters and fulfillment automation.
China
Synthetic caffeine supply concentrates in pharmaceutical intermediate production zones, exposing formulators to input cost swings. SAMR dietary supplement regulations require reformulation cycles that delay product launches. Yangtze River Delta manufacturing clusters integrate time-release microencapsulation technology for premium positioning.
Australia
Collegiate and professional sports procurement channels gate access through TGA-listed medicine verification. TGA therapeutic goods administration enforces strict label claim substantiation for stimulant-containing products. Sydney and Melbourne health club chains embed point-of-consumption placement for immediate post-workout replenishment.
Energy Supplements Market Key Industry Players
Portfolio diversification dominates the current landscape as legacy beverage conglomerates and nutrition specialists converge on functional energy positioning. The vendor base stratifies across three tiers: multinational CPG conglomerates with beverage infrastructure, dedicated sports nutrition houses with certification density, and direct-selling platforms bypassing traditional retail markup structures entirely. Strategic archetypes include backward-integrated dairy processors controlling whey isolate quality from farm to finished powder, formulation specialists leveraging extended-release delivery mechanisms, and subscription-native brands capturing consumption data for personalized adjustments. Dominant competitive moves include M&A activity targeting certification-acquired sports nutrition assets and geographic expansion through EU novel food authorization pathways.
Among multinational beverage and nutrition conglomerates, The Coca-Cola Company, PepsiCo, and Nestle Health Science exemplify the CPG infrastructure archetype with established convenience channel placement and trade promotion investment capacity. Within the dedicated sports nutrition tier, Glanbia PLC and NOW Foods occupy positions reflecting contrasting supply chain philosophies: Glanbia leverages captive dairy-derived protein infrastructure while NOW Foods sustains competitive positioning through domestic manufacturing scale and third-party certification density. Herbalife International of America anchors the direct-selling channel control archetype, bypassing retail slotting fees entirely through personal distribution networks. GNC Holdings represents the specialty retail consolidation play with curated assortments and educated staff consultation supporting premium positioning.
| Leading Market Players |
|---|
| Amway Corp. |
| The Coca-Cola Company |
| Glanbia PLC |
| Thorne |
| GNC Holdings |
| Nestle Health Science |
| PepsiCo |
| NOW Foods |
| Herbalife International of America |
| Others |
Cost & Logistics Intelligence
Fitness enthusiasts demanding NSF Certified for Sport verification are compressing margins for uncertified suppliers while rewarding manufacturers with captive certification infrastructure and transparent sourcing documentation. This procurement preference shift forces supply chain reconfiguration toward third-party testing partnerships and backward-integrated ingredient control, elevating pricing power for qualified players.
Pricing Analysis
Volume leadership in protein powders trades at commodity-thin margins against premium capsule formats with sustained-release microencapsulation commanding three-to-fourfold unit economics. Three-tier pricing structure across premium, standard, and economy levels separates NSF-verified formulations from conventional blends and private-label substitutes. Pricing pressure stems from synthetic caffeine raw material volatility concentrated in Chinese pharmaceutical intermediates. Students exhibit highest price sensitivity favoring bulk powder procurement, while athletes demonstrate lowest elasticity accepting certification premiums.
Supply Chain Analysis
NSF Certified for Sport and BSCG Certified Drug Free verification function as supply chain gatekeepers, limiting qualified manufacturing partners and extending certification queues. Synthetic caffeine production concentrates in China, whey isolate processing anchors in the United States and Germany, and time-release microencapsulation technology clusters in the Yangtze River Delta. Formulators draw from dairy-derived protein infrastructure, botanical extract supply from third-country adaptogen sources, and pharmaceutical-grade stimulant inputs. Tariff exposure on Chinese caffeine intermediates creates structural vulnerability. Distribution runs through direct-to-consumer subscription platforms bypassing retail slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic caffeine supply concentration in Chinese pharmaceutical intermediates constrains input availability, propping pricing power for manufacturers with diversified sourcing or captive supply arrangements.
For Market Incumbents: Cement certification density advantages by accelerating NSF Informed Sport and BSCG Certified Drug Free portfolio coverage before testing queue bottlenecks intensify. Deepen backward integration into dairy-derived protein infrastructure to isolate margins from whey isolate commodity swings. Prioritize direct-to-consumer channel control to bypass retail markup compression from supermarket trade promotion demands. For New Entrants and Emerging Players: Begin with cognitive-physical hybrid formulations targeting office workers and esports competitors, the fastest-climbing audience segment with underdeveloped incumbent presence. Exploit EU novel food authorization pathways for emerging botanical actives to secure first-mover positioning ahead of EFSA clearance backlogs. Launch through subscription-native auto-ship models capturing consumption data for personalized formulation adjustments. For Investors and Strategic Acquirers: The window for entry favors direct-to-consumer brands with proprietary consumption data infrastructure and certification-acquired manufacturing assets. Viability extends across a multi-year horizon contingent on sustained fitness culture mainstreaming and regulatory disclosure tightening. Watch for DSHEA modernization implementation timelines as inflection trigger for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | NSF and BSCG verification density gates collegiate and professional sports procurement channels. |
| Backward Integration into Dairy Processing | Glanbia-style captive whey isolate supply controls quality from farm to finished powder. |
| Direct-to-Consumer Channel Launch | Subscription auto-ship bypasses retail slotting fees and captures higher lifetime value metrics. |
| EU Novel Food Authorization Pursuit | EFSA clearance for botanical actives creates first-mover positioning in European functional food crossover. |
| Time-Release Delivery Technology Investment | Microencapsulation expertise differentiates sustained-energy formulations from immediate-release commodity formats. |
Research Approach
Trade databases, FDA DSHEA guidance documents, and EFSA novel food registers formed the secondary backbone, cross-referenced against primary interviews with sports nutrition formulators, third-party certification laboratory directors, and direct-to-consumer brand supply chain managers. Bottom-up demand modeling triangulated against top-down macro consumption trend analysis validated segment-level projections.
Historical trendline analysis across protein powder, energy drink, and supplement format trajectories informed baseline assumptions, with CAGRs derived from segment momentum differentials across the projection horizon. Modeled dimensions encompass product type, delivery form, target audience intensity, and distribution channel control. Forecast inputs incorporated fitness culture penetration rates, certification queue duration estimates, and raw material cost pass-through elasticity.
Underlying measurement precision varies by segment; protein powder volume data carries tighter precision than emerging nootropic stack adoption estimates. Forecasts reflect assumptions about regulatory disclosure timelines and botanical extract standardization advances. A model refresh is warranted upon material change in FDA DSHEA modernization implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Chromium Picolinate Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Nicotine Gum Market