
 Vegan Protein Market | 2026-2036
Vegan Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Protein Market Intelligence
EU Green Deal protein diversification targets are hardening the cost-of-entry calculus for new vegan protein suppliers. Cargill, Incorporated leverages its oilseed processing footprint to secure pea protein isolate supply. Kerry Group PLC differentiates through flavor-mask technology that broadens application scope beyond vanilla and chocolate. Orgain sustains direct-to-consumer velocity that insulates margin from retail slotting fee inflation.
Vegan protein encompasses isolated, concentrated, or hydrolyzed plant-derived amino acid profiles achieving protein digestibility-corrected amino acid scores comparable to animal counterparts, typically processed through wet fractionation or dry milling to yield 80-90% protein content for food fortification. Pea protein dominates powder formulations due to superior emulsification and neutral flavor relative to hemp or rice alternatives. Ready-to-drink applications attract the fastest margin expansion as beverage brands seek clean-label alternatives to soy. Sports nutrition anchors volume absorption, though functional foods now represent the fastest-growing application as bakery and snack manufacturers reformulate for plant-forward positioning.
FDA GRAS self-determination governs novel protein ingredient entry in the United States, while EFSA novel food authorizations impose stricter toxicological dossier requirements that extend European commercialization timelines. BIS standards in India and China's SAMR food safety registrations further fragment compliance burden for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions that treat precision-fermented proteins as novel foods versus conventional processing aids, as this classification split will determine which technology pathways achieve scalable market access.
Market Dynamics
EU Green Deal protein diversification targets are hardening the cost-of-entry calculus for new vegan protein suppliers. Cargill, Incorporated leverages its oilseed processing footprint to secure pea protein isolate supply. Kerry Group PLC differentiates through flavor-mask technology that broadens application scope beyond vanilla and chocolate. Orgain sustains direct-to-consumer velocity that insulates margin from retail slotting fee inflation.
Growth Catalysts
- EU Green Deal protein diversification:Mandatory targets redirect public procurement and agricultural subsidies toward legume-dominant supply chains, expanding contract farming for pea and fava bean protein feedstock across member states.
- Sports nutrition category expansion:Athletic performance brands now allocate R&D budgets to plant-based recovery formulations, pulling powder volumes from legacy whey-dominant portfolios.
- Precision fermentation scale-up:Novel protein production methods achieve cost parity with extracted isolates, enabling clean-label positioning without agricultural land-use constraints.
Market Restraints
- Pea protein input cost volatility:Yellow pea futures correlate with North American crop yields, squeezing margin predictability for isolate processors dependent on single-source geography.
- EFSA novel food authorization timelines:Toxicological dossier requirements extend European commercialization by 18-24 months versus FDA GRAS self-determination pathways.
- Hemp protein technical limitations:Inferior emulsification and pronounced grassy off-notes restrict application scope to niche whole-food positioning.
Strategic Opportunities
- Ready-to-drink beverage white space:Clean-label RTD brands seek alternatives to soy lecithin and dairy emulsifiers, opening formulation partnerships with hydrolyzed pea protein suppliers.
- India BIS standards harmonization:Emerging domestic protein fortification mandates for school nutrition programs create import substitution opportunities for local isolate production.
- Bakery and snack functional foods:Reformulation pipelines for plant-forward positioning drive technical service contracts linking protein suppliers to CPG manufacturers.
Industry Challenges
- Flavor chemist talent scarcity:Masking vegetal off-notes in high-concentration isolates requires specialized sensory science expertise concentrated in legacy dairy flavor houses.
- Dual carbon compliance complexity:China's SAMR food safety registrations and carbon intensity disclosures impose parallel documentation burdens for multinational suppliers.
- Precision fermentation IP fragmentation:Licensing disputes over host strain modifications and downstream processing patents delay technology transfer agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Protein Market |
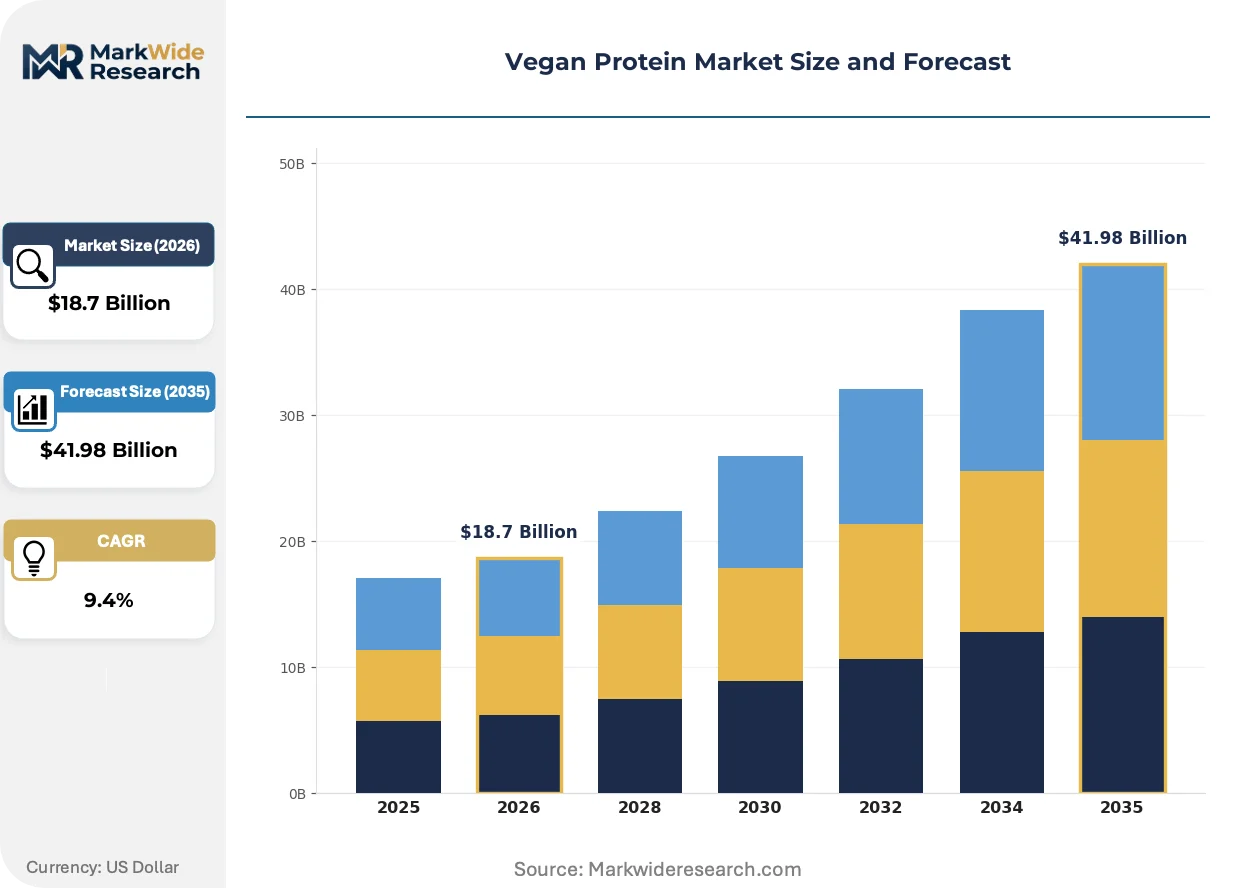
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Rice Protein, Soy Protein, Hemp Protein, Pumpkin Seed Protein Form: Powder, Ready-to-Drink, Bar, Capsules, Concentrate Application: Sports Nutrition, Weight Management, Functional Foods, Infant Nutrition, Animal Feed End User: Athletes, Fitness Enthusiasts, Seniors, Pregnant Women, Children |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Ingredion Incorporated, Glanbia PLC, Kerry Group PLC, Garden of Life, Orgain, Bunge Global SA, Wilmar International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Protein Market Strategic Shifts & Innovations
Technology convergence between extraction efficiency and sensory masking is compressing formulation barriers that historically segmented vegan protein into commodity and premium tiers.
Membrane filtration advances in wet fractionation are electrifying isolate purity thresholds. Sports nutrition manufacturers now specify 90% protein content with sub-1% ash residue, displacing legacy spray-dried concentrates. This specification compression is enabling clean-label positioning in mass-market retail channels previously closed to plant-based fortification.
EFSA novel food authorizations are tightening toxicological evidence requirements for emerging protein sources. Fava bean and potato protein entrants face extended safety dossier preparation, diverting R&D budgets from formulation innovation toward regulatory compliance. European suppliers are responding by front-loading clinical trials and establishing dedicated novel food submission teams.
Direct-to-consumer subscription models are displacing traditional retail slotting fee structures. Functional food startups now capture 40-60% gross margins through owned-channel sales, bypassing conventional grocer distribution. Germany and the United Kingdom exhibit the highest concentration of these vertically integrated brands, with Berlin and London anchoring European D2C protein logistics clusters.
Vegan Protein Market Segmentation
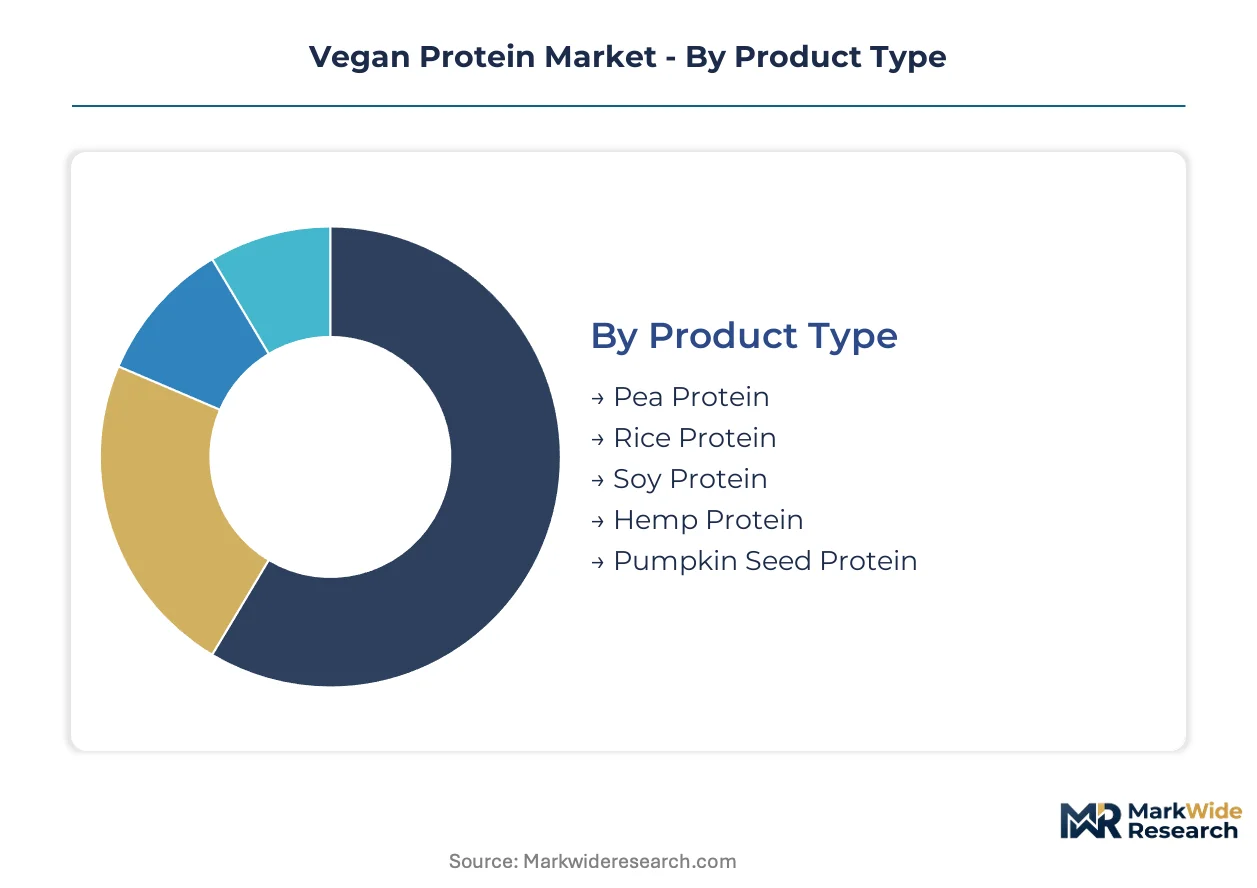
Product differentiation in vegan proteins follows distinct upgrade cycles across form factors and purity grades. Manufacturers compete on specification compression as sports nutrition brands demand 90% isolate thresholds that displace legacy concentrates.
Product Type:
Upgrade cycles in protein sourcing track emulsification performance and flavor neutrality as the primary replacement drivers.
- Pea Protein:Wet-fractionated isolates achieve 80-90% protein content with superior emulsification stability versus legume alternatives. Sports nutrition manufacturers in Germany specify pea protein for clean-label RTD formulations, though North American yellow pea futures volatility squeezes margin predictability for processors.
- Rice Protein:Hypoallergenic amino acid profiles processed through enzymatic hydrolysis yield bitter off-notes that require Kerry Group flavor-mask technology. Weight management applications in the United States absorb volume as dairy-allergic consumers seek whey alternatives.
- Soy Protein:Mature supply chains from oilseed processing deliver cost-competitive concentrates, though GMO labeling requirements constrain clean-label positioning.
- Hemp Protein:Cold-pressed whole-food formats retain fiber and omega fatty acids at the expense of protein density, limiting application scope to niche wellness positioning.
- Pumpkin Seed Protein:Emerging European supply from Austrian and Hungarian contract farming addresses allergen-free demand in functional food fortification.
Pea protein sits at the top of the volume ranking, with pumpkin seed protein climbing the fastest.
Form:
Form factor selection tracks convenience upgrade cycles from kitchen preparation to on-consumption occasions.
- Powder:Bulk concentrates and isolates dominate home-use preparation, with specification compression toward 90% protein content displacing legacy spray-dried grades. German retail SKU multiplication across conventional grocers anchors volume absorption.
- Ready-to-Drink:Beverage brands seek hydrolyzed pea protein to replace soy lecithin and dairy emulsifiers in clean-label positioning. Margin expansion attracts formulation partnerships with isolate suppliers.
- Bar:Extruded protein matrices require binding technologies that mask vegetal texture, with bakery manufacturers driving technical service contracts.
- Capsules:Precision-dosed delivery formats target senior and pregnant women segments with controlled amino acid intake.
- Concentrate:Lower-purity grades retain application in animal feed and economy-tier sports nutrition.
Powder maintains volume leadership, though RTD formats are expanding most quickly.
Application:
Application segmentation reflects reformulation cycles as CPG manufacturers reposition portfolios for plant-forward claims.
- Sports Nutrition:Athletic performance brands allocate R&D budgets to plant-based recovery formulations, pulling powder volumes from whey-dominant portfolios. EFSA novel food authorizations impose 18-24 month delays versus FDA GRAS pathways.
- Weight Management:Meal replacement formulations leverage satiety-index positioning with high-protein, low-calorie density profiles.
- Functional Foods:Bakery and snack reformulation pipelines drive the steepest expansion trajectory as manufacturers seek protein fortification without allergen declarations.
- Infant Nutrition:Hypoallergenic positioning requires toxicological dossier preparation that extends European commercialization timelines.
- Animal Feed:Pet food manufacturers adopt human-grade isolate specifications for premium positioning.
Sports nutrition holds volume primacy, with functional foods gaining share fastest.
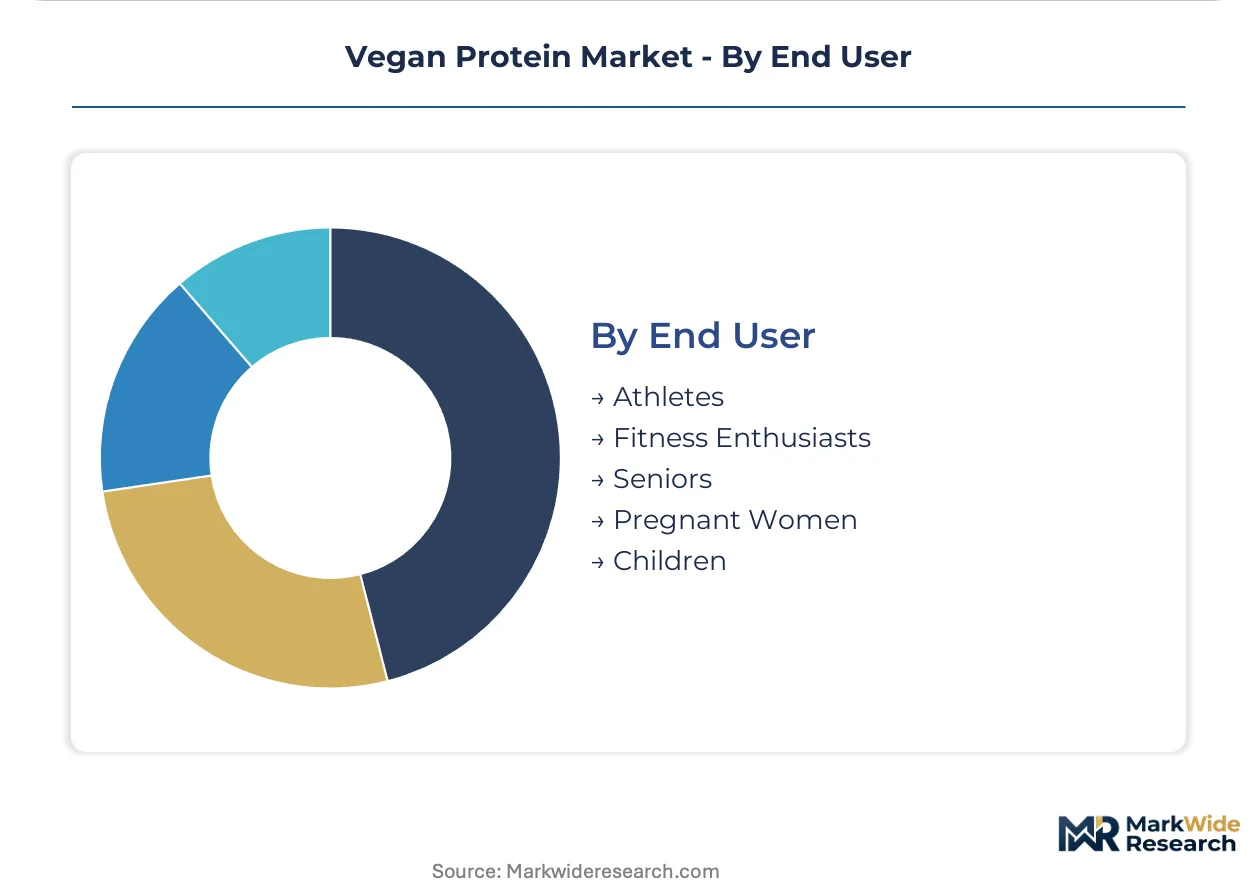
End User:
End-user segmentation tracks demographic-specific protein requirements and consumption occasion patterns.
- Athletes:Leucine-threshold requirements drive specification toward 90% isolate purity with rapid absorption kinetics. Sports nutrition brands in the United Kingdom and Germany anchor demand concentration.
- Fitness Enthusiasts:Weekend warrior segments prioritize convenience and flavor variety over clinical performance metrics.
- Seniors:Sarcopenia-prevention positioning emphasizes complete amino acid profiles with digestibility-corrected scores comparable to animal proteins.
- Pregnant Women:Folate and iron co-fortification requirements intersect with protein supplementation in prenatal nutrition.
- Children:School nutrition program mandates in India create import substitution opportunities for local isolate production under BIS standards.
Athletes represent the largest addressable base, with seniors showing the steepest demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemists and food technologists cluster in Germany's Rhine-Ruhr corridor and the Netherlands' Wageningen agri-tech ecosystem, anchoring Europe's formulation leadership. These talent concentrations drive specification compression toward 90% isolate purity.
Germany
Retail vegan SKU multiplication across conventional grocers anchors volume absorption, with Edeka and REWE chains expanding plant-based protein assortments. The EU Green Deal protein diversification targets redirect agricultural subsidies toward legume-dominant contract farming in Lower Saxony. Berlin anchors European D2C protein logistics clusters where vertically integrated brands capture 40-60% gross margins through owned-channel sales.
United States
Sports nutrition brands allocate R&D budgets to plant-based recovery formulations, pulling powder volumes from whey-dominant portfolios. FDA GRAS self-determination governs novel protein ingredient entry, compressing commercialization timelines versus European pathways. Chicago and Austin anchor formulation partnerships between hydrolyzed pea protein suppliers and clean-label RTD beverage brands.
China
Domestic protein fortification mandates for school nutrition programs create import substitution opportunities for local isolate production. SAMR food safety registrations and dual carbon goals impose parallel documentation burdens for multinational suppliers. Yangtze River Delta processing clusters scale wet-fractionation capacity to meet 80-90% protein content specifications for food fortification.
India
BIS standards harmonization for emerging domestic protein fortification mandates opens import substitution opportunities for local isolate production. School nutrition program expansion drives technical service contracts linking protein suppliers to CPG manufacturers. Maharashtra and Gujarat contract farming networks redirect toward pea and fava bean protein feedstock cultivation.
United Kingdom
Fitness enthusiasts and weekend warrior segments prioritize convenience and flavor variety over clinical performance metrics, expanding powder distribution through Boots and Holland & Barrett. EFSA novel food authorization timelines for fava bean and potato protein entrants face extended safety dossier preparation. London anchors European D2C brand headquarters alongside Berlin, with shared logistics infrastructure spanning the Channel.
Vegan Protein Market Key Industry Players
The competitive structure tilts toward diversified ingredient conglomerates with legacy oilseed processing footprints. Tier-one suppliers leverage wet-fractionation scale and captive agricultural supply contracts to compress isolate purity thresholds toward 90% specifications. Three archetypes dominate: extraction-technology specialists, flavor-mask technology providers, and vertically integrated D2C brands. Capacity expansion and strategic formulation partnerships constitute the dominant competitive moves as players defend margin position against input cost volatility.
Within the diversified conglomerate tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify players leveraging oilseed processing infrastructure to secure pea protein isolate supply. Kerry Group PLC occupies a distinct position as a flavor-mask technology provider broadening application scope beyond traditional vanilla and chocolate formulations. Orgain anchors the D2C archetype, sustaining direct-to-consumer velocity that insulates margin from retail slotting fee inflation.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Glanbia PLC |
| Kerry Group PLC |
| Garden of Life |
| Orgain |
| Bunge Global SA |
| Wilmar International Limited |
| Others |
Cost & Logistics Intelligence
Yellow pea futures volatility propagates through isolate processors' cost structures, compressing margins at the 80-90% protein purity tier while sports nutrition brands in Germany and the United States demand 90% specifications. This input-cost pressure stratifies pricing across premium isolates, standard concentrates, and economy-grade feed applications.
Pricing Analysis
Ingredient-plus-technical-service bundling separates Cargill and Kerry Group offerings from commodity isolate suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks protein purity grades and flavor-mask technology inclusion. Pricing pressure stems from North American crop yield correlation squeezing margin predictability for wet-fractionation processors. Powder formats exhibit highest price sensitivity among home-preparation consumers, while RTD beverage brands absorb premium positioning for clean-label emulsifier replacement.
Supply Chain Analysis
Regional distribution centers in Germany's Rhine-Ruhr corridor and the Netherlands' Wageningen cluster anchor European formulation logistics. Pea protein supply concentrates in Canada, France, and China, with wet-fractionation capacity scaling in the Yangtze River Delta. Raw material dependencies center on yellow pea, fava bean, and rice feedstock cultivation. Single-source geography vulnerability in North American pea farming exposes processors to climate-driven input cost spikes. Distribution runs through conventional grocer networks in Germany and direct-to-consumer subscription channels in Berlin and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan protein market reads as a late-cycle quality story where specification compression toward 90% isolate purity rewards suppliers with flavor-mask capabilities and captive agricultural contracts.
For Market Incumbents: Anchor margin position through backward integration into Lower Saxony and Canadian contract farming networks. Kerry Group's flavor-mask technology demonstrates defensible differentiation against emerging precision-fermented protein substitutes. Capacity expansion in Yangtze River Delta processing clusters addresses SAMR registration requirements for Chinese market access. EFSA novel food authorization front-loading insulates against 18-24 month competitive delays for fava bean entrants. For New Entrants and Emerging Players: Enter via India's BIS standards harmonization window for school nutrition program supply. Functional foods reformulation pipelines in bakery and snack applications offer the most penetrable white space versus saturated sports nutrition. Direct-to-consumer subscription models in London and Berlin bypass retail slotting fee barriers. Technical service partnerships with CPG manufacturers provide formulation credibility without captive extraction infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where flavor chemist talent scarcity intersects with precision-fermentation IP fragmentation. Long-term viability favors extraction-technology specialists with 80-90% purity scale and established EFSA submission capabilities. Acquisition targets include regional isolate processors in Maharashtra and Gujarat with BIS-compliant infrastructure. The signal to watch is precision-fermentation cost parity achievement displacing agricultural extraction economics.| Strategic Initiative | Industry Significance |
|---|---|
| Flavor-Mask Technology Licensing | Kerry Group's sensory science capabilities broaden application scope beyond vanilla and chocolate formulations. |
| Contract Farming Integration | Cargill's oilseed processing footprint secures yellow pea isolate supply against futures volatility. |
| Direct-to-Consumer Channel Buildout | Orgain's owned-channel sales capture 40-60% gross margins insulated from retail slotting fees. |
| Novel Food Authorization Front-Loading | EFSA submission teams compress 18-24 month delays for fava bean and potato protein entrants. |
| Precision Fermentation Scale-Up | Clean-label positioning without agricultural land-use constraints achieves cost parity with isolates. |
Research Approach
Coverage spans Germany, the United States, China, India, and the United Kingdom, with primary inputs from each market cluster. Conversations with sports nutrition brand R&D directors, flavor house sensory scientists, wet-fractionation plant managers, EFSA regulatory consultants, and Indian CPG procurement leads informed demand-side and supply-side dynamics. Secondary validation drew from EU Green Deal policy documentation, FDA GRAS determination filings, SAMR food safety registration databases, BIS standards publications, and customs trade records for pea protein isolate shipments. Bottom-up volume modeling triangulated against top-down protein fortification mandate targets.
Granularity-level modeling tracked protein source, form factor, application segment, and end-user demographic across the projection horizon. Product-type segmentation captured pea, rice, soy, hemp, and pumpkin seed protein dynamics. Form analysis distinguished powder, RTD, bar, capsule, and concentrate delivery formats. Application modeling spanned sports nutrition, weight management, functional foods, infant nutrition, and animal feed. End-user segmentation addressed athletes, fitness enthusiasts, seniors, pregnant women, and children. CAGRs derived from volume absorption rates against EU protein diversification targets and Indian school nutrition program expansion.
Inputs from EFSA, FDA, SAMR, and BIS regulatory filings were available through the study window; gaps in precision-fermentation commercialization timelines introduce uncertainty bands around novel protein source adoption curves. Forecasts reflect documented assumptions regarding crop yield correlations, regulatory authorization durations, and D2C subscription model penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
US and Canada Beta Glucan Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market