
 Middle East and Africa Collagen Supplements Market | 2026-2036
Middle East and Africa Collagen Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Collagen Supplements Market Foresight
Single-serve sachet and travel-sized liquid collagen formats is rebalancing consumer purchasing patterns across pharmacy and online channels. GELITA AG leverages its bovine collagen supply chain to sustain bulk ingredient dominance in regional manufacturing partnerships. Rousselot anchors marine-sourced peptide production for aesthetic clinic channels in the Gulf. PB Leiner competes through gelatin-based formulations targeting halal-certified product requirements.
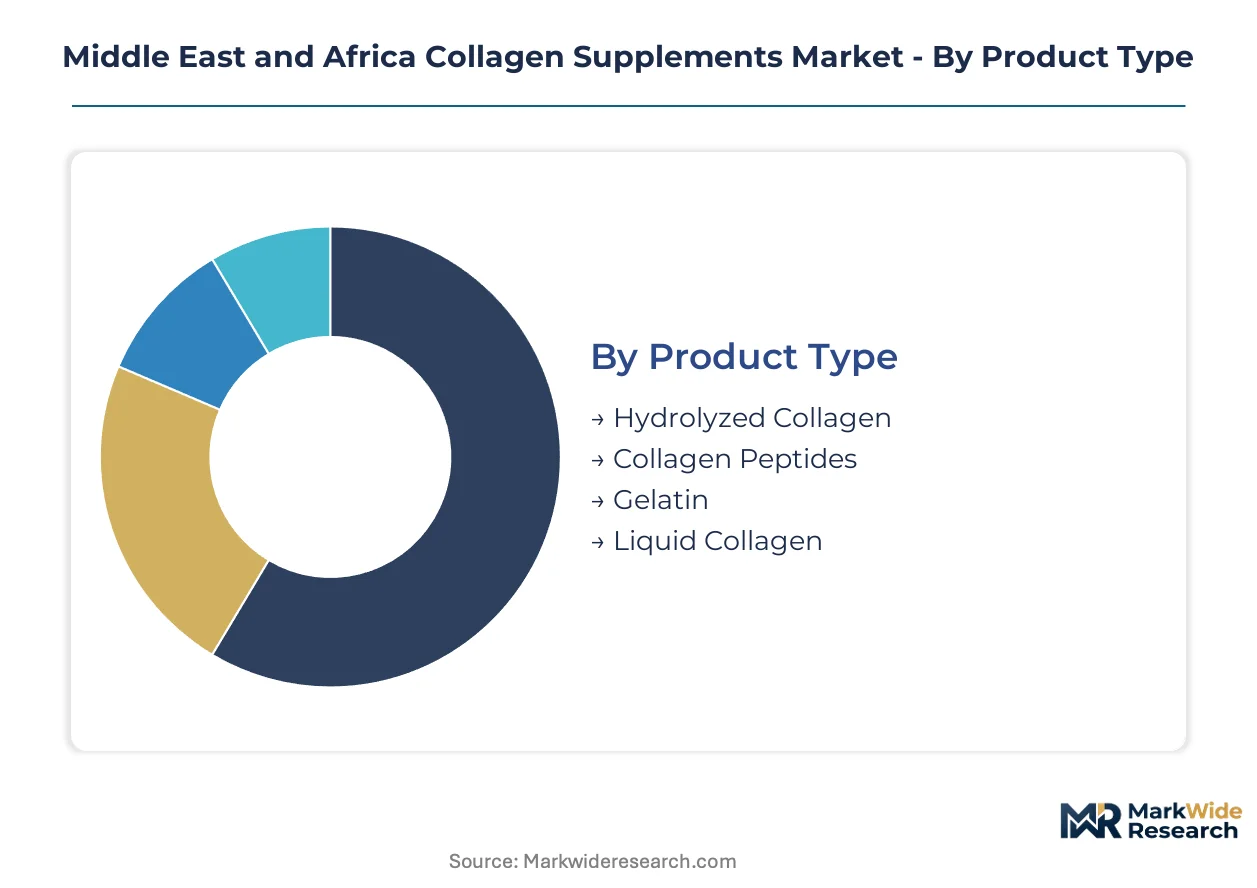
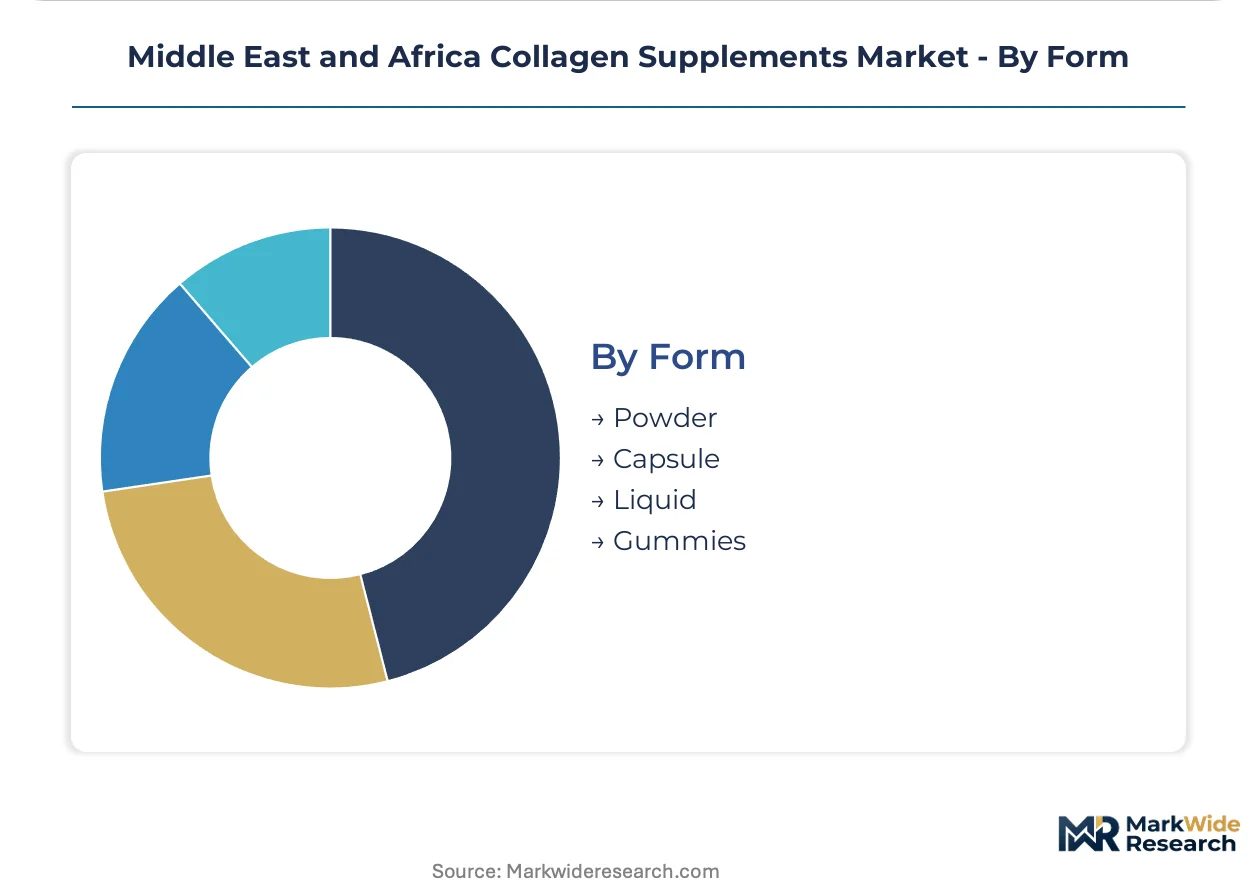
Collagen supplements comprise hydrolyzed animal or marine protein fractions, typically containing 90-95% pure collagen with specified molecular weight below 10,000 Daltons for bioavailability, consumed to support dermal elasticity, joint integrity, and musculoskeletal recovery. Hydrolyzed collagen and collagen peptides command the largest volume share due to faster absorption kinetics and broader formulation compatibility in beverages and powders. Liquid collagen and gummies represent the fastest-growing form segments as convenience-seeking health-conscious consumers shift away from traditional powder preparation. The elderly individual end-user category remains comparatively mature, while sports enthusiasts and aesthetic clinic procurement are expanding the margin pool through premium-positioned, clinically positioned products.
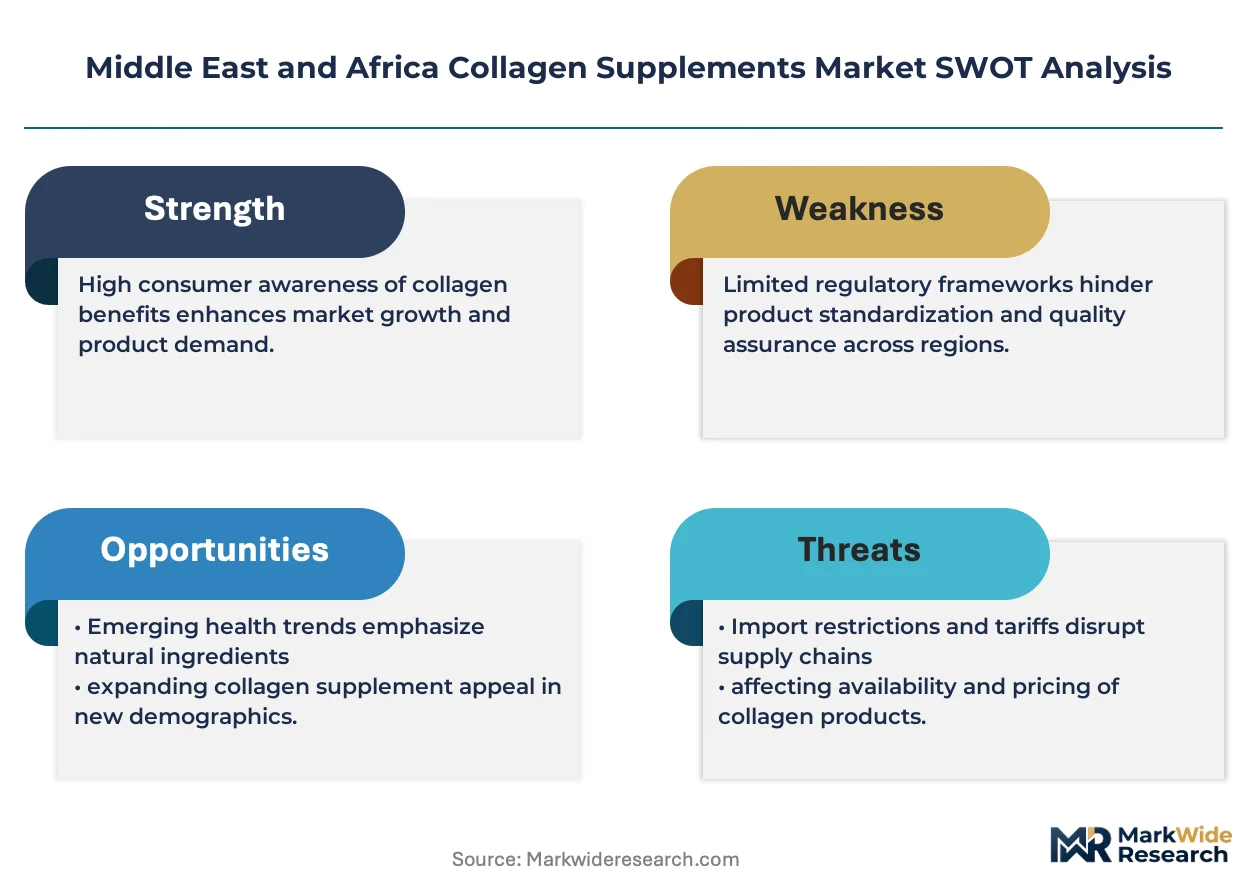
SFDA in Saudi Arabia and the Emirates Authority for Standardization and Metrology (ESMA) in the UAE enforce halal certification, label claims verification, and import registration for collagen supplements, elevating compliance costs for non-regional suppliers while creating protected channels for certified producers. South Africa's Health Products Regulatory Authority (SAHPRA) applies complementary standards for complementary medicines that restrict unsubstantiated efficacy claims and mandate Good Manufacturing Practice documentation. Stakeholders must monitor evolving halal audit protocols and e-commerce labeling enforcement as cross-border direct-to-consumer channels proliferate without traditional retail gatekeeping.
Market Dynamics
SFDA registration tightening and ESMA halal certification mandates are restructuring import compliance costs, favoring regional manufacturers with established certification pathways while elevating barriers for cross-border direct-to-consumer entrants.
Growth Catalysts
- Fitness culture deepening across Gulf states:Sports enthusiasts are expanding the addressable consumer base as gym memberships and athletic participation rates climb in Saudi Arabia and the UAE.
- Urban wellness infrastructure maturation:Premium aesthetic clinics in Dubai and Johannesburg are integrating collagen peptides into post-procedure recovery protocols, creating institutional procurement channels.
- Marine collagen bioavailability advances:Hydrolyzed peptide production improvements are enabling faster absorption claims that resonate with time-sensitive professional consumers.
Market Restraints
- Bovine raw material cost volatility:Feed price fluctuations and livestock supply constraints in Brazil and Argentina transmit directly to hydrolyzed collagen input costs for regional formulators.
- Halal certification concentration:A limited pool of ESMA-recognized audit bodies creates bottlenecks for new market entrants seeking UAE market access.
- Marine collagen substitution pressure:Plant-based collagen boosters and ceramide supplements are capturing price-sensitive segments in South African pharmacy channels.
Strategic Opportunities
- Nigeria and Kenya underpenetration:These East African markets show rising disposable income without established domestic collagen manufacturing, creating first-mover advantages for halal-certified imports.
- E-commerce direct-to-consumer expansion:Cross-border platforms are bypassing traditional retail gatekeeping, though stakeholders must monitor evolving SFDA labeling enforcement for online sales.
- Clinically positioned product premiumization:Sports recovery and joint health positioning commands margin premiums over generic beauty claims in Gulf pharmacy networks.
Industry Challenges
- Halal audit timeline compression:SFDA and ESMA documentation requirements extend product registration cycles, delaying revenue recognition for new formulations.
- Peptide characterization skill scarcity:Regional quality control laboratories lack standardized molecular weight verification capabilities, forcing reliance on European testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Collagen Supplements Market |
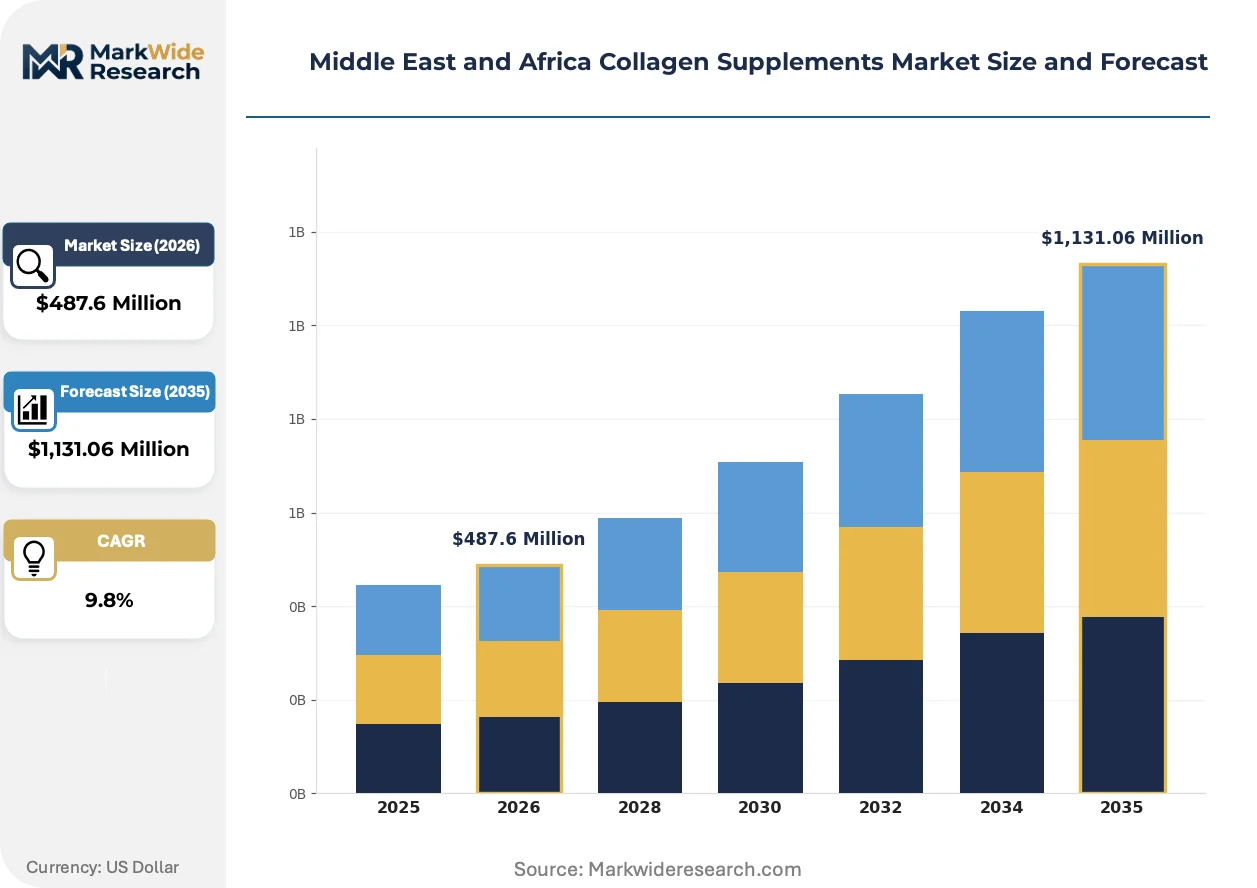
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Collagen Peptides, Gelatin, Liquid Collagen End User: Sports Enthusiasts, Aesthetic Clinics, Health-Conscious Consumers, Elderly Individuals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Form: Powder, Capsule, Liquid, Gummies |
| Companies Covered | GELITA AG, Rousselot, Collagen Solutions Plc, PB Leiner, Vital Proteins, DSM, COBIOSA, Nitta Gelatin Inc., Holista Colltech, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Collagen Supplements Market Shifts & Advancements
Liquid collagen formats and single-serve delivery systems are compressing traditional powder preparation rituals, while regulatory digitization and channel fragmentation simultaneously reshape how products reach end-users across the Middle East and Africa.
Ready-to-drink liquid collagen is overtaking conventional powder sachets in Gulf pharmacy and convenience retail channels. Young professional consumers in Dubai and Riyadh are adopting these formats for on-the-go consumption without mixing requirements. This shift is enabling premium unit pricing and expanding placement in airport retail and hotel minibars where powder formats face preparation barriers.
ESMA halal certification digitization is streamlining audit documentation and traceability requirements for marine and bovine supply chains. Manufacturers must now submit blockchain-verified chain-of-custody records to maintain certification status. Smaller regional formulators without integrated ERP systems face compliance cost escalation while certified incumbents consolidate shelf presence in UAE hypermarkets.
Subscription-based replenishment models are capturing recurring revenue from aesthetic clinic procurement officers and dedicated fitness consumers. Direct brand websites and specialized wellness platforms are displacing traditional pharmacy loyalty programs in South Africa and the Emirates. This pattern concentrates most visibly in Johannesburg and Cape Town where urban logistics infrastructure supports reliable monthly delivery cadences.
Middle East and Africa Collagen Supplements Market Segmentation
Consumer purchasing decisions in Middle East and Africa collagen supplements hinge on absorption speed, halal certification compliance, and format convenience. Manufacturers must align product architecture with these priority attributes to secure pharmacy shelf placement and e-commerce visibility.
Product Type:
Buyers prioritize bioavailability specifications and formulation versatility when selecting collagen inputs for personal use or institutional procurement.
- Hydrolyzed Collagen:Enzymatically broken protein chains with molecular weight below 10,000 Daltons enable rapid intestinal absorption. Demand concentrates in South African aesthetic clinics where post-procedure recovery protocols require fast-acting peptide delivery.
- Collagen Peptides:Highly purified fractions standardized for specific amino acid profiles support joint health positioning. Sports enthusiasts in Saudi Arabia and the UAE drive procurement through premium-priced clinical formulations targeting musculoskeletal recovery.
- Gelatin:Partially hydrolyzed collagen with gelling properties serves food and beverage applications. Halal-certified gelatin from bovine sources dominates regional manufacturing partnerships.
- Liquid Collagen:Ready-to-drink formulations eliminate preparation barriers for time-constrained professionals. Dubai airport retail and hotel channels favor this format for on-the-go consumption.
Volume sits with hydrolyzed collagen; growth tilts toward liquid collagen.
End User:
Margin potential varies sharply across consumer archetypes, with institutional buyers commanding premium pricing and individual segments showing divergent loyalty patterns.
- Sports Enthusiasts:Athletes and fitness practitioners seeking performance recovery represent the steepest expansion trajectory. Gym membership growth in Riyadh and Jeddah expands addressable base for protein-adjacent positioning.
- Aesthetic Clinics:Medical spas and dermatology practices in Johannesburg and Dubai integrate peptides into post-treatment regimens. Procurement officers favor clinically validated products with documented molecular weight verification.
- Health-Conscious Consumers:Urban professionals prioritizing preventive wellness drive pharmacy and online channel velocity. Subscription models capture recurring purchases in Cape Town and Abu Dhabi.
- Elderly Individuals:Joint health and mobility maintenance motivate sustained consumption. This segment shows established demand patterns with lower price elasticity than younger demographics.
Revenue concentrates with aesthetic clinics; volume expansion centers on sports enthusiasts.
Distribution Channel:
Channel selection determines compliance burden and margin capture, with regulatory gatekeeping favoring established retail over direct-to-consumer alternatives.
- Online Retail:Cross-border platforms bypass traditional import registration, though SFDA labeling enforcement is tightening for e-commerce shipments. Direct brand websites displace pharmacy loyalty programs in South Africa.
- Supermarkets:UAE hypermarkets demand ESMA halal certification and blockchain-verified supply chain documentation. Certified incumbents consolidate shelf presence against unverified competitors.
- Pharmacies:Professional recommendation channels dominate collagen peptide sales. Saudi pharmacy networks enforce stricter label claims verification than convenience retail.
- Specialty Stores:Wellness boutiques and fitness retail capture premium positioning for sports-targeted formulations. Limited footprint outside major metropolitan clusters.
Transaction volume flows through pharmacies; channel growth accelerates fastest in online retail.
Form:
Preparation ritual elimination and portability requirements reshape format preferences among younger demographic cohorts.
- Powder:Traditional sachet formats retain cost-sensitive segments and bulk purchasers. Mixing requirements limit adoption in convenience-oriented channels.
- Capsule:Standardized dosing appeals to supplement-routine adherents. Limited differentiation potential in saturated pharmacy environments.
- Liquid:Single-serve bottles and shots command premium unit pricing in Gulf airport retail and hotel minibars. Young professionals in Dubai and Riyadh favor on-the-go consumption without preparation.
- Gummies:Palatability-focused formats capture entry-level consumers and gift purchasers. Sugar content concerns constrain clinical positioning.
Installed base remains with powder; format innovation concentrates in liquid and gummies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional manufacturing capacity concentrates in South Africa and the UAE, while consumption growth accelerates across Gulf states and East African markets. This production-consumption asymmetry shapes import dependency patterns and regulatory gatekeeping strategies.
Saudi Arabia
Sports enthusiasts and fitness practitioners drive demand expansion as gym memberships surge in Riyadh and Jeddah. SFDA registration requirements tighten quality benchmarks and extend product approval timelines for nutritional supplements. Jeddah's pharmaceutical distribution clusters serve as the primary import gateway for halal-certified collagen peptides entering the Kingdom.
United Arab Emirates
Premium aesthetic clinics in Dubai integrate collagen into post-procedure recovery protocols, creating institutional procurement channels. ESMA halal certification mandates and blockchain-verified supply chain documentation reshape compliance costs for market entrants. Dubai airport retail and hotel minibars favor ready-to-drink liquid formats for on-the-go professional consumers.
South Africa
Urban wellness infrastructure in Johannesburg and Cape Town supports pharmacy and online channel velocity for preventive health positioning. SAHPRA applies complementary medicines standards that restrict unsubstantiated efficacy claims and mandate Good Manufacturing Practice documentation. Cape Town's subscription logistics infrastructure enables recurring revenue capture from dedicated fitness consumers.
Nigeria
Rising disposable income in Lagos and Abuja creates first-mover opportunities for halal-certified imports without established domestic manufacturing. The country's national pharmaceutical regulator applies evolving import standards for nutritional supplements. Lagos distribution networks serve as the regional hub for East African market penetration.
Kenya
Nairobi's expanding middle class demonstrates growing preventive health awareness without local collagen production capacity. Import registration requirements for nutritional supplements remain less stringent than Gulf state benchmarks. The city's emerging e-commerce logistics infrastructure supports cross-border direct-to-consumer channel development.
Middle East and Africa Collagen Supplements Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across ingredient supply and finished formulation segments. Market structure tilts toward consolidated bulk ingredient supply and fragmented branded product distribution. Three archetypes dominate: multinational gelatin conglomerates with halal certification capabilities, marine peptide specialists serving aesthetic clinic channels, and direct-to-consumer wellness brands leveraging subscription models. Competitive moves concentrate on strategic partnerships with regional distributors and portfolio diversification into convenience-oriented delivery formats.
Within the multinational ingredient tier, GELITA AG and Rousselot exemplify divergent supply chain strategies. GELITA AG represents bovine-sourced bulk dominance through established regional manufacturing partnerships. Rousselot occupies a position as the marine peptide anchor for Gulf aesthetic clinic procurement. PB Leiner sits within the halal-certified gelatin specialization segment, targeting regional formulators with compliance-ready inputs. These three companies illustrate how certification capabilities and raw material sourcing strategies determine competitive positioning across Middle East and Africa market access points.
| Leading Market Players |
|---|
| GELITA AG |
| Rousselot |
| Collagen Solutions Plc |
| PB Leiner |
| Vital Proteins |
| DSM |
| COBIOSA |
| Nitta Gelatin Inc. |
| Holista Colltech |
| Others |
Supply & Pricing Matrix
Captive bovine sourcing through Brazilian and Argentine feedlot partnerships anchors GELITA AG's cost position while enabling premium pricing power in halal-certified peptide markets. This backward integration shields regional formulators from livestock supply volatility while concentrating pricing leverage among certified incumbents.
Pricing Analysis
Margin tightening in economy-tier powder formats reflects plant-based collagen booster substitution pressure from South African pharmacy channels. Pricing stratifies across premium liquid shots, standard hydrolyzed peptides, and economy gelatin powders, with ESMA halal certification and molecular weight verification as primary differentiation levers. Cost-down pressure on standard-tier products accelerates because feed price volatility transmits directly from Brazilian livestock markets. Sports enthusiasts show lowest price sensitivity due to clinical positioning premiums, while elderly joint-health consumers demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from UAE aesthetic clinic procurement officers mandate both marine peptide and bovine gelatin qualification to secure institutional contracts. Raw material supply concentrates in Brazil, Argentina, and South Africa for bovine collagen, while marine sourcing draws from Southeast Asian fisheries through Rousselot's processing network. Single-source vulnerability sits with ESMA-recognized halal audit bodies, where certification bottlenecks constrain new entrant qualification timelines. Distribution runs through Jeddah pharmaceutical clusters and Dubai airport retail channels for premium liquid formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around certification-capable incumbents as SFDA registration tightening and ESMA blockchain documentation requirements force subscale formulators toward exit. Halal audit timeline compression and peptide characterization skill scarcity filter out undercapitalized competitors.
For Market Incumbents: Extend certification moats by deepening blockchain-verified supply chain integration into Southeast Asian marine sourcing and securing exclusive ESMA audit body relationships. Defend against plant-based collagen booster substitution by accelerating clinically validated joint health positioning in Saudi pharmacy networks. Capacity addition in South African manufacturing clusters captures Nigeria and Kenya import demand before halal-certified competitors establish local partnerships.
For New Entrants and Emerging Players: The gap between premium aesthetic clinic pricing and economy pharmacy tiers creates entry space for mid-market liquid collagen formats targeting Nairobi and Lagos fitness consumers. Nigeria's rising disposable income without domestic manufacturing offers the most penetrable geography for halal-certified direct-to-consumer launches. Subscription-based replenishment models bypass traditional retail gatekeeping while building recurring revenue before pharmacy shelf presence.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational gelatin conglomerates seeking halal certification capabilities and regional distribution infrastructure. Long-term viability hinges on regulatory compliance automation and clinical validation assets that sustain premium positioning through tightening SFDA enforcement. Watch ESMA digitization timeline acceleration as the signal indicating certification cost escalation and incumbent consolidation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Digitization | Blockchain-verified supply chain documentation secures ESMA compliance and hypermarket shelf access. |
| Clinical Validation Investment | Documented molecular weight verification enables aesthetic clinic procurement and premium positioning. |
| Liquid Format Expansion | Ready-to-drink collagen captures Dubai airport retail and hotel minibar channels from powder incumbents. |
| Subscription Model Deployment | Recurring revenue platforms displace pharmacy loyalty programs in Johannesburg and Cape Town. |
| East African Market Entry | First-mover halal-certified imports capture Nigeria and Kenya before domestic manufacturing emerges. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across ingredient procurement managers at regional formulators, halal certification auditors, aesthetic clinic procurement officers, and pharmacy category buyers. SFDA registration databases, ESMA halal certification registries, and South African complementary medicines filings provided compliance benchmarking. Bottom-up demand modeling from gym membership growth and clinic procedure volumes triangulated against top-down trade flow analysis.
Granularity-level modeling applied country-specific regulatory cluster segmentation alongside end-user archetype differentiation across sports enthusiasts, aesthetic clinics, and elderly consumers. Product type splits between hydrolyzed collagen, peptides, gelatin, and liquid formats were modeled with molecular weight specification tiers. CAGRs were derived from regression analysis against disposable income proxies and wellness infrastructure investment indicators. Feed price volatility indices and halal audit capacity constraints informed supply-side scenario boundaries.
Underlying measurement precision varies by segment; Saudi Arabia and UAE volume estimates carry tighter precision than Nigeria and Kenya where formal channel data remains sparse. Forecasts reflect assumptions around SFDA enforcement intensity and ESMA digitization rollout pace. Deviation in halal audit body accreditation timelines or marine raw material supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
North America Digestive Health Supplements Market