
 Lithium Orotate Supplement Market | 2026-2036
Lithium Orotate Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Orotate Supplement Market Insights
The R&D-to-manufacturing capability gap between premium and value-tier suppliers is reorganizing competitive tiers in lithium orotate supplements. Pure Encapsulations leverages pharmaceutical-grade sourcing protocols to sustain premium positioning. Swanson Health Products anchors mass-market volume through private-label scale and catalog distribution. NOW Foods competes on price-accessibility while maintaining third-party certification coverage.
Lithium orotate is a lithium salt of orotic acid, typically formulated at elemental lithium doses of 5 mg per serving through chelation bonding with the pyrimidine base carrier. Manufacturers produce it via direct crystallization followed by micronization for bioavailability enhancement, targeting consumers seeking trace mineral support for mood stability and cognitive function. Capsules dominate current output due to dosing precision and moisture protection, while liquid formats attract pediatric and geriatric populations with swallowing difficulties. The Vegan formulation segment captures expanding margin pools as clean-label preferences intensify among Wellness Seekers purchasing through Online Retailers.
FDA oversight under DSHEA mandates adverse event reporting and Good Manufacturing Practice compliance for all domestic lithium orotate production, while FTC advertising standards restrict unapproved disease claims that would trigger drug classification. The National Sanitation Foundation and United States Pharmacopeia voluntary certification programs increasingly function as de facto market access requirements for pharmacy and health store placement. Stakeholders must monitor evolving FDA enforcement priorities around mental health positioning claims to avoid warning letters that disrupt channel relationships.
Market Dynamics
DSHEA enforcement tightening around mental health claims is compressing permissible marketing language and forcing reformulation of positioning strategies across the lithium orotate category. This regulatory pressure cascades through labeling, advertising, and channel access decisions.
Growth Catalysts
- Clean-label certification expansion:NSF International and USP verification programs now serve as gatekeepers for pharmacy shelf placement, pulling lithium orotate into mainstream retail channels previously closed to unverified supplements.
- Trace mineral repositioning:Formulators are recasting lithium orotate as a cognitive wellness mineral rather than a psychiatric adjunct, bypassing FDA drug claim restrictions while accessing the brain health segment.
- Direct-to-consumer channel maturation:Subscription-based wellness platforms capture recurring revenue from mood support seekers, reducing customer acquisition costs and building lifetime value pools outside traditional retail.
Market Restraints
- Elemental lithium supply concentration:Spodumene and brine extraction concentrates in Chile, Argentina, and Australia, exposing supplement manufacturers to battery industry demand spikes and price volatility.
- FDA warning letter risk:Unapproved disease claims for depression, anxiety, or bipolar disorder trigger enforcement actions that freeze distribution and force costly label revisions.
- Pharmaceutical substitution threat:Prescription mood stabilizers and emerging digital therapeutics capture diagnosed patient populations, narrowing the addressable market to subclinical wellness seekers.
Strategic Opportunities
- Pediatric formulation white space:Liquid microdose formats for children with attention difficulties represent an underserved application segment with limited current competition.
- Vegan certification arbitrage:Plant-based capsule shells and excipient-free formulations command 40-60% price premiums in specialty channels, expanding margin pools for compliant manufacturers.
- Practitioner channel development:Functional medicine and integrative psychiatry networks create prescriptive authority pathways that bypass mass-market advertising restrictions.
Industry Challenges
- Third-party testing capacity constraints:NSF and USP laboratory backlogs extend certification timelines to 6-12 months, delaying product launches and freezing working capital.
- Raw material identity verification complexity:Orotic acid precursor sourcing from multiple chemical suppliers requires rigorous incoming QC to detect adulteration and maintain batch consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Orotate Supplement Market |
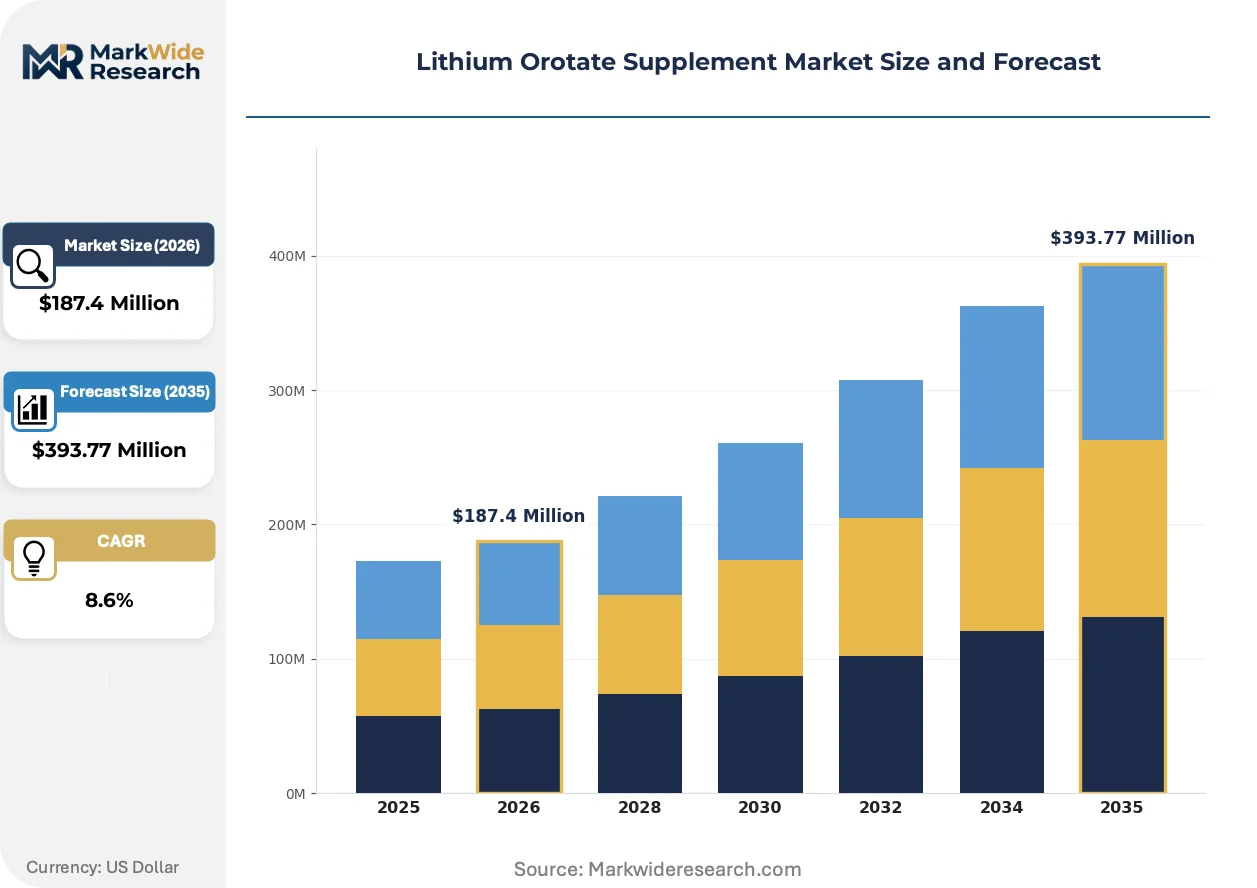
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powders, Liquid End User: Adults, Seniors, Athletes, Wellness Seekers Sales Channel: Online Retailers, Pharmacies, Health Stores, Nutraceutical Suppliers Formulation: Vegan, Gluten-Free, Non-GMO, Organic |
| Companies Covered | Pure Encapsulations, Swanson Health Products, Advanced Research, NOW Foods, Life Extension, Thorne Research, American Biologics, Good State Health Solutions, Jarrow Formulas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Orotate Supplement Market Trends and Innovations
Liposomal delivery systems and nano-micronization processes are rewriting bioavailability assumptions in mineral supplementation, collapsing the effective dose threshold and enabling new competitive positioning.
Micronization technology is reducing elemental lithium particle size below 10 microns, enhancing cellular uptake rates and allowing manufacturers to market reduced-dose efficacy claims. Wellness seekers seeking minimalist supplementation protocols are adopting these advanced formats at accelerating rates. This technological shift is displacing standard crystalline lithium orotate in premium tier positioning, compressing margins for legacy formulation suppliers.
FDA enforcement priorities have sharpened around mental health positioning claims, with the Division of Dietary Supplement Programs issuing targeted warning letters to firms implying antidepressant or anxiolytic effects. Manufacturers are responding by scrubbing social media testimonials and reformulating packaging to emphasize trace mineral status rather than mood modulation. The direct-to-consumer segment bears the highest compliance burden, as e-commerce listings lack the filtering oversight of brick-and-mortar retail buyers.
Subscription wellness platforms are consolidating purchasing decisions into algorithm-driven replenishment cycles, reducing brand switching and locking consumers into proprietary formulation ecosystems. Mass-market retailers are losing traffic to these digital-native channels, which capture detailed consumption data and personalize dosing recommendations. California and New York metro areas exhibit the highest subscription penetration, correlating with functional medicine practitioner density and clean-label preference intensity.
Lithium Orotate Supplement Market Segmentation
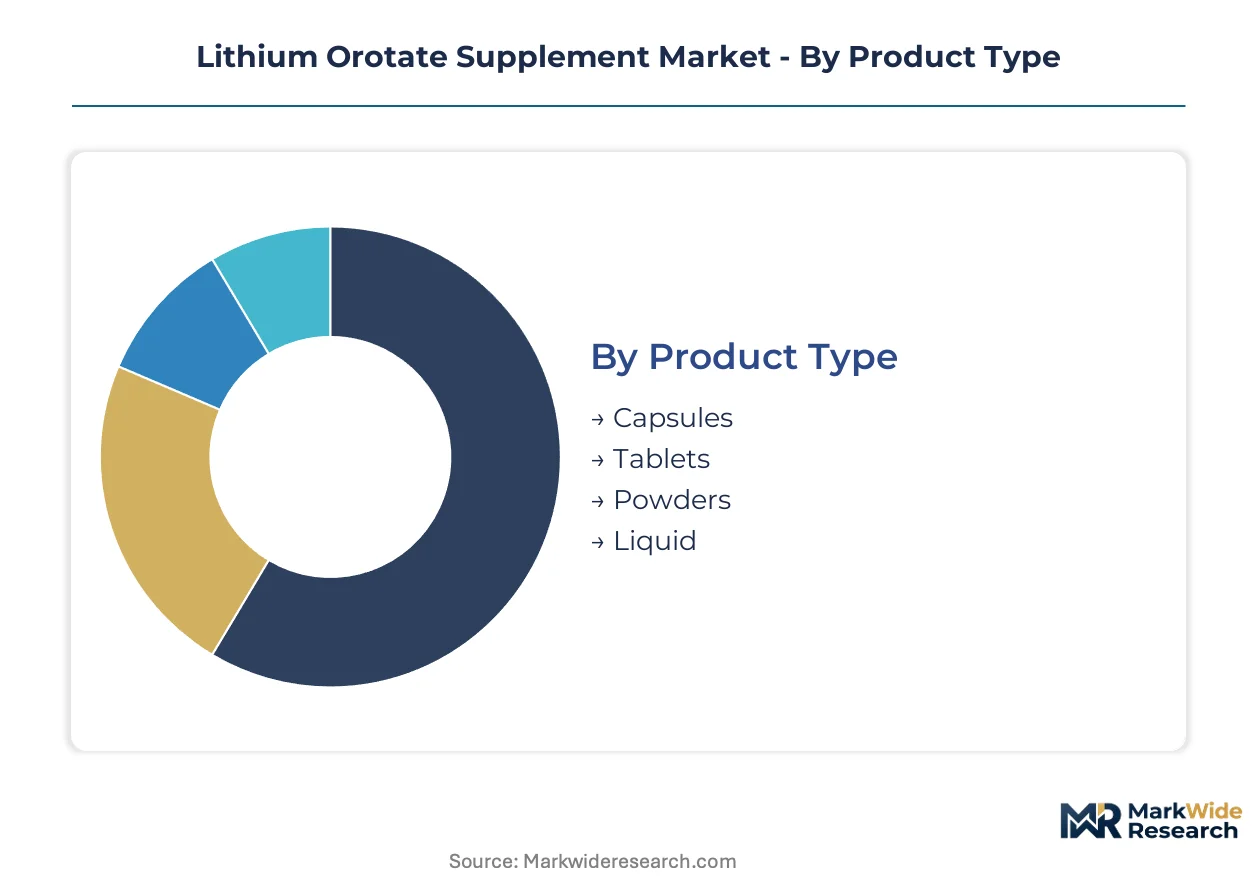
Segmentation in lithium orotate supplements reveals how regulatory pressure and consumer preference divergence create distinct competitive arenas. Each dimension exposes different margin structures, channel access requirements, and compliance burdens that reshape supplier positioning.
Product Type:
FDA moisture-content specifications and dissolution testing requirements segment manufacturing capability across dosage forms, concentrating premium production among GMP-certified facilities while commodity formats compete on throughput scale.
- Capsules:Gelatin and hypromellose shells enclose precisely metered lithium orotate doses, typically 5 mg elemental lithium per unit. Adults in the United States seeking mood support applications drive volume through pharmacy and health store channels where NSF verification functions as shelf placement gatekeeper.
- Liquid:Micronized suspensions in aqueous or glycerin bases enable dose titration for populations with swallowing difficulties. Pediatric and geriatric applications in California and New York metro areas expand fastest as subscription wellness platforms capture recurring replenishment cycles.
- Tablets:Direct-compression manufacturing with binders and disintegrants yields cost-efficient output for mass-market distribution.
- Powders:Bulk crystalline product serves compounding pharmacies and practitioner-directed protocols requiring custom dosing flexibility.
Established volume favors capsules; emerging adoption favors liquid.
End User:
Customer archetypes diverge sharply in their sensitivity to clinical positioning language, with diagnosed condition populations requiring strict DSHEA compliance while wellness seekers tolerate trace mineral framing.
- Wellness Seekers:Subclinical consumers pursuing cognitive optimization and stress resilience represent the addressable core outside pharmaceutical substitution threat. Direct-to-consumer subscription platforms in the United States concentrate demand through algorithm-driven replenishment with personalized dosing recommendations.
- Seniors:Aging populations with polypharmacy concerns prefer low-dose mineral supplementation over prescription mood stabilizers. Florida and Arizona retirement corridors exhibit concentrated uptake through integrative medicine practitioners who bypass mass-market advertising restrictions.
- Adults:Working-age consumers with mild mood variability drive baseline demand through retail and e-commerce channels.
- Athletes:Competitive and recreational performers seeking neurochemical balance and recovery support adopt lithium orotate within broader nootropic stacks.
Wellness seekers command margin premiums; seniors represent the steepest expansion trajectory.
Sales Channel:
Channel selection determines exposure to FTC advertising scrutiny, with brick-and-mortar retail buyers filtering non-compliant products while digital platforms bear direct enforcement risk.
- Online Retailers:Amazon, brand-direct sites, and subscription wellness platforms capture the majority of lithium orotate volume through algorithmic replenishment and detailed consumption data capture. FTC monitoring of disease claims intensifies here, forcing social media testimonial scrubbing and label revision cycles.
- Pharmacies:CVS, Walgreens, and independent drugstores require USP or NSF certification as de facto entry conditions, concentrating shelf presence among premium-tier suppliers with pharmaceutical-grade sourcing protocols.
- Health Stores:Whole Foods and regional cooperatives emphasize clean-label positioning with vegan and organic certification requirements.
- Nutraceutical Suppliers:B2B ingredient distribution serves contract manufacturers and private-label brands with bulk procurement and formulation services.
Pharmacies anchor revenue stability; online retailers drive volume expansion.
Formulation:
Certification tiering creates price stratification that expands margin pools for compliant manufacturers while compressing returns for uncertified commodity production.
- Vegan:Plant-based capsule shells from pullulan or modified cellulose eliminate animal-derived excipients, commanding 40-60% price premiums in specialty channels. Clean-label preference intensity in California and New York metro areas concentrates demand among wellness seekers purchasing through online retailers.
- Non-GMO:Identity-preserved orotic acid and lithium carbonate sourcing with third-party verification meets Project Non-GMO and similar program standards for mainstream retail placement.
- Gluten-Free:Certification under GFCO or NSF protocols enables celiac and gluten-sensitive population access without cross-contamination risk.
- Organic:USDA Organic certification for excipients and processing aids captures niche premium positioning despite limited organic lithium source availability.
Vegan certification captures expanding margin pools; organic remains supply-constrained.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers absorb price premiums that German and Australian buyers refuse, creating a transatlantic margin divergence that shapes supplier investment priorities. This pricing-power asymmetry concentrates manufacturing scale in North American distribution hubs while European and Asia-Pacific markets operate on thinner certification-driven economics.
United States
Wellness seekers in California and New York metro areas drive subscription platform adoption for trace mineral mood support. FDA Division of Dietary Supplement Programs enforcement actions against unapproved disease claims force label revisions and social media scrubbing cycles. Miami and Phoenix retirement corridors channel senior demand through integrative medicine practitioners who bypass mass-market advertising restrictions.
Germany
EMA guidance on borderline substances creates regulatory clarity that enables pharmacy-channel placement for lithium orotate with explicit mineral-water positioning. Federal Institute for Drugs and Medical Devices adverse event reporting requirements exceed DSHEA stringency, elevating compliance costs for exporters. Bavaria's nutraceutical manufacturing cluster near Munich hosts GMP-certified contract facilities serving private-label brands across the European Economic Area.
United Kingdom
Medicines and Healthcare products Regulatory Agency borderline determinations classify lithium orotate as a food supplement when elemental lithium stays below specified thresholds. MHRA enforcement against implied medicinal claims mirrors FDA warning letter patterns, compressing permissible marketing vocabulary. London's functional medicine practitioner density supports direct-distribution models that circumvent traditional retail pharmacy gatekeepers.
Australia
Therapeutic Goods Administration scheduling decisions exempt low-dose lithium orotate from prescription requirements, enabling pharmacy shelf presence with listed medicine status. TGA advertising code restrictions on mental health claims parallel FTC and MHRA enforcement trajectories. Sydney and Melbourne wellness retail clusters emphasize TGA-listed certification as a de facto quality signal for clean-label consumers.
Canada
Health Canada Natural and Non-prescription Health Products Directorate licensing requirements impose pre-market notification burdens that delay product launches relative to DSHEA jurisdictions. NHPD site licensing mandates GMP compliance verification that filters out uncertified suppliers. Toronto and Vancouver direct-to-consumer distribution hubs serve cross-border demand from US wellness seekers seeking TGA-equivalent regulatory rigor.
Lithium Orotate Supplement Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with pharmaceutical-grade sourcing protocols separating premium-tier suppliers from mass-market volume competitors. The vendor base stratifies across three functional tiers: GMP-certified facilities with NSF verification, catalog-scale private-label operators, and price-accessible third-party-certified commodity producers. Dominant competitive moves include practitioner channel development to bypass advertising restrictions and vegan certification arbitrage to capture clean-label margin premiums.
Within the premium-tier vector, Pure Encapsulations and Thorne Research exemplify pharmaceutical-grade sourcing archetypes that sustain pricing power through NSF and USP verification. NOW Foods occupies a position on the price-accessibility tier while maintaining third-party certification coverage. Swanson Health Products anchors mass-market volume through private-label scale and catalog distribution infrastructure.
| Leading Market Players |
|---|
| Pure Encapsulations |
| Swanson Health Products |
| Advanced Research |
| NOW Foods |
| Life Extension |
| Thorne Research |
| American Biologics |
| Good State Health Solutions |
| Jarrow Formulas |
| Others |
Pricing and Supply Chain Analysis
Six-to-twelve-month NSF certification timelines compress working capital cycles and concentrate pricing power among GMP-verified manufacturers who can absorb inventory carrying costs. This lead-time asymmetry separates premium-tier suppliers commanding certification premiums from commodity producers exposed to spot-market lithium volatility.
Pricing Analysis
The customization-premium spread spans forty-to-sixty percent between vegan-certified specialty formulations and standard gelatin-capsule equivalents. Subscription-based wellness platforms anchor the dominant pricing model through algorithm-driven replenishment cycles, while NSF verification and USP certification function as primary price differentiation drivers alongside clean-label positioning. Pricing pressure stems from battery-industry demand spikes for elemental lithium feedstock, which squeezes margin pools for uncertified commodity producers. Wellness seekers purchasing through direct-to-consumer channels exhibit lowest price sensitivity, whereas mass-market retail buyers drive hardest bargaining for volume-tier supply agreements.
Supply Chain Analysis
Chile, Argentina, and Australia anchor global spodumene and brine extraction for elemental lithium feedstock. Orotic acid precursor sourcing draws from multiple chemical suppliers across North American and European specialty chemical corridors, requiring rigorous incoming quality control to detect adulteration. Single-source vulnerability concentrates in Chilean brine operations exposed to water rights disputes and climate-driven extraction variability. Distribution runs through three parallel channels: pharmacy networks demanding certification gatekeeping, health store cooperatives emphasizing clean-label positioning, and direct-to-consumer platforms capturing consumption data for personalized dosing recommendations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium orotate category functions as a service-attach opportunity where subscription replenishment algorithms and practitioner-protocol consulting expand faster than capsule hardware sales. Recurring revenue layers from personalized dosing platforms now outpace unit shipment growth across premium-tier suppliers.
For Market Incumbents: Fortify certification moats through simultaneous NSF and USP verification investments while expanding captive lithium carbonate sourcing agreements with Chilean and Australian producers. Pharmaceutical substitution from prescription mood stabilizers and emerging digital therapeutics threatens addressable market scope, making backward integration into trace mineral extraction the critical defensive lever for margin preservation. For New Entrants and Emerging Players: Differentiate on pediatric liquid microdose formats for attention-difficulty applications, a white-space segment with limited incumbent competition and practitioner-channel access that bypasses mass-market advertising restrictions. California and New York metro wellness clusters offer most penetrable geography given subscription platform density and clean-label preference intensity, with functional medicine practitioner networks providing the essential go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutraceutical conglomerates with underoptimized lithium orotate divisions lacking dedicated certification investment or direct-to-consumer infrastructure. Long-term viability across the projection horizon hinges on regulatory arbitrage capability and practitioner-channel control rather than retail shelf presence alone, with FDA enforcement priority shifts around mental health claims serving as the critical inflection indicator for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Vegan Certification Arbitrage | Plant-based capsule shells capture forty-to-sixty percent price premiums in California and New York specialty channels. |
| Practitioner Channel Development | Functional medicine networks create prescriptive authority pathways that bypass FTC advertising restrictions on disease claims. |
| Backward Integration into Lithium Sourcing | Captive spodumene agreements with Australian producers insulate margin pools from battery-industry demand spikes. |
| Liposomal Delivery System Launch | Nano-micronization technology collapses effective dose thresholds and displaces standard crystalline formulations in premium positioning. |
| Subscription Platform Partnership | Algorithm-driven replenishment cycles reduce customer acquisition costs and lock consumers into proprietary formulation ecosystems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with supplement formulators, regulatory affairs directors at GMP-certified facilities, pharmacy category buyers, and functional medicine practitioners; and secondary validation through FDA warning letter databases, NSF certification registries, DSHEA enforcement records, and customs trade data for lithium carbonate imports. Bottom-up demand modeling across dosage forms, certification tiers, and channel structures was triangulated against top-down market sizing from production capacity disclosures and retail audit data.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation across product type, end-user archetype, sales channel, and formulation certification tier. CAGRs were derived from elasticity-adjusted demand curves incorporating practitioner adoption rates, subscription platform penetration, and regulatory enforcement intensity variations. Industry-specific inputs included NSF laboratory backlog durations, elemental lithium spot price volatility bands, and clean-label preference indices by metropolitan statistical area.
The analysis sits within stated boundaries; outcomes outside sustained DSHEA enforcement patterns, stable lithium feedstock availability, or continued practitioner-channel expansion would require recalibration. Forecasts reflect documented assumptions regarding certification timeline normalization and battery-industry demand spillover containment. Recalibration cycles align with material shifts in FDA Division of Dietary Supplement Programs enforcement priorities and TGA scheduling decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Meal Replacement Products OEM Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
North America Vegan Supplements Market