
 Chromium Picolinate Market | 2026-2036
Chromium Picolinate Market Size, Share, and Industry Trends Forecast 2026-2036
Chromium Picolinate Market Outlook
Modular capsule-and-powder bundle formats is rebalancing how fitness enthusiasts and clinical buyers compare value across Chromium Picolinate suppliers. Lonza Group leverages its pharmaceutical-grade mineral chelation expertise to command premium positioning in practitioner channels. Nutrition 21 anchors its portfolio on patented chromium complexes backed by clinical validation for insulin sensitivity claims. NOW Foods competes through vertical control over raw material sourcing and direct-to-consumer distribution scale.
Chromium picolinate constitutes a trivalent chromium complex formed with picolinic acid, typically standardized to 12.5% elemental chromium content and produced via aqueous chelation followed by spray-drying or crystallization for bioavailability enhancement in human and animal nutrition. The compound functions primarily as a trace mineral supplement supporting carbohydrate and lipid metabolism through enhanced insulin receptor signaling. Tablet and capsule formats dominate volume in dietary supplements due to dosing precision and stability advantages over liquid alternatives, while powder segments capture margin in bulk sports nutrition and custom compounding pharmacies. Functional foods represent the fastest-growing application as beverage and bar manufacturers integrate chromium picolinate into positioned metabolic health products.
The US FDA's dietary supplement CGMP enforcement and the EPA's heavy metal testing protocols for mineral ingredients collectively elevate compliance costs for chromium picolinate suppliers seeking North American market access. India's CDSCO and FSSAI frameworks impose parallel purity and label-claim verification requirements for imported mineral chelates entering pharmaceutical and nutraceutical channels. Stakeholders must monitor evolving pharmacovigilance data on chromium bioaccumulation as regulatory bodies reassess acceptable daily intake thresholds for long-term supplementation.
Market Dynamics
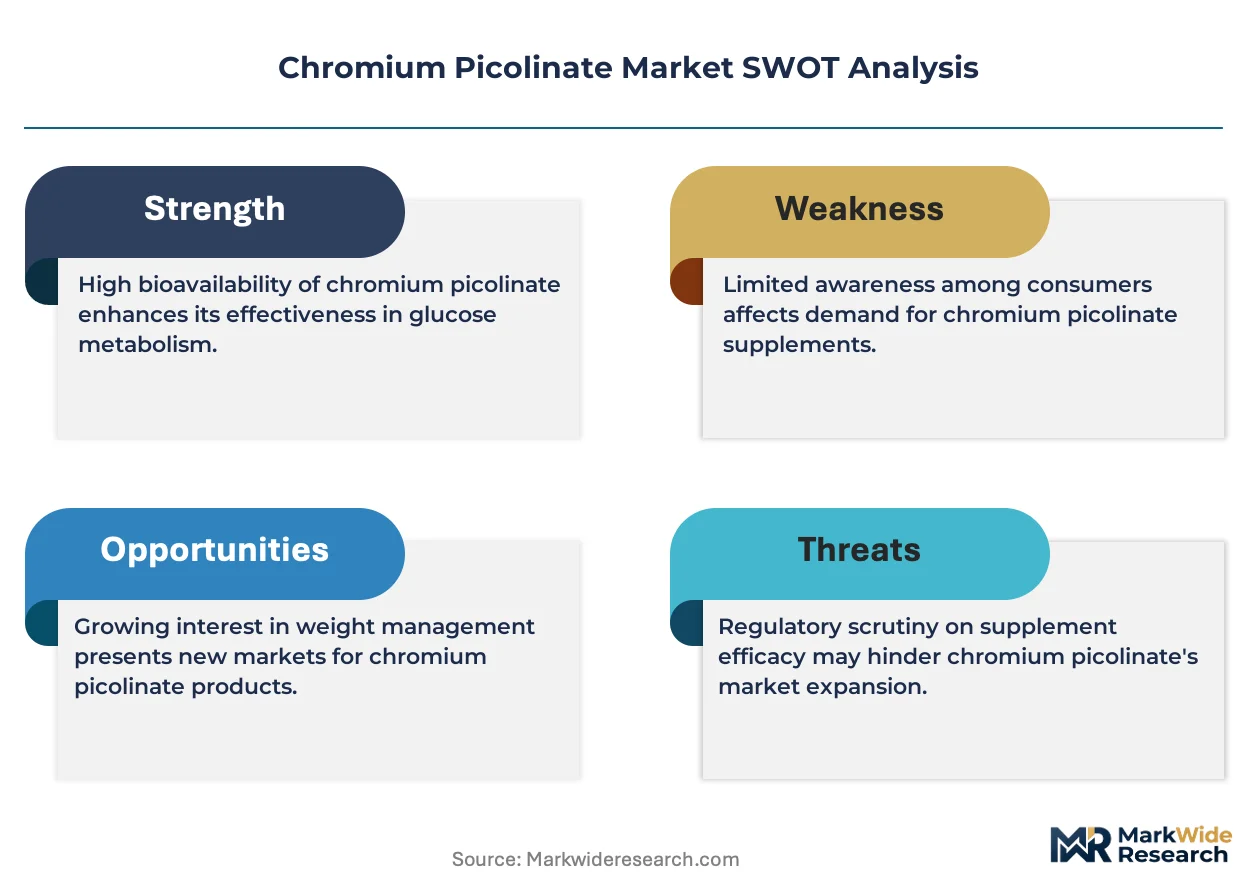
The US FDA's dietary supplement CGMP enforcement is compressing supplier margins while simultaneously elevating entry barriers for mineral chelate manufacturers seeking North American market access.
Growth Catalysts
- Metabolic health positioning:Functional food and beverage manufacturers are integrating chromium picolinate into positioned glucose management products targeting prediabetic consumers.
- CGMP compliance differentiation:The FDA's purity benchmark tightening creates competitive separation for suppliers with pharmaceutical-grade mineral chelation capabilities.
- India:CDSCO and FSSAI import verification requirements for mineral chelates are accelerating demand for certified suppliers with documented supply chain traceability.
Market Restraints
- Heavy metal input volatility:Chromium ore price fluctuations and EPA testing protocol compliance costs compress margins for non-integrated producers.
- Substitution threat from chromium nicotinate:Alternative trivalent chromium complexes with comparable bioavailability claims capture price-sensitive segments in sports nutrition.
- Regulatory friction from bioaccumulation surveillance:Pharmacovigilance data reassessment by EFSA and FDA creates uncertainty around acceptable daily intake thresholds for long-term supplementation.
Strategic Opportunities
- Underpenetrated clinical nutrition:Hospital and long-term care facilities in Germany and France represent untapped institutional procurement channels for practitioner-grade chromium picolinate.
- Custom compounding pharmacies:Powder format demand from compounding pharmacists creating margin-rich specialty distribution bypassing mass-market retail.
- Technology convergence:Combination formulations pairing chromium picolinate with berberine or alpha-lipoic acid are capturing metabolic health positioning in practitioner channels.
Industry Challenges
- Analytical chemistry skill scarcity:Mineral chelate characterization and heavy metal testing expertise shortages constrain quality control scaling for mid-tier suppliers.
- Certification timeline compression:Multi-jurisdiction CGMP, ISO 22000, and organic certification synchronization creates working capital intensity for export-oriented manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromium Picolinate Market |
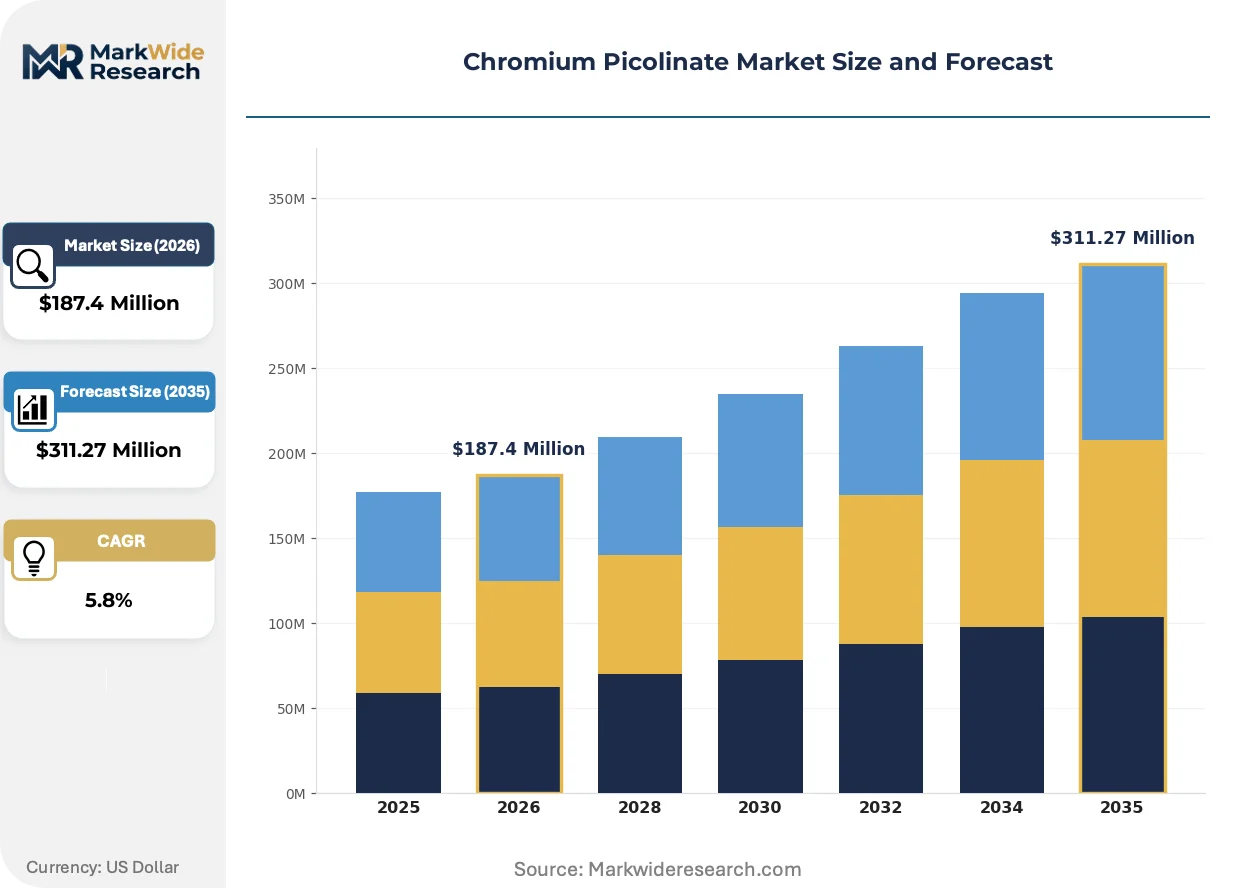
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Tablet, Liquid Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Animal Feed Distribution Channel: Online, Offline, Pharmacies, Health Stores End User: Health Conscious Individuals, Athletes, Patients, Fitness Enthusiasts |
| Companies Covered | Resonance Specialties Limited, Salvi Chemical Industries Limited, Oceanic Laboratories Pvt. Ltd., Lonza Group, Merck KGaA, Balchem Corporation, Nutrition 21, NOW Foods, Sabinsa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromium Picolinate Market Strategic Shifts
Formulation science and regulatory precision are converging to reshape how chromium picolinate suppliers differentiate beyond elemental content claims.
Microencapsulation technology using lipid or polymer matrices is electrifying stability profiles for chromium picolinate in functional beverages and heat-processed bars. Sports nutrition manufacturers in the United States and Australia are adopting these formats at accelerated procurement cycles. The technology is electrifying competitive positioning by enabling shelf-stable claims that liquid and standard powder formats cannot match.
REACH registration requirements for chromium compounds are elevating documentation burdens for European market entry. ECHA substance evaluation workflows now demand extensive toxicokinetic data for trivalent chromium complexes. Mineral ingredient suppliers are responding by consolidating European distribution through established REACH-compliant intermediaries rather than direct registration.
Direct-to-practitioner subscription models are displacing traditional wholesale distribution in clinical nutrition channels. Functional medicine practitioners in Canada and the United Kingdom are consolidating mineral supplement procurement through platform-based vendors offering patient compliance tracking. This channel shift is most visible in metabolic health protocols where dosing adherence monitoring justifies premium positioning.
Chromium Picolinate Market Segmentation
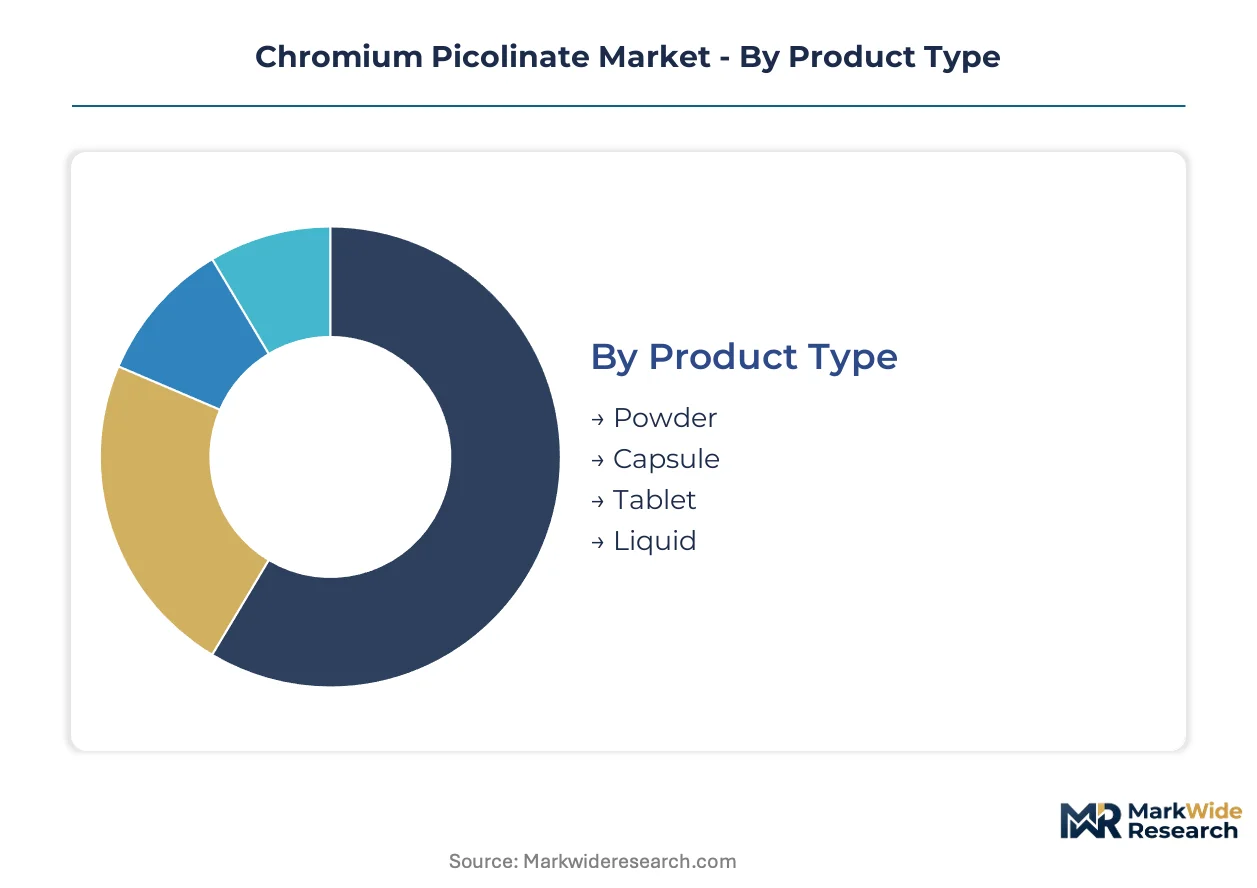
Segmentation in chromium picolinate reveals how capital deployment and regulatory compliance costs concentrate across manufacturing formats and channel structures. Product type selection dictates equipment investment, while application choice determines certification burden and margin profile.
Product Type:
Powder production demands the lowest capital intensity, while tablet and capsule manufacturing requires pharmaceutical-grade compression and encapsulation equipment.
- Tablet:Standardized to 200-1000 mcg elemental chromium with excipient matrices for dissolution control. Demand concentrates in North American retail pharmacy chains where FDA CGMP compliance certificates are mandatory for shelf placement. Compression tooling and coating equipment represent the highest fixed-cost barrier among solid formats.
- Capsule:Hard gelatin or vegetable cellulose shells containing 200-500 mcg standardized powder blends. Sports nutrition buyers in Australia and Canada prefer this format for stackability with other supplements. Two-piece encapsulation lines require cleanroom infrastructure but offer faster changeover between SKUs than tablet presses.
- Powder:Bulk 12.5% elemental chromium concentrate for custom compounding and sports nutrition blending. Lower equipment threshold attracts mid-tier suppliers, though analytical testing costs for heavy metal verification persist.
- Liquid:Aqueous suspensions with stabilizers for pediatric and geriatric compliance segments. Limited demand due to shorter shelf life and higher shipping weights.
Most installed capacity flows through Tablet. Expansion is steepest in Capsule.
Application:
Regulatory filing costs and clinical validation requirements create sharp tiering between pharmaceutical and nutraceutical applications.
- Dietary Supplements:Dominant volume channel with structure-function claims for glucose metabolism support. NOW Foods and Nutrition 21 compete through differentiated chelation technologies and label-claim substantiation.
- Functional Foods:Microencapsulated chromium picolinate integration into bars and beverages targets prediabetic positioning. Heat stability requirements drive lipid-matrix coating investments that exclude smaller suppliers.
- Pharmaceuticals:Prescription-grade mineral supplementation in clinical nutrition protocols. CDSCO and FDA IND filing costs restrict participation to Lonza Group and comparable pharmaceutical-grade manufacturers.
- Animal Feed:Trace mineral fortification for livestock metabolic efficiency. Lower purity thresholds and price sensitivity favor commodity-grade suppliers with captive chromium sourcing.
Dietary Supplements absorbs the majority of production volume. Functional Foods is climbing the fastest as beverage manufacturers seek metabolic health positioning.
Distribution Channel:
Customer acquisition economics and working capital intensity vary dramatically between direct-to-consumer platforms and brick-and-mortar retail.
- Online:Amazon and specialized supplement platforms capture fitness enthusiast and practitioner segments with subscription mechanics. Lower inventory carrying costs offset digital marketing spend.
- Offline:Mass-market retail through Walmart and Target requires slotting fees and promotional calendars that strain smaller suppliers.
- Pharmacies:CVS and Walgreens chains demand USP verification and insurance reimbursement coding for practitioner-recommended SKUs.
- Health Stores:GNC and Vitamin Shoppe specialize in sports nutrition stacks with trained staff consultation. Higher margins compensate for lower throughput.
Online channels now route the largest share of volume. Pharmacies show the steepest expansion trajectory as clinical nutrition protocols formalize.
End User:
Purchasing sophistication and price elasticity diverge sharply between clinical patients and self-directed fitness consumers.
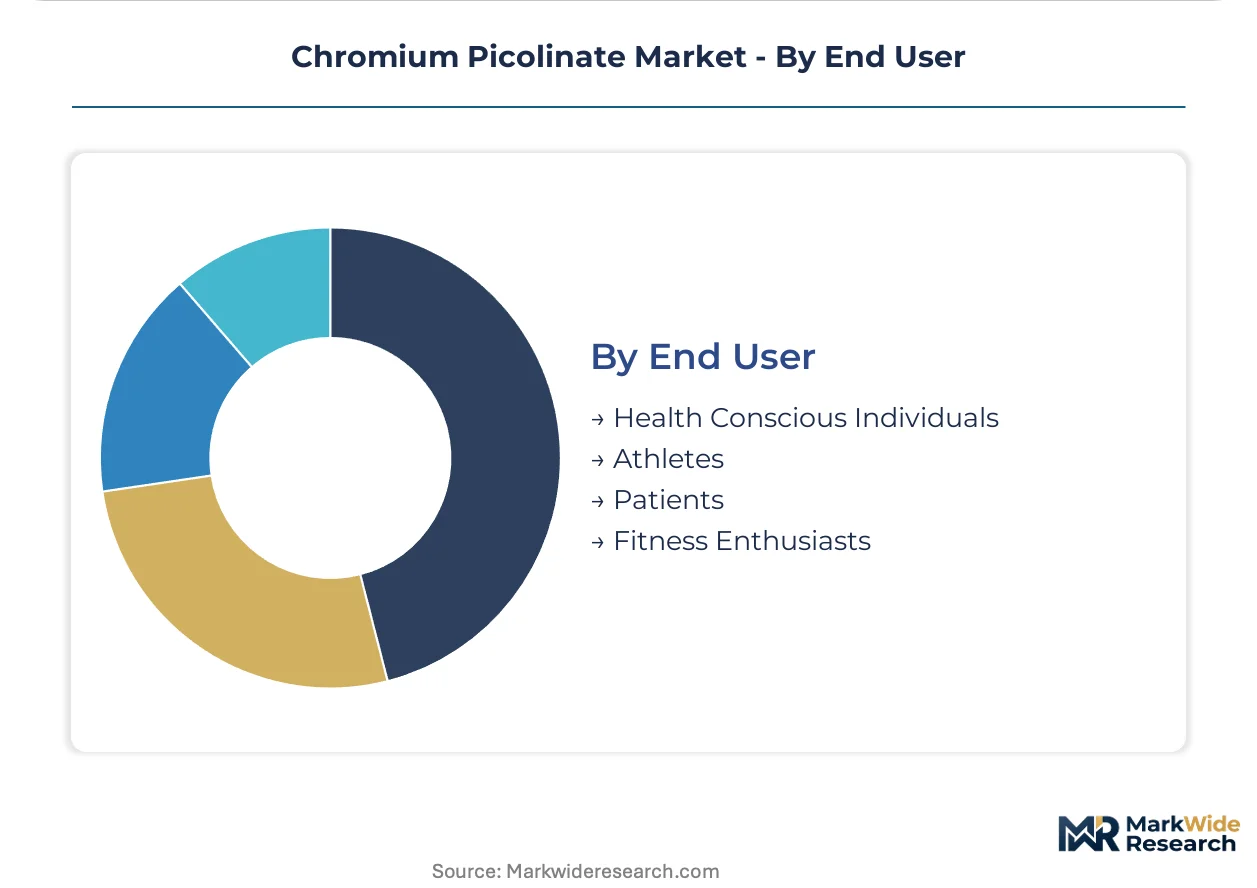
- Health Conscious Individuals:Prediabetic consumers seeking glucose management support through preventive supplementation. This segment drives functional food integration and practitioner-channel subscription growth.
- Athletes:Bodybuilders and endurance competitors stacking chromium picolinate with insulin-mimetic compounds for body composition goals. Australian and US sports nutrition manufacturers target this cohort with powder formats.
- Patients:Physician-supervised metabolic syndrome management in clinical nutrition settings. Insurance reimbursement and hospital formulary placement determine access.
- Fitness Enthusiasts:Recreational gym-goers purchasing through retail and online channels with lower dosing adherence and higher price sensitivity.
Health Conscious Individuals represents the largest addressable base. Athletes is gaining share fastest as sports nutrition formulation science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromium picolinate manufacturing originated in Swiss and German pharmaceutical corridors during the 1980s, with mineral chelation expertise later diffusing to North American and Asian production centers. The industry's geographic footprint now tracks regulatory stringency and practitioner-channel density across four primary markets.
United States
Sports nutrition manufacturers in Utah and California drive powder-format demand for body composition applications. The FDA's dietary supplement CGMP enforcement compresses margins for non-compliant suppliers while rewarding pharmaceutical-grade mineral chelators with practitioner-channel access. Lonza Group's Port Washington facility anchors North American pharmaceutical-grade production capacity.
Germany
Clinical nutrition protocols in Bavarian and North Rhine-Westphalian hospital networks generate institutional procurement demand for prescription-grade chromium picolinate. ECHA REACH registration requirements for chromium compounds elevate documentation burdens and consolidate European distribution through compliant intermediaries. Frankfurt's chemical logistics corridor handles bulk mineral chelate transshipment.
India
CDSCO and FSSAI import verification frameworks accelerate demand for certified suppliers with documented supply chain traceability into pharmaceutical and nutraceutical channels. Maharashtra and Gujarat host contract manufacturing clusters serving export markets with lower-cost aqueous chelation and spray-drying capacity. Mumbai's port infrastructure supports bulk mineral ingredient re-export.
Australia
TGA regulatory alignment with FDA purity benchmarks positions Australian manufacturers as compliant suppliers to Southeast Asian markets. Sports nutrition formulators in Sydney and Melbourne adopt microencapsulated chromium picolinate for shelf-stable beverage applications. The country's mineral testing laboratory density supports quality control scaling for mid-tier suppliers.
Chromium Picolinate Market Competitive Environment
The competitive structure tilts toward pharmaceutical-grade mineral chelation specialists with multi-jurisdiction certification portfolios. Tiered supplier segmentation separates FDA-cgmp certified manufacturers from commodity-grade producers serving animal feed and price-sensitive sports nutrition segments. Three strategic archetypes dominate: integrated pharmaceutical-grade suppliers with captive chromium sourcing, contract manufacturers with flexible format capabilities, and direct-to-consumer brands with vertical distribution control. Capacity expansion and technology licensing constitute the primary competitive moves, with microencapsulation IP transfers accelerating among functional food ingredient suppliers.
Within the pharmaceutical-grade tier, Lonza Group and Merck KGaA exemplify integrated mineral chelation specialists with practitioner-channel positioning. Nutrition 21 occupies a position as a clinical-validation-focused developer of patented chromium complexes. Among diversified contract manufacturers, Balchem Corporation and Sabinsa Corporation represent format-flexible suppliers serving multiple end-use segments. NOW Foods anchors the direct-to-consumer archetype with distribution scale advantages in North American retail and online channels. Resonance Specialties Limited and Salvi Chemical Industries Limited sit within the India-based export manufacturing tier serving price-sensitive global markets.
| Leading Market Players |
|---|
| Resonance Specialties Limited |
| Salvi Chemical Industries Limited |
| Oceanic Laboratories Pvt. Ltd. |
| Lonza Group |
| Merck KGaA |
| Balchem Corporation |
| Nutrition 21 |
| NOW Foods |
| Sabinsa Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive chromium sourcing by integrated pharmaceutical-grade manufacturers anchors both supply security and premium pricing power in practitioner channels. Lonza Group's backward integration into mineral chelation inputs insulates its Port Washington facility from ore price volatility while commanding FDA-cGMP certified price premiums that commodity-grade competitors cannot match.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, practitioner-certified, and commodity-grade levels separates Lonza and Merck KGaA from Nutrition 21 and NOW Foods. Price differentiation hinges on FDA-cGMP certification tier and elemental chromium purity verification, with pharmaceutical-grade suppliers capturing premiums through documented bioavailability claims. Cost compression in the commodity tier intensifies as Indian contract manufacturers absorb heavy metal testing burdens for export markets. Sports nutrition buyers in Australia and the United States exhibit the highest price sensitivity, while clinical procurement committees in German hospital networks prioritize certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Mumbai, and Sydney orchestrate hub-and-spoke patterns for mineral chelate transshipment. Manufacturing concentrates in Switzerland, Germany, and India, with Swiss and German facilities handling pharmaceutical-grade aqueous chelation and Indian clusters managing spray-drying capacity for bulk powder exports. Raw material feeds draw from South African chromium ore deposits, picolinic acid precursors from Chinese chemical manufacturers, and excipient matrices from European suppliers. Single-source vulnerability in picolinic acid inputs creates exposure to intermediate chemical trade restrictions. Distribution runs through REACH-registered European intermediaries, CDSCO-certified Indian exporters, and TGA-aligned Australian distributors serving Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in chromium picolinate rests on certification-driven premium tier migration as FDA-cGMP compliance costs filter out commodity competitors. Microencapsulation technology licensing and practitioner-channel subscription models offer parallel paths to pricing power.
For Market Incumbents: Anticipate chromium nicotinate substitution threats in sports nutrition by deepening backward integration into picolinic acid production and locking long-term ore offtake agreements. Pharmaceutical-grade manufacturers should reinforce practitioner-channel control through direct-to-clinic subscription platforms with patient compliance tracking, while commodity-grade suppliers face margin compression from EPA heavy metal testing protocol escalation. For New Entrants and Emerging Players: Microencapsulation IP for functional beverage heat stability offers entry into prediabetic positioning segments where established suppliers lack format expertise. Custom compounding pharmacies in Germany and France represent the most penetrable white-space channel, bypassing mass-market slotting fees through powder-format specialization. A go-to-market angle anchored on berberine-chromium combination formulations captures metabolic health protocol adoption in Canadian functional medicine practices. For Investors and Strategic Acquirers: Roll-up economics work for FDA-cGMP certified mid-tier manufacturers because regulatory compliance creates artificial scarcity in practitioner-channel supply. Long-term viability favors acquisition targets with documented REACH registration and captive chromium ore relationships rather than pure-play formulators. Watch EFSA pharmacovigilance reassessment on chromium bioaccumulation as the signal for potential daily intake threshold compression that would reshape addressable market scope.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables heat-stable functional beverage claims that liquid formats cannot match. |
| Backward Integration into Chromium Ore | Insulates pharmaceutical-grade suppliers from South African supply volatility. |
| Direct-to-Practitioner Subscription Platforms | Captures Canadian and UK functional medicine procurement consolidation. |
| CDSCO and FSSAI Certification Investment | Unlocks Indian pharmaceutical and nutraceutical channel access for exporters. |
| Berberine Combination Formulation Development | Targets metabolic health positioning in practitioner protocol adoption. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dietary supplement formulators, FDA regulatory consultants, hospital procurement managers, and mineral ingredient distributors with secondary validation. Sources included FDA cGMP inspection databases, ECHA REACH registration filings, CDSCO import approval records, and trade data from Indian chemical export registries. Bottom-up capacity modeling across tablet, capsule, and powder production lines triangulated against top-down demand estimates from sports nutrition and clinical nutrition channels.
Segment-weighting approaches distributed value across product type, application, and distribution channel dimensions, with additional modeling for microencapsulation technology adoption rates and practitioner-channel subscription penetration. CAGRs were derived from fitted growth curves applied to baseline volume data across the projection horizon. Industry-specific forecast inputs incorporated EPA heavy metal testing cost trajectories and EFSA pharmacovigilance monitoring timelines for chromium bioaccumulation reassessment.
The model holds under stable regulatory enforcement intensity; deviation in FDA cGMP audit frequency or EFSA daily intake threshold revision would shift volume and value trajectories. Forecasts reflect documented assumptions on certification timeline compression and ore price volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market