
 Postbiotic Supplements Market | 2026-2036
Postbiotic Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Postbiotic Supplements Market Analytics
Modular dosing formats is pivoting how consumers build personalized gut-health stacks. DSM-Firmenich leverages its biotech fermentation infrastructure to supply standardized postbiotic active compounds. Kerry Group Plc anchors its position through integrated formulation services that bridge ingredient supply and finished supplement production. Sabinsa Corporation specializes in Ayurveda-influenced postbiotic extracts targeting niche botanical-dietary crossover segments.
Postbiotic supplements contain non-viable microbial cells, cell wall fragments, or metabolites such as short-chain fatty acids, exopolysaccharides, and lipoteichoic acids that confer host health benefits without requiring live probiotic cultures. Manufacturers employ heat-inactivation, enzymatic treatment, or controlled fermentation termination to preserve bioactive integrity while ensuring shelf stability. Capsule formats dominate current revenue due to dosing precision and consumer familiarity, though gummies attract younger demographics seeking palatability. Online distribution channels expand fastest as direct-to-consumer brands bypass traditional retail markups, while health stores retain margin concentration through personalized consultation services.
The FDA oversees New Dietary Ingredient notifications and structure-function claim compliance, pressuring manufacturers to invest in clinical substantiation. EFSA's novel food authorization pathway in Europe demands comprehensive toxicology and bioavailability data, creating divergent market access timelines across jurisdictions. Japan's FOSHU system offers a functional claims certification that postbiotic suppliers increasingly pursue for premium positioning. Stakeholders must monitor evolving definitions of postbiotics versus probiotics across regulatory regimes to anticipate compliance cost shifts and label flexibility constraints.
Market Dynamics
FDA dietary supplement enforcement priorities are compressing label claim flexibility and forcing manufacturers toward clinical substantiation investments that reshape competitive economics.
Growth Catalysts
- Japan's FOSHU certification pathway:Functional claims authorization enables premium positioning for postbiotic suppliers targeting evidence-demanding consumers. Manufacturers pursuing this certification gain differentiated shelf access in Japanese health channels.
- Sports nutrition end-use expansion:Athlete recovery protocols increasingly incorporate gut-immune modulation through standardized postbiotic powders. Team nutritionists and performance coaches drive institutional procurement.
- Heat-inactivation processing advances:Controlled fermentation termination preserves bioactive integrity while eliminating cold-chain dependencies. This technology unlocks distribution reach into ambient retail environments.
Market Restraints
- EFSA novel food authorization costs:Comprehensive toxicology and bioavailability data requirements create multi-year market access timelines for European entry. Smaller manufacturers lack capital reserves for compliance.
- Fermentation substrate volatility:Agricultural input costs for specialized growth media fluctuate with commodity grain and dairy markets. Margin compression hits contract manufacturers hardest.
- Live probiotic substitution threat:Established refrigerated probiotic brands leverage consumer familiarity and lower price points. Refrigerated distribution infrastructure already exists for these incumbents.
Strategic Opportunities
- Pediatric formulation white space:Palatable gummy formats for children remain underdeveloped relative to adult capsules. Parents seeking immune support alternatives represent untapped demand.
- Direct-to-consumer channel innovation:Subscription models bypass traditional retail markups while capturing recurring revenue. Personalized gut-health stacks built through modular dosing attract digitally native buyers.
- Ayurveda-influenced botanical convergence:Traditional medicine frameworks offer regulatory familiarity in Indian and Southeast Asian markets. Extract standardization meets postbiotic bioactive preservation.
Industry Challenges
- Clinical trial design complexity:Postbiotic mechanism-of-action documentation requires distinct endpoints from live probiotic studies. Regulatory agencies lack harmonized guidance on biomarker selection.
- Cross-jurisdictional definition friction:Divergent postbiotic versus probiotic classifications across FDA, EFSA, and Japan's Consumer Affairs Agency create label reformulation burdens. Product registrations must be rebuilt per market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postbiotic Supplements Market |
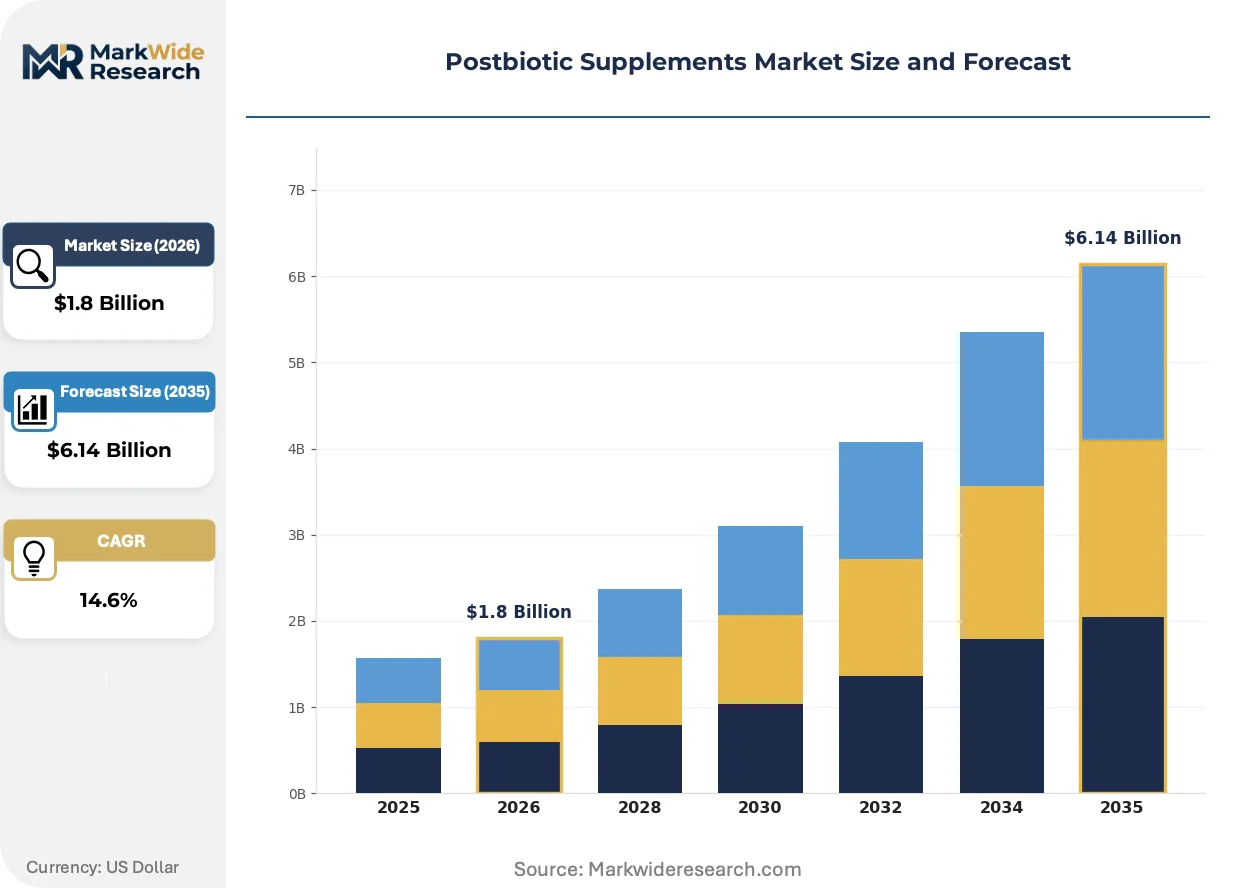
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Gummies, Liquids Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies End User: Adults, Children, Athletes, Seniors Formulation: Vegetarian, Vegan, Gluten-Free, Organic |
| Companies Covered | DSM-Firmenich, Cargill, Incorporated, Archer Daniels Midland (ADM), Kerry Group Plc, BASF SE, Sabinsa Corporation, Essential Formulas Incorporated, Beekeeper's Naturals Inc., Novozymes A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postbiotic Supplements Market Evolving Landscape
Manufacturing technology and regulatory interpretation are simultaneously evolving, compressing development cycles while expanding addressable consumer segments through format innovation.
Controlled fermentation termination is expanding into ambient-stable bioactive preservation. Sports nutrition brands adopt this technology fastest, eliminating refrigeration costs for athletic facility distribution. The structural consequence is geographic market expansion into regions lacking cold-chain infrastructure.
EFSA's evolving novel food guidance demands comprehensive toxicology datasets for postbiotic metabolite authorization. European manufacturers face extended approval timelines compared to probiotic legacy products. Capsule-format suppliers absorb the highest compliance burden as they target pharmacy channels requiring full authorization.
Modular dosing formats are reshaping how consumers assemble personalized regimens. Direct-to-consumer brands displace one-size-fits-all SKUs with stackable powders and capsules. United States functional food startups lead this behavioral shift, using online quizzes to configure individualized protocols.
Postbiotic Supplements Market Segmentation
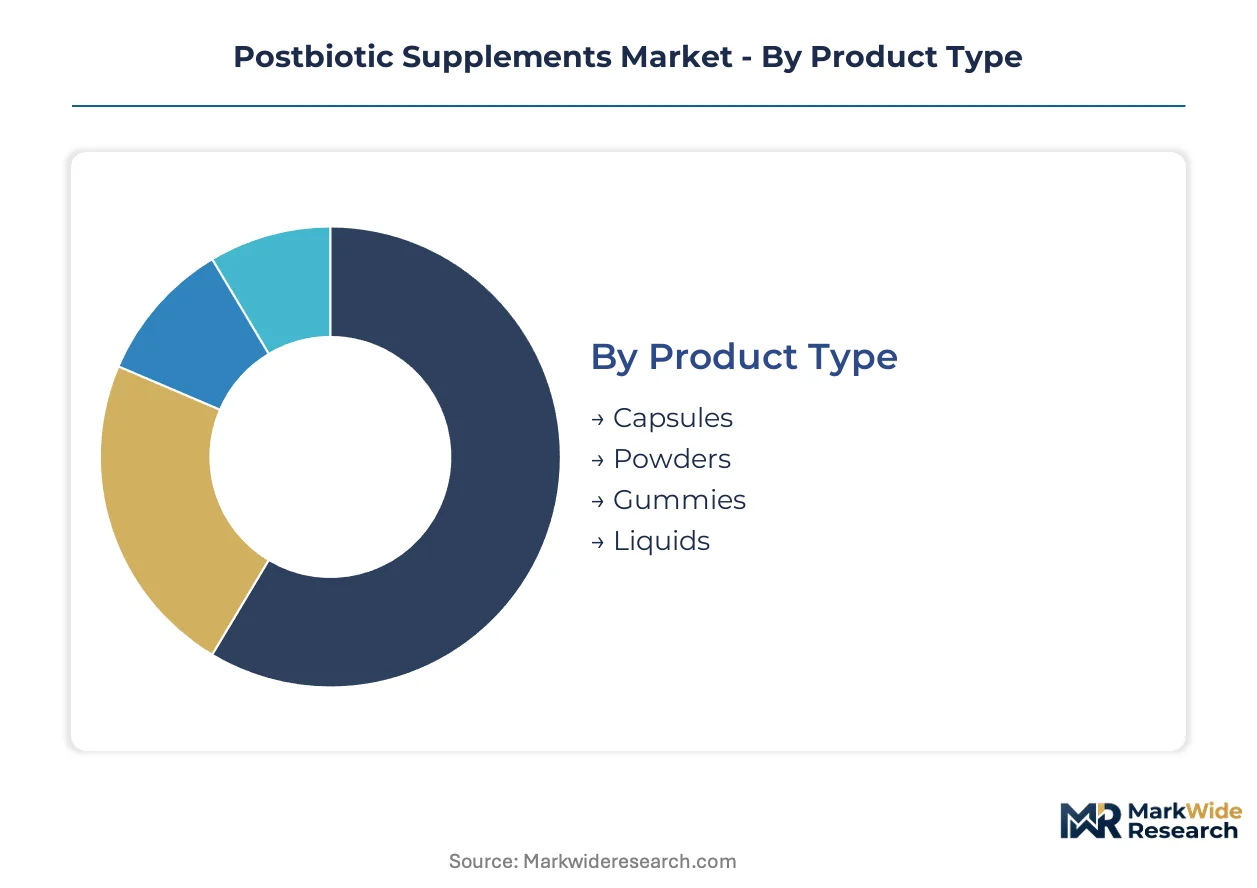
Postbiotic supplements fragment across four distinct category axes, each shaping manufacturing investment and channel strategy differently. Product format dictates processing technology and shelf-stability requirements. Distribution channel determines margin structure and consumer education burden. Understanding these intersections reveals where standardization yields scale versus where customization commands premium positioning.
Product Type:
Heat-inactivation and controlled fermentation termination technologies determine which formats achieve ambient stability without bioactive degradation.
- Capsules:Gelatin and vegetable-based shells deliver precise dosing of heat-inactivated microbial cells and metabolite concentrates. Sports nutrition procurement teams favor capsules for institutional athletic programs where dosing accuracy supports recovery protocols. Cold-chain elimination expands distribution into ambient retail environments previously inaccessible to live probiotics.
- Powders:Bulk postbiotic concentrates blend into protein formulations and functional beverages, requiring moisture-resistant packaging to preserve short-chain fatty acid integrity. Direct-to-consumer brands stack powders with other gut-health ingredients, capturing subscription revenue through personalized protocol configuration.
- Gummies:Palatable chewable formats incorporate exopolysaccharides into pectin or gelatin matrices, attracting younger demographics and parental purchasers seeking immune support alternatives for children.
- Liquids:Ready-to-drink formulations concentrate lipoteichoic acids and cell wall fragments into suspension, demanding preservative systems and aseptic filling lines that elevate unit economics.
Capsules lead on scale; powders lead on momentum.
Distribution Channel:
Channel selection determines regulatory exposure and consumer touchpoint intensity, with divergent margin structures across digital and physical retail.
- Online:Direct-to-consumer platforms bypass traditional retail markups while capturing recurring subscription revenue. Functional food startups leverage quiz-based personalization to configure modular gut-health stacks, building customer lifetime value through data-driven protocol adjustments.
- Supermarkets:Mass-market placement demands price competitiveness and simplified label claims that withstand FDA scrutiny without consultation support. Shelf-stable formats dominate as refrigeration infrastructure remains inconsistent across store footprints.
- Health Stores:Personalized consultation services justify premium positioning and complex ingredient storytelling. Staff training investments convert browsing into purchase for consumers comparing postbiotic mechanisms against live probiotic alternatives.
- Pharmacies:Clinical credibility requirements elevate substantiation burdens, with structure-function claims facing heightened pharmacist scrutiny. EFSA novel food authorization becomes prerequisite for European pharmacy channel entry.
Online channels expand most quickly; health stores concentrate margin.
End User:
Physiological life stage and activity level shape bioactive targeting, dosing protocols, and palatability requirements across distinct consumer cohorts.
- Adults:General wellness seekers drive baseline volume through familiar capsule formats and standardized metabolite blends. Workplace stress and digestive comfort positioning dominate marketing without requiring specialized clinical endpoints.
- Children:Pediatric immune support represents formulation white space where palatable gummy formats remain underdeveloped relative to adult offerings. Parental demand for alternatives to pharmaceutical interventions creates premium pricing tolerance.
- Athletes:Gut-immune recovery protocols institutionalize postbiotic adoption through team nutritionist procurement. Heat-inactivated powders integrate into existing supplement regimens without refrigeration logistics burdening athletic facilities.
- Seniors:Age-related microbiome degradation and medication interaction concerns drive demand for bioactive standardization and third-party testing transparency. Capsule formats accommodate swallowing difficulties through smaller sizing or liquid-filled alternatives.
Adults anchor volume; athletes drive steepest expansion trajectory.
Formulation:
Clean-label positioning and dietary restriction accommodation differentiate SKUs within crowded shelf environments, with certification costs varying by claim stringency.
- Vegetarian:Gelatin-free capsule shells and dairy-free fermentation substrates accommodate lacto-ovo dietary patterns without requiring full vegan supply chain segregation.
- Vegan:Plant-derived growth media and non-animal capsule materials command certification premiums from ethically motivated consumers, with fermentation substrate traceability demanding supplier documentation.
- Gluten-Free:Grain-free substrate validation prevents cross-contamination for celiac and sensitivity populations, with third-party testing becoming table stakes for credibility.
- Organic:Certified organic fermentation inputs and processing aids attract premium health channel placement, with USDA and equivalent international certifications gating access to specific retailer sets.
Vegetarian formulations dominate unit volume; vegan claims gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Postbiotic supplementation emerged from Japanese fermentation science and European dairy research traditions before scaling through North American functional food commercialization. The industry now distributes across distinct regulatory environments that shape product authorization timelines and label claim flexibility. Each major market presents unique compliance architectures and consumer education challenges.
United States
Sports nutrition procurement teams drive institutional adoption through heat-inactivated powders for athletic recovery protocols. FDA structure-function claim enforcement pressures manufacturers toward clinical substantiation investments. Utah and California host the densest clusters of direct-to-consumer brands configuring personalized gut-health stacks through online subscription platforms.
Japan
FOSHU certification creates premium positioning for postbiotic suppliers targeting evidence-demanding consumers in aging demographics. Consumer Affairs Agency functional claims authorization demands rigorous bioavailability documentation. Tokyo and Osaka metropolitan areas concentrate retail pharmacy distribution where certified products command shelf preference.
Germany
Pharmacy channel credibility requirements elevate substantiation burdens for capsule-format suppliers targeting clinical positioning. EFSA novel food authorization timelines extend market entry compared to probiotic legacy products. Bavaria anchors fermentation biotechnology infrastructure supplying standardized active compounds across European markets.
India
Ayurveda-influenced botanical convergence creates regulatory familiarity for traditional medicine frameworks in postbiotic extract development. FSSAI novel ingredient notifications proceed faster than EFSA pathways though still demand safety documentation. Maharashtra and Gujarat concentrate contract manufacturing capacity serving domestic and export markets.
Australia
TGA complementary medicine regulations permit listed medicine pathways for postbiotics with established safety profiles, accelerating market access relative to novel food jurisdictions. Sports nutrition demand from professional athletic programs mirrors North American adoption patterns. Sydney and Melbourne host formulation service providers bridging ingredient import and finished product distribution.
Postbiotic Supplements Market Competitive Landscape
The competitive structure tilts toward diversified ingredient conglomerates with fermentation infrastructure rather than pure-play specialists. Tiered positioning separates premium clinical-grade suppliers from mass-market commodity producers. Two strategic archetypes dominate: integrated biotech-nutrition hybrids controlling upstream fermentation capacity, and formulation-service intermediaries bridging ingredient supply and finished goods. Capacity expansion and portfolio diversification through M&A represent the dominant competitive moves as players seek vertical scope.
Among integrated biotechnology conglomerates, DSM-Firmenich and BASF SE exemplify archetypes leveraging captive fermentation infrastructure to supply standardized postbiotic actives. Kerry Group Plc occupies a position within the formulation-service tier, bridging ingredient procurement and finished supplement production. Sabinsa Corporation represents the botanical-dietary crossover specialist archetype, anchoring Ayurveda-influenced extract development for niche premium segments.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Cargill, Incorporated |
| Archer Daniels Midland (ADM) |
| Kerry Group Plc |
| BASF SE |
| Sabinsa Corporation |
| Essential Formulas Incorporated |
| Beekeeper's Naturals Inc. |
| Novozymes A/S |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fermentation specialists concentrated in Bavaria and Gujarat anchor upstream supply, translating captive substrate access into pricing discipline that resists commodity volatility. Their ownership structure prioritizes long-term customer contracts over spot-market maximization, compressing margin variance across tiered buyer segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and bioactive standardization precision. FOSHU-certified Japanese products command the widest premiums, while mass-market capsules face cost compression from live probiotic substitution. Athletic procurement teams show lowest price sensitivity, prioritizing dosing accuracy and ambient stability over per-unit cost.
Supply Chain Analysis
Domestic-content mandates in India and evolving FDA traceability requirements are reshaping sourcing toward verified fermentation substrate provenance. Supply concentrates in Germany, India, and Japan, drawing from specialized growth media, pharmaceutical-grade capsule shells, and standardized metabolite concentrates. Single-source vulnerability in heat-inactivation equipment creates chokepoint exposure. Distribution runs through direct-to-consumer platforms fastest, though health stores retain margin concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postbiotic supplementation has matured into a late-cycle quality story where athlete recovery protocols and pediatric immune support now demand clinical-grade substantiation over commodity positioning.
For Market Incumbents: Deploy backward integration into captive fermentation infrastructure to defend against DSM-Firmenich and Kerry Group capacity advantages. Secure FOSHU or EFSA novel food authorizations ahead of label claim enforcement tightening. Absorb margin compression from live probiotic substitution through subscription-model customer lifetime value capture. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel wedge, bypassing retail markup structures that favor established distributors. Target pediatric gummy formulation white space where palatability requirements create barrier-to-entry protection. Pursue Ayurveda-influenced botanical convergence for regulatory familiarity in Indian and Southeast Asian markets. For Investors and Strategic Acquirers: Valuations sit cheapest among formulation-service intermediaries lacking captive fermentation assets but possessing health store channel relationships. Five-to-ten-year viability hinges on clinical substantiation depth rather than ingredient commodity scale. Monitor EFSA novel food authorization timelines as the critical inflection signal for European market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FOSHU Certification Pursuit | Japan's Consumer Affairs Agency authorization unlocks premium pharmacy shelf positioning and functional claims flexibility. |
| Heat-Inactivation Capacity Expansion | Ambient-stable processing eliminates cold-chain dependency, expanding distribution into athletic facility and mass retail environments. |
| Pediatric Gummy Format Development | Palatable exopolysaccharide matrices address immune support demand from parents seeking alternatives to pharmaceutical interventions. |
| Direct-to-Consumer Subscription Launch | Quiz-based personalization captures recurring revenue while building data-driven protocol adjustment capabilities. |
| Ayurveda-Botanical Convergence R&D | Traditional medicine frameworks accelerate regulatory familiarity in FSSAI-governed Indian and Southeast Asian markets. |
Research Methodology
Direct dialogue with fermentation technology directors, sports nutrition procurement managers, regulatory affairs specialists at supplement brands, and health store category buyers grounded qualitative findings. Secondary validation drew from FDA New Dietary Ingredient notifications, EFSA novel food submission databases, FOSHU certification registries, and Japanese Consumer Affairs Agency functional claims listings. Bottom-up SKU-level analysis triangulated against top-down category spend estimates.
Segment-level value outputs calibrated across product format, distribution channel, end-user physiology, and formulation certification dimensions over the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory authorization timeline risk and channel shift elasticity. Forecast inputs incorporated heat-inactivation technology adoption curves, FOSHU certification pursuit rates, and direct-to-consumer subscription penetration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA guidance evolution, FDA structure-function enforcement intensity, and fermentation substrate commodity volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Red Ginseng Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
Energy Supplements Market