
 Dhea Supplement Market | 2026-2036
Dhea Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Dhea Supplement Market Analytics
Asset-light contract manufacturing and white-label financing is rewriting competitive entry economics for DHEA supplement brands. Nutricost leverages e-commerce-native distribution to sustain price-competitive positioning across multiple online retail platforms. Life Extension anchors its market presence through vertically integrated quality control from raw material sourcing to finished capsule production. Pure Encapsulations differentiates via pharmaceutical-grade manufacturing standards that command premium placement in specialty stores and practitioner channels.
Dehydroepiandrosterone (DHEA) is a naturally occurring steroid hormone produced primarily in the adrenal glands, commercially synthesized through microbial fermentation or chemical extraction for oral supplementation in 25-50 milligram standardized doses. Manufacturers formulate DHEA into capsules, tablets, and powders to support endocrine balance, metabolic function, and age-related hormone decline management in wellness and clinical applications. Capsule formulations dominate current volume due to dosing precision and consumer convenience, while powder segments capture growing demand from compounding pharmacies and personalized protocol practitioners. The aging population end-user segment generates the highest per-customer lifetime value, though fitness enthusiasts and bodybuilders drive more frequent repurchase cycles through online retail channels.
The FDA's Dietary Supplement Health and Education Act (DSHEA) framework and New Dietary Ingredient notification requirements govern market access, while the FTC monitors advertising claims for hormone-related efficacy statements. ISO 17025 laboratory accreditation and USP verification programs increasingly serve as de facto quality gatekeepers for retail pharmacy placement and clinician recommendation. Stakeholders must monitor evolving state-level age-restriction legislation and international customs classification disputes that could reshape cross-border e-commerce fulfillment models.
Market Dynamics
The FDA's New Dietary Ingredient notification requirements are compressing product entry timelines and forcing reformulation strategies across the DHEA supplement landscape. Contract manufacturers now absorb disproportionate compliance burden, reshaping competitive economics toward asset-light brand operators.
Growth Catalysts
- Longevity clinic protocols:Anti-aging wellness programs in the United States integrate DHEA into hormone optimization stacks, creating institutional demand pull-through.
- DSHEA framework maturity:The Dietary Supplement Health and Education Act's established compliance pathways reduce regulatory uncertainty for domestic manufacturers.
- Microbial fermentation synthesis:Biotechnological production methods are lowering raw material costs and improving batch-to-batch steroid purity consistency.
Market Restraints
- Wild yam extract supply concentration:Precursor chemical sourcing clusters in specific subtropical growing regions, exposing formulators to climatic volatility.
- State-level age restrictions:Variable legislation across US jurisdictions creates fulfillment complexity for direct-to-consumer channels.
- Endocrine disruption liability:Hormone-related adverse event litigation risk elevates product liability insurance premiums above standard dietary supplement benchmarks.
Strategic Opportunities
- Compounding pharmacy partnerships:Custom dosage protocols for personalized medicine practitioners open premium pricing corridors outside mass retail.
- USP verification differentiation:Third-party quality certification programs enable placement in clinician-recommendation networks and hospital outpatient dispensaries.
- Subscription model integration:Auto-replenishment platforms capture recurring revenue from aging population segments managing chronic hormone protocols.
Industry Challenges
- ISO 17025 laboratory accreditation timelines:Analytical method validation for steroid quantification extends quality control setup by 12-18 months for new entrants.
- Cross-border customs classification disputes:Inconsistent harmonized system coding for steroid-derived supplements triggers seizure risk in international e-commerce fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dhea Supplement Market |
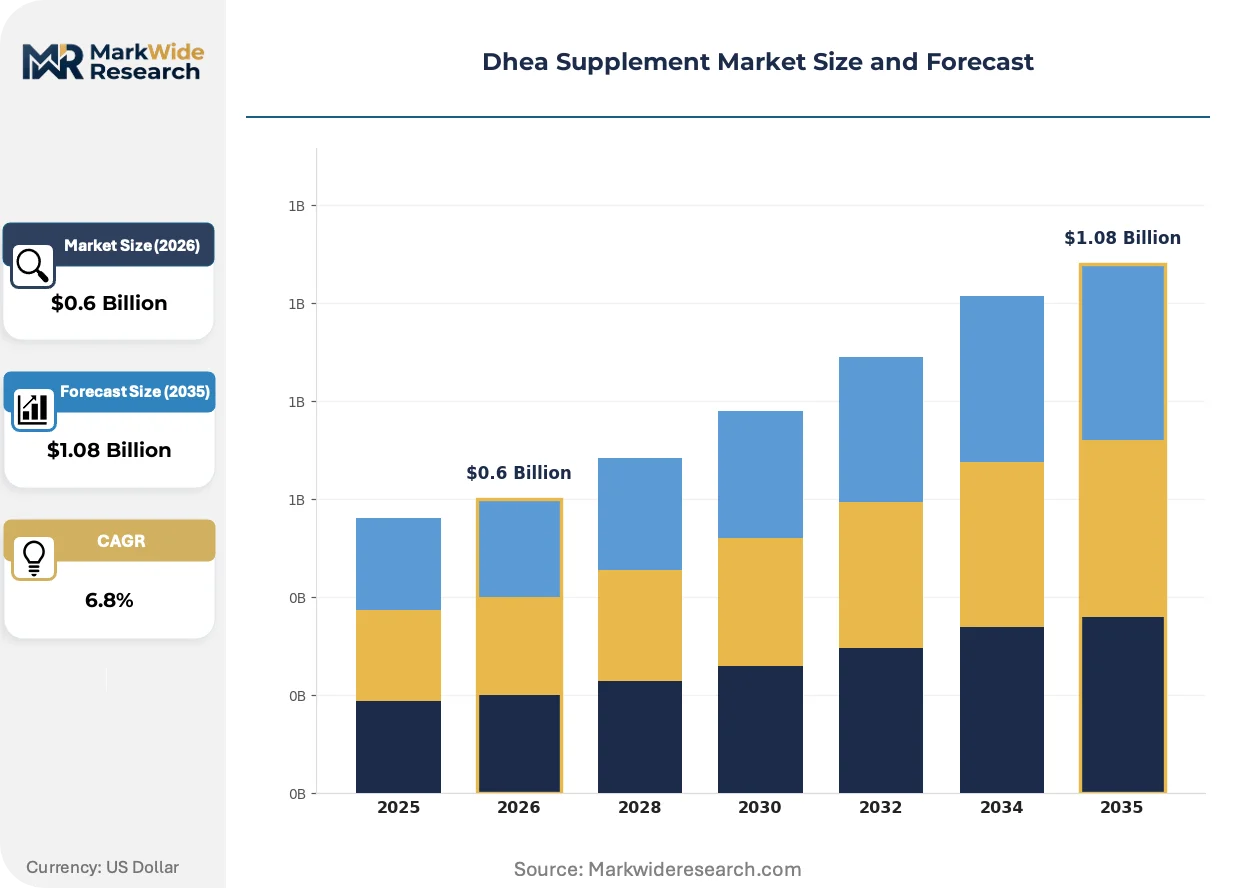
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powders, Liquids End User: Fitness Enthusiasts, Aging Population, Bodybuilders, Health Conscious Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Formulation: Organic, Synthetic, Vegan, Non-GMO |
| Companies Covered | Acetar Bio-Tech, Douglas Laboratories, Life Extension, Nutricost, Designs for Health, Pure Encapsulations, Shaanxi Fuheng (FH) Biotechnology, Vitacost, Schiff Vitamins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dhea Supplement Market Evolving Landscape
Formulation science and distribution architecture are undergoing parallel transformation. Manufacturers confront pressure to differentiate through delivery mechanism innovation while channel structures fragment between practitioner-directed and self-directed purchase pathways.
Microencapsulation technology is migrating from pharmaceutical applications into nutraceutical DHEA production, enabling enteric-coated release profiles that bypass first-pass hepatic metabolism. Compounding pharmacies in the United States are adopting these modified-release formats for bioavailability-optimized protocols. The shift is compressing margins on conventional immediate-release capsules while creating specialty manufacturing partnerships.
The FTC's intensified scrutiny of hormone-related efficacy claims is forcing advertising compliance restructuring across the supplement sector. Marketing copy now undergoes legal review cycles that extend campaign launch timelines by 30-60 days. Direct-to-consumer brands with heavy digital advertising exposure are most affected, pivoting toward educational content frameworks that avoid specific outcome promises.
Practitioner channel consolidation is displacing fragmented retail distribution as the primary volume pathway for premium-grade DHEA. Functional medicine clinics and integrative health networks now coordinate group purchasing agreements that bypass traditional wholesale intermediaries. This concentration is most visible in California, Texas, and Florida metropolitan corridors where anti-aging medicine practice density exceeds national averages.
Dhea Supplement Market Segmentation
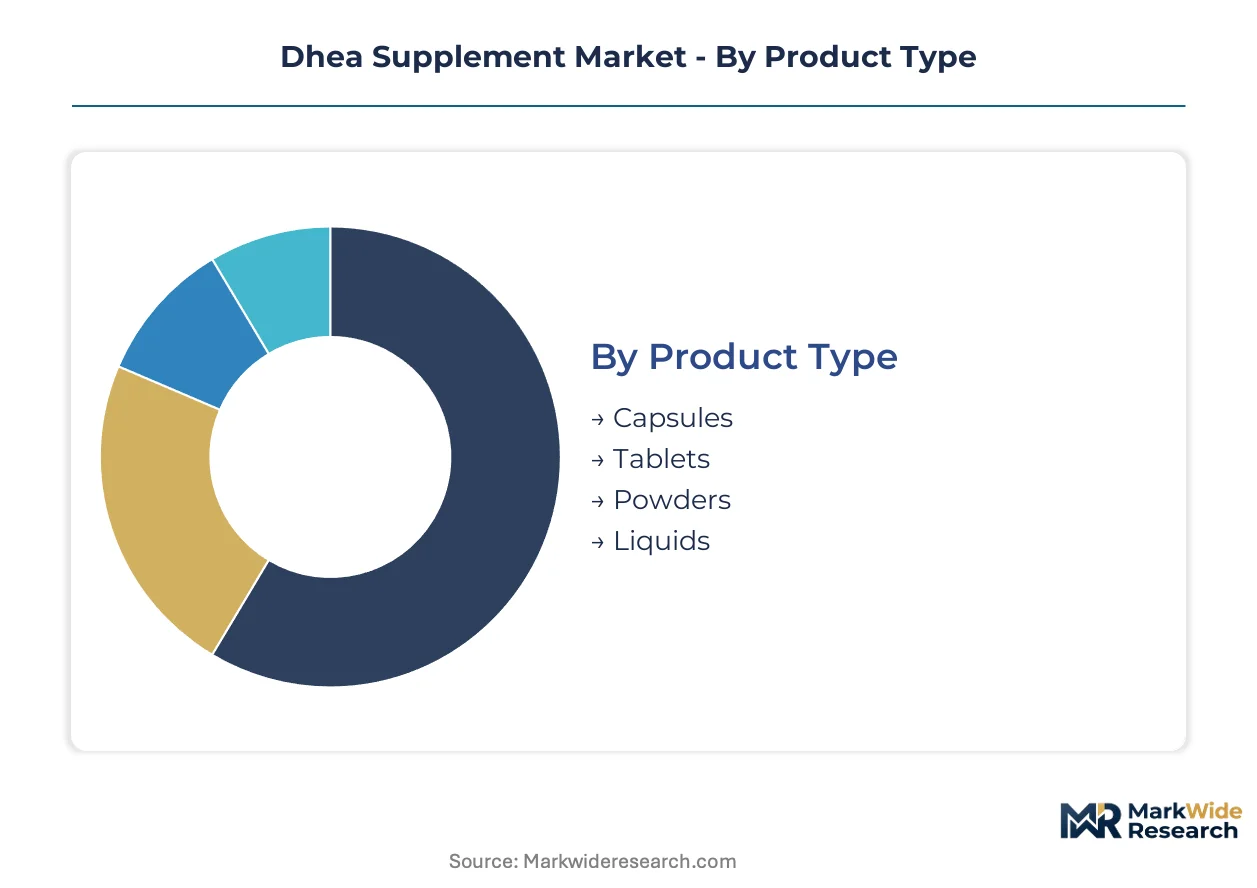
DHEA supplement purchasing patterns diverge sharply across delivery formats and buyer psychographics. Manufacturers configure production lines and inventory strategies around these structural differences in consumption velocity and margin profile.
Product Type:
Capsule formulations turn inventory fastest through practitioner channels, while powder formats sit longest in compounding pharmacy workflows. Liquids and tablets occupy intermediate velocity positions with distinct seasonal patterns.
- Capsules:Gelatin or vegetable-based shells deliver precise 25-50 milligram dosing with minimal oxidation exposure. Anti-aging clinics in the United States specify capsules for protocol standardization, driving institutional procurement contracts. The format dominates direct-to-consumer subscriptions due to portability and shelf stability.
- Tablets:Compressed formulations enable higher-density packaging and lower per-unit shipping costs. Fitness enthusiasts repurchase tablets most frequently through online retail channels for cost-optimized hormone support stacks.
- Powders:Bulk formats serve compounding pharmacies requiring custom dosage flexibility for personalized medicine protocols.
- Liquids:Sublingual and oral suspension formats target consumers with swallowing difficulties or rapid absorption preferences.
Capsules anchor the volume base while powders gain share at the steepest rate through practitioner channel expansion.
End User:
Customer lifetime value spreads across a fourfold range, with protocol adherence duration varying by user motivation type. Acquisition cost and repurchase frequency invert across demographic segments.
- Fitness Enthusiasts:Gym-oriented consumers integrate DHEA into peri-workout supplementation stacks. Repurchase cycles compress to 30-45 days through subscription platforms.
- Aging Population:Hormone optimization protocols for individuals over 50 generate the highest per-customer lifetime value. Functional medicine practitioners in California, Texas, and Florida metropolitan corridors drive concentrated demand.
- Bodybuilders:Competitive physique athletes pursue supraphysiological dosing strategies through underground sourcing channels, limiting legitimate market capture.
- Health Conscious Consumers:Preventive wellness adopters demonstrate sporadic trial behavior with limited protocol adherence.
The aging population generates the revenue foundation while fitness enthusiasts deliver the most predictable replenishment cadence.
Distribution Channel:
Channel economics separate by credential requirements and fulfillment infrastructure intensity. Margin structures diverge based on intermediary layer count and regulatory scrutiny exposure.
- Online Retail:Direct-to-consumer platforms capture the majority of volume through Amazon, iHerb, and brand-native storefronts. Nutricost and similar e-commerce-native operators dominate price-competitive positioning.
- Specialty Stores:Vitamin Shoppe and GNC locations serve as discovery channels for new supplement adopters with higher staff-assisted conversion rates.
- Supermarkets:Mass retail placement remains limited due to hormone-related stocking hesitancy among grocery category managers.
- Pharmacies:CVS and Walgreens shelf space concentrates in USP-verified product lines with clinician recommendation backing.
Online retail commands the volume base while pharmacies expand most quickly through verification program adoption.
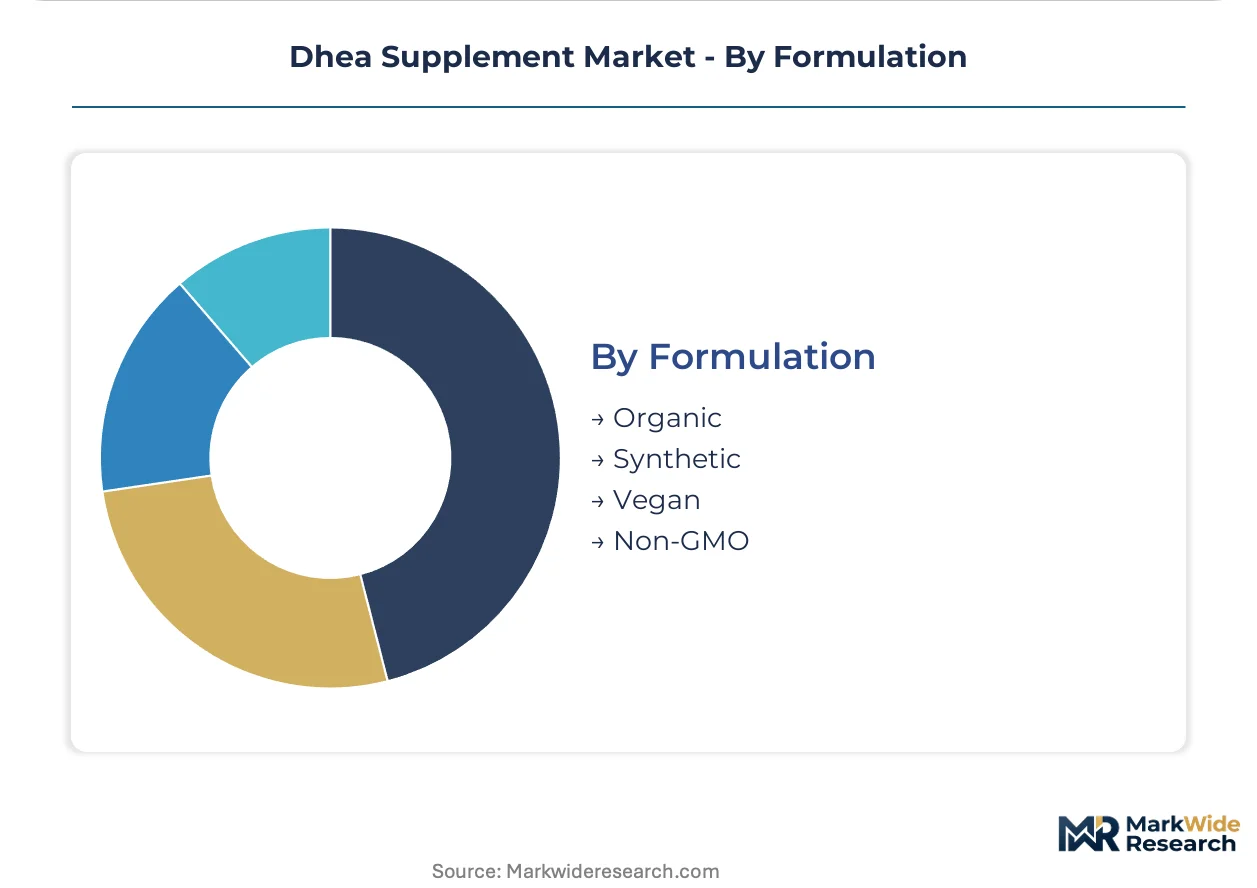
Formulation:
Ingredient sourcing claims structure price positioning across three distinct certification tiers. Manufacturing complexity and raw material cost differentials separate premium from standard positioning.
- Organic:Wild yam-derived precursors from certified organic growing regions command 40-60% price premiums. Supply concentrates in specific subtropical climatic zones with harvest volatility exposure.
- Synthetic:Microbial fermentation production delivers batch-to-batch purity consistency at scale. Life Extension and Pure Encapsulations anchor market presence through vertically integrated synthetic manufacturing.
- Vegan:Plant-based capsule excipients and fermentation-derived actives target ethical consumption segments with allergen exclusion requirements.
- Non-GMO:Identity-preserved supply chains satisfy European export requirements and US consumer skepticism toward biotechnology.
Synthetic formulations anchor the volume base while organic certification gains share fastest through premium wellness channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States distribution channels while European markets absorb compliance-driven cost premiums. Regulatory fragmentation across jurisdictions fragments procurement strategies for multinational supplement brands.
United States
Anti-aging clinics in California, Texas, and Florida metropolitan corridors drive institutional procurement volume for hormone optimization protocols. FDA DSHEA framework and New Dietary Ingredient notification requirements govern domestic manufacturing compliance pathways. Direct-to-consumer e-commerce platforms in these states capture the majority of subscription-based replenishment revenue.
Germany
Pharmacy-dispensed supplement protocols generate premium pricing corridors for USP-verified and pharmaceutical-grade formulations. BfArM and EFSA regulatory coordination shapes import documentation requirements for steroid-derived ingredients. Industrial clusters in Bavaria and Baden-Württemberg host contract manufacturing facilities serving Central European practitioner networks.
Japan
Aging demographic concentration in Tokyo and Osaka metropolitan areas sustains demand for endocrine balance supplementation. PMDA and Ministry of Health, Labour and Welfare oversight requires pre-market notification for hormone-containing products. Kanto region distribution infrastructure channels volume through pharmacy and clinic networks with strict quality verification protocols.
Australia
TGA scheduling restrictions classify DHEA as prescription-only, limiting direct-to-consumer channel development. Compounding pharmacy networks in New South Wales and Victoria serve personalized medicine practitioners with custom dosage formulations. Import permit requirements create fulfillment complexity for cross-border e-commerce operators.
United Kingdom
MHRA borderline classification disputes create regulatory uncertainty for hormone supplement positioning. London and Southeast England wellness clinics drive demand for premium-grade practitioner-channel products. Post-Brexit customs procedures complicate EU-sourced raw material supply chains for domestic formulators.
Dhea Supplement Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation technology. The vendor base separates between asset-light brand operators and vertically integrated manufacturers with captive raw material supply. Three archetypes dominate: e-commerce-native price competitors, pharmaceutical-grade quality anchors, and practitioner-channel specialists. Consolidation pressure favors M&A activity among mid-tier contract manufacturers, while geographic expansion into compounding pharmacy networks represents the second dominant competitive vector.
Among US-based quality anchors, Life Extension and Pure Encapsulations exemplify pharmaceutical-grade manufacturing archetypes with vertically controlled production pipelines. Nutricost occupies a position within the e-commerce-native tier, leveraging platform distribution economics for price-competitive positioning. These three entities represent the structural poles around which competitive strategy organizes: quality certification differentiation, manufacturing integration depth, and digital-native cost structure.
| Leading Market Players |
|---|
| Acetar Bio-Tech |
| Douglas Laboratories |
| Life Extension |
| Nutricost |
| Designs for Health |
| Pure Encapsulations |
| Shaanxi Fuheng (FH) Biotechnology |
| Vitacost |
| Schiff Vitamins |
| Others |
Value Network & Pricing Analysis
Los Angeles-Long Beach port congestion surcharges ripple through DHEA import economics, amplifying cost differentials between wild yam-derived precursors from subtropical zones and microbial fermentation outputs from controlled bioreactor facilities. These freight dynamics compress margins on organic-certified formulations while reinforcing pricing power for synthetic producers with captive domestic manufacturing.
Pricing Analysis
The customization-premium spread separates compounding pharmacy protocols from mass-market capsules by a factor of three to five, with bespoke dosage formulations commanding sustained margin premiums. Three-tier pricing structure across premium, standard, and economy levels reflects USP verification status and practitioner channel placement. Cost compression in the economy tier intensifies because Nutricost and e-commerce-native operators leverage platform scale for procurement leverage. Fitness enthusiasts demonstrate highest price sensitivity through subscription platform comparison shopping, while aging population segments in California and Florida metropolitan corridors exhibit lowest sensitivity due to protocol adherence incentives.
Supply Chain Analysis
Contract manufacturing concentration sits with Shaanxi Fuheng Biotechnology and Acetar Bio-Tech holding dominant fermentation capacity in China, while Douglas Laboratories and Pure Encapsulations anchor North American pharmaceutical-grade production. Raw material dependencies center on wild yam diosgenin from Mexico and China, microbial culture media, and gelatin or vegetable-derived capsule excipients. Single-source vulnerability in wild yam extract precursors exposes formulators to climatic volatility in specific subtropical growing regions. Distribution runs through direct-to-consumer platforms for volume, with practitioner channels capturing premium placement through group purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DHEA supplement market occupies early-cycle expansion territory, with longevity clinic protocol adoption in United States metropolitan corridors driving institutional demand pull-through ahead of mass-market saturation.
For Market Incumbents: Harden quality certification moats through USP verification and ISO 17025 laboratory accreditation investments that extend new entrant setup timelines by 12-18 months. Deepen backward integration into microbial fermentation capacity to reduce wild yam supply volatility exposure. Prioritize subscription platform infrastructure to capture recurring revenue from aging population protocol adherence. For New Entrants and Emerging Players: Germany pharmacy-dispensed supplement corridors offer underpenetration relative to United States saturation, with BfArM regulatory pathways enabling premium pricing for pharmaceutical-grade formulations. Target compounding pharmacy partnerships in Bavaria and Baden-Württemberg industrial clusters for custom dosage protocol placement. Deploy educational content frameworks that avoid specific hormone-related efficacy claims to navigate FTC advertising scrutiny. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier contract manufacturers with captive fermentation capacity but underutilized brand assets and fragmented channel presence. Five-to-ten year viability hinges on regulatory compliance infrastructure as FDA New Dietary Ingredient notification requirements compress product entry timelines. Monitor state-level age-restriction legislation proliferation as inflection indicator for direct-to-consumer fulfillment model disruption.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Program Enrollment | Enables placement in CVS and Walgreens pharmacy networks with clinician recommendation backing. |
| Compounding Pharmacy Partnership Development | Opens premium pricing corridors outside mass retail through custom dosage protocol integration. |
| Microbial Fermentation Capacity Expansion | Reduces wild yam supply volatility while improving batch-to-batch steroid purity consistency. |
| Subscription Platform Infrastructure Buildout | Captures recurring revenue from aging population segments managing chronic hormone protocols. |
| State-Level Regulatory Monitoring System | Anticipates age-restriction legislation that reshapes direct-to-consumer fulfillment complexity. |
Research Methodology
Desk research of FDA New Dietary Ingredient notification filings, FTC advertising enforcement actions, and USP verification program databases preceded structured interviews with contract manufacturing executives, anti-aging clinic protocol directors, compounding pharmacy procurement managers, and dietary supplement brand operators. Secondary validation drew from customs import records, ISO 17025 laboratory accreditation registries, and state-level legislative tracking systems. Bottom-up demand modeling triangulated against top-down market sizing from practitioner channel volume estimates.
Assumptions held regulatory frameworks constant at DSHEA baseline while varying state-level age-restriction adoption rates and longevity clinic expansion trajectories across the analysis window. Segmentation dimensions included delivery format, end-user motivation type, distribution channel credential requirements, and formulation certification tier. CAGRs derived from cohort-based protocol adherence modeling and repurchase cycle velocity by customer segment, with microbial fermentation cost curves and wild yam harvest volatility as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by e-commerce-native operators would shift outcomes through price compression acceleration. Quarterly review of FDA enforcement action frequency, state legislative introduction rates, and compounding pharmacy network expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
US and Canada Beta Glucan Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market
Nutritional Supplements
Europe Botanical Supplements Market